
 Global Food Processing Seals Market | 2026-2036
Global Food Processing Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Processing Seals Market Intelligence
The rise of alternative protein and plant-based beverage production is realigning demand away from traditional dairy facilities. This specific shift requires seals with different chemical and thermal resistance properties. Trelleborg Sealing Solutions leverages its material science expertise to serve this demanding niche. Freudenberg Sealing Technologies specializes in hygienic design for aseptic processing lines, while SKF sustains its market position through a wide portfolio covering various food manufacturing applications.
Food processing seals are engineered components designed to prevent contamination and leakage in food and beverage manufacturing equipment. These seals are made from materials like food-grade silicone or PTFE, which are inert and withstand aggressive clean-in-place (CIP) chemicals. Mechanical seals and O-rings constitute a significant portion of the market by value. The material segment shows a preference for high-performance fluorocarbons and silicones over elastomers like neoprene due to superior thermal stability and compliance.
Regulatory frameworks are a primary market determinant. The FDA's Code of Federal Regulations Title 21 in the United States and EFSA's regulations in Europe set stringent requirements for food contact materials. In China, national GB standards for food safety also dictate material composition and performance. Navigating these evolving material compliance standards while managing cost pressures remains the central challenge for component manufacturers and their suppliers.
Market Dynamics
The convergence of stricter food contact material regulations from bodies like the FDA and EFSA with new processing demands from the alternative protein sector is the central force shaping the market. This dual pressure accelerates material innovation and compliance investment.
Growth Catalysts
- EFSA Regulations:Europe's increasingly stringent EFSA food contact material standards mandate the use of high-purity elastomers and fluoropolymers, directly driving demand for certified, premium-grade seals.
- Beverage Sector Expansion:Growth in plant-based beverage production requires seals with specific chemical resistance to new ingredients and cleaning agents, creating a dedicated high-value niche.
- German Manufacturing Hub:Germany’s concentrated and technologically advanced food and beverage equipment manufacturing industry serves as a primary demand center for high-performance sealing components.
Market Restraints
- Fluoropolymer Price Volatility:The market remains exposed to price fluctuations and supply constraints for key raw materials like PTFE resins, impacting component manufacturer cost structures and margins.
- Regulatory Divergence:Navigating disparate national standards, such as China's GB framework versus EU regulations, adds significant testing costs and logistical complexity for global suppliers.
- Elastomer Substitution:In less critical, lower-temperature applications, lower-cost elastomers like neoprene and EPDM continue to compete against premium fluorocarbons, capping market value.
Strategic Opportunities
- Cultured Meat Bioreactors:The emerging cell-cultured meat industry will require novel, ultra-hygienic sealing solutions capable of maintaining absolute sterility in bioreactor environments, creating a new application frontier.
- Smart Seal Integration:Embedding sensors into seals for IIoT connectivity enables predictive maintenance and real-time monitoring of seal integrity, offering a significant value-add service opportunity.
- Southeast Asia Upgrades:Food processing facilities in markets like Vietnam and Thailand are upgrading to meet international export standards, opening new channels for certified sealing products.
Industry Challenges
- Certification Timelines:The protracted and expensive process of achieving material certification under frameworks like the FDA's Code of Federal Regulations Title 21 creates high barriers to entry for new materials.
- Specialized Talent Scarcity:A deficit of material scientists possessing dual expertise in advanced polymer chemistry and the principles of hygienic equipment design constrains innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Processing Seals Market |
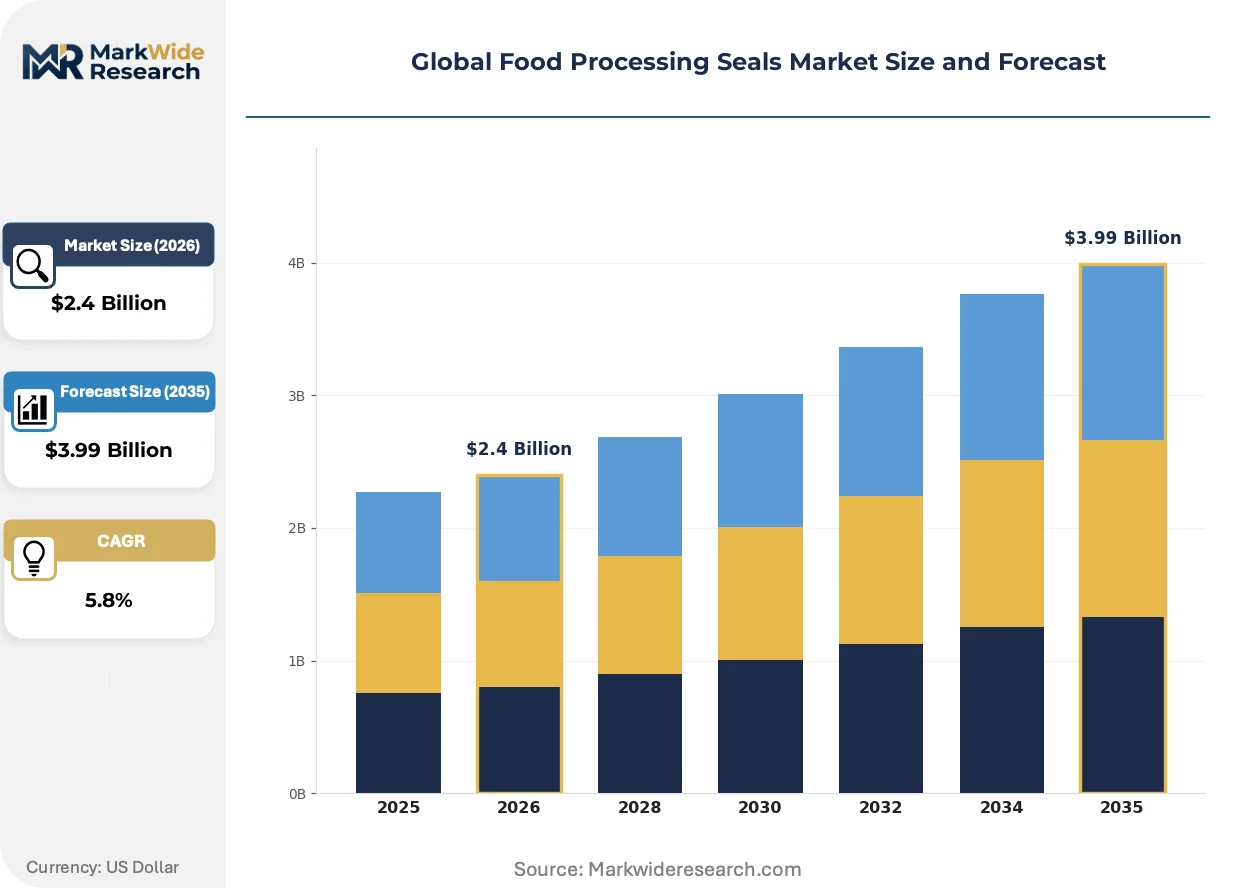
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seal Type: Gasket Seals, Lip Seals, Mechanical Seals, O-Rings, Diaphragm Seals Material: Silicone, PTFE, Neoprene, Nitrile, EPDM, Fluorocarbon Application: Pasteurization, Homogenization, CIP Processes, Bottling, Mixing End User: Food Manufacturers, Beverage Producers, Dairy Facilities, Bakeries |
| Companies Covered | Freudenberg Sealing Technologies, Parker Hannifin, Trelleborg Sealing Solutions, SKF, Flowserve Corporation, Garlock, John Crane, EagleBurgmann, IDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Processing Seals Market Strategic Shifts & Innovations
Material science innovation is accelerating in response to dual pressures from global food safety regulators and the operational demands of new food production categories. This creates a complex but opportunity-rich environment for component manufacturers specializing in certified materials.
Advanced hygienic design principles are engineered directly into elastomeric and PTFE seal profiles to eliminate microbial harborage points. Aseptic processing lines for beverages and dairy are rapidly adopting these components. This development is unifying the previously separate objectives of mechanical performance and microbiological safety into a single design criterion for component selection.
Regulatory frameworks in Asia are tightening, with China’s national GB standards for food contact materials becoming a key compliance hurdle. This forces manufacturers to reformulate products for the Chinese market, often requiring dedicated supply chains. Elastomer and silicone compounders are most affected, needing to validate materials against specific migration limits dictated by the SAMR.
A clear preference shift is occurring where food producers prioritize seals with comprehensive certification packages over those with only basic material compliance. This moves purchasing decisions beyond component price, disrupting traditional procurement for standard O-rings. The shift is most pronounced in North American and European export-oriented food segments where traceability is paramount.
Global Food Processing Seals Market Segmentation
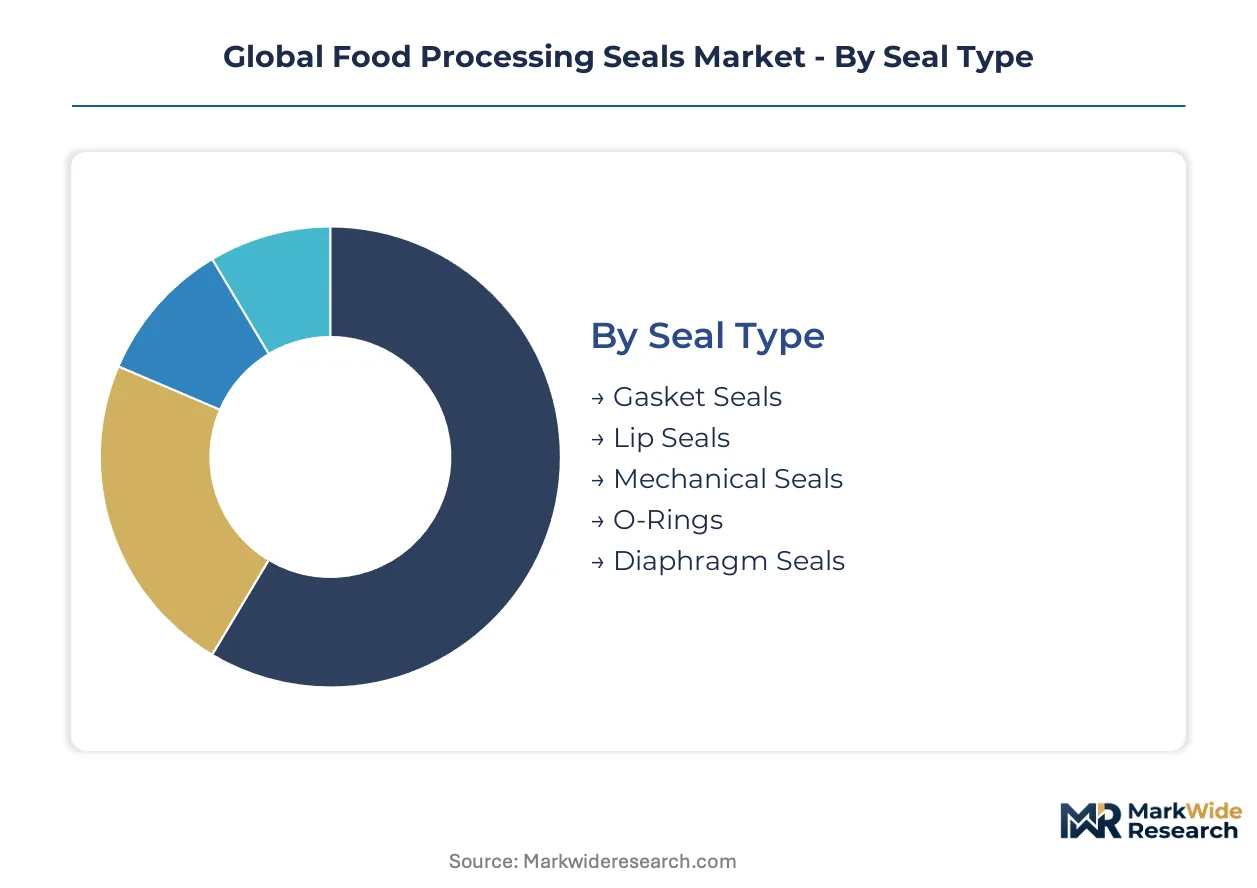
The Global Food Processing Seals Market segmentation reveals diverse requirements across material compositions, seal designs, application environments, and end-user industries. Understanding these distinct segment needs allows manufacturers to tailor solutions for specific operational challenges and regulatory compliance.
Seal Type:
Buyer decisions for seal types prioritize operational reliability and regulatory adherence, with critical implications for food safety and equipment longevity.
- Mechanical Seals:These seals provide robust containment for rotating equipment, preventing leakage in pumps and mixers. Demand is concentrating in high-speed processing lines within European beverage facilities, driven by stringent uptime requirements.
- O-Rings:Versatile and widely used, O-rings offer effective static and dynamic sealing in various connections and valves. North American food manufacturers prioritize certified O-rings for their ease of replacement and broad material compatibility in diverse applications.
- Gasket Seals:Gasket seals prevent leakage between static components, commonly found in pipe flanges and access panels. They require material compatibility with aggressive cleaning agents.
- Lip Seals:Designed for dynamic rotary applications, lip seals provide effective exclusion of contaminants and retention of lubricants. Their application is prevalent in gearboxes and motor shafts.
- Diaphragm Seals:These seals isolate pressure-sensing instruments from process media, crucial for maintaining hygiene in sensitive measurement points. They see use in aseptic processing.
Volume sits with O-Rings; growth tilts toward Mechanical Seals.
Material:
Material selection is dictated by the specific chemical and thermal demands of food processing applications, ensuring inertness and longevity.
- PTFE:Polytetrafluoroethylene offers exceptional chemical resistance and high-temperature stability, making it ideal for aggressive CIP environments. Demand is high in German food and beverage plants requiring non-stick and low-friction properties.
- Fluorocarbon:These high-performance elastomers provide superior thermal and chemical resistance compared to standard rubbers, critical for demanding food contact applications. European dairy facilities increasingly specify fluorocarbon seals for their pasteurization equipment.
- Silicone:Food-grade silicone provides excellent flexibility and temperature resistance, suitable for a wide range of static and dynamic sealing applications. It is often chosen for its hygienic properties.
- Neoprene:Neoprene offers good resistance to oils and chemicals, serving in less critical or lower-temperature food processing applications. Its cost-effectiveness drives adoption in basic sealing functions.
- Nitrile:Nitrile rubber provides good oil resistance and mechanical strength, commonly used in general-purpose sealing where high-temperature performance is not paramount. It finds application in various equipment.
- EPDM:Ethylene Propylene Diene Monomer offers excellent resistance to steam and hot water, making it suitable for cleaning processes in food manufacturing. This material is prevalent in beverage lines.
High-performance materials command premium pricing; standard elastomers offer cost-effectiveness.
Application:
Specific application areas impose distinct hygiene and operational demands on sealing components, influencing material choice and design.
- CIP Processes:Clean-in-Place processes involve aggressive chemicals and high temperatures, requiring seals with exceptional chemical and thermal resistance. Seals for CIP are crucial in facilities upgrading to international export standards in Southeast Asia.
- Bottling:Bottling lines demand seals that ensure product integrity and prevent leakage at high speeds, often involving diverse liquids. The expansion of plant-based beverage production drives demand for specialized seals in these operations.
- Pasteurization:Pasteurization involves heating processes that require seals capable of withstanding elevated temperatures and steam exposure. These seals are vital for dairy and juice processing.
- Homogenization:Homogenization processes operate under high pressures, necessitating robust seals to maintain equipment integrity and prevent product bypass. Seals in homogenizers prevent contamination.
- Mixing:Seals in mixing equipment must prevent product leakage and ingress of contaminants, often dealing with abrasive or viscous food ingredients. They ensure product consistency.
Aseptic processing and cleaning protocols drive demand for advanced sealing solutions.
End User:
End-user segments differentiate their sealing requirements based on product diversity and processing complexity, influencing procurement decisions.
- Beverage Producers:This segment requires seals resistant to a wide array of ingredients, including plant-based proteins and various cleaning agents. Growth in alternative protein beverages significantly impacts seal specifications here.
- Dairy Facilities:Dairy processing demands seals with ultra-hygienic designs and resistance to milk fats and CIP chemicals. Strict regulatory frameworks from EFSA drive material choices for these facilities.
- Food Manufacturers:This broad category encompasses diverse processing needs, from baked goods to prepared meals, requiring a wide portfolio of sealing solutions. Their operations range from simple to complex.
- Bakeries:Bakeries utilize seals in equipment like dough mixers and ovens, where high temperatures and specific food contact materials are necessary. Seals prevent ingredient leakage.
The beverage sector exhibits dynamic material requirements, while traditional food manufacturing maintains consistent demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The advanced food and beverage manufacturing sector in Germany, particularly its concentrated industrial clusters, drives significant demand for high-performance sealing components. This central European hub exemplifies a market where stringent quality mandates shape procurement patterns. Regulatory compliance and specialized material requirements define regional market dynamics.
Germany
Germany's advanced food and beverage manufacturing industry demands high-purity PTFE and fluorocarbon seals. The EFSA regulations influence material choices for German dairy and beverage facilities. Bavaria and North Rhine-Westphalia house significant food processing equipment manufacturers, concentrating demand for precision-engineered components.
United States
United States food manufacturers prioritize certified O-rings and mechanical seals for diverse applications. The FDA's Code of Federal Regulations Title 21 sets rigorous standards for food contact materials. California's extensive food processing industry, including plant-based beverage producers, requires seals with specific chemical resistance properties.
China
China’s food processing sector increasingly requires seals compliant with national GB standards for food safety. The SAMR enforces strict material composition and performance criteria across the country. The Yangtze River Delta region, a major manufacturing and consumption hub, sees a growing need for certified sealing products.
Vietnam
Vietnam's food processing facilities are upgrading to meet international export standards, creating new channels for certified sealing products. The country's Ministry of Health (MOH) regulations are tightening for food contact materials. Ho Chi Minh City's burgeoning food and beverage industry drives demand for modern, hygienic sealing solutions.
India
India's expanding food processing industry, particularly in dairy and beverages, seeks durable and hygienic sealing solutions. The FSSAI standards guide material selection and application across the sector. Maharashtra and Gujarat, with their significant food and beverage manufacturing bases, contribute to the growing demand for advanced seals.
Global Food Processing Seals Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized mid-cap manufacturers and regional suppliers compete across various application niches. The market structure exhibits a tiered approach, with material science expertise differentiating key players. Archetypes include material science innovators, hygienic design specialists, and broad-portfolio providers. Strategic partnerships and targeted portfolio diversification represent dominant competitive moves among market participants.
Specialists in hygienic design include Freudenberg Sealing Technologies, known for its expertise in aseptic processing lines and stringent regulatory compliance. Trelleborg Sealing Solutions leverages material science to serve demanding niches such as alternative protein production, requiring specific chemical and thermal resistance. SKF occupies a position as a broad-portfolio provider, sustaining its market standing through a wide array of food manufacturing applications across various processing stages. These companies exemplify the strategic focus on either high-performance materials, specialized application solutions, or comprehensive product offerings to meet diverse industry needs.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies |
| Parker Hannifin |
| Trelleborg Sealing Solutions |
| SKF |
| Flowserve Corporation |
| Garlock |
| John Crane |
| EagleBurgmann |
| IDEX Corporation |
| Others |
Cost & Logistics Intelligence
European food and beverage equipment manufacturers often drive a value-based pricing model, prioritizing certified, high-performance seals over cost. This concentration of demand reinforces premium pricing for specialized components.
Pricing Analysis
Short lead times for specialized, certified food processing seals command a premium, reflecting the critical need for operational continuity in food production. The dominant pricing structure is a hybrid, combining value-based pricing for high-performance fluorocarbons and silicones with transactional pricing for standard elastomers. Price differentiation stems from stringent certification levels like FDA Title 21 and material science expertise for specific chemical resistance. Pricing pressure is upward, driven by fluoropolymer price volatility and rising compliance investment; export-oriented food segments exhibit low price sensitivity, while less critical applications prioritize cost-effectiveness.
Supply Chain Analysis
Logistics and freight costs influence the final delivered price, particularly for high-purity, specialized sealing components sourced globally. The supply chain concentrates in Germany for finished components, while raw materials like PTFE resins and fluoropolymers originate from a broader base. This market relies on a few key suppliers for advanced materials, creating single-source vulnerability for component manufacturers. The dominant distribution model involves direct sales to large food and beverage equipment OEMs and specialized industrial distributors for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food processing seals market operates as a supply-constrained story, primarily due to limited production capacity for certified high-purity fluoropolymers. This bottleneck props up pricing for advanced sealing solutions, especially in regulated applications.
For Market Incumbents: Anchor existing market share through continuous investment in material science R&D, focusing on next-generation fluoropolymers for alternative protein and cultured meat applications. Deepen strategic partnerships with major European food equipment OEMs to counter potential pricing pressure from new material entrants. Expand global certification capabilities to navigate evolving regulatory frameworks like China’s GB standards. This strategy leverages material science expertise and hygienic design principles.
For New Entrants and Emerging Players: EFSA regulations in Europe open a window for new entrants specializing in ultra-hygienic seals for aseptic processing lines. Target the emerging cultured meat industry with novel, sterile sealing solutions for bioreactors, representing a significant white-space opportunity. Focus on Southeast Asian markets like Vietnam, where facilities are upgrading to meet international export standards. A go-to-market angle emphasizing comprehensive certification packages and local technical support will be critical.
For Investors and Strategic Acquirers: The window for entry favors patient capital with a long-term view of non-negotiable food safety standards and continuous material innovation. This market offers strong long-term viability over the next decade, driven by regulatory stringency and new food production methods. Acquisition targets should be mid-cap specialists possessing proprietary material science expertise or advanced hygienic design intellectual property. A key signal to watch is the commercial scaling of cultured meat bioreactors, indicating a new frontier for sealing technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D Investment | Develops next-generation fluoropolymers for demanding alternative protein applications. |
| Global Certification Expansion | Navigates diverse regulatory frameworks like China's GB standards for market access. |
| Hygienic Design Patent Portfolio Growth | Strengthens competitive advantage in aseptic processing lines for beverage producers. |
| Smart Seal Technology Integration | Enables predictive maintenance for critical equipment in European dairy facilities. |
| Southeast Asia Market Entry | Captures demand from facilities upgrading to international export standards in Vietnam. |
Research Approach
The FDA's Code of Federal Regulations, EFSA scientific opinions, and China's national GB standards formed the secondary backbone for this market analysis. Primary interviews with material scientists, food safety regulators, equipment engineers, and procurement managers provided crucial qualitative insights. This research combined bottom-up data aggregation with top-down market validation, ensuring robust findings. Triangulation across these diverse sources strengthened the overall market understanding.
Bottom-up analysis of component demand across specific seal types and materials was validated against top-down market sizing over the projection horizon. The forecast framework integrated segmentation dimensions including application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends, expert projections, and anticipated new application adoption rates. Key industry-specific forecast inputs included raw material price forecasts and food safety regulation updates.
The model assumes a particular technology adoption path; alternative pathways for smart seal integration or cultured meat scale-up would alter the outlook. Forecasts reflect inherent assumptions about regulatory stability and raw material availability, with unforeseen geopolitical events presenting significant risk. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Squeeze Tube Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Fanfold Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Neoprene Coffee Sleeves Market