
 Insulated Box Liner Market | 2026-2036
Insulated Box Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Box Liner Market Analytics
Modular liner kits that separate thermal barrier from structural containment is decoupling procurement decisions across pharmaceutical and food-service buyers. Sealed Air Corporation leverages its film extrusion capabilities to control reflective barrier supply. Sonoco Products Company anchors North American manufacturing through molded foam operations. Cold Chain Technologies specializes in validated shipper systems for clinical trial distribution.
An insulated box liner is a deployable thermal barrier inserted into corrugated or rigid containers to attenuate heat transfer and maintain designated temperature bands, typically constructed from expanded polystyrene foam, metallized film laminates, or aerogel-composite sheets bonded to protective skins. The product serves cold-chain logistics by bridging the gap between active refrigeration and ambient exposure during last-mile transit. Foam-based configurations dominate unit economics in food and beverage applications where single-use cost minimization governs selection. Reflective film laminates command premium positioning in pharmaceutical distribution where validated performance between two and eight degrees Celsius justifies higher material outlay. Polyester nonwoven variants are gaining traction in electronics protection where static dissipation combines with thermal buffering.
The EPA regulates blowing agents under SNAP rules that restrict hydrofluorocarbon content in expanded foam production, while the EU F-Gas Regulation phases down greenhouse gas-intensive insulation materials. FDA guidance on cold-chain validation for temperature-sensitive pharmaceuticals creates compliance pull-through for certified liner systems. REACH chemical registration requirements in Europe constrain adhesive and film additive formulations. Stakeholders must weigh material transition timelines against validation costs as regulatory stringency tightens across multiple jurisdictions.
Market Dynamics
Regulatory tightening on thermal insulation materials is forcing simultaneous material transitions across multiple jurisdictions, compressing validation timelines while pharmaceutical cold-chain volumes accelerate demand for certified performance.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for greenhouse gas-intensive blowing agents are pulling demand toward low-global-warming-potential foam alternatives in temperature-assured packaging.
- Pharmaceutical cold-chain expansion:Clinical trial distribution networks require validated shipper systems with documented thermal performance between two and eight degrees Celsius.
- Frankfurt-Cologne corridor:Pharmaceutical distribution hub concentration in Germany is concentrating procurement volumes for modular liner kits with decoupled thermal and structural components.
Market Restraints
- Blowing agent cost volatility:Hydrofluorocarbon restrictions under EPA SNAP rules are constraining expanded polystyrene production economics and input availability.
- Validation cost concentration:FDA cold-chain guidance for temperature-sensitive biologics imposes documentation burdens that favor larger shippers with dedicated quality infrastructure.
- Aerogel supply bottleneck:Limited domestic manufacturing of silica aerogel composites creates import dependency for premium pharmaceutical liner grades.
Strategic Opportunities
- Electronics protection segment:Static-dissipative polyester nonwoven variants are penetrating semiconductor and precision instrument packaging with combined thermal and electrostatic buffering.
- REACH-compliant adhesive reformulation:European chemical registration requirements are creating first-mover advantage for suppliers with pre-registered film additive portfolios.
- Last-mile foodservice:Meal-kit delivery channels are adopting single-use foam configurations where cost minimization governs selection criteria.
Industry Challenges
- Cross-jurisdictional compliance:Simultaneous EPA SNAP, EU F-Gas, and REACH transitions require parallel material qualification tracks with non-aligned timelines.
- Thermal validation expertise:Qualified engineers capable of executing ISTA 7E and WHO PQS thermal testing protocols command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Box Liner Market |
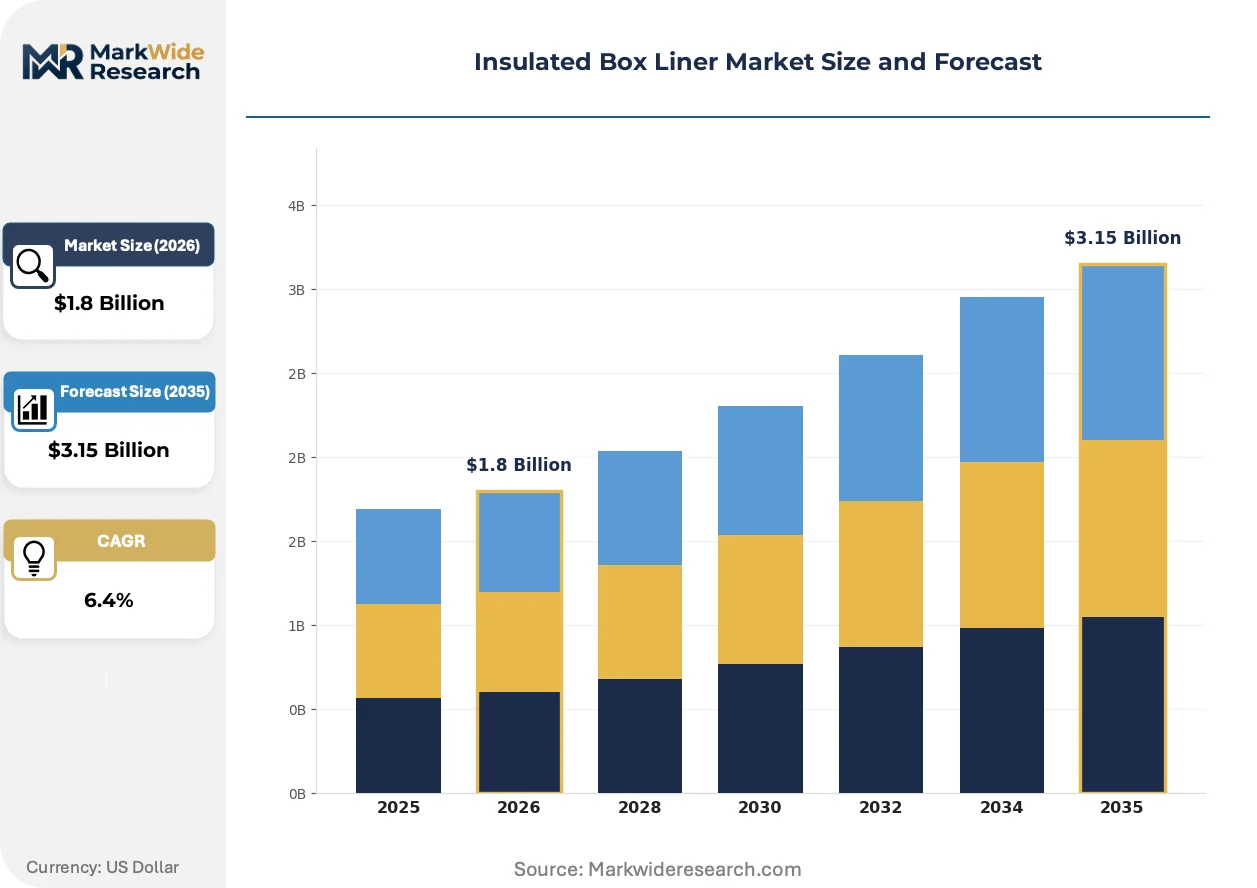
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Reflective Film, Bubble Wrap, Polyester End User: Food & Beverage, Pharmaceuticals, Chemicals, Electronics Application: Cooling, Heating, Temperature Control, Protection Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Polar Tech Industries, Thermal Shipping Solution, PAC Worldwide, Coldkeepers, IPC, Softbox Systems, Cold Chain Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Box Liner Market Evolving Landscape
Material science advances are compressing thermal conductivity targets while regulatory chemistry constraints are reshaping formulation roadmaps across the insulated packaging value chain.
Aerogel-composite sheet technology is expanding into pharmaceutical distribution where validated performance windows justify material premiums against conventional expanded foam. Cold-chain managers at biologics shippers are adopting these laminates for international lane qualification. The technology is expanding into temperature ranges previously dominated by active refrigeration systems, compressing the addressable market for powered thermal containers.
The EU F-Gas Regulation's phasedown schedule is accelerating blowing agent transitions in expanded polystyrene production. Foam extruders must reformulate with hydrocarbon or hydrofluoroolefin alternatives while maintaining dimensional stability and R-value performance. German pharmaceutical packaging converters face the steepest compliance curve given their concentration of validated product lines requiring requalification.
Modular procurement patterns are fragmenting buyer-seller relationships as pharmaceutical and food-service customers separately source thermal barriers and structural containers. Distributors are unbundling liner kits into component catalogs with distinct specification tracks. This unbundling is most advanced in North American foodservice channels where corrugated converters compete directly with thermal specialists for the barrier specification.
Insulated Box Liner Market Segmentation
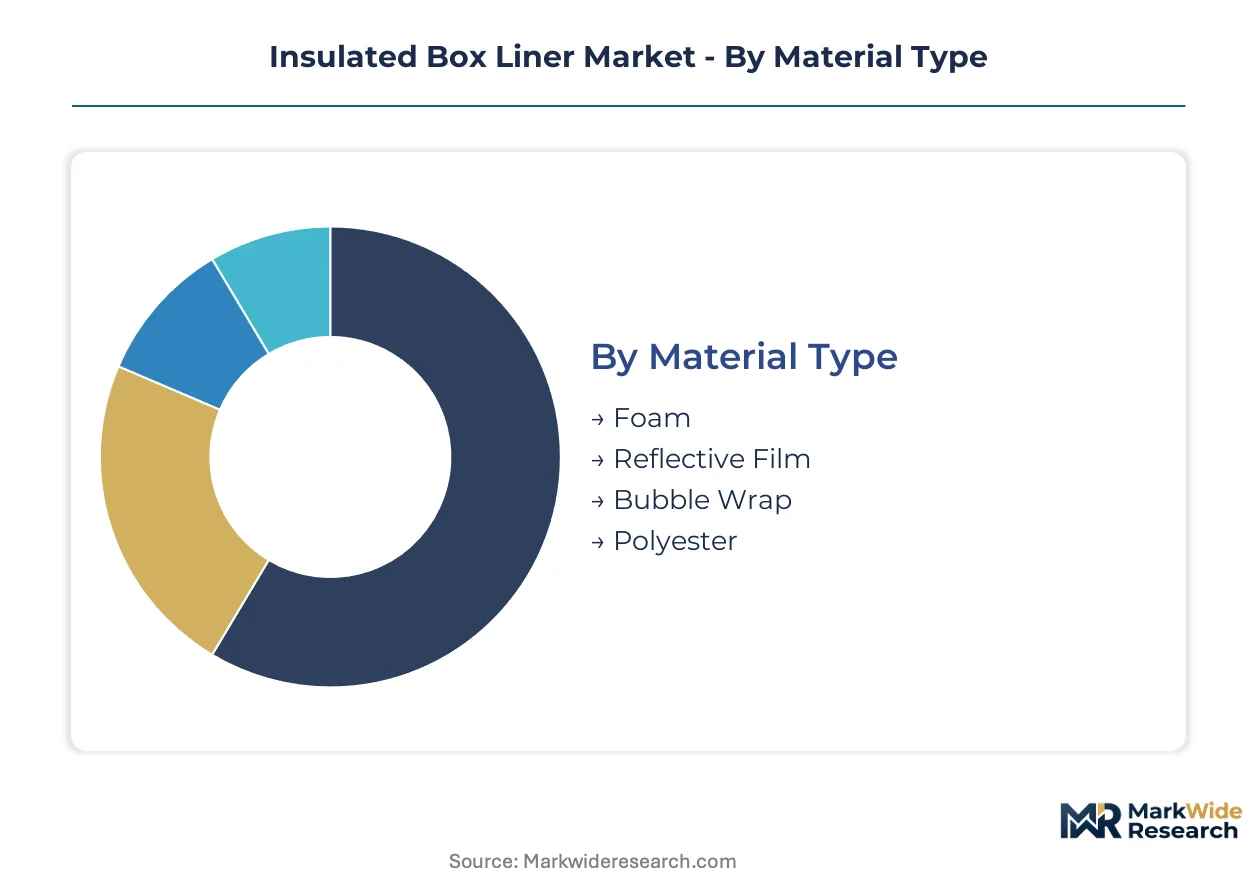
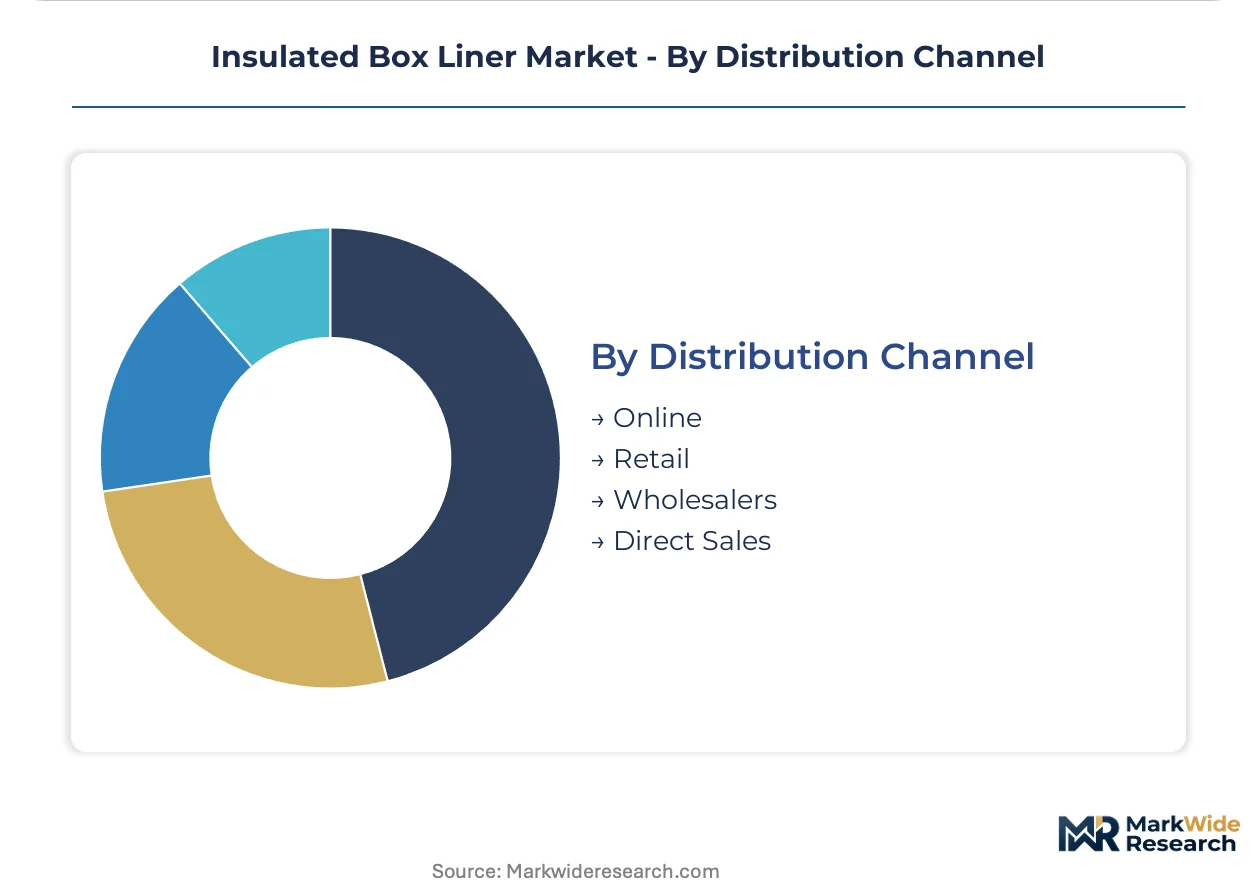
Insulated box liner procurement splits across material chemistry, end-use validation requirements, and channel access economics. Buyers in pharmaceutical cold-chain demand certified thermal performance, while food-service operators prioritize unit cost minimization in high-volume configurations.
Material Type:
Material chemistry governs thermal conductivity, structural integrity, and regulatory compliance trajectory across liner specifications.
- Foam:Expanded polystyrene and polyurethane variants dominate unit economics through low material cost and established extrusion infrastructure. Food & Beverage procurement in North American meal-kit channels concentrates demand for single-use configurations where disposal cost minimization drives selection. EPA SNAP restrictions on hydrofluorocarbon blowing agents are forcing reformulation timelines that compress validation windows for established product lines.
- Reflective Film:Metallized polyester laminates with trapped air layers deliver validated performance between two and eight degrees Celsius for pharmaceutical distribution. German pharmaceutical hubs around Frankfurt and Cologne anchor premium demand for these specifications where FDA cold-chain guidance mandates documented thermal qualification. EU F-Gas Regulation compliance adds formulation complexity for adhesive bonding layers.
- Bubble Wrap:Air-cell configurations with metallized skins offer intermediate thermal resistance for short-duration transit protection. Electronics manufacturers in precision instrument packaging specify these for combined cushioning and moderate thermal buffering.
- Polyester:Nonwoven spunbond variants with static-dissipative additives serve semiconductor packaging where electrostatic discharge protection combines with thermal attenuation. REACH chemical registration requirements in Europe constrain additive formulation options for suppliers targeting this segment.
Foam leads on scale; Reflective Film leads on momentum.
End User:
End-use differentiation separates validated pharmaceutical requirements from cost-optimized food-service procurement patterns.
- Food & Beverage:Meal-kit delivery platforms and fresh produce distributors specify single-use foam configurations where per-unit cost governs selection criteria. Last-mile temperature maintenance for chilled proteins and dairy drives volume concentration in North American urban corridors.
- Pharmaceuticals:Biologics shippers require ISTA 7E and WHO PQS validated systems with documented performance between two and eight degrees Celsius. Clinical trial distribution networks impose quality infrastructure burdens that favor larger packaging converters with dedicated thermal testing capabilities.
- Chemicals:Temperature-sensitive reagents and diagnostic materials specify intermediate thermal protection for laboratory supply chains. Distribution concentrates through specialized chemical wholesalers with cold-storage consolidation points.
- Electronics:Semiconductor and precision instrument manufacturers adopt static-dissipative polyester variants for combined electrostatic and thermal protection. Cleanroom-compatible specifications add material certification requirements for this segment.
Food & Beverage dominates volume contribution; Pharmaceuticals commands margin premium.
Application:
Functional specification separates passive cooling dominance from emerging heating and multi-mode temperature control requirements.
- Cooling:Chilled and frozen product protection accounts for the majority of liner deployment across food and pharmaceutical channels. Gel pack and phase-change material integration with foam or reflective barriers defines standard configurations for this application.
- Heating:Prepared meal and temperature-sensitive chemical applications require thermal retention above ambient conditions. Active heating element integration with insulated barriers expands addressable use cases in meal-service and industrial chemical segments.
- Temperature Control:Narrow-band maintenance between two and eight degrees Celsius for pharmaceuticals and fifteen to twenty-five degrees for electronics defines precision specifications. Aerogel-composite sheets are penetrating this application for international lane qualification where duration requirements exceed conventional foam capability.
- Protection:Combined thermal and mechanical cushioning for fragile electronics and diagnostic instruments specifies multi-functional liner designs. Impact absorption specifications add structural engineering requirements beyond pure thermal performance.
Cooling anchors installed base; Temperature Control exhibits steepest expansion trajectory.
Distribution Channel:
Channel structure fragments buyer relationships as unbundled procurement of thermal barriers and structural containers advances.
- Online:E-commerce platforms aggregate small-volume buyers with standardized specification catalogs. Modular liner kit unbundling is most visible through this channel where pharmaceutical and food-service customers separately configure thermal and structural components.
- Retail:Packaging supply distributors serve mid-volume converters with stocked inventory for immediate fulfillment. Regional concentration of corrugated converters drives geographic variation in available liner specifications through this channel.
- Wholesalers:Industrial packaging distributors consolidate procurement for multi-site food-service and chemical operations. Volume aggregation through this channel supports cost minimization for standardized foam configurations.
- Direct Sales:Large pharmaceutical and electronics manufacturers negotiate validated system specifications directly with converter engineering teams. FDA cold-chain documentation and ISTA thermal testing protocols require relationship depth that this channel alone provides.
Direct Sales captures value concentration; Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The insulated box liner industry traces its commercial origins to post-war American food distribution networks, where expanded polystyrene foam first replaced straw and sawdust for refrigerated rail transport of meat and dairy products.
United States
Meal-kit delivery platforms and biologics cold-chain networks drive liner procurement across the Midwest and Northeast corridors. The EPA SNAP program restricts hydrofluorocarbon blowing agents in expanded foam production, forcing reformulation timelines. Greater Boston anchors pharmaceutical packaging engineering talent concentrated around clinical trial logistics operations.
Germany
Pharmaceutical distribution hubs clustered around Frankfurt and Cologne concentrate demand for validated thermal shipper systems. The EU F-Gas Regulation mandates phase-down of greenhouse gas-intensive insulation materials, compressing requalification windows. Bavaria hosts specialized converters serving temperature-assured packaging for European biologics distribution.
China
Domestic pharmaceutical cold-chain infrastructure expansion and electronics export protection create dual demand streams for thermal barrier materials. The national dual carbon goals constrain conventional foam production economics. The Yangtze River Delta concentrates manufacturing of reflective film laminates for precision instrument packaging.
India
Vaccine distribution networks and generic pharmaceutical exports drive adoption of modular liner kits with decoupled thermal and structural components. CDSCO cold-chain guidance for temperature-sensitive biologics imposes documentation requirements. Maharashtra and Gujarat host emerging converter operations serving South Asian pharmaceutical logistics.
Japan
Semiconductor packaging and precision electronics exports specify static-dissipative thermal barriers with cleanroom compatibility. METI industrial standards govern material specifications for temperature-sensitive cargo. The Kansai region around Osaka concentrates electronics logistics operations requiring combined electrostatic and thermal protection.
Insulated Box Liner Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material chemistry and validation capability dimensions. The vendor base separates into three distinct tiers: integrated packaging conglomerates with film extrusion or molded foam capabilities, specialized cold-chain engineering firms with thermal testing infrastructure, and regional converters serving cost-sensitive food-service channels. Consolidation pressure concentrates among mid-scale foam extruders facing simultaneous EPA SNAP and EU F-Gas compliance costs. Dominant competitive moves include backward integration into reflective barrier supply and geographic expansion into German pharmaceutical hub markets.
Within the integrated packaging tier, Sealed Air Corporation and Sonoco Products Company exemplify scale-driven positions spanning multiple material technologies. Cold Chain Technologies occupies a specialist position anchored in validated shipper systems for pharmaceutical distribution. These three entities represent the structural poles of the competitive landscape: diversified materials conglomerates versus focused cold-chain engineering operations.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Polar Tech Industries |
| Thermal Shipping Solution |
| PAC Worldwide |
| Coldkeepers |
| IPC |
| Softbox Systems |
| Cold Chain Technologies |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply for premium pharmaceutical liner grades while simultaneously compressing margin structures for commodity foam extruders. German pharmaceutical buyers absorb material premiums for validated thermal performance, whereas North American food-service channels drive cost compression through volume aggregation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical specifications from commodity meal-kit configurations. Price differentiation hinges on FDA cold-chain certification tier and volume scale commitments, with ISTA 7E validation commanding substantial premiums. Cost compression in expanded polystyrene foam is intensifying because EPA SNAP hydrofluorocarbon restrictions constrain blowing agent availability. Food-service operators exhibit highest price sensitivity, while biologics shippers prioritize thermal qualification over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for temperature-assured packaging. Manufacturing draws from expanded polystyrene resin, metallized polyester film, and silica aerogel precursor feedstocks. Single-source vulnerability concentrates in domestic aerogel composite production, creating import dependency for premium pharmaceutical grades. Distribution runs through direct sales relationships for validated systems and wholesaler consolidation for standardized foam configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU F-Gas compliance costs in Germany exceed EPA SNAP transition expenses in the United States, creating divergent margin structures across Atlantic pharmaceutical corridors.
For Market Incumbents: Lock in backward integration into reflective barrier supply before film extrusion capacity tightens further. Consolidate thermal testing infrastructure around ISTA 7E and WHO PQS protocols to defend against specialized cold-chain engineering entrants. Prioritize requalification investment for low-global-warming-potential foam alternatives ahead of EU F-Gas enforcement milestones. For New Entrants and Emerging Players: EPA SNAP restrictions in the United States open a window for hydrocarbon-blown foam specialists to capture displaced conventional extruder volumes. Target static-dissipative polyester nonwoven segments in Japanese electronics corridors where METI standards create certification barriers for incumbent converters. Pursue modular liner kit unbundling as the primary go-to-market angle, decoupling thermal barrier procurement from structural container decisions. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale foam extruders facing simultaneous EPA SNAP and EU F-Gas compliance burdens because consolidation spreads fixed validation costs across broader production bases. Focus acquisition screening on converters with pre-registered REACH additive portfolios and established German pharmaceutical hub relationships. Watch for inflection when CDSCO cold-chain guidance in India mandates documented thermal qualification, signaling regulatory convergence with Western pharmaceutical standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reflective Barrier Supply | Sealed Air Corporation's film extrusion capabilities demonstrate captive supply advantages for metallized laminates. |
| REACH-Compliant Adhesive Reformulation | First-mover suppliers with pre-registered additive portfolios capture German pharmaceutical converter procurement. |
| Modular Liner Kit Unbundling | Decoupled thermal and structural component sourcing fragments buyer relationships across food-service channels. |
| Aerogel-Composite Sheet Capacity Expansion | Cold Chain Technologies leverages silica aerogel laminates for international pharmaceutical lane qualification. |
| Static-Dissipative Nonwoven Certification | Polar Tech Industries targets semiconductor packaging where METI standards govern cleanroom-compatible specifications. |
Research Methodology
Direct dialogue with cold-chain logistics directors, pharmaceutical packaging engineers, foam extrusion plant managers, and thermal testing laboratory heads grounded qualitative findings. Secondary validation drew from EPA SNAP rulemakings, EU F-Gas Regulation implementing acts, FDA cold-chain guidance documents, and customs trade data for reflective film laminates. Bottom-up demand modeling across material type, end user, application, and distribution channel segments combined with top-down macroeconomic triangulation.
Segment-level projections across the analysis window incorporate material chemistry transitions, regulatory compliance timelines, and pharmaceutical cold-chain volume expansion. The analytical framework modeled foam, reflective film, bubble wrap, and polyester nonwoven material categories against food and beverage, pharmaceutical, chemical, and electronics end-use segments. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory assumptions, with specific weighting for blowing agent reformulation timelines and aerogel manufacturing scale-up rates.
Revisions become necessary when EPA SNAP enforcement intensity shifts, EU F-Gas phase-down accelerates, or CDSCO cold-chain guidance in India mandates unexpected documentation requirements. Forecasts reflect documented assumptions regarding material substitution elasticities and regulatory compliance cost pass-through rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Foil Laminates Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
China Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Single-Use Packaging Market