
 Book Wraps Market | 2026-2036
Book Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Book Wraps Market Outlook
Buyer concentration among independent bookstores and specialty retailers is decoupling from the historical dominance of mass-market distributors. WrapMaster leverages its geographic dominance across North American craft retail channels to sustain volume leadership. EcoPack Solutions anchors its position through in-house production of recycled kraft substrates. SafePack competes on brand strength within the library procurement segment.
Book wraps are protective enclosures manufactured from paper, fabric, plastic, or leather substrates, typically incorporating closure mechanisms such as magnetic flaps, fabric ties, or button fasteners to shield volumes from abrasion, moisture, and UV degradation during transit or storage. Paper-based wraps dominate unit volume due to cost parity with conventional corrugated alternatives, while leather wraps command concentrated margin pools among collector and gift segments. Magnetic closure designs lead functional preference rankings in the library end-user category, whereas customizable design styles are accelerating fastest within the author-direct and specialty bookstore channels.
The US EPA and California's Department of Resources Recycling and Recovery shape substrate selection through extended producer responsibility frameworks that penalize non-recyclable multi-material constructions. The EU REACH regulation and FSC chain-of-custody standards govern chemical content and fiber provenance for wraps entering European distribution. Stakeholders must monitor evolving state-level packaging EPR enactments and decide between regional SKU proliferation versus unified global product platforms.
Market Dynamics
Extended producer responsibility frameworks are forcing substrate transitions across the Book Wraps Market, with converters abandoning multi-material laminates in favor of fiber-based alternatives that satisfy compliance without sacrificing protective performance.
Growth Catalysts
- California SB 54:The state's extended producer responsibility law mandates recyclable packaging, driving converters toward mono-material kraft and molded fiber constructions that simplify end-of-life processing.
- Heritage publishing procurement:German academic and specialty houses maintain premium packaging standards that sustain demand for leather and fabric wraps with archival-grade closures.
- Magnetic closure systems:These mechanisms are displacing adhesive and tie-based alternatives in library procurement specifications due to superior reusability and reduced handling damage.
Market Restraints
- Pulp price volatility:Kraft linerboard and recycled fiber input costs fluctuate with energy markets, compressing converter margins on paper-based wrap contracts.
- Leather supply concentration:Tannery capacity clusters in Italy and India create geographic vulnerability for premium wrap producers dependent on full-grain substrates.
- Multi-material construction bans:EU Single-Use Plastics Directive and analogous state-level enactments prohibit plastic-laminated paper wraps, eliminating established product formats.
Strategic Opportunities
- Author-direct channels:Self-publishing platforms and crowdfunding campaigns create demand for customizable wraps with short-run digital printing capabilities.
- FSC chain-of-custody certification:European retailers and institutional buyers increasingly require documented fiber provenance, rewarding certified suppliers with preferred vendor status.
- Smart packaging convergence:Integration of NFC tags and QR codes into wrap designs enables authentication and provenance tracking for collector editions.
Industry Challenges
- Digital print operator scarcity:Short-run customization demand outpaces availability of technicians skilled in UV and latex ink systems for rigid substrates.
- EPR compliance timeline compression:California's phased implementation deadlines force rapid reformulation of existing product lines without extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Book Wraps Market |
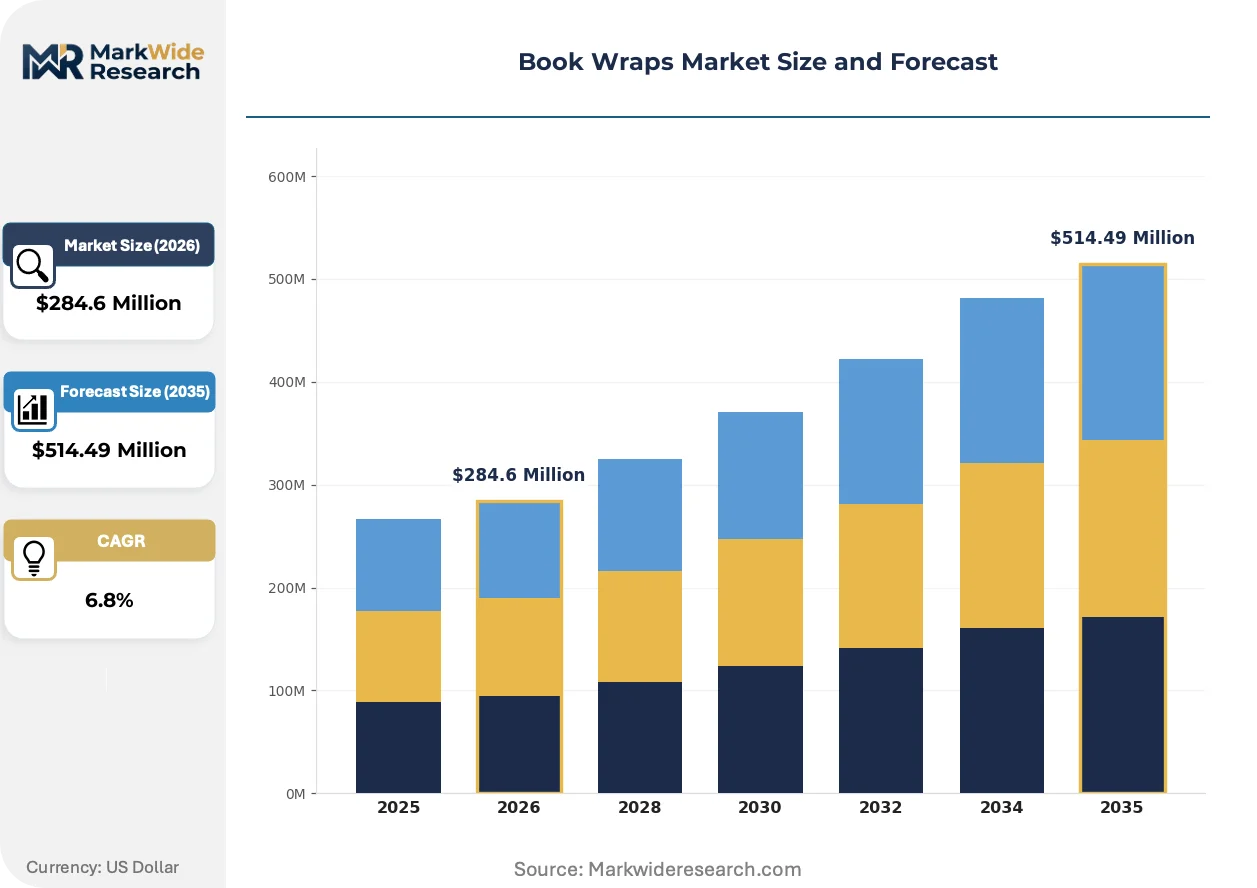
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Fabric, Plastic, Leather Closure Type: Magnetic, Tie, Velcro, Button Design Style: Minimalist, Artistic, Classic, Customizable End User: Students, Authors, Libraries, Bookstores |
| Companies Covered | WrapMaster, SecureWrap, EcoPack Solutions, FlexiWrap, BookGuard, SafePack, PackShield, WrapIt, EcoWraps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Book Wraps Market Strategic Shifts
Active substrate experimentation and closure mechanism refinement are redefining protective packaging performance standards, with sustainability compliance now inseparable from functional design.
Molded fiber forming technology is overtaking die-cut corrugated for medium-duty protection applications. Independent bookstores and specialty retailers are specifying these wraps for shipment of signed editions and gift sets. The shift is compressing demand for plastic bubble mailers and enabling direct substitution in channels previously locked into poly-based logistics.
REACH substance restrictions and evolving EU packaging waste directives are eliminating certain chemical treatments from anti-moisture coatings. Converters serving European distribution must reformulate barrier layers using bio-based alternatives. Heritage publishing houses in Germany and France are responding by tightening supplier qualification requirements around chemical disclosure.
Author-direct fulfillment models are fragmenting historical distributor concentration. Crowdfunding platforms and print-on-demand services now specify branded protective packaging as a backer reward tier. This pattern concentrates in North American and UK markets where direct-to-reader sales infrastructure matured earliest.
Book Wraps Market Segmentation
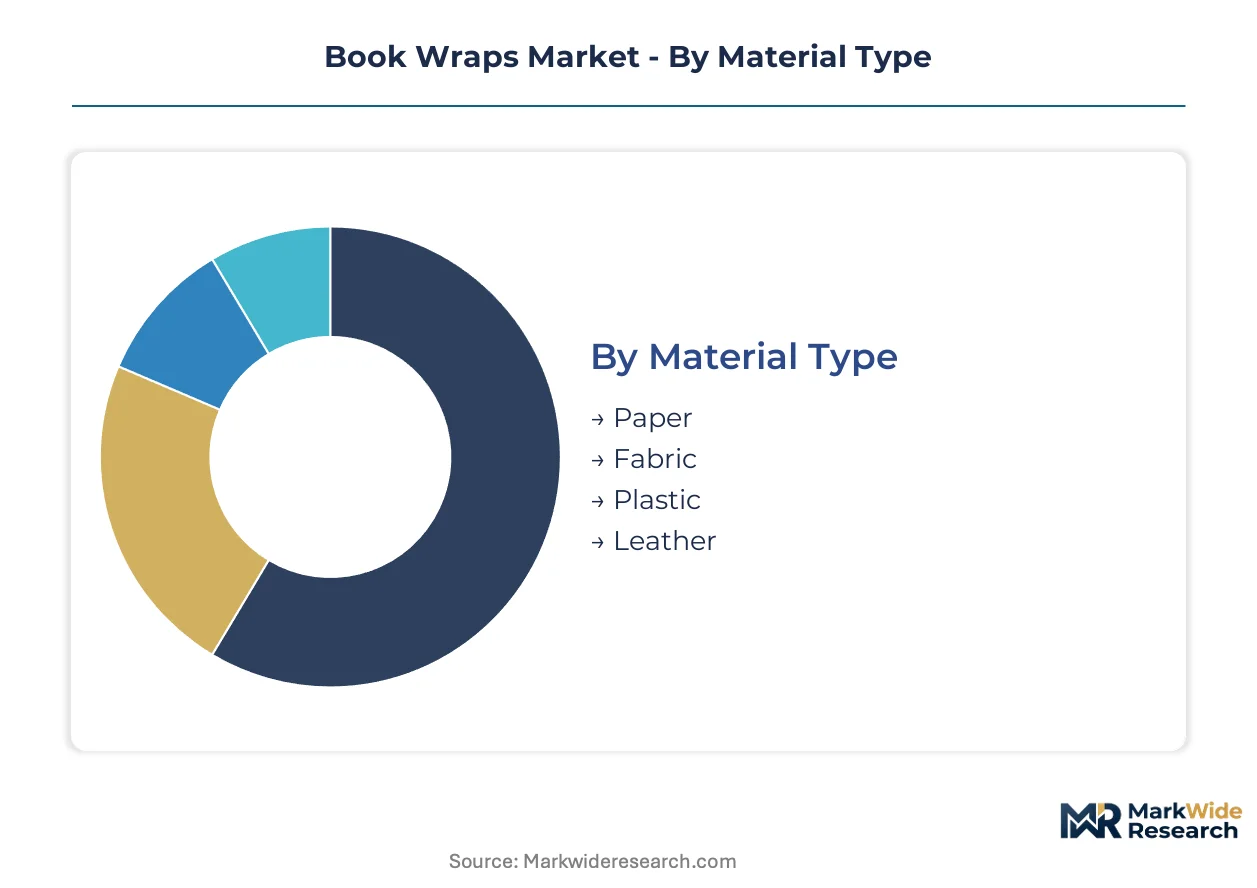
Material substrate selection and closure mechanism design determine compliance viability and margin capture across the book wraps market. Segmentation reveals where fiber-based alternatives displace legacy constructions and which functional specifications command procurement premiums.
Material Type:
Standalone protective wraps dominate unit economics, while embedded multi-material laminates face regulatory phase-out under extended producer responsibility frameworks.
- Paper:Kraft linerboard and molded fiber constructions satisfy California SB 54 recyclability mandates while matching corrugated cost structures. Independent bookstores in North America specify these wraps for signed edition shipments.
- Fabric:Cotton canvas and linen substrates serve archival applications where breathability prevents moisture trapping. German heritage publishing houses maintain procurement standards requiring fabric wraps for limited collector releases.
- Plastic:Polypropylene and polyethylene wraps face mounting restrictions under EU Single-Use Plastics Directive and analogous state-level enactments.
- Leather:Full-grain and bonded leather command concentrated margin pools in gift and collector segments, though tannery capacity clustering in Italy and India creates supply vulnerability.
Volume placements concentrate in paper-based wraps; the faster expansion belongs to fabric alternatives as archival standards tighten.
Closure Type:
Mechanism selection tracks reusability requirements and handling damage thresholds, with procurement specifications diverging sharply between institutional and consumer channels.
- Magnetic:Neodymium flap closures enable rapid access without adhesive residue or fabric fatigue. Library procurement specifications increasingly mandate magnetic systems for circulating collections.
- Tie:Fabric ribbon and cord closures persist in artisanal and gift segments where tactile presentation outweighs speed of access.
- Velcro:Hook-and-loop fasteners serve budget-tier educational markets despite lint accumulation and wear degradation.
- Button:Corozo and metal button closures anchor premium positioning in Japanese and Korean gift wrap traditions.
Magnetic closures capture institutional procurement volume; button mechanisms gain share fastest in Asia-Pacific premium gifting.
Design Style:
Aesthetic positioning separates commodity protective function from brand extension value, with production economics diverging between template-based and variable-data approaches.
- Minimalist:Unadorned kraft and monochrome finishes align with Scandinavian retail aesthetics and corporate gifting protocols.
- Artistic:Illustrated and patterned wraps support author-direct crowdfunding tiers where packaging functions as collectible artifact.
- Classic:Marbled paper and traditional binding motifs serve academic and theological publishers maintaining historical presentation standards.
- Customizable:Digital print-enabled variable designs allow single-unit personalization for self-publishing platforms and memorial editions.
Classic designs retain stable placement in academic channels; customizable formats are climbing the fastest as print-on-demand infrastructure matures.
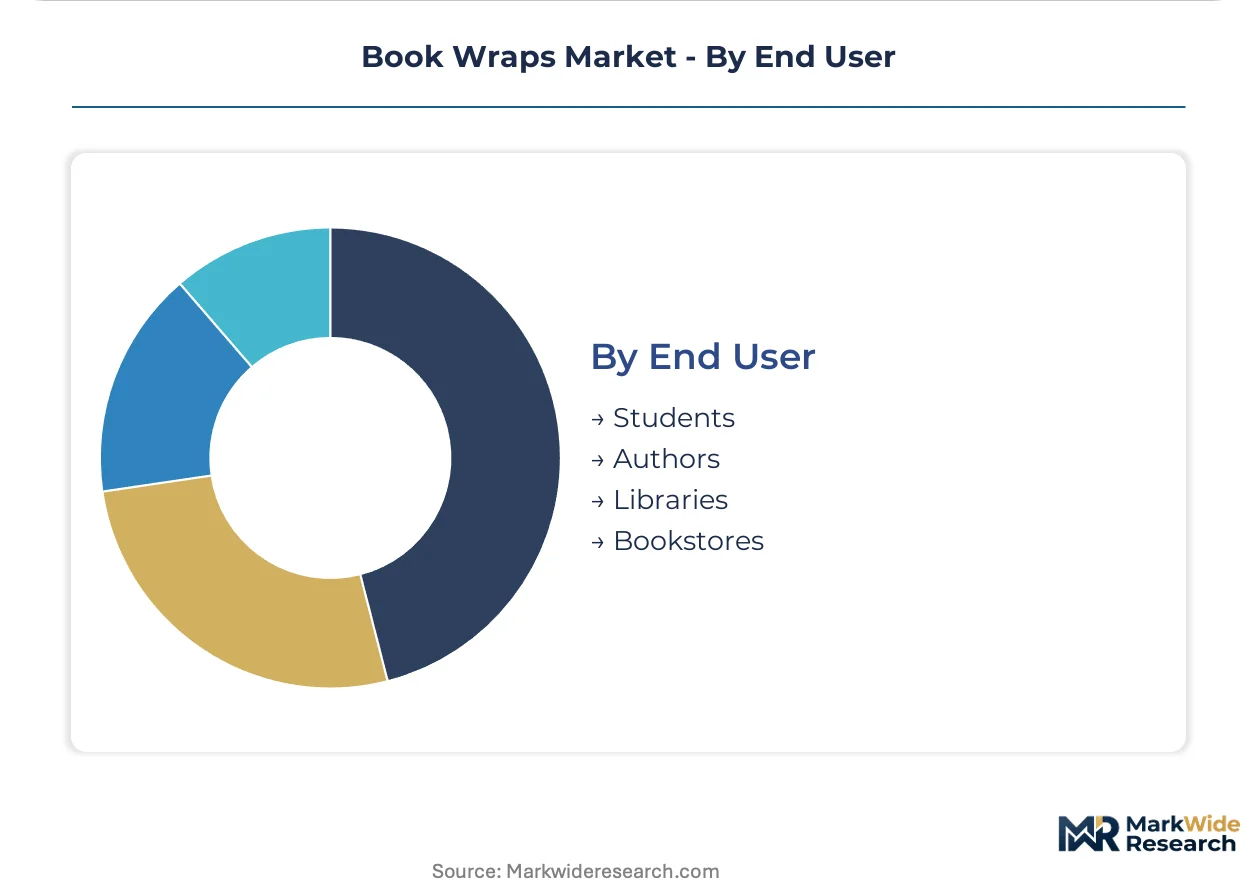
End User:
Procurement authority and volume scale fragment across user categories, with specification power concentrating in institutional buyers while growth concentrates in direct-to-creator models.
- Students:Price-sensitive demand concentrates in semester-start purchasing windows, with durability requirements modest relative to protective function.
- Authors:Self-publishing and crowdfunding participants specify branded wraps as backer reward tiers, creating short-run digital print demand.
- Libraries:Municipal and academic systems issue detailed specifications for circulating collection protection, with magnetic closures and abrasion resistance as non-negotiable requirements.
- Bookstores:Independent and specialty retailers differentiate through proprietary wrap designs, with California-based chains leading fiber-based substrate adoption.
Library procurement anchors volume commitments; author-direct channels show the steepest expansion trajectory as platform infrastructure enables bypass of traditional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent bookstores and specialty retailers in Germany anchor premium procurement volumes for archival-grade wraps. California's SB 54 implementation is forcing substrate transitions among converters serving North American distribution. Heritage publishing clusters in Western Europe sustain demand for fabric and leather enclosures with documented fiber provenance.
United States
California-based independent bookstore chains are specifying fiber-based wraps to satisfy SB 54 recyclability mandates. The EPA and California's Department of Resources Recycling and Recovery penalize multi-material constructions through extended producer responsibility frameworks. Los Angeles and San Francisco metro areas concentrate converter capacity for molded fiber forming technology serving author-direct fulfillment channels.
Germany
Heritage academic and specialty publishing houses in Tübingen and Göttingen maintain procurement standards requiring fabric wraps with archival-grade closures. EU REACH substance restrictions and FSC chain-of-custody standards govern chemical content and fiber provenance for all wraps entering European distribution. Bavaria and Baden-Württemberg host tannery-linked suppliers serving collector edition leather wrap demand.
United Kingdom
Self-publishing platforms and crowdfunding campaigns in London and Manchester generate short-run digital print demand for customizable wraps. The UK's implementation of EU packaging waste directive analogues is eliminating plastic-laminated constructions from retail channels. The Midlands concentrate die-cutting and UV print infrastructure serving author-direct fulfillment models.
Japan
Premium gift wrap traditions in Tokyo and Osaka sustain demand for corozo and metal button closure mechanisms on fabric substrates. METI standards and JIS certification requirements shape supplier qualification protocols for protective packaging entering distribution. The Kansai region maintains specialized finishing capacity for illustrated and patterned wraps serving collector markets.
India
Educational procurement in Delhi-NCR and Maharashtra concentrates demand for kraft linerboard wraps with Velcro fasteners in budget-tier segments. BIS standards govern substrate specifications for institutional purchases, while DGFT export frameworks shape converter access to European retail channels. Gujarat hosts recycled fiber processing clusters supplying domestic and export wrap manufacturers.
Book Wraps Market Competitive Environment
North American producers anchor volume-tier supply through craft retail channel dominance; European specialists hold premium positioning via heritage publishing relationships. The vendor base splits between geographic scale players and substrate-specific fabricators. Three archetypes define competitive positioning: fiber-based sustainability specialists, magnetic closure system innovators, and leather substrate premium-tier suppliers. Capacity expansion and FSC chain-of-custody certification represent the dominant competitive moves as EPR compliance deadlines compress.
Among North American sustainability-focused fabricators, EcoPack Solutions exemplifies the in-house recycled kraft substrate archetype through captive supply chain control. WrapMaster occupies a position representing geographic dominance across craft retail channels with established distributor relationships. SafePack sits within the institutional procurement specialist tier, serving library specification requirements for magnetic closure systems and abrasion-resistant constructions.
| Leading Market Players |
|---|
| WrapMaster |
| SecureWrap |
| EcoPack Solutions |
| FlexiWrap |
| BookGuard |
| SafePack |
| PackShield |
| WrapIt |
| EcoWraps |
| Others |
Value Chain & Pricing Dynamics
Kraft linerboard and recycled fiber input costs fluctuate with energy markets, compressing converter margins on paper-based wrap contracts before these pressures cascade into three-tier pricing structure across premium, standard, and economy levels. California's SB 54 recyclability mandates and EU Single-Use Plastics Directive analogues are eliminating plastic-laminated constructions, forcing substrate transitions that reshape procurement economics for independent bookstores and library systems.
Pricing Analysis
Volume placements concentrate in paper-based wraps at economy-tier pricing, while leather and fabric alternatives command concentrated margin pools in gift and collector segments. Price differentiation hinges on certification grade—FSC chain-of-custody and archival-grade closures—and customization level enabled by short-run digital print capabilities. Cost compression in fiber-based tiers is intensifying because pulp price volatility tracks energy markets, with independent bookstores in North America showing greatest price sensitivity and German heritage publishing houses least.
Supply Chain Analysis
Direct-to-author fulfillment channels handle short-run digital print demand from self-publishing platforms and crowdfunding campaigns. Raw material sourcing draws from Italy and India for tannery-linked leather substrates, China for magnetic closure components, and domestic North American clusters for molded fiber forming capacity. Single-source vulnerability concentrates in Italian and Indian tannery capacity for premium leather wraps. Distribution runs through craft retail channels, institutional procurement specifications, and emerging author-direct platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Book Wraps Market sits in a substrate-transition phase as molded fiber forming technology displaces die-cut corrugated and plastic-laminated constructions under extended producer responsibility frameworks.
For Market Incumbents: Cement FSC chain-of-custody certification across product lines to secure preferred vendor status with European retailers and institutional buyers facing REACH substance restrictions. Deepen backward integration into recycled kraft substrate production to insulate margin pools from pulp price volatility threatening paper-based wrap contracts. For New Entrants and Emerging Players: Author-direct digital channels offer the most penetrable entry vector, with self-publishing platforms and crowdfunding campaigns generating short-run demand for customizable wraps with variable-data printing. Target North American independent bookstore chains seeking fiber-based alternatives to satisfy California SB 54 mandates, positioning on rapid-turn digital print capabilities and mono-material kraft constructions. For Investors and Strategic Acquirers: Distressed-cycle entries favor magnetic closure system innovators with established library procurement relationships in North America and Western Europe. Long-term viability over a multi-year horizon rests on converters capable of rapid substrate reformulation under compressed EPR compliance timelines. Monitor California's phased implementation deadlines and analogous state-level enactments for inflection signals on forced product line transitions.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | Secures preferred vendor status with European retailers and institutional buyers requiring documented fiber provenance. |
| Backward Integration into Recycled Kraft | Captive supply of molded fiber substrates insulates margins from pulp price volatility driven by energy markets. |
| Digital Print Infrastructure Investment | Enables short-run customization for author-direct channels and crowdfunding platform fulfillment requirements. |
| Magnetic Closure System Expansion | Captures library procurement volume as neodymium flap designs displace adhesive and tie-based alternatives. |
| Geographic Capacity Expansion | Los Angeles and San Francisco metro clusters serve California SB 54 compliance demand with localized converter presence. |
Study Parameters
Trade association filings, customs and trade databases, and SEC 10-K disclosures from publicly listed packaging converters formed the secondary backbone of this analysis. Primary interviews with plant managers at molded fiber forming facilities, procurement leads at independent bookstore chains, library collection management officers, and regulatory affairs specialists at substrate suppliers were triangulated against secondary validation. Bottom-up volume modeling across material type, closure mechanism, design style, and end-user segments was cross-referenced with top-down market sizing from trade flow analysis.
Bottom-up unit economics were aggregated across substrate categories and closure types, then reconciled with top-down value estimates derived from trade data and channel flow analysis. Segmentation dimensions modeled include material substrate, closure mechanism, design style, end-user category, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of volume and value trajectories, incorporating pulp price volatility assumptions, EPR implementation timelines, and digital print infrastructure buildout rates as industry-specific forecast inputs.
The model holds under stable regulatory implementation timelines and continued pulp price volatility within historical bands; deviation in accelerated EPR phase-outs or energy market shocks would shift volume trajectories. Forecasts reflect assumptions about substrate substitution rates and author-direct channel expansion. Practitioners should monitor California Department of Resources Recycling and Recovery enforcement patterns and EU packaging waste directive analogues for early signals of compliance timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Standard Liner Market
Packaging Materials
Reel in Box Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Neoprene Coffee Sleeves Market