
 Trifold Packaging Market | 2026-2036
Trifold Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Trifold Packaging Market Analytics
Converter-level print engineering talent is rotating toward digital finishing and short-run customization, tightening labor availability for conventional folding-carton operations. Amcor leverages its global pre-media network to sustain high-volume pharmaceutical trifold contracts. WestRock anchors North American corrugated trifold production through integrated pulp-to-box mills. Mondi Group differentiates via kraftliner-based trifold formats for fresh-protein shelf display.
Trifold packaging denotes a three-panel carton or sleeve structure scored to fold into a compact protective enclosure, typically manufactured from SBS paperboard, microflute corrugated, or recycled Kraft liner between 12 and 24 points caliper, with glue-free or friction-lock closure for hand-assembly at packing lines. Its primary purpose is to deliver rigid protection combined with flat-ship efficiency for retail-ready presentation. Paper-based trifold formats lead volume across food and beverage end users where shelf aesthetics and recyclability converge, while biodegradable substrates represent the fastest-growing segment as brand owners face extended producer responsibility mandates. Flat pack form factors dominate logistics economics, though display box variants command higher margin pools in cosmetics and electronics channels.
FDA enforces child-resistant packaging standards for over-the-counter pharmaceuticals distributed in trifold blister formats, while EPA guidelines on recycled fiber content shape substrate selection for domestic converters. The EU Green Deal and REACH chemical restrictions limit certain coatings and adhesives in paper trifold applications bound for European retail. Stakeholders must monitor evolving state-level extended producer responsibility legislation and decide whether to regionalize substrate sourcing or absorb compliance-driven cost pass-throughs.
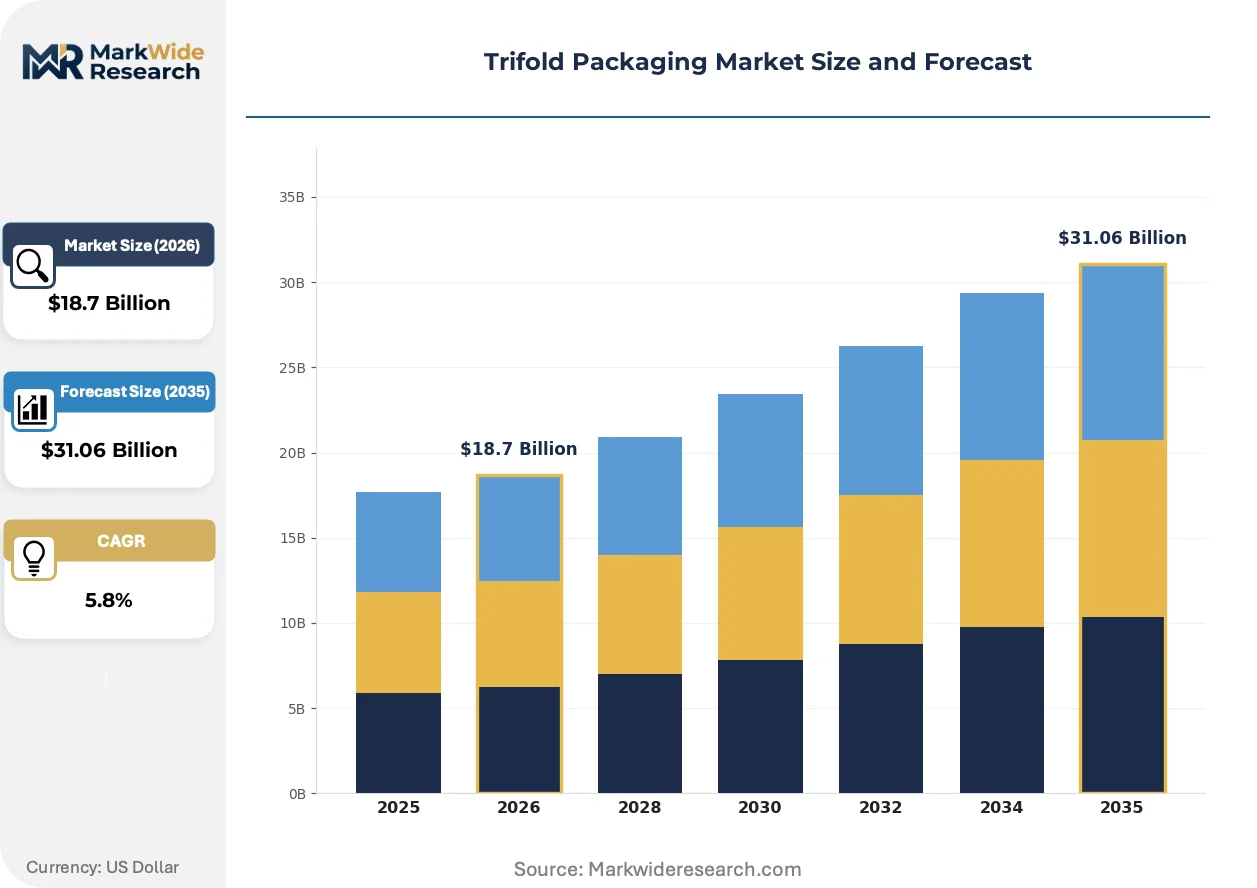
Market Dynamics
EU Packaging and Packaging Waste Regulation material recovery targets are compressing substrate choice timelines for converters, forcing rapid qualification of paper-based alternatives before 2030 mandates take full effect.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distributors in Germany are specifying trifold sleeves with integrated thermal barriers for precision component protection during international transit.
- REACH chemical restrictions:ECHA limits on certain coatings and adhesives are accelerating converter migration toward bio-based barrier technologies for European-bound retail packaging.
- Automotive parts export protocols:German automotive suppliers have standardized trifold formats for precision component protection, creating specification pull-through across tier-one supplier networks.
Market Restraints
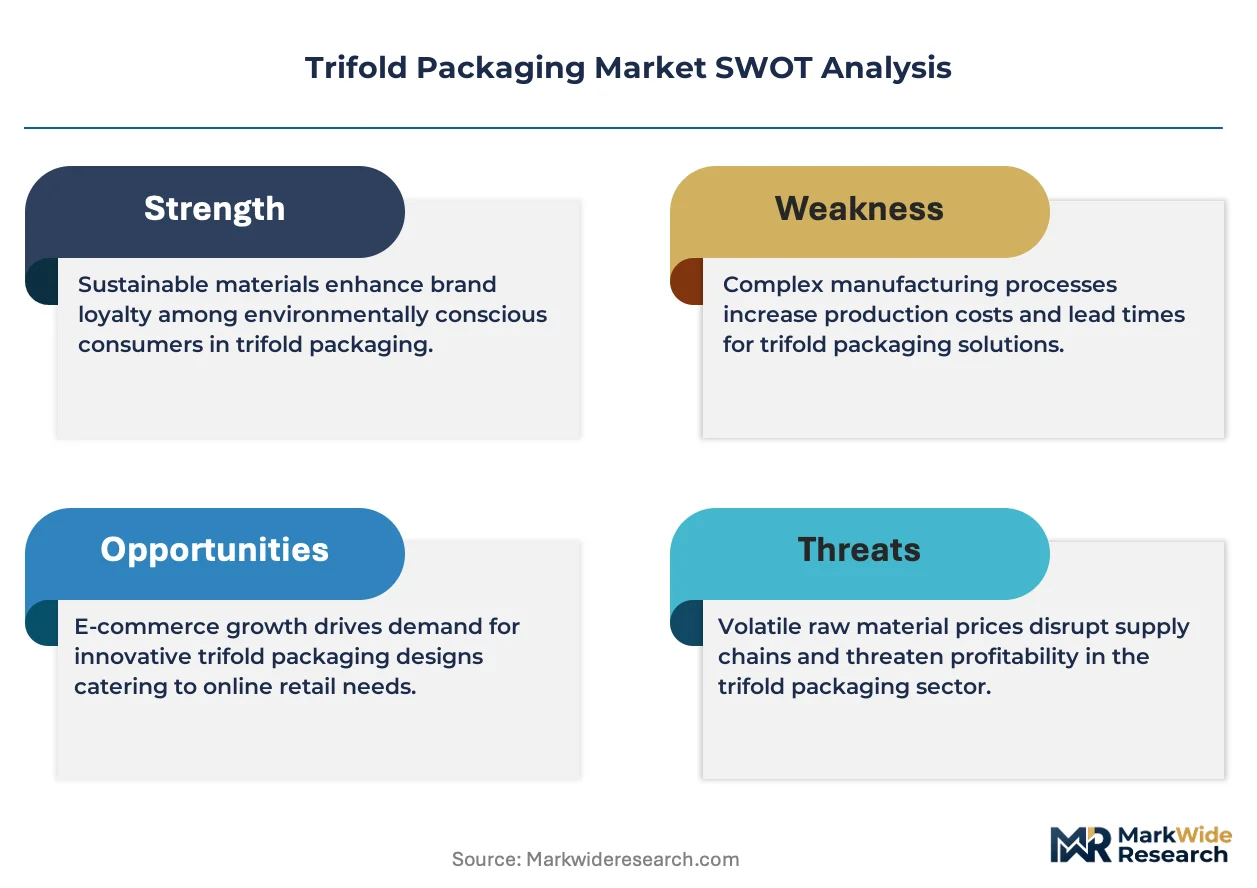
- Pulp price volatility:SBS paperboard and kraftliner input costs fluctuate with Nordic softwood pulp contract pricing, squeezing converter margins on fixed-price annual contracts.
- Print engineering labor scarcity:Digital finishing and short-run customization are drawing skilled operators away from conventional folding-carton operations, tightening availability for high-volume pharmaceutical contracts.
- Rigid box substitution:Premium cosmetics and electronics brands are testing hinged rigid boxes with magnetic closures for unboxing experiences that paperboard trifolds cannot replicate.
Strategic Opportunities
- Extended producer responsibility tailwinds:EU Green Deal implementation is creating compliance-driven demand for biodegradable substrate trifolds among brand owners facing packaging fee escalations.
- Fresh-protein shelf display convergence:Mondi Group's kraftliner-based formats demonstrate path for moisture-resistant paper trifolds to capture share from expanded polystyrene trays in European retail meat cases.
- Digital finishing integration:Hybrid production lines combining offset base printing with inkjet personalization enable lot-size-one pharmaceutical serialization without plate changeover delays.
Industry Challenges
- Pre-media talent attrition:Converter-level print engineering expertise is rotating toward digital workflows, leaving gaps in die-line optimization and scoring calibration for complex friction-lock designs.
- Multi-jurisdiction certification complexity:FDA child-resistant standards for OTC pharmaceuticals, EPA recycled fiber guidelines, and REACH chemical restrictions create overlapping compliance timelines that delay new product launches.
- Flat-pack assembly line integration:Glue-free and friction-lock closure mechanisms require precise hand-assembly protocols that conflict with automated packing line speeds in high-volume distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trifold Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Plastic, Metal, Biodegradable End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Form: Flat Pack, Rigid Box, Sleeve, Display Box Packaging Type: Primary, Secondary, Tertiary, Custom |
| Companies Covered | Amcor, WestRock, Sonoco, Smurfit Kappa, Mondi Group, Huhtamaki, Sealed Air, Berry Global, Uflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trifold Packaging Market Evolving Landscape
Active substrate experimentation is reshaping competitive positioning across pharmaceutical, food, and cosmetics channels as converters race to qualify paper-based alternatives ahead of regulatory deadlines.
Water-based barrier coatings are displacing polyethylene-laminated paperboard in fresh-protein and frozen-food applications. German retailers and French supermarket chains are piloting these formats for modified-atmosphere packaging. The structural shift is compressing demand for conventional extrusion-coated substrates in temperature-controlled supply chains.
EU Green Deal packaging fee structures are forcing brand owners to internalize end-of-life costs. EPR fee differentials between recyclable paper and multi-material laminates are redirecting R&D budgets toward mono-material trifold designs. Cosmetics houses in Italy and the Netherlands are reformulating specifications to capture fee advantages.
Brand owner sustainability scorecards now weight packaging recyclability in supplier selection. Procurement teams at European pharmaceutical distributors and North American food manufacturers are disqualifying converters lacking certified fiber chain-of-custody documentation. The practice is most visible in Germany, where automotive parts exporters require packaging suppliers to demonstrate closed-loop recovery partnerships.
Trifold Packaging Market Segmentation
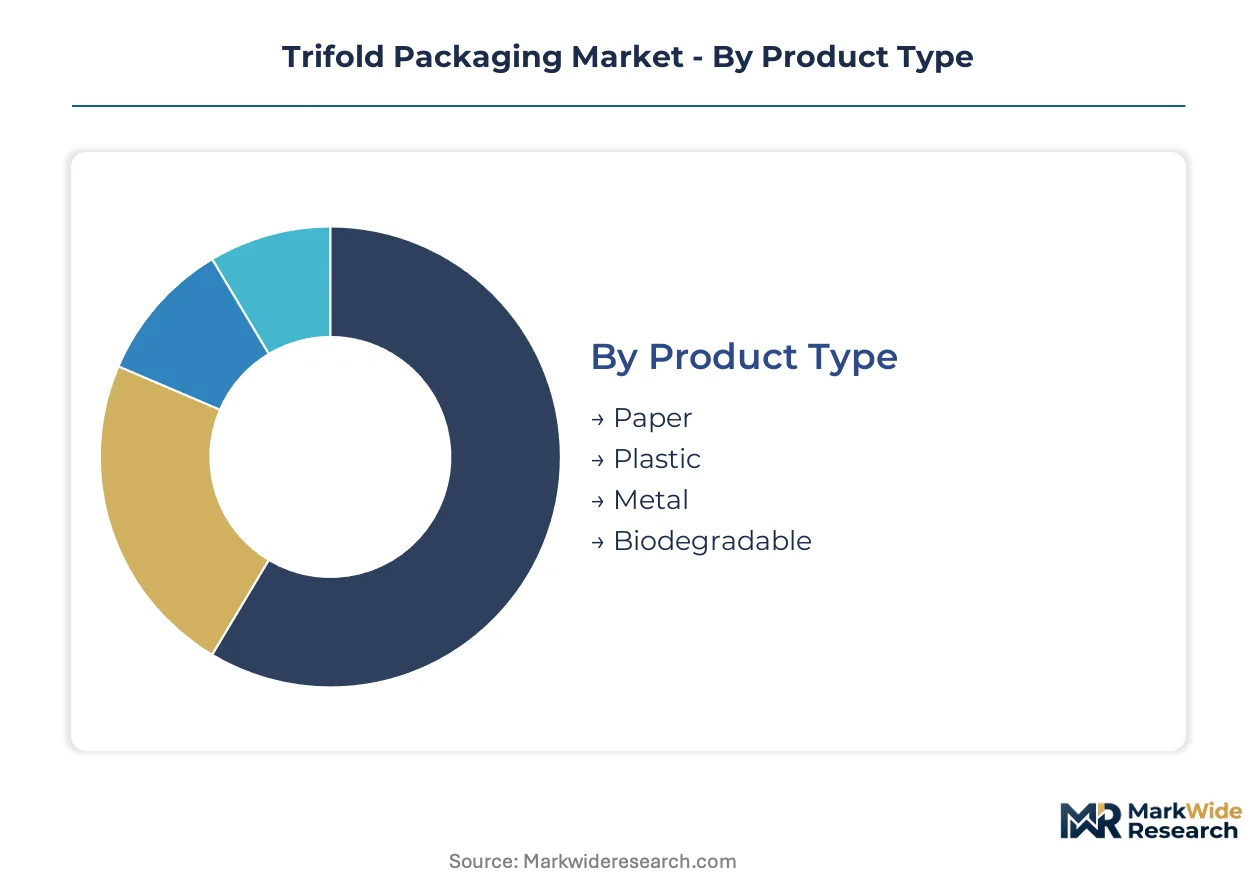
Trifold packaging serves divergent channel economics where flat-pack pharmaceutical formats and display-box cosmetics applications carry fundamentally different margin profiles and tooling requirements. Segmentation reveals how substrate choice and structural form factor determine converter specialization and customer lock-in intensity across end-use verticals.
Product Type:
Paper formats flow through high-volume food retail and pharmaceutical cold-chain channels, while biodegradable substrates command premium positioning in cosmetics and European export markets facing EPR fee structures.
- Paper:SBS paperboard and kraftliner grades between 12-24 points caliper dominate food and beverage shelf presentation where recyclability drives procurement decisions. German automotive parts exporters specify paper-based trifold sleeves for precision component protection during international transit, with REACH-compliant barrier coatings replacing polyethylene laminates under tightening chemical restrictions.
- Biodegradable:Cellulose-based and bio-polymer substrates incorporate moisture-resistant barriers for fresh-protein retail cases, capturing share from expanded polystyrene trays. EU Green Deal packaging fee escalations are accelerating brand owner migration toward certified compostable formats that qualify for reduced extended producer responsibility levies in France and the Netherlands.
- Plastic:PET and PP formats persist in temperature-sensitive pharmaceutical blister applications requiring child-resistant compliance under FDA standards.
- Metal:Aluminum-laminated trifolds serve niche luxury cosmetics segments demanding premium unboxing rigidity and electromagnetic shielding for electronics accessories.
Paper dominates installed base. Biodegradable formats are where expansion concentrates.
End User:
Customer concentration varies sharply by order frequency and specification complexity, with pharmaceutical contracts demanding serialization compliance and automotive suppliers requiring die-line precision that generalist converters cannot match.
- Pharmaceuticals:Temperature-sensitive biologics distributors specify trifold sleeves with integrated thermal barriers, requiring FDA child-resistant certification for over-the-counter blister formats and EMA compliance for European distribution. German cold-chain logistics providers are standardizing these specifications across tier-one supplier networks.
- Food & Beverage:Modified-atmosphere packaging applications in German and French retail chains are piloting water-based barrier coatings on paperboard trifolds for fresh-protein display cases, displacing conventional extrusion-coated substrates in temperature-controlled supply chains.
- Cosmetics:Italian and Dutch cosmetics houses are reformulating specifications toward mono-material paper designs to capture EPR fee advantages under EU Green Deal structures.
- Electronics:Precision component protection requirements mirror automotive specifications, with anti-static coatings and friction-lock closures for hand-assembly at packing lines.
Pharmaceuticals anchor high-margin contract stability. Food and beverage delivers volume scale.
Form:
Structural configuration determines logistics economics and automation compatibility, with flat-pack formats optimizing container utilization and rigid box variants capturing display premiums at point of sale.
- Flat Pack:Glue-free or friction-lock closure mechanisms enable hand-assembly at high-volume distribution centers, dominating pharmaceutical and food service logistics where shipping cube efficiency outweighs presentation requirements. EPA recycled fiber guidelines shape substrate selection for domestic US converters serving this segment.
- Display Box:Shelf-ready formats with reinforced panels and window apertures command margin premiums in cosmetics and electronics channels where unboxing experience influences brand perception. Premium brands are testing hinged rigid boxes with magnetic closures as substitutes for paperboard trifolds in luxury positioning.
- Sleeve:Open-ended trifold wraps provide component protection with minimal material usage, favored by German automotive parts exporters for precision hardware.
- Rigid Box:Thick paperboard or composite structures with laminated finishes serve gift-set and limited-edition cosmetics applications.
Flat pack commands logistics-driven volume. Display box captures shelf-premium pricing.
Packaging Type:
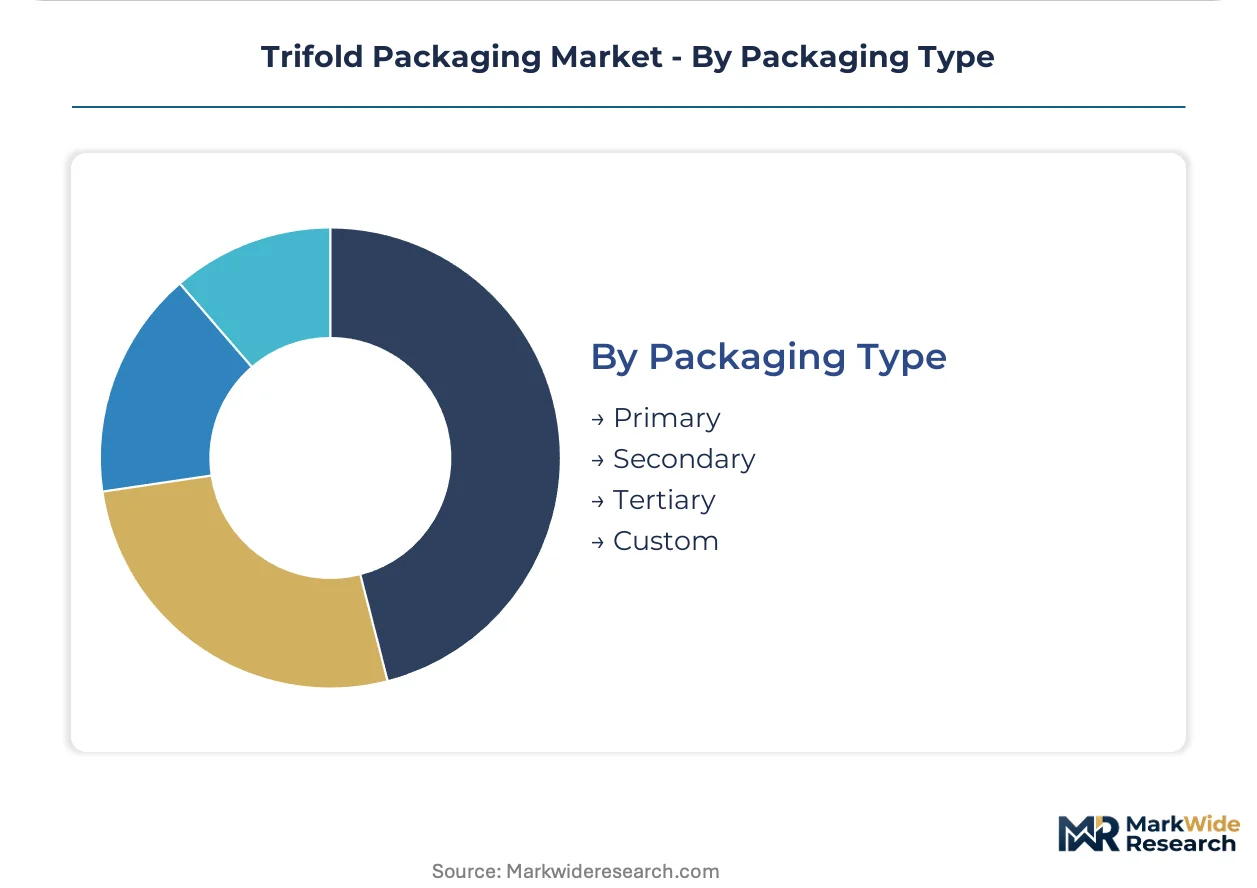
Hierarchy position in the packaging system determines regulatory exposure and converter qualification requirements, with primary packaging facing direct food-contact and pharmaceutical safety standards.
- Primary:Direct-product-contact trifolds for pharmaceuticals and food carry FDA, EFSA, and national pharmaceutical regulator compliance burdens, requiring certified fiber chain-of-custody documentation that disqualifies uncertified converters from European and North American procurement shortlists.
- Secondary:Outer cartons and grouping sleeves for retail multipacks face lighter regulatory scrutiny but must integrate with automated packing line speeds, creating tension with glue-free hand-assembly protocols.
- Tertiary:Shipping containers and pallet wraps prioritize cube utilization and stack strength over presentation, with corrugated microflute formats dominating this layer.
- Custom:Lot-size-one pharmaceutical serialization and short-run cosmetics personalization require hybrid production lines combining offset base printing with inkjet personalization without plate changeover delays.
Secondary packaging dominates transaction volume. Custom formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging fee structures and REACH chemical restrictions are compressing substrate qualification timelines across European converters, while FDA child-resistant standards and EPA recycled fiber guidelines shape procurement decisions in North American pharmaceutical and food channels.
Germany
Automotive parts exporters in Baden-Württemberg and Bavaria specify trifold sleeves for precision component protection during international transit, with tier-one suppliers standardizing these formats across supplier networks. KBA vehicle safety protocols indirectly influence packaging durability specifications for shipped components. Stuttgart's automotive cluster drives die-line precision requirements that generalist converters cannot match.
United States
Pharmaceutical distributors specify trifold blister formats with FDA child-resistant certification for over-the-counter medications, while food manufacturers face EPA recycled fiber guidelines in substrate selection. Cold-chain logistics providers in the Northeast and Midwest are piloting thermal-barrier sleeves for temperature-sensitive biologics. Chicago's pharmaceutical packaging corridor anchors high-volume contract stability for domestic converters.
France
French supermarket chains pilot water-based barrier coatings on paperboard trifolds for fresh-protein modified-atmosphere packaging, displacing extrusion-coated substrates in retail meat cases. ANSM pharmaceutical packaging standards align with broader EU regulatory frameworks. The Lyon-Grenoble logistics corridor concentrates converter activity serving protein processors and cosmetics houses.
China
SAMR packaging safety standards and GB standards for food-contact materials shape substrate selection for domestic and export-bound trifold production. E-commerce fulfillment centers in the Yangtze River Delta demand flat-pack formats optimizing shipping cube efficiency. Shanghai's converter cluster supplies both domestic pharmaceutical distributors and export-oriented electronics manufacturers.
India
CDSCO pharmaceutical packaging regulations and FSSAI food-contact standards drive compliance investments among domestic converters serving generic drug exporters and processed food brands. BIS certification requirements for paperboard grades filter supplier qualification. Gujarat's pharmaceutical packaging belt and Maharashtra's food processing corridors concentrate converter capacity expansion.
Trifold Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational converters controlling high-volume pharmaceutical contracts through certified fiber chain-of-custody documentation while regional players capture fresh-protein and automotive sleeve applications. The structure rewards backward integration into pulp supply and pre-media network scale. Two archetypes dominate: integrated multinational converters with global pre-media capabilities, and regional specialists with die-line precision for automotive and electronics protection. Competitive moves center on hybrid production line investments combining offset base printing with inkjet personalization, and rapid qualification of bio-based barrier technologies ahead of regulatory deadlines.
Among integrated multinational converters, Amcor and WestRock occupy positions exemplifying global pre-media network scale and integrated pulp-to-box production respectively. Mondi Group represents the kraftliner-based specialist archetype, with its fresh-protein formats demonstrating moisture-resistant paper trifold pathways. These three companies anchor the competitive landscape without exhausting its diversity, as regional specialists in Germany, India, and China continue capturing automotive and electronics sleeve contracts through die-line precision and proximity to manufacturing clusters.
| Leading Market Players |
|---|
| Amcor |
| WestRock |
| Sonoco |
| Smurfit Kappa |
| Mondi Group |
| Huhtamaki |
| Sealed Air |
| Berry Global |
| Uflex |
| Others |
Value Network & Pricing Analysis
Forty-five-day pulp inventory cycles at Nordic softwood mills translate directly into converter pricing power during contract renegotiations, with German automotive suppliers and North American pharmaceutical distributors absorbing divergent pass-through structures. This lead-time compression concentrates margin pressure on fixed-price annual contracts while rewarding backward-integrated players with captive fiber supply.
Pricing Analysis
Geographic price spreads between German kraftliner grades and North American SBS paperboard reflect divergent energy cost burdens and regulatory compliance investments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pharmaceutical formats from REACH-compliant European exports and generic food-service applications. Cost compression in standard-tier paperboard is intensifying because pulp contract volatility outpaces converter hedging capacity. Food and beverage buyers exhibit highest price sensitivity due to thin retail margins, while pharmaceutical distributors prioritize certification reliability over unit cost.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container lanes elevates inbound logistics costs for Swedish and Finnish pulp shipments destined for German converter clusters. Raw material supply concentrates in Sweden, Finland, and Brazil for softwood pulp, with Germany, China, and the United States anchoring downstream converting capacity. Single-source vulnerability persists in specialized barrier coating chemicals subject to REACH authorization delays. Distribution runs through tier-one automotive supplier networks and pharmaceutical cold-chain logistics providers with certified chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trifold packaging market sits in early-cycle recovery as EU Green Deal packaging fee structures force brand owner specification changes ahead of 2030 mandates. This regulatory-driven replacement wave creates asymmetric opportunity for prepared converters.
For Market Incumbents: Secure die-line engineering talent through apprenticeship pipelines and digital finishing cross-training before pre-media expertise attrition widens. Capture tier-one automotive supplier networks in Baden-Württemberg by demonstrating KBA-aligned durability protocols. Backward integration into certified fiber sourcing insulates margin positions from Nordic pulp contract volatility.
For New Entrants and Emerging Players: Lead with bio-based barrier coating qualifications for French and Dutch fresh-protein retail chains facing EPR fee escalations. White-space concentrates in moisture-resistant paper trifolds displacing expanded polystyrene trays. Target regional pharmaceutical distributors in India and China lacking FDA serialization capabilities through hybrid offset-inkjet production partnerships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable substrate conversion lines as ECHA chemical restrictions accelerate equipment replacement cycles. Five-to-ten-year viability favors converters with demonstrated REACH compliance pathways and established automotive supplier relationships. Monitor EU Packaging and Packaging Waste Regulation implementation timelines as inflection signal for paper-based substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Production Line Investment | Enables lot-size-one pharmaceutical serialization without plate changeover delays at Chicago corridor converters. |
| Bio-Based Barrier Qualification | Captures EPR fee advantages for Mondi Group formats in French supermarket fresh-protein pilots. |
| Automotive Supplier Network Lock-In | Stuttgart cluster specifications create specification pull-through resistant to price competition. |
| Certified Fiber Chain-of-Custody | Disqualifies uncertified competitors from European pharmaceutical and North American food procurement shortlists. |
| Digital Finishing Talent Acquisition | Addresses print engineering labor scarcity tightening availability for high-volume pharmaceutical contracts. |
Research Methodology
A spread of perspectives from converter operations directors, pharmaceutical packaging procurement managers, automotive tier-one supplier quality engineers, and retail category buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC filings from integrated packaging multinationals, EU ECHA regulatory databases, and FDA packaging guidance documents. Bottom-up volume estimates triangulated against top-down market sizing across substrate grades and end-use verticals.
Segmentation dimensions modeled include substrate material, end-use industry, structural form factor, packaging hierarchy position, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement demand timing, and penetration assumptions across the projection horizon. Forecast inputs incorporated EU Green Deal implementation schedules, REACH chemical restriction timelines, and pharmaceutical cold-chain logistics expansion trajectories.
Underlying assumptions cover sustained pulp price volatility, regulatory deadline adherence, and converter qualification pace, with deviation risk concentrated in EPR fee structure modifications and barrier coating technology substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cavitated Films Market
Packaging Materials
Fanfold Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Shrink Packaging Market