
 Sandwich Panel System Market | 2026-2036
Sandwich Panel System Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Panel System Market Analytics
A shift from single-source steel supply toward multi-source raw material procurement is rebalancing procurement economics for panel fabricators. Kingspan Group leverages its captive insulation supply chain to sustain margin control across European project pipelines. Nucor Building Systems anchors North American production through integrated steelmaking and roll-forming capacity. ArcelorMittal competes on metallurgical consistency, supplying coated flat steel to multiple downstream panel laminators simultaneously.
A sandwich panel system comprises two rigid metal or composite facings bonded to an insulating core, typically achieving thermal conductivity values between 0.020 and 0.040 W/mK depending on core chemistry. These assemblies function as structural envelope elements that reduce heat transfer in commercial and industrial buildings while providing span capability without secondary steel. Mineral wool panels command premium positioning in fire-rated specifications across European commercial buildings, whereas polyurethane panels dominate cold storage and refrigeration applications where thermal efficiency determines operating cost. Prefabricated installation methods are gaining share in warehouse and factory construction as general contractors compress envelope schedules.
EMA and ECHA frameworks in Europe govern fire reaction classification and chemical substance restrictions in insulating cores, directly influencing product substitution toward mineral wool and halogen-free polyurethane formulations. In the United States, OSHA and ICC building codes enforce worker safety and structural wind-load standards that panel manufacturers must certify through third-party evaluation reports. Stakeholders must monitor evolving carbon border adjustments and embodied carbon disclosure rules that will reshape supplier qualification criteria and core material selection across major construction markets.
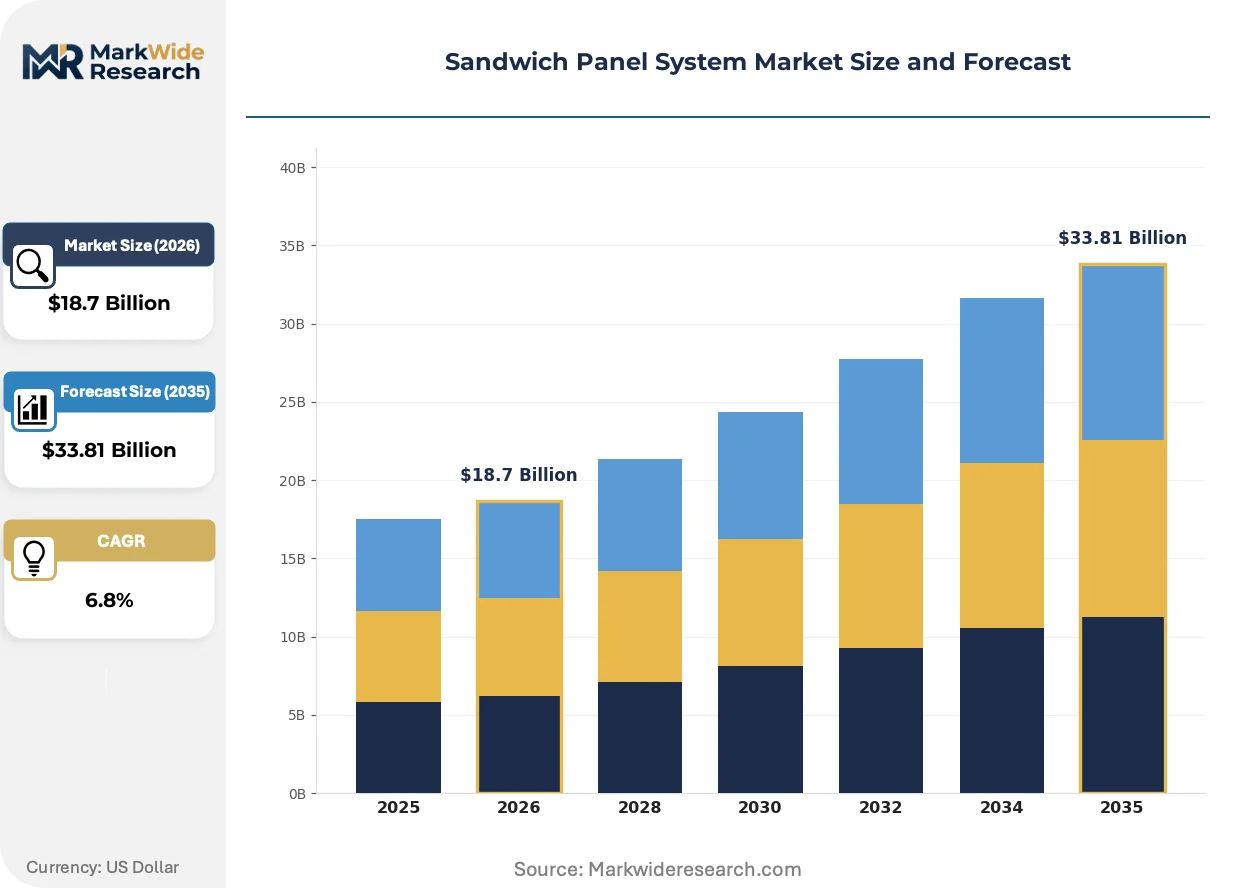
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing thermal performance thresholds across European building codes, forcing panel fabricators to reformulate core chemistries and recertify product lines ahead of enforcement deadlines.
Growth Catalysts
- Cold storage logistics:Warehouse operators in Germany and the Netherlands are procuring polyurethane-cored panels to meet stringent energy efficiency mandates for refrigerated distribution centers.
- REACH chemical restrictions:ECHA frameworks are accelerating substitution toward halogen-free polyurethane and mineral wool formulations in fire-rated commercial specifications.
- Retrofit wave:Industrial building envelope upgrades across German food processing facilities are sustaining elevated panel demand through 2035.
Market Restraints
- Steel input volatility:Coated flat steel prices fluctuate with energy costs, compressing fabricator margins on fixed-price construction contracts.
- Core material concentration:Polyurethane chemical supply clusters in northwestern Europe create geographic vulnerability to logistics disruptions.
- Fire reaction classification:EMA and ECHA testing protocols extend product approval timelines by 8-14 months for new core formulations.
Strategic Opportunities
- Carbon border adjustments:EU CBAM implementation will advantage domestic and near-shore panel producers over imports from carbon-intensive steel regions.
- Prefabricated envelope systems:General contractors are adopting factory-assembled panel modules to compress warehouse construction schedules.
- Embodied carbon disclosure:CSRD reporting requirements are creating premium positioning for manufacturers with verified Environmental Product Declarations.
Industry Challenges
- Fire engineering talent:Shortage of specialists capable of navigating ECHA substance restrictions and EN 13501 reaction-to-fire testing slows product development cycles.
- Core-to-facing bonding certification:Third-party evaluation reports for structural wind-load performance require 12-18 month validation timelines under ICC and OSHA frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Panel System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Panels, Polystyrene Panels, Mineral Wool Panels, Fire-Resistant Panels Application: Construction, Refrigeration, Cold Storage, Industrial End User: Commercial Buildings, Warehouses, Factories, Residential Installation Type: On-Site, Prefabricated, Modular, Custom |
| Companies Covered | Tata Steel, Nucor Building Systems, Kingspan Group, Duowei Union Group, Isopan, ArcelorMittal, Assan Panel, Arconic Inc, Metecno Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Panel System Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape core formulation strategies across the panel fabrication base.
Polyisocyanurate (PIR) core chemistry is expanding into European commercial building specifications as fabricators seek thermal conductivity values below 0.025 W/mK without halogenated flame retardants. German and French distributors are prioritizing PIR-cored inventory for mid-rise office and retail envelopes. This chemistry is expanding into segments previously dominated by polyurethane, compressing the performance gap between cold-storage and general construction panels.
The EU F-Gas Regulation phase-down is forcing refrigerant-dependent cold storage operators to prioritize envelope thermal efficiency over mechanical system upgrades. Panel manufacturers must now certify lambda values under dynamic aging conditions rather than laboratory steady-state testing. German logistics real estate developers are specifying mineral wool cores for fire-rated zones while retaining polyurethane for non-rated spans, creating hybrid procurement patterns.
General contractors are unbundling envelope installation from structural steel erection, creating dedicated panel subcontractor tiers with specialized fastening and sealing equipment. This disintermediation compresses general contractor risk exposure while transferring weatherproofing liability to certified envelope specialists. The model is most visible in Dutch and Belgian warehouse construction, where speed-to-occupancy clauses dominate developer-contractor agreements.
Sandwich Panel System Market Segmentation
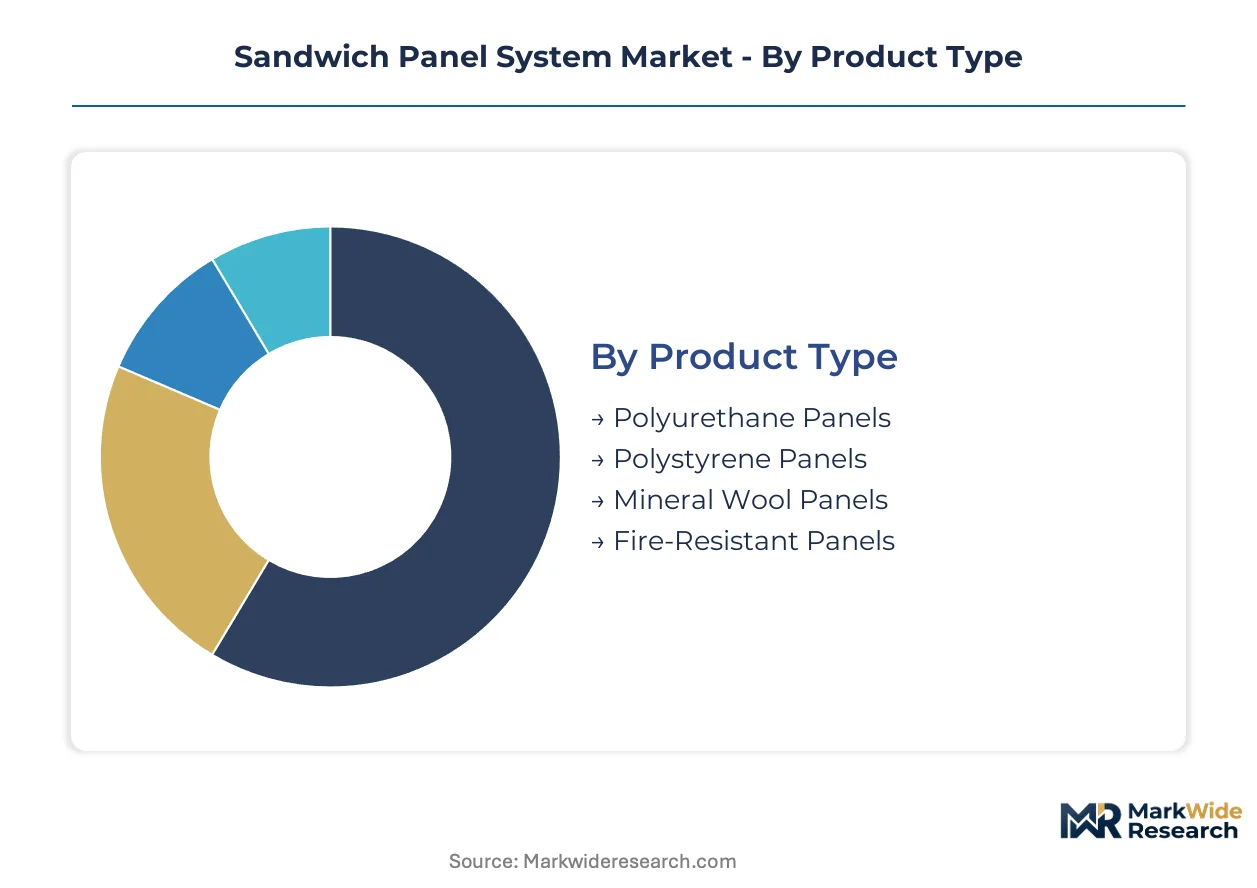
Core chemistry and facing composition determine thermal conductivity, fire reaction classification, and structural span capability across sandwich panel specifications. Certification requirements vary sharply by segment, with fire-rated products demanding EN 13501 testing under EMA frameworks and cold-storage panels requiring lambda validation under dynamic aging protocols.
Product Type:
Fire reaction classification under ECHA and EMA frameworks creates divergent certification burdens across core chemistries, with mineral wool and halogen-free formulations facing extended approval timelines.
- Polyurethane Panels:These panels bond coated steel facings to closed-cell polyurethane foam cores, achieving thermal conductivity values between 0.020 and 0.025 W/mK. German cold storage logistics operators specify polyurethane-cored panels for refrigerated distribution centers under tightening F-Gas Regulation thermal efficiency mandates.
- Mineral Wool Panels:Rock wool or glass wool cores deliver fire resistance ratings up to REI 120 while sacrificing thermal performance to 0.040-0.050 W/mK. French and German commercial building developers procure mineral wool panels for fire-rated mid-rise office envelopes where EN 13501-1 A2-s1,d0 classification is mandatory.
- Polystyrene Panels:Expanded polystyrene cores offer cost-positioned thermal insulation at 0.035-0.040 W/mK, primarily specified in non-rated agricultural and light industrial buildings where fire reaction requirements remain minimal.
- Fire-Resistant Panels:Specialized formulations integrate intumescent coatings or mineral composite cores to achieve extended fire resistance ratings for tunnel linings and high-occupancy infrastructure.
Polyurethane panels sit at the top of the volume ranking, with fire-resistant panels climbing the fastest as infrastructure safety codes tighten across European member states.
Application:
End-use thermal and structural requirements create distinct margin profiles, with refrigeration applications commanding specification premiums over general construction.
- Construction:Commercial and industrial building envelopes specify sandwich panels for roofing and wall cladding, spanning 6-12 meters without secondary steel. Dutch warehouse developers are compressing envelope schedules through prefabricated panel procurement.
- Refrigeration:Food processing facilities and refrigerated distribution centers demand core lambda values below 0.025 W/mK to minimize mechanical cooling loads. Belgian logistics real estate operators specify hybrid procurement patterns combining mineral wool for fire-rated zones with polyurethane for non-rated spans.
- Cold Storage:Deep-freeze facilities operating below -25°C require core formulations resistant to thermal drift and moisture ingress. German food processing facility retrofits are sustaining elevated panel demand through specialized cold storage specifications.
- Industrial:Manufacturing plants and heavy industrial envelopes prioritize structural wind-load performance and chemical resistance over thermal optimization, typically accepting higher conductivity values in exchange for durability.
Construction captures the largest revenue share, while cold storage applications are expanding most quickly as e-commerce fulfillment networks proliferate across Northern Europe.
End User:
Building typology determines procurement scale and specification complexity, with industrial facilities generating repeat volume against fragmented commercial project demand.
- Warehouses:Large-format distribution centers require continuous envelope spans exceeding 15 meters with minimal thermal bridging. General contractors in the Netherlands and Belgium are unbundling envelope installation from structural steel erection to compress speed-to-occupancy timelines.
- Factories:Manufacturing facilities demand panels resistant to chemical exposure, mechanical impact, and elevated humidity levels. German industrial construction activity remains elevated for food processing and automotive component facilities.
- Commercial Buildings:Office and retail envelopes prioritize aesthetic facing finishes and fire reaction classification over extreme thermal performance. French distributors are prioritizing PIR-cored inventory for mid-rise commercial specifications.
- Residential:Multi-family and single-family applications remain marginal due to cost positioning and architectural preference for traditional construction methods.
Warehouses dominate procurement volume, with factories gaining share fastest as reshoring initiatives expand European manufacturing capacity.
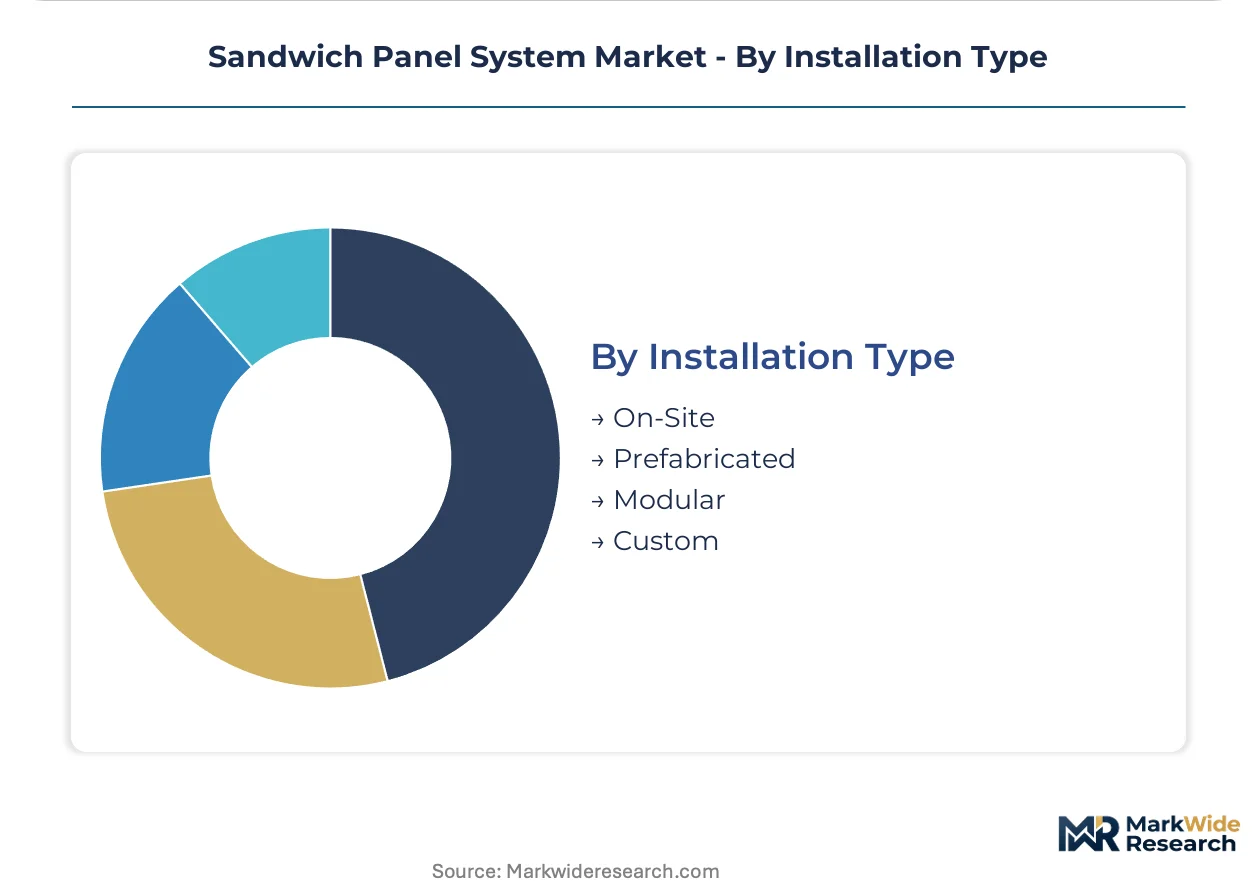
Installation Type:
Delivery methodology determines labor allocation, schedule risk, and weatherproofing liability distribution between general contractors and specialized envelope subcontractors.
- Prefabricated:Factory-assembled panel modules arrive with integrated windows, doors, and sealing systems, reducing on-site labor by 40-60%. Dutch warehouse construction contracts increasingly specify prefabricated envelope systems to meet aggressive occupancy deadlines.
- On-Site:Traditional stick-built panel installation requires specialized fastening and sealing equipment, transferring weatherproofing liability to certified envelope specialists with dedicated crews.
- Modular:Complete volumetric units incorporating sandwich panel walls enable rapid deployment for temporary or relocatable facilities.
- Custom:Project-specific dimensions, core chemistries, and facing finishes address non-standard architectural or performance requirements.
On-site installation retains the largest project count, with prefabricated systems capturing the steepest expansion trajectory as general contractors seek schedule certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial construction clusters anchor sandwich panel demand through 2035, with cold storage logistics and food processing retrofits driving specification intensity across Northern European markets.
Germany
Cold storage logistics operators in the Rhine-Ruhr corridor are procuring polyurethane-cored panels for refrigerated distribution centers. The EU F-Gas Regulation mandates thermal efficiency upgrades that compress envelope performance thresholds. Bavarian food processing facilities sustain retrofit demand through specialized panel specifications for deep-freeze environments.
Netherlands
Warehouse developers in the Randstad region specify prefabricated envelope systems to meet aggressive speed-to-occupancy clauses. ECHA frameworks under REACH accelerate substitution toward halogen-free polyurethane formulations. Rotterdam port logistics clusters generate concentrated demand for hybrid procurement combining mineral wool fire-rated zones with polyurethane spans.
France
Mid-rise commercial building developers in Île-de-France prioritize PIR-cored inventory for office and retail envelopes. EMA fire reaction classification protocols extend product approval timelines for new core formulations. Lyon and Marseille distribution hubs are expanding panel procurement for e-commerce fulfillment networks.
Belgium
Logistics real estate operators specify sandwich panels for continuous envelope spans exceeding 15 meters in Antwerp and Liège industrial zones. EU Green Deal thermal performance requirements tighten building code enforcement deadlines. Belgian general contractors are unbundling envelope installation from structural steel erection to compress construction schedules.
United Kingdom
Industrial construction activity in the Midlands and Northern England sustains panel demand for manufacturing facilities and warehouses. UK building regulations enforce structural wind-load standards through third-party certification. London-area commercial developers specify mineral wool panels for fire-rated mid-rise specifications under tightening safety codes.
Sandwich Panel System Market Competitive Landscape
Global majors compete with regional champions across metallurgical supply and captive insulation integration. The vendor base separates into steel-integrated fabricators, independent panel laminators, and captive chemistry specialists. Three archetypes dominate: backward-integrated steel suppliers controlling coated flat steel input costs; independent fabricators sourcing multi-origin raw materials; and chemistry-integrated operators with in-house core formulation. Capacity expansion and strategic raw material partnerships constitute the dominant competitive moves.
Among steel-integrated fabricators, ArcelorMittal and Nucor Building Systems exemplify metallurgical supply chain anchoring. Kingspan Group occupies a position within the chemistry-integrated tier, representing captive insulation supply chain control. These three companies illustrate the structural divergence between raw material self-sufficiency and multi-source procurement economics.
| Leading Market Players |
|---|
| Tata Steel |
| Nucor Building Systems |
| Kingspan Group |
| Duowei Union Group |
| Isopan |
| ArcelorMittal |
| Assan Panel |
| Arconic Inc |
| Metecno Group |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EN 13501 A2-s1,d0 fire-rated mineral wool panels and commodity polyurethane cores manifests in both pricing power and supply chain configuration. Premium mineral wool specifications command structural margins through extended ECHA approval timelines and specialized bonding certification, while polyurethane panel fabricators compete on coated flat steel input costs and captive chemistry integration.
Pricing Analysis
Coated flat steel pass-through dynamics dominate pricing formation across European panel fabricators, with ArcelorMittal metallurgical premiums and energy-cost volatility compressing margins on fixed-price construction contracts. Three-tier pricing structure across premium fire-rated, standard commercial, and economy agricultural levels differentiates by EN 13501 certification grade and lambda thermal performance. Cost compression in standard commercial tiers is intensifying because general contractors unbundle envelope installation and transfer weatherproofing liability. Cold storage logistics operators show least price sensitivity due to F-Gas Regulation thermal efficiency mandates, while agricultural buyers prioritize economy polystyrene specifications.
Supply Chain Analysis
Specialized fire engineering talent shortages in Germany, France, and the Netherlands constrain production scaling for ECHA-compliant core formulations. Polyurethane chemical supply clusters in northwestern Europe draw from MDI and polyol feedstock streams anchored in Belgian and German petrochemical complexes. Single-source vulnerability to logistics disruptions at Rotterdam and Antwerp port hubs threatens just-in-time panel delivery for Dutch warehouse developers. Distribution runs through regional fabricator networks with certified envelope subcontractor tiers handling specialized fastening and sealing installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sandwich panel system market operates as a regulatory compounder where EU F-Gas Regulation thermal performance mandates and ECHA chemical restrictions continuously reshape specification demand and supplier qualification criteria.
For Market Incumbents: Acquire captive insulation formulation capabilities to defend margin control against steel-integrated competitors like Kingspan Group. Secure ECHA pre-registration for halogen-free polyurethane chemistries ahead of REACH restriction deadlines. Add certified envelope installation capacity in the Randstad region to capture unbundling general contractor demand. For New Entrants and Emerging Players: The price-point gap between premium mineral wool fire-rated panels and economy polystyrene agricultural specifications offers white-space entry for mid-tier PIR-cored commercial products. Target French mid-rise office developers prioritizing PIR inventory for Île-de-France retail envelopes. Pursue project-based partnerships with Dutch logistics real estate operators specifying hybrid procurement patterns. For Investors and Strategic Acquirers: Asymmetric upside sits with chemistry-integrated mid-cap specialists with verified Environmental Product Declarations under CSRD reporting requirements. Long-term viability favors fabricators controlling both core formulation and regional installation networks. Monitor EU CBAM implementation progress as inflection indicator for domestic versus import competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Chemistry | Kingspan Group's captive insulation supply chain sustains margin control across European project pipelines. |
| EN 13501 Fire Reaction Certification Investment | EMA and ECHA testing protocols extend product approval timelines, creating defensive moats for certified fabricators. |
| Prefabricated Envelope Module Expansion | Dutch warehouse developers compress speed-to-occupancy clauses through factory-assembled panel procurement. |
| Halogen-Free Polyurethane Formulation Pivot | REACH chemical restrictions accelerate substitution toward ECHA-compliant core chemistries in commercial specifications. |
| Regional Installation Network Buildout | Belgian and Dutch general contractors unbundle envelope installation, transferring weatherproofing liability to certified specialists. |
Research Methodology
Bottom-up cold storage and warehouse construction modeling reconciled against top-down coated flat steel and chemical feedstock tracking forms the analytical core. Primary interviews with panel fabricator procurement directors, ECHA regulatory affairs specialists, Dutch general contractor envelope managers, and German food processing facility engineers combined with secondary validation from EU Green Deal implementation documents, ECHA substance restriction databases, EN 13501 certification registries, and European construction output statistics.
Historical trendline analysis across thermal conductivity performance tiers, core chemistry substitution patterns, and regional installation methodology shifts established baseline growth trajectories. Segmentation dimensions modeled include fire reaction classification grade, end-use thermal requirement, prefabricated versus on-site delivery mode, and regional regulatory enforcement cluster. CAGRs were derived through elasticity analysis of construction permit volumes against F-Gas Regulation compliance deadlines and embodied carbon disclosure adoption curves.
Caveats apply where ECHA substance restriction timeline acceleration, EU CBAM carbon border adjustment scope expansion, or coated flat steel energy-cost volatility could materially shift the outlook. Forecasts reflect assumptions around REACH chemical substitution pace and general contractor unbundling adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Cultured Marble Market