
 Middle East and Africa Industrial Centrifuge Market | 2026-2036
Middle East and Africa Industrial Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Industrial Centrifuge Market Foresight
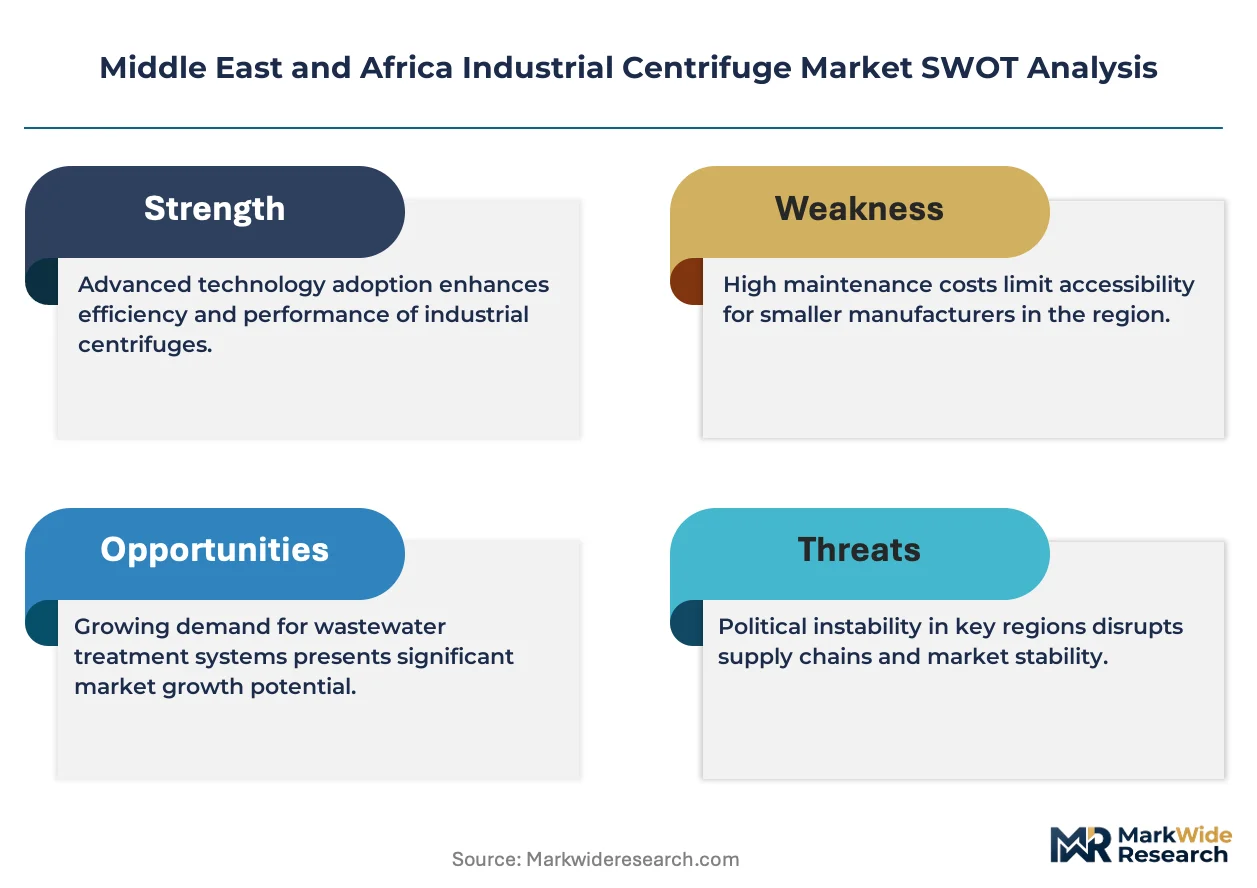
Stainless steel alloys with higher molybdenum content are expanding their share in centrifuge bowl construction as operators seek longer service intervals in corrosive process environments. Alfa Laval AB leverages its Gulf service network to anchor aftermarket revenue streams across Saudi Arabia and the UAE. Andritz AG competes through specialized decanter configurations tailored for oil sludge recovery in Nigerian upstream operations. GEA Group Aktiengesellschaft dominates food-grade centrifuge supply to North African dairy processing cooperatives.
An industrial centrifuge is a rotating mechanical device that generates centrifugal forces typically between 1,000 and 20,000 times gravitational acceleration to separate immiscible liquids or solids from liquids based on density differentials. Bowl diameter, differential speed, and pond depth constitute critical design parameters that determine separation efficiency and throughput capacity for continuous industrial processing. Decanter centrifuges command the largest product type share due to their dominance in oilfield services and wastewater treatment, while sedimentation types represent the fastest-growing category as mining tailings management intensifies across Southern Africa. Continuous technology configurations attract capital investment from large-scale chemical producers seeking uninterrupted throughput, whereas batch systems retain relevance in pharmaceutical applications where campaign-based production and cleaning validation requirements predominate.
Saudi Arabia's SFDA enforces Good Manufacturing Practice standards that mandate validated cleaning protocols for pharmaceutical centrifuge installations, while South Africa's Department of Water and Sanitation applies progressively stricter effluent discharge limits under the National Water Act. The UAE's MOHAP aligns medical device regulations with Gulf Cooperation Council harmonization initiatives, creating cross-border certification efficiencies for equipment suppliers. Stakeholders must monitor how Egypt's industrial wastewater regulatory expansion and Nigeria's proposed petroleum industry environmental standards reshape procurement specifications and aftermarket service obligations across the region.
Market Dynamics
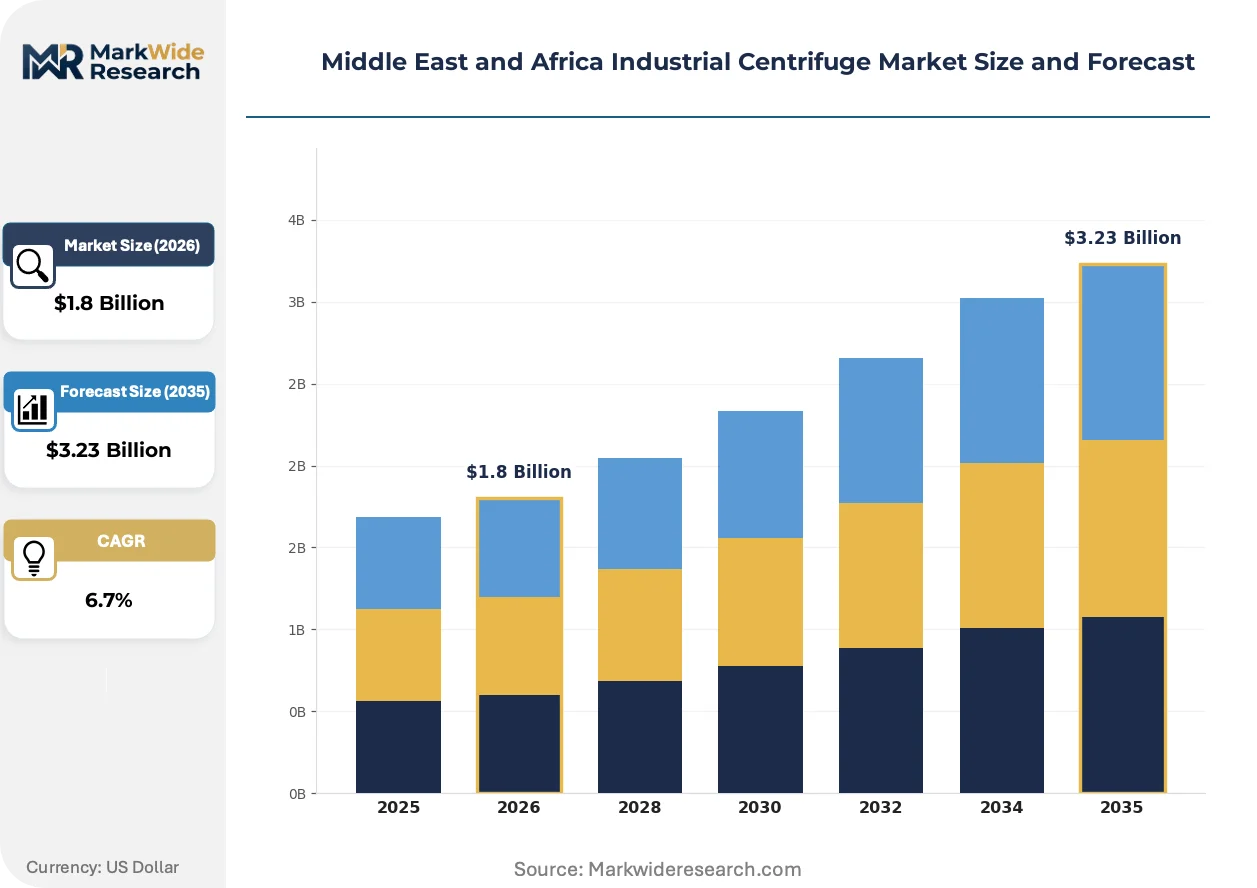
Gulf petrochemical operators are consolidating centrifuge procurement around continuous-duty decanter systems as Saudi Arabia's Eastern Province expands refining capacity and South African mining houses face tailings management mandates. This equipment shift compresses replacement cycles and intensifies aftermarket service competition.
Growth Catalysts
- Produced water treatment mandates:Gulf Cooperation Council oilfield operators face stricter discharge protocols, forcing upgrades to high-capacity decanter centrifuges for solids separation.
- South Africa's National Water Act:Progressive effluent tightening under the Department of Water and Sanitation drives mining and chemical facilities toward advanced solid-liquid separation.
- Desalination scale-up:Saudi Arabia's Eastern Province petrochemical complexes require continuous-duty systems for process optimization and brine concentration.
Market Restraints
- Alloy cost volatility:Molybdenum price swings in stainless steel bowl construction compress margins for fabricators serving corrosive process environments.
- Service network concentration:Gulf aftermarket infrastructure clusters in Dubai and Dammam, creating geographic coverage gaps for Nigerian upstream operators.
- Batch system persistence:Pharmaceutical cleaning validation requirements under Saudi SFDA GMP standards slow continuous technology penetration in drug manufacturing.
Strategic Opportunities
- Egyptian regulatory expansion:Industrial wastewater rule development around the Nile Delta creates first-mover positioning for decanter suppliers in untreated chemical processing.
- Food-grade dairy centrifuges:North African cooperative processing modernization opens specification windows for hygienic disc-stack configurations.
- Nigerian environmental standards:Proposed petroleum industry discharge rules would mandate oil sludge recovery systems across onshore production.
Industry Challenges
- Specialized technician scarcity:Differential speed control and pond depth calibration expertise remains concentrated in European and Gulf service hubs, complicating Nigerian and South African field support.
- Legacy system integration:Mining tailings retrofits in Southern Africa require mechanical compatibility with existing thickener circuits, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Industrial Centrifuge Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decanter, Filter, Basket, Sedimentation End User: Chemicals, Food & Beverage, Pharmaceuticals, Waste Management Application: Liquid-Liquid Separation, Solid-Liquid Separation, Emulsions, Sludge Treatment Technology: Automatic, Semi-Automatic, Batch, Continuous |
| Companies Covered | Alfa Laval AB, Andritz AG, GEA Group Aktiengesellschaft, FLSmidth & Co. A/S, Sulzer AG, Flowserve Corporation, Xylem Inc., KSB SE & Co. KGaA, Grundfos Holding A/S, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Industrial Centrifuge Market Shifts & Advancements
Equipment architecture is converging around predictive maintenance integration and modular bowl designs that reduce field service dependency. These shifts compress total cost of ownership calculations and redistribute value capture toward software-enabled service providers.
Advanced corrosion-resistant alloys with elevated molybdenum content are unifying bowl construction specifications across oilfield and chemical processing applications. Gulf petrochemical operators now specify these materials as standard rather than premium options. This metallurgical convergence is unifying supplier qualification requirements and compressing price differentiation between regional and international fabricators.
South Africa's National Environmental Management Act amendments are tightening particulate discharge thresholds for industrial effluent. Mining houses must retrofit tailings circuits with sedimentation centrifuges or face operational suspension. The platinum belt around Rustenburg and the gold regions of Gauteng show the steepest compliance-driven equipment procurement acceleration.
Service contract unbundling is fragmenting traditional bundled maintenance agreements. Nigerian upstream operators now procure spare parts through independent distributors while retaining OEM specialists for critical overhauls. This channel bifurcation is most visible in the Niger Delta, where logistics constraints favor localized inventory holding over centralized Gulf warehousing.
Middle East and Africa Industrial Centrifuge Market Segmentation
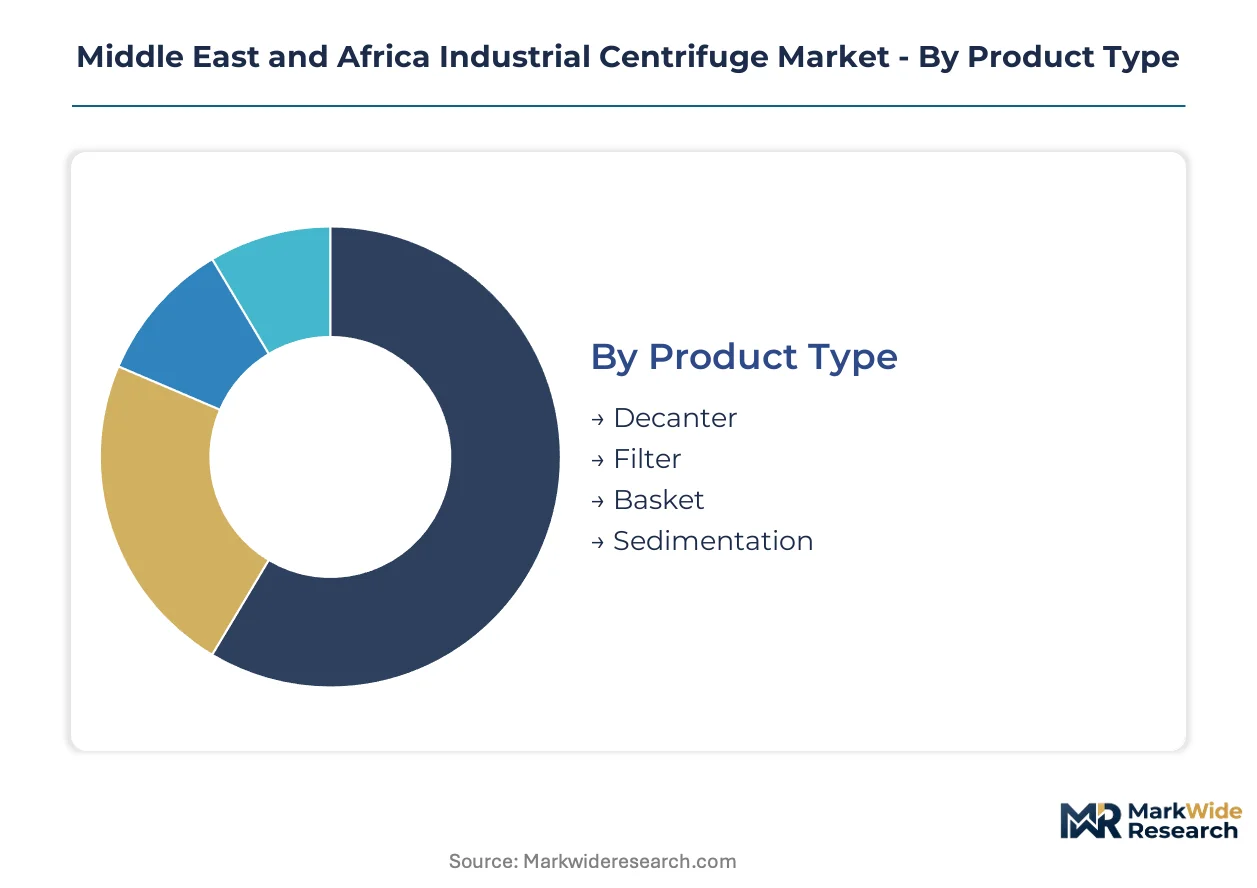
Centrifuge procurement specifications across the Middle East and Africa diverge sharply by regulatory environment and process duty. Saudi SFDA validation requirements, South African discharge mandates, and Gulf petrochemical scale each reshape which segments capture capital allocation.
Product Type:
Certification burdens cluster around food-grade and pharmaceutical applications where Saudi SFDA and UAE MOHAP enforce hygienic design standards. Decanter and sedimentation types face divergent approval pathways for oilfield versus mining deployments.
- Decanter:Continuous horizontal scroll discharge systems dominate high-solids processing in Saudi Arabia's Eastern Province petrochemical complexes and Nigerian upstream oil sludge recovery. Bowl diameter specifications above 500mm attract Gulf investment as operators seek single-unit throughput maximization for produced water treatment mandates.
- Sedimentation:Vertical bowl configurations with intermittent solids discharge are displacing legacy thickeners across South Africa's platinum belt around Rustenburg. Mining houses retrofit these systems to comply with National Water Act particulate thresholds without circuit reconfiguration.
- Filter:Screen bowl and pusher variants handle crystalline solids in Egyptian chemical processing around the Nile Delta.
- Basket:Vertical perforated-bowl units retain relevance in batch pharmaceutical operations under Saudi GMP cleaning validation protocols.
Leading the category by volume: Decanter. Growing fastest: Sedimentation.
End User:
Customer procurement sophistication varies by sector maturity. Chemical and waste management operators prioritize continuous-duty specifications, while pharmaceutical buyers absorb premium pricing for validated cleaning protocols.
- Chemicals:Saudi Arabia's Eastern Province refineries and Egyptian fertilizer producers specify corrosion-resistant alloys for acid slurry separation. Molybdenum-enhanced stainless bowls command specification lock-in as facilities extend service intervals in chloride-rich process streams.
- Waste Management:South African mining tailings retrofits and Gulf produced water treatment facilities drive sedimentation centrifuge demand. The Department of Water and Sanitation's progressive effluent tightening forces capital deployment ahead of compliance deadlines.
- Food & Beverage:North African dairy cooperatives modernize with hygienic disc-stack configurations for milk fat separation.
- Pharmaceuticals:Saudi SFDA GMP standards mandate validated cleaning protocols that slow continuous technology penetration in Riyadh and Jeddah manufacturing clusters.
Expanding most quickly: Waste Management. Dominating current procurement value: Chemicals.
Application:
Process physics determines equipment architecture selection. Density differential magnitude and solids concentration dictate whether liquid-liquid or solid-liquid separation technologies capture project specifications.
- Solid-Liquid Separation:High-solids decanter configurations handle drilling mud recovery in Nigerian onshore operations and tailings dewatering across Southern Africa. Mining houses in Gauteng gold regions specify these systems to meet National Environmental Management Act discharge thresholds.
- Sludge Treatment:Oil sludge recovery systems face imminent mandate expansion under Nigeria's proposed petroleum industry environmental standards. Differential speed control and pond depth calibration requirements concentrate specification expertise in Gulf service hubs.
- Liquid-Liquid Separation:Disc-stack centrifuges separate immiscible process fluids in UAE petrochemical downstream units.
- Emulsions:High-g-force tubular bowl units break stable oil-water emulsions in desalination brine concentration applications.
Commanding largest share: Solid-Liquid Separation. Steepest expansion trajectory: Sludge Treatment.
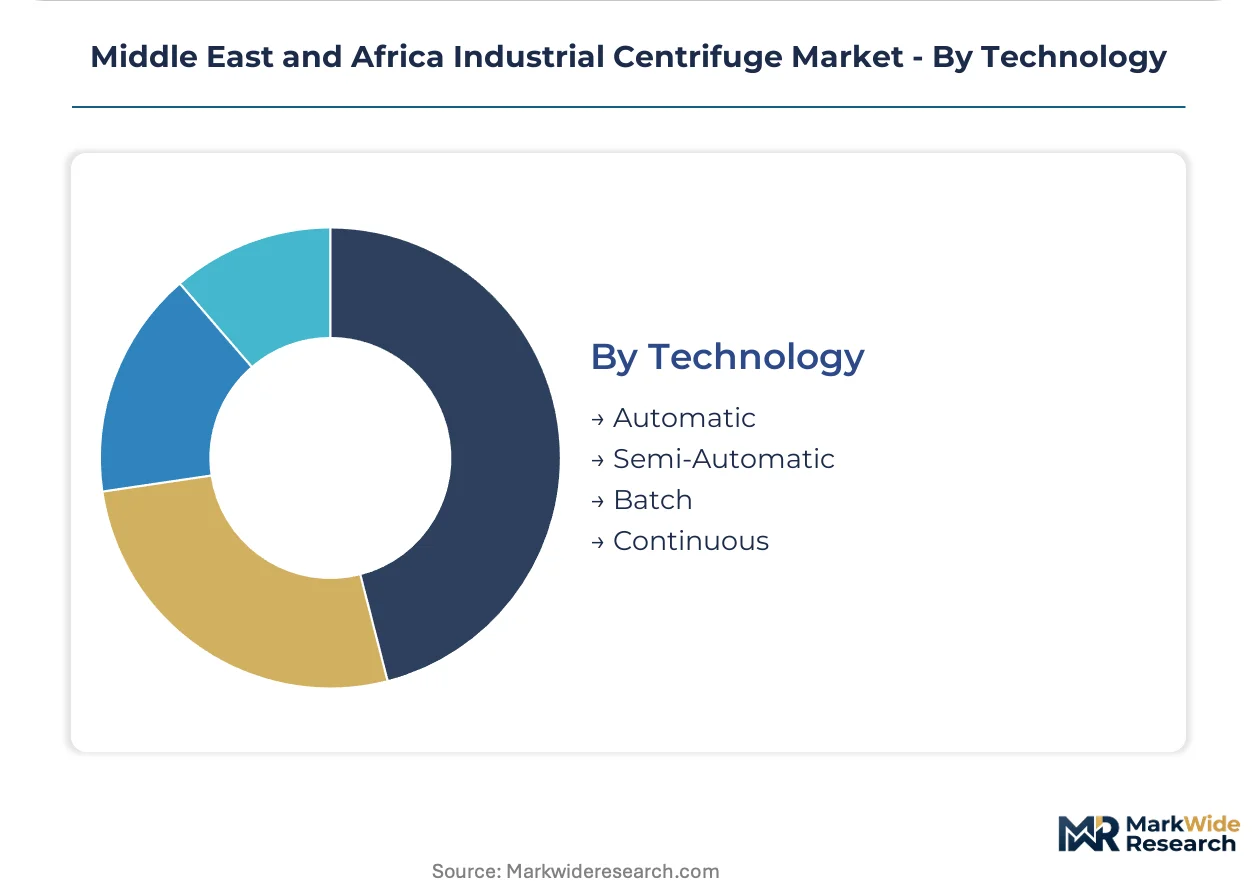
Technology:
Capital intensity and labor availability shape automation level selection. Continuous configurations attract chemical sector investment while batch systems retain pharmaceutical relevance.
- Continuous:Uninterrupted throughput systems dominate Saudi petrochemical and desalination scale-up where process optimization demands 24-hour duty cycles. Eastern Province procurement specifications now exclude batch alternatives for greenfield refining capacity.
- Batch:Campaign-based production and cleaning validation requirements predominate in pharmaceutical applications under Saudi SFDA oversight. Riyadh formulation facilities retain these systems despite higher unit operating costs.
- Automatic:Self-regulating differential speed control reduces field technician dependency in Nigerian upstream operations.
- Semi-Automatic:Manual pond depth adjustment retains cost advantage in South African mining retrofits with existing thickener circuit integration.
Capturing majority investment: Continuous. Climbing the fastest: Automatic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in Saudi Arabia's Eastern Province, where petrochemical scale and desalination expansion drive continuous-duty centrifuge specifications. South Africa's mining belt and Nigeria's upstream oil regions follow as secondary demand nodes shaped by environmental compliance timelines.
Saudi Arabia
Eastern Province refineries and desalination plants anchor regional demand for high-capacity decanter systems. The Saudi Food and Drug Authority enforces Good Manufacturing Practice standards that mandate validated cleaning protocols for pharmaceutical installations. Jubail Industrial City and Yanbu petrochemical complexes specify corrosion-resistant alloys for 24-hour process duty cycles.
United Arab Emirates
Dubai and Abu Dhabi downstream petrochemical units require disc-stack centrifuges for liquid-liquid separation in process optimization. The Ministry of Health and Prevention aligns medical device regulations with Gulf Cooperation Council harmonization initiatives. Jebel Ali industrial zones attract centrifuge service providers consolidating aftermarket infrastructure for regional coverage.
South Africa
The platinum belt around Rustenburg and gold regions of Gauteng drive sedimentation centrifuge retrofits for tailings dewatering. The Department of Water and Sanitation applies progressively stricter effluent discharge limits under the National Water Act. Mining houses face operational suspension risks without compliance-driven capital deployment ahead of regulatory deadlines.
Nigeria
Onshore oil operators in the Niger Delta confront imminent mandate expansion under proposed petroleum industry environmental standards. The country's national environmental regulator develops discharge rules that would mandate oil sludge recovery systems. Lagos and Port Harcourt logistics constraints favor localized spare parts inventory holding over centralized Gulf warehousing.
Egypt
Nile Delta chemical processors face expanding industrial wastewater regulations driving first-mover equipment procurement. The country's environmental authority develops discharge standards around untreated chemical processing zones. Alexandria and Suez Canal industrial corridors attract decanter suppliers targeting specification windows in fertilizer and basic chemicals production.
Middle East and Africa Industrial Centrifuge Market Competitive Landscape
Strategic partnerships dominate the current landscape as fabricators anchor aftermarket revenue through localized service networks. The vendor base clusters around three tiers: European multinationals with Gulf service infrastructure, regional distributors holding inventory for Nigerian logistics constraints, and specialized mining equipment suppliers penetrating South African retrofits. Two archetypes capture positioning: corrosion-resistant alloy specialists serving Saudi petrochemical duty cycles, and sedimentation system providers targeting South African compliance deadlines. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers bridge coverage gaps in Nigerian upstream operations.
Among European-based industrial equipment groups, Alfa Laval AB, Andritz AG, and GEA Group Aktiengesellschaft occupy anchor positions exemplifying the service-network archetype. Alfa Laval leverages its Gulf infrastructure to capture aftermarket revenue streams across Saudi Arabia and the UAE. Andritz represents the specialized configuration approach through decanter systems tailored for oilfield applications. GEA Group sits within the food-grade and hygienic design tier, supplying North African dairy processing cooperatives. These three companies illustrate how European fabricators consolidate regional presence through differentiated technical positioning rather than undifferentiated volume competition.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Andritz AG |
| GEA Group Aktiengesellschaft |
| FLSmidth & Co. A/S |
| Sulzer AG |
| Flowserve Corporation |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Grundfos Holding A/S |
| Others |
Supply & Pricing Matrix
Specialized centrifuge technician pools concentrated in European and Gulf service hubs widen labor-cost differentials between premium OEM-serviced units and economy-tier alternatives. These geographic skill asymmetries compress pricing spreads for standard decanter configurations while sustaining premium tiers for validated pharmaceutical and corrosive-duty installations.
Pricing Analysis
Volume capture concentrates in continuous-duty decanter systems for Saudi petrochemical operators, while margin extraction clusters around pharmaceutical basket centrifuges under Saudi SFDA GMP validation requirements. Three-tier pricing structure across premium corrosion-resistant alloys, standard stainless configurations, and economy refurbished units separates specification tiers. Cost compression in standard decanter segments intensifies as Gulf fabricators expand bowl diameter offerings above 500mm. Mining houses in South Africa's platinum belt exhibit highest price sensitivity due to retrofit budget constraints, whereas Eastern Province desalination plants absorb premium pricing for 24-hour duty cycle guarantees.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Aramco and Nigerian upstream operators mandate multi-supplier qualification for critical bowl components and differential speed control systems. Manufacturing concentration rests on Germany, Sweden, and Austria for precision-machined scroll conveyors and high-alloy bowl castings. Raw material dependencies center on molybdenum-enhanced stainless steel feedstock, nickel-based superalloys for corrosive environments, and specialized bearing assemblies. Single-source vulnerability concentrates in European fabrication of pond depth calibration instrumentation. Distribution runs through Jebel Ali warehousing clusters for Gulf coverage and localized Port Harcourt inventory nodes addressing Nigerian logistics constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward control over corrosion-resistant alloy supply and captive aftermarket service networks determines pricing power. Players pursuing in-house production of molybdenum-enhanced bowl castings secure specification lock-in for Eastern Province petrochemical duty cycles.
For Market Incumbents: Lock in aftermarket revenue streams by anchoring Gulf service infrastructure in Dammam and Dubai while extending predictive maintenance software integration. Defend against independent spare parts distributors in Nigeria by localizing critical inventory holding in Port Harcourt. Certification investment in Saudi SFDA GMP protocols preserves pharmaceutical segment margins against continuous-technology challengers. For New Entrants and Emerging Players: The 40-60% price-point gap between premium OEM decanters and economy refurbished units opens specification windows for mid-tier sedimentation systems in South African mining retrofits. Target Rustenburg platinum belt tailings compliance deadlines as the most penetrable geography. Pursue joint-venture fabrication partnerships with Egyptian Nile Delta chemical processors to bypass European supply chain chokepoints. For Investors and Strategic Acquirers: Re-rating potential sits with corrosion-resistant alloy specialists given Saudi Arabia's Eastern Province capacity expansion and molybdenum specification standardization. Long-term viability favors fabricators with backward integration into high-performance stainless supply and software-enabled service platforms. The signal to watch is Nigerian petroleum industry environmental standard finalization, which would mandate oil sludge recovery system deployment across onshore production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive molybdenum-enhanced stainless production secures Eastern Province specification lock-in against commodity fabricators. |
| Localized Service Network Expansion | Port Harcourt and Lagos inventory nodes address Nigerian logistics constraints while displacing Gulf-centric aftermarket competitors. |
| Predictive Maintenance Platform Launch | Software-enabled differential speed monitoring reduces field technician dependency in Rustenburg mining retrofits. |
| Pharmaceutical Validation Certification | Saudi SFDA GMP compliance investment defends batch system margins against continuous-technology penetration in Riyadh. |
| Nile Delta Joint Venture Formation | Egyptian chemical processor partnerships establish first-mover positioning ahead of industrial wastewater regulatory expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors at Saudi petrochemical complexes, aftermarket service heads in Dubai, plant engineers across South Africa's platinum belt, and OEM procurement teams in Germany combined with secondary validation. Secondary sources encompassed Department of Water and Sanitation discharge records, Saudi SFDA GMP filing databases, Gulf Cooperation Council harmonization directives, and customs import manifests for centrifuge components. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections from regional refining and mining operators.
Granularity-level modeling distinguished continuous versus batch technology configurations, decanter versus sedimentation product architectures, and solid-liquid versus liquid-liquid application categories across the projection horizon. Segmentation dimensions encompassed end-use industry, corrosion-resistance specification tier, automation level, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity announcements. Industry-specific forecast inputs incorporated Saudi Aramco desalination expansion timelines and South African National Water Act compliance enforcement patterns.
Inputs from Saudi SFDA validation registries and South African mining procurement databases were available through the study window; gaps in Nigerian upstream operator capital expenditure disclosure introduce uncertainty bands around sludge treatment demand projections. Deviation in Nigerian petroleum industry environmental standard promulgation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Global Liquid Handling Systems Market