
 Global Electron Microscopy and Sample Preparation Market | 2026-2036
Global Electron Microscopy and Sample Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electron Microscopy and Sample Preparation Market Foresight
Aftermarket service revenue for electron microscopy platforms is fragmenting across independent service organizations and captive OEM teams. Thermo Fisher Scientific leverages its installed base of cryo-EM systems to sustain recurring revenue streams in structural biology. Danaher Corporation anchors its position through Leica Microsystems' specimen preparation workflows that integrate with imaging platforms. JEOL competes on field service density in Asia-Pacific manufacturing corridors.
Electron microscopy and sample preparation encompasses charged-particle beam systems operating at vacuum pressures below 10⁻⁵ Pa, utilizing thermionic or field-emission electron sources to achieve sub-ångström spatial resolution for material characterization. The primary commercial purpose spans failure analysis in semiconductor fabrication, protein structure determination in drug discovery, and quality control in advanced materials production. Scanning electron microscope systems occupy the largest revenue pool due to cross-industry versatility in surface imaging, while cryo-electron microscope installations represent the fastest-expanding segment as pharmaceutical companies adopt single-particle analysis for biologic development. Sample preparation equipment commands durable margins because workflow automation reduces operator-induced artifacts that compromise imaging fidelity.
The FDA's nanotechnology guidance and EPA's characterization requirements for engineered materials shape product development priorities for instrument manufacturers seeking North American market access. EMA's evolving standards for biosimilar comparability studies drive European pharmaceutical investment in cryo-EM infrastructure. ISO 17025 accreditation requirements for testing laboratories influence procurement specifications across academic and industrial end users. Stakeholders must monitor how regulatory convergence on nanomaterial safety assessment creates cross-border instrument standardization opportunities.
Market Dynamics
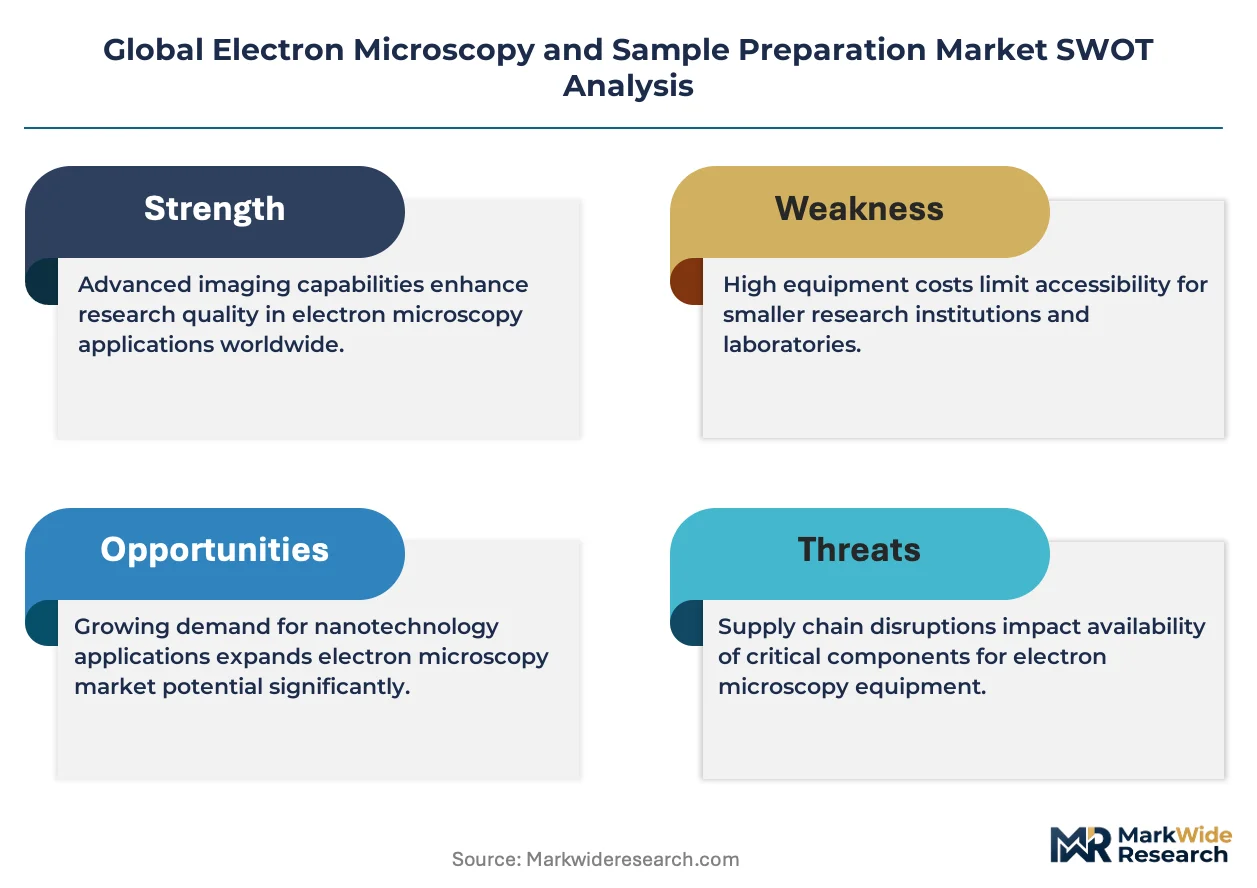
EUV lithography scaling below 3nm process nodes is forcing semiconductor foundries to multiply metrology sampling rates, compressing electron microscopy platform utilization cycles and expanding aftermarket service contracts.
Growth Catalysts
- FDA nanomaterial characterization guidance:Drug sponsors now submit cryo-EM structural data for complex biologics, mandating instrument procurement across pharmaceutical R&D centers.
- Taiwan and South Korea fabrication clusters:Leading-edge foundries in Hsinchu and Pyeongtaek are tripling failure analysis throughput requirements as transistor density increases.
- Single-particle cryo-EM workflows:Protein structure determination at near-atomic resolution is replacing X-ray crystallography for membrane protein targets in drug discovery pipelines.
Market Restraints
- Helium supply volatility:Field-emission gun maintenance and cryo-sample transfer depend on liquid helium, with pricing swings tied to Qatar and US extraction capacity.
- Field service engineer scarcity:Vacuum system specialists and electron optics technicians concentrate at OEM headquarters in Japan, Germany, and the US, creating geographic coverage gaps.
- Substitution by correlative light-electron microscopy:Lower-cost super-resolution fluorescence techniques capture some cellular imaging applications previously requiring transmission electron microscopy.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q5A guidelines for viral safety testing creates demand for cryo-EM infrastructure in biosimilar development hubs near Hyderabad and Bengaluru.
- AI-driven image reconstruction:Deep learning algorithms trained on cryo-EM particle stacks are compressing structure determination timelines from weeks to days.
- Leasing and subscription models:Academic consortia in Brazil and Mexico are adopting shared-access platforms rather than capital purchase, opening service revenue streams for regional distributors.
Industry Challenges
- Cryo-EM operator certification timelines:ISO 17025 accreditation for single-particle analysis requires 18-24 months of proficiency validation, constraining laboratory expansion.
- Legacy SEM-EDS integration:Manufacturing quality control labs face workflow disruption when connecting 1990s-era electron microscopes to modern laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electron Microscopy and Sample Preparation Market |
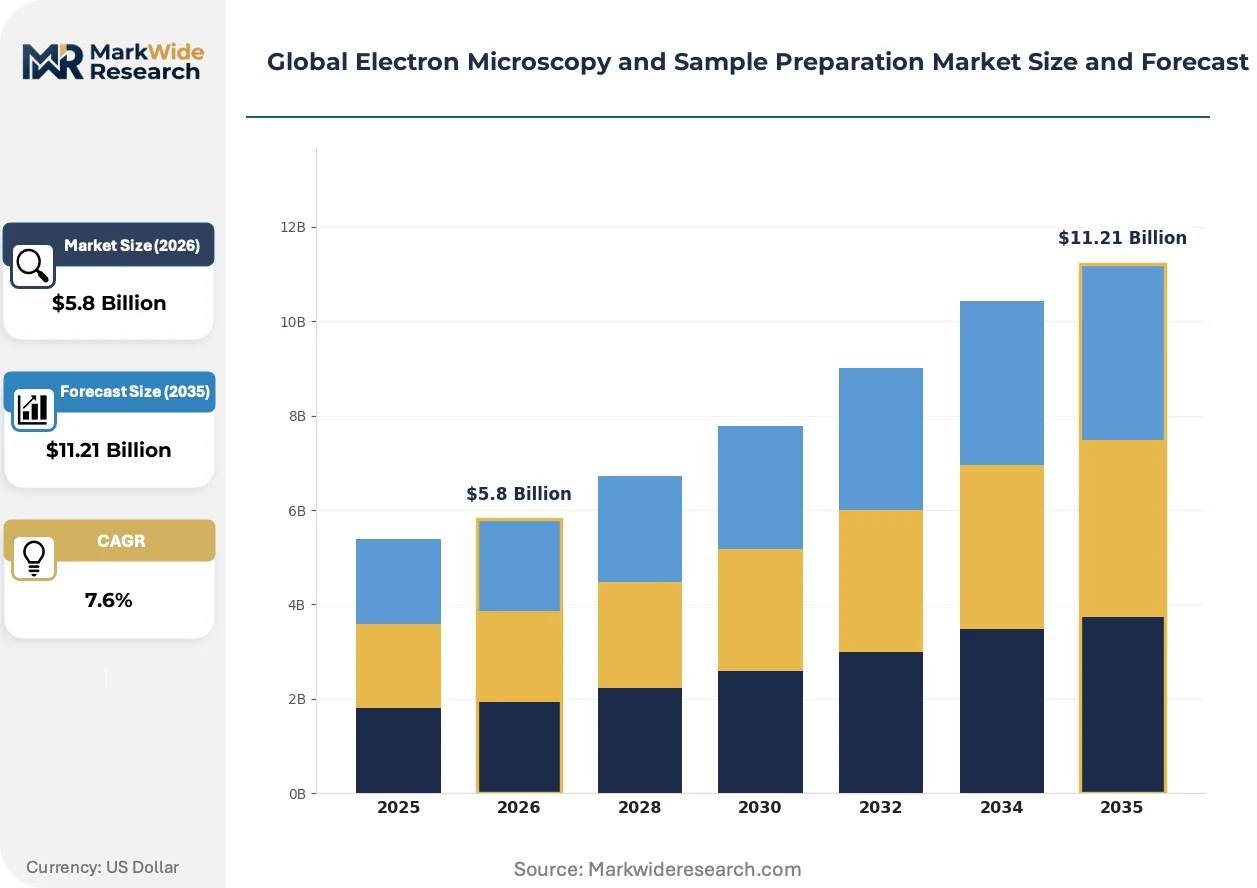
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Electron Microscope, Scanning Electron Microscope, Sample Preparation Equipment, Focused Ion Beam, Cryo-Electron Microscope Technology: Energy Dispersive Spectroscopy, Electron Backscatter Diffraction, Cathodoluminescence, Electron Tomography, X-ray Microanalysis Application: Materials Science, Semiconductor Inspection, Nanotechnology Research, Forensic Analysis, Biotechnology End User: Academic Institutes, Research Laboratories, Electronics Manufacturers, Pharmaceutical Companies, Quality Control Units |
| Companies Covered | Leica Microsystems, Danaher Corporation, Thermo Fisher Scientific, Gatan, Bruker Corporation, JEOL, Hitachi High-Technologies Corporation, Oxford Instruments, Carl Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electron Microscopy and Sample Preparation Market Shifts & Advancements
Computational microscopy and automated specimen handling are compressing the expertise barrier for sub-ångström imaging, while regulatory convergence on nanomaterial safety is standardizing data formats across jurisdictions.
Direct electron detectors with CMOS architecture are digitizing structural biology workflows by capturing single-electron events at 300 frames per second. Pharmaceutical CROs in Cambridge, Massachusetts and Cambridge, UK are retrofitting 200kV platforms with these sensors to accelerate biologic candidate screening. The technology is digitizing service contract structures, shifting vendor revenue from hardware replacement to detector upgrade subscriptions and cloud-based image processing.
REACH Annex amendments for nanomaterial registration are compelling European industrial chemical producers to submit electron microscopy-derived size distribution data for engineered particles. ECHA's 2023 guidance on tiered testing strategies prioritizes imaging over chromatographic methods for aggregate characterization. German and Dutch testing laboratories are responding by automating sample preparation to handle submission volume spikes.
Consolidated procurement through multi-site service agreements is displacing single-instrument purchases at US National Laboratory networks. Oak Ridge and Argonne are negotiating enterprise-wide cryo-EM access contracts with shared maintenance pools and centralized operator training. This pattern is most visible in federally funded materials science research, where budget sequestration pressures favor operational expenditure models over capital outlays.
Global Electron Microscopy and Sample Preparation Market Segmentation
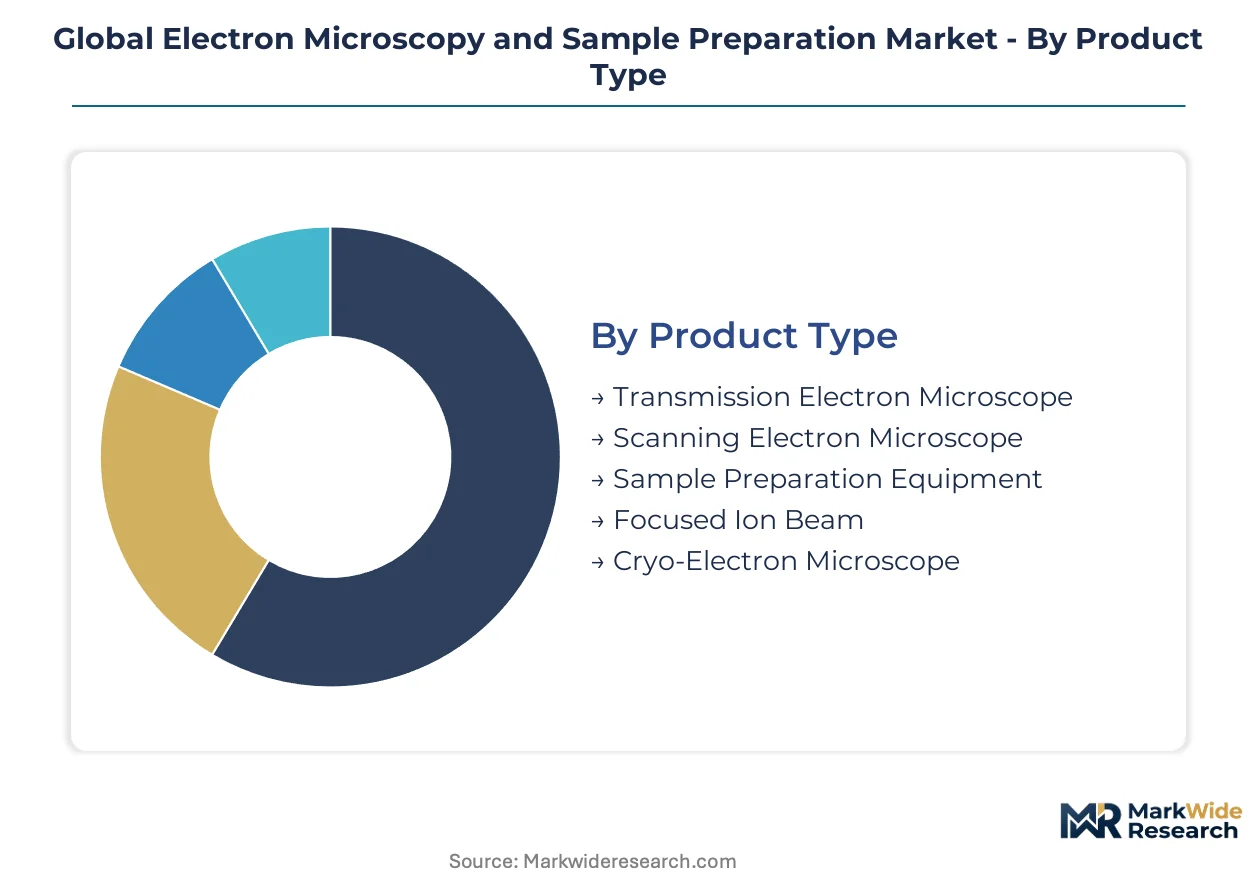
Electron microscopy procurement cycles vary dramatically across product categories, with semiconductor metrology platforms turning over every 4-6 years while academic cryo-EM installations persist for 12-15 years. Understanding these replacement rhythms helps vendors calibrate service contract pricing and predict upgrade revenue windows.
Product Type:
Scanning electron microscopes refresh fastest in manufacturing environments where throughput demands accelerate obsolescence, while cryo-EM platforms show the longest depreciation schedules in institutional settings.
- Scanning Electron Microscope:Surface imaging systems utilizing thermionic or field-emission sources achieve 1-3 nm resolution for cross-industry quality control. Electronics manufacturers in Taiwan and South Korea drive replacement cycles below five years as EUV node transitions demand higher magnification stability.
- Cryo-Electron Microscope:Single-particle analysis platforms operating at liquid nitrogen temperatures enable near-atomic protein structure determination. Pharmaceutical companies in Cambridge, Massachusetts and Cambridge, UK are expanding installed capacity as FDA guidance mandates structural data for complex biologic submissions.
- Transmission Electron Microscope:High-voltage beam systems penetrate thin specimens for crystallographic analysis at sub-ångström resolution.
- Sample Preparation Equipment:Automated ion milling and ultramicrotomy systems reduce operator-induced artifacts prior to imaging.
- Focused Ion Beam:Gallium or xenon ion sources enable site-specific milling and deposition for semiconductor failure analysis.
Scanning electron microscopes dominate installed base volumes. Cryo-electron microscopes are where expansion concentrates.
Technology:
Detection technology selection tracks end-use precision requirements, with materials science favoring elemental mapping while semiconductor labs prioritize crystallographic orientation data.
- Energy Dispersive Spectroscopy:Silicon drift detectors capture characteristic X-rays for elemental composition mapping at spatial resolutions below 100 nm. Quality control units in German automotive supply chains deploy EDS-SEM combinations for contaminant identification in failure analysis workflows.
- Electron Backscatter Diffraction:Pattern indexing from diffracted electrons reveals grain orientation and phase distribution in polycrystalline materials. Research laboratories at Oak Ridge National Laboratory leverage EBSD for radiation damage studies in nuclear materials development.
- Electron Tomography:Tilt-series reconstruction generates three-dimensional volumetric data from two-dimensional projections.
- Cathodoluminescence:Photon emission mapping correlates optical properties with structural features in semiconductors and geological samples.
- X-ray Microanalysis:Wavelength-dispersive spectrometry achieves higher energy resolution than EDS for light element quantification.
Energy dispersive spectroscopy commands the broadest installed base. Electron backscatter diffraction is climbing the fastest as advanced materials research expands.
Application:
Application prioritization reflects regional industrial structure, with East Asian economies weighting heavily toward semiconductor inspection while North American and European investment concentrates in biotechnology.
- Semiconductor Inspection:Metrology protocols for EUV lithography nodes below 3nm require electron microscopy for pattern fidelity verification and defect review. Foundries in Hsinchu, Taiwan and Pyeongtaek, South Korea are tripling sampling rates as transistor density increases, compressing platform utilization cycles.
- Biotechnology:Structural biology workflows for membrane protein characterization and viral particle analysis. Academic institutes in Boston and Basel are consolidating cryo-EM access through shared facility models to amortize capital costs across multiple principal investigators.
- Materials Science:Alloy microstructure, ceramic fracture surfaces, and polymer morphology characterization for industrial R&D.
- Nanotechnology Research:Engineered particle size distribution and aggregation state verification for regulatory submission.
- Forensic Analysis:Gunshot residue, trace evidence, and document examination for criminalistics laboratories.
Semiconductor inspection dominates current procurement volumes. Biotechnology is gaining share fastest as pharmaceutical cryo-EM adoption accelerates.
End User:
End-user segmentation reveals divergent procurement authority structures, with corporate capital committees moving faster than institutional review boards but academic consortia achieving superior per-instrument utilization rates.
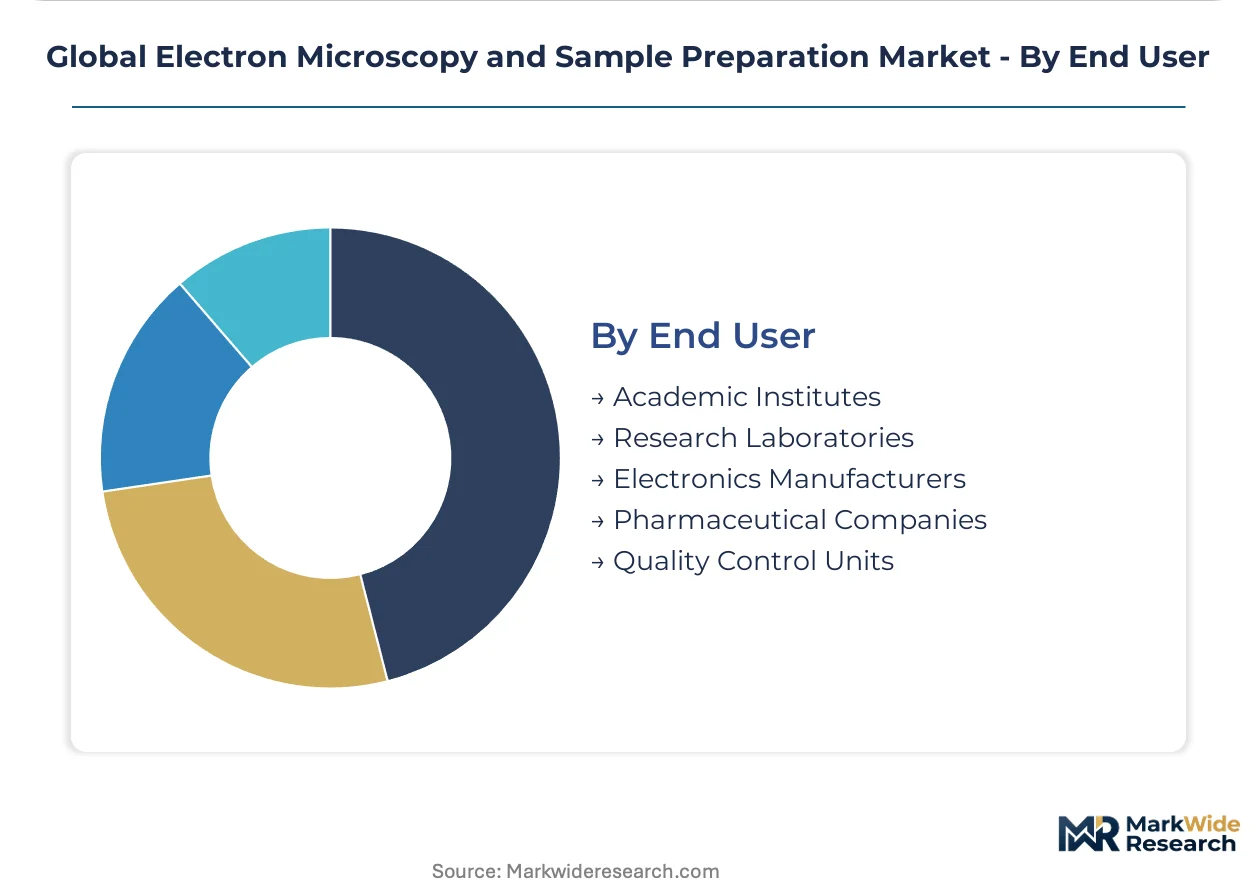
- Electronics Manufacturers:In-house failure analysis labs at integrated device manufacturers and outsourced semiconductor assembly and test providers. Samsung and TSMC operate captive electron microscopy fleets exceeding 200 platforms each for 24/7 production line support.
- Pharmaceutical Companies:Structural biology departments and biologics CMC groups submitting cryo-EM data to FDA and EMA. Roche and Novartis in Basel are building dedicated cryo-EM centers to support biosimilar comparability studies.
- Academic Institutes:University core facilities serving multiple departments through fee-for-service access models.
- Research Laboratories:Government-funded national labs and independent research institutes with mission-directed programs.
- Quality Control Units:Industrial testing laboratories seeking ISO 17025 accreditation for materials characterization services.
Electronics manufacturers maintain the largest installed base. Pharmaceutical companies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Switzerland and Germany accept premium pricing for cryo-EM platforms, while electronics manufacturers in Taiwan and South Korea drive aggressive cost compression on scanning electron microscope procurement.
United States
FDA nanomaterial characterization guidance mandates cryo-EM structural data for complex biologic submissions. The National Institutes of Health expanded shared facility funding through the S10 Shared Instrumentation Grant program. Pharmaceutical clusters in Cambridge, Massachusetts and South San Francisco are consolidating cryo-EM access through multi-investigator service centers.
Germany
REACH Annex amendments compel industrial chemical producers to submit electron microscopy-derived particle size distribution data. ECHA's 2023 tiered testing guidance prioritizes imaging methods for aggregate characterization. Testing laboratories in Cologne and Düsseldorf are automating sample preparation workflows to manage submission volume spikes.
Japan
Semiconductor foundries and materials science institutes sustain dual demand for failure analysis and basic research platforms. METI's innovation corridor programs fund university-industry microscopy consortia. Electron optics specialists concentrate in Tokyo-Osaka corridor facilities serving captive OEM service networks.
South Korea
Samsung and SK Hynix operate captive electron microscopy fleets exceeding 200 platforms each for 24/7 production line support. The Ministry of Trade, Industry and Energy funds metrology infrastructure upgrades through the K-Semiconductor Belt initiative. Pyeongtaek fabrication complexes are tripling failure analysis throughput as EUV nodes shrink below 3nm.
Switzerland
Roche and Novartis are building dedicated cryo-EM centers to support biosimilar comparability studies for EMA submission. Swissmedic alignment with FDA structural biology data requirements accelerates instrument procurement timelines. Basel pharmaceutical R&D infrastructure anchors European biologic characterization capacity.
Global Electron Microscopy and Sample Preparation Market Competitive Landscape
Full-line platform vendors and specimen preparation specialists split the market along workflow integration lines. The installed base concentrates among Japanese, German, and American headquarters clusters where vacuum system expertise and electron optics engineering concentrate. Three archetypes dominate: diversified life science conglomerates with cryo-EM portfolios, precision optics manufacturers with heritage in semiconductor metrology, and captive service organizations leveraging geographic proximity to fabrication corridors. Competitive positioning hinges on field service density in Asia-Pacific manufacturing zones and detector upgrade subscription models that shift revenue from hardware replacement to recurring software and sensor refresh cycles.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform-plus-consumables strategies that embed recurring revenue through installed base expansion. JEOL represents the precision manufacturing archetype with heritage electron optics capabilities concentrated in Japanese industrial corridors. These three anchors illustrate how competitive positioning diverges between pharmaceutical workflow integration and semiconductor field service responsiveness.
| Leading Market Players |
|---|
| Leica Microsystems |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Gatan |
| Bruker Corporation |
| JEOL |
| Hitachi High-Technologies Corporation |
| Oxford Instruments |
| Carl Zeiss |
| Others |
Supply & Pricing Matrix
Trans-Pacific air freight corridors connecting Osaka and San Jose carry liquid helium dewars and field-emission gun assemblies whose per-kilogram rates directly determine service contract pricing tiers for semiconductor foundries in Hsinchu and Pyeongtaek, while cryo-EM pharmaceutical buyers in Basel and Cambridge absorb premium logistics costs through extended warranty bundling that OEMs structure around captive spare parts inventories.
Pricing Analysis
Aftermarket service contracts and detector upgrade subscriptions generate lifetime value that exceeds initial hardware margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 17025 accreditation status and field service response time guarantees. Pricing pressure stems from foundry procurement teams in South Korea demanding compressed maintenance windows as EUV node transitions accelerate. Electronics manufacturers exhibit highest price sensitivity due to volume procurement leverage, while pharmaceutical companies accept premium positioning for cryo-EM platforms tied to regulatory submission timelines.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates risk calculations for electron optics assemblies and vacuum chamber components. Manufacturing concentrates in Japan, Germany, and the United States for precision electron sources and ion optical columns. Raw material dependencies include high-purity copper for electromagnetic lenses, rare-earth permanent magnets for beam deflection systems, and liquid helium for cryogenic sample handling. Single-source vulnerability persists for field-emission tips etched from single-crystal tungsten wire. Distribution runs through captive OEM service networks in Asia-Pacific fabrication corridors and independent distributors serving academic consortia in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron microscopy vendors face a platform-economics inflection as cloud-based image reconstruction and AI-driven particle picking transform proprietary hardware margins into software-subscription revenue streams, with interoperability standards for cryo-EM data formats emerging from the EMDB and wwPDB consortiums.
For Market Incumbents: Pre-empt detector commoditization by locking pharmaceutical customers into multi-year image-processing subscriptions that bundle cloud compute credits with hardware maintenance. Deepen backward integration into direct electron detector fabrication to capture sensor margins currently flowing to Gatan and DECTRIS. Defend against independent service organizations by embedding predictive maintenance algorithms that require proprietary diagnostic access ports.
For New Entrants and Emerging Players: Build out automated sample preparation workflows for European testing laboratories facing REACH Annex submission volume spikes, where incumbents lack dedicated automation portfolios. Target Indian pharmaceutical manufacturing corridors near Hyderabad and Bengaluru where CDSCO alignment with ICH Q5A guidelines creates first-mover cryo-EM infrastructure demand. Pursue leasing and subscription go-to-market models that convert academic consortia in Brazil and Mexico from capital purchase to recurring revenue relationships.
For Investors and Strategic Acquirers: Specialist specimen preparation automation firms with ISO 17025-compliant workflow software represent attractive acquisition targets as regulatory data integrity requirements harden. Long-term viability hinges on vendor ability to shift revenue mix from hardware replacement toward recurring service and software streams. Watch for inflection signals in pharmaceutical CRO consolidation patterns around Cambridge, Massachusetts and Cambridge, UK, where multi-investigator facility models concentrate purchasing authority.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Image Reconstruction Platform | Deep learning algorithms trained on EMDB particle stacks compress structure determination timelines for pharmaceutical R&D centers. |
| Detector Upgrade Subscription Model | CMOS sensor refresh cycles shift vendor revenue from hardware replacement to recurring software and cloud processing contracts. |
| Automated Sample Preparation System | Robotic ultramicrotomy and ion milling reduce operator-induced artifacts that compromise FDA nanomaterial characterization submissions. |
| Multi-Site Service Agreement Consolidation | Oak Ridge and Argonne-style enterprise contracts favor operational expenditure models over capital outlays in federally funded research. |
| Field Service Engineer Certification Program | Regional training hubs address scarcity of vacuum system specialists and electron optics technicians in Asia-Pacific manufacturing corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electron microscopy facility directors, semiconductor metrology engineers, pharmaceutical structural biology group leaders, and aftermarket service contract managers. Secondary validation drew from FDA nanomaterial guidance documents, EMA biosimilar comparability guidelines, ISO 17025 accreditation records, and SEC filings of diversified life science conglomerates. Bottom-up instrument shipment tracking and top-down end-user budget analysis were triangulated to calibrate market sizing.
Calibration against historical replacement cycle data and announced foundry metrology budget expansions anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, detection technology, application vertical, and end-user procurement authority structure. CAGRs were derived from weighted average of equipment refresh rates and service contract expansion trajectories. Forecast inputs incorporated EUV lithography node transition timelines and pharmaceutical cryo-EM adoption curves tied to regulatory submission requirements.
Stress conditions across helium supply volatility, field service engineer availability, and correlative light-electron microscopy substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory convergence on nanomaterial safety assessment and standardization of cryo-EM data formats. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Array Instruments Market