
 PVD Coaters Market | 2026-2036
PVD Coaters Market Size, Share, and Industry Trends Forecast 2026-2036
PVD Coaters Market Analysis
Aftermarket service revenue is narrowing relative to initial equipment sales as PVD coater manufacturers bundle longer-term maintenance contracts into original purchase agreements. Oerlikon Balzers Coating AG leverages its global service network to sustain recurring income streams across Europe and Asia. Applied Materials, Inc. dominates semiconductor-facing sputtering platforms through vertical integration into process control software. IHI Corporation anchors heavy-industrial coating demand in Japan through specialized turbine blade applications.
Physical vapor deposition coaters are vacuum chamber systems that deposit thin films by condensing vaporized target material onto substrates, typically operating at pressures below 10^-3 mbar and temperatures ranging from ambient to 500°C depending on the process. These systems serve primarily to enhance surface hardness, corrosion resistance, optical properties, or electrical conductivity across precision manufacturing sectors. Sputtering coaters lead capital expenditure among product types due to their versatility across metal, ceramic, and compound targets for electronics fabrication. Functional coatings command premium pricing within the application dimension because medical implant and aerospace turbine specifications require validated biocompatibility and thermal barrier performance. Evaporation coaters retain stronghold positions in optical coatings where uniformity requirements for anti-reflective lenses and mirror substrates favor simpler thermal processes.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that constrain solvent use and venting from coating operations, compelling PVD equipment upgrades in U.S. manufacturing facilities. REACH registration requirements in Europe mandate chemical safety documentation for coating precursors, creating compliance barriers for imported target materials and favoring localized supply chains. ISO 13485 quality management standards govern medical device coating validations, extending certification timelines but locking in supplier relationships once approved. Stakeholders must monitor divergence between regional emissions frameworks and medical device standards to anticipate where capital deployment for compliant capacity will yield durable returns.
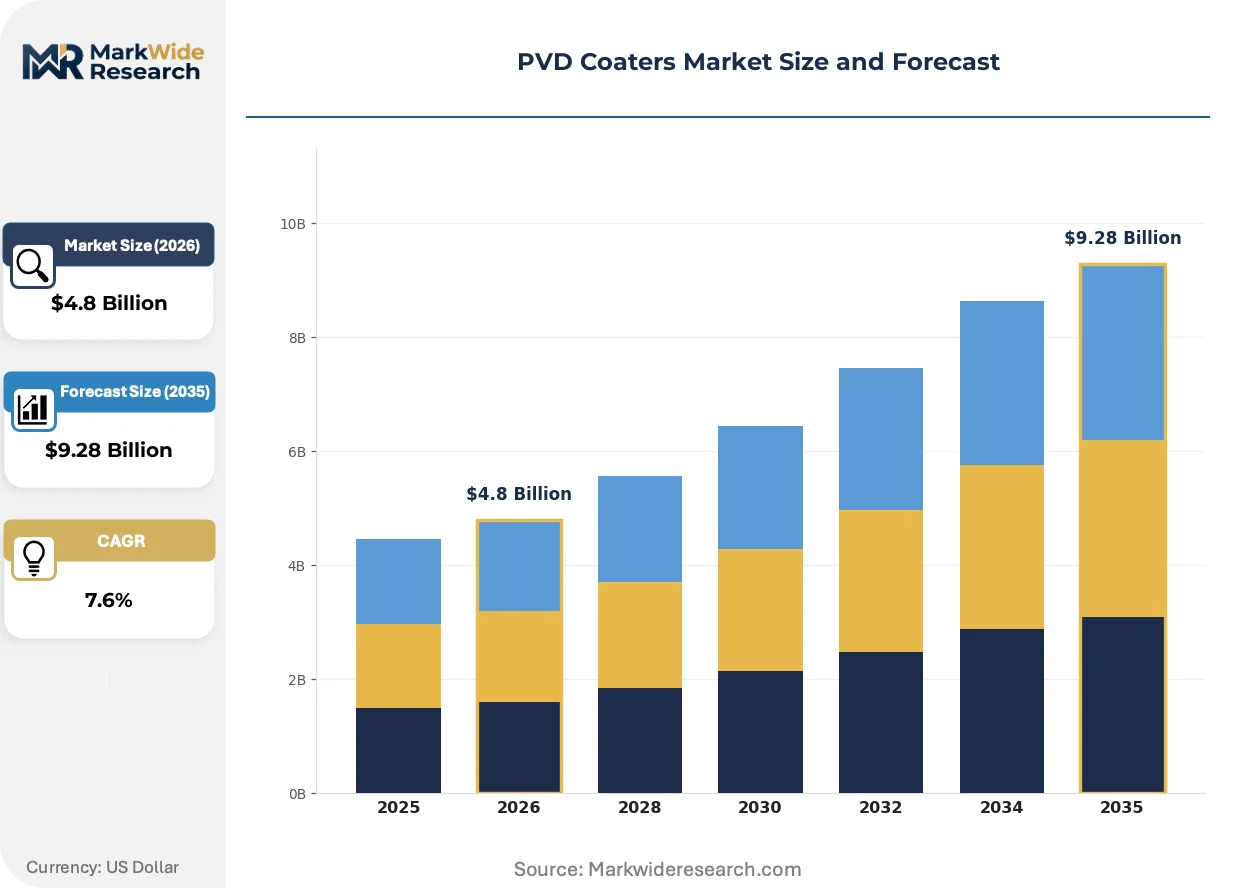
Market Dynamics
Closed-loop sputtering architectures are compressing operating margins for legacy open-venting equipment while concentrating procurement among fabs capable of meeting tightening EPA and REACH emission thresholds.
Growth Catalysts
- Semiconductor node shrinkage:Sub-7nm chip architectures demand atomic-precision barrier films that only advanced sputtering platforms can deposit. Foundries in Taiwan and South Korea are expanding captive PVD capacity to secure supply chain control over critical deposition steps.
- EU Green Deal industrial funding:European coating houses accessing decarbonization grants are retrofitting vacuum systems with regenerative energy recovery modules. This policy tailwind accelerates replacement cycles for aging thermal evaporators across German automotive component suppliers.
- OLED substrate scaling:Chinese display panel manufacturers are commissioning multi-chamber inline coaters for flexible OLED encapsulation. Beijing's dual carbon goals favor PVD over solvent-heavy wet coating processes for reducing volatile organic compound footprints.
Market Restraints
- High-purity target material concentration:Tantalum and titanium sputtering targets for semiconductor applications concentrate among Japanese and Kazakhstani refiners. Geopolitical friction or export licensing delays propagate directly into coater utilization rates.
- Capital intensity barriers:Single-wafer cluster tools for 300mm semiconductor production require eight-figure capital commitments. Mid-tier job shops cannot amortize depreciation against thin-margin decorative coating volumes.
- Technical substitution threat:Atomic layer deposition is penetrating precision barrier applications where PVD previously dominated. ALD's conformal coverage advantage at sub-5nm thicknesses threatens sputtering's position in advanced packaging.
Strategic Opportunities
- Indian medical device localization:CDSCO's phased manufacturing program for orthopedic implants creates demand for biocompatible coating validation services. Domestic contract manufacturers lack in-house PVD expertise, opening service-based entry for equipment-plus-process providers.
- Solid-state battery interface engineering:Lithium-metal anode stabilization requires ceramic-polymer multilayers that hybrid PVD-ALD systems can deposit. Korean and Chinese cell producers are piloting dedicated coating lines for next-generation cell architectures.
- Digital twin integration:Real-time chamber monitoring via IoT sensors is enabling predictive maintenance contracts. Equipment vendors bundling software subscriptions transform episodic hardware sales into recurring revenue streams.
Industry Challenges
- Vacuum technician scarcity:Specialized skills for cryopump maintenance and residual gas analysis command premium wages. Training pipelines at technical institutes have not scaled with equipment deployment rates.
- ISO 13485 certification timelines:Medical implant coating validations require 18-24 month documentation cycles. Supplier lock-in effects disadvantage new entrants even where technical performance matches incumbents.
- Legacy system integration friction:Retrofitting Industry 4.0 connectivity onto 1990s-era batch coaters demands custom middleware development. Facilities with heterogeneous equipment fleets face stranded asset risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVD Coaters Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporation Coaters, Sputtering Coaters, Ion Plating Coaters, Multi-Arc Coaters Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Plasma Spray, Laser Coating End User: Aerospace, Automotive, Electronics, Medical Devices Application: Tool Coatings, Decorative Coatings, Optical Coatings, Functional Coatings |
| Companies Covered | Oerlikon Balzers Coating AG, PLATIT AG, Applied Materials, Inc., IHI Corporation, Buhler AG, ULVAC, Inc., Denton Vacuum, LLC, Von Ardenne GmbH, Veeco Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVD Coaters Market Emerging Trajectories
Process control software is digitizing deposition parameter optimization, compressing recipe development cycles while enabling remote diagnostic capabilities that alter service delivery economics across the installed base.
Magnetron sputtering with rotating cylindrical targets is digitizing thickness uniformity control for large-area architectural glass and display substrates. Glass processors in China and Germany are adopting these systems to reduce target consumption rates by 30-40% while extending maintenance intervals. The technology is digitizing competitive differentiation away from raw throughput metrics toward total cost-per-coated-area optimization.
REACH authorization requirements for chromium VI compounds are forcing decorative coating houses toward trivalent chrome and metallic nitride alternatives. ECHA's sunset date enforcement creates compliance cliffs that compress decision timelines for European automotive trim suppliers. Decorative applications in Italy and Spain are responding with accelerated capital deployment toward physical vapor deposition platforms capable of depositing titanium nitride gold substitutes.
Aftermarket service unbundling is fragmenting traditional equipment-plus-maintenance bundles into subscription-based performance guarantees. Semiconductor fabs in Taiwan and memory producers in South Korea now demand uptime-based contracts with penalty clauses for unplanned downtime. This behavioral shift concentrates service capability among vendors with sufficient geographic density to guarantee four-hour response windows.
PVD Coaters Market Segmentation
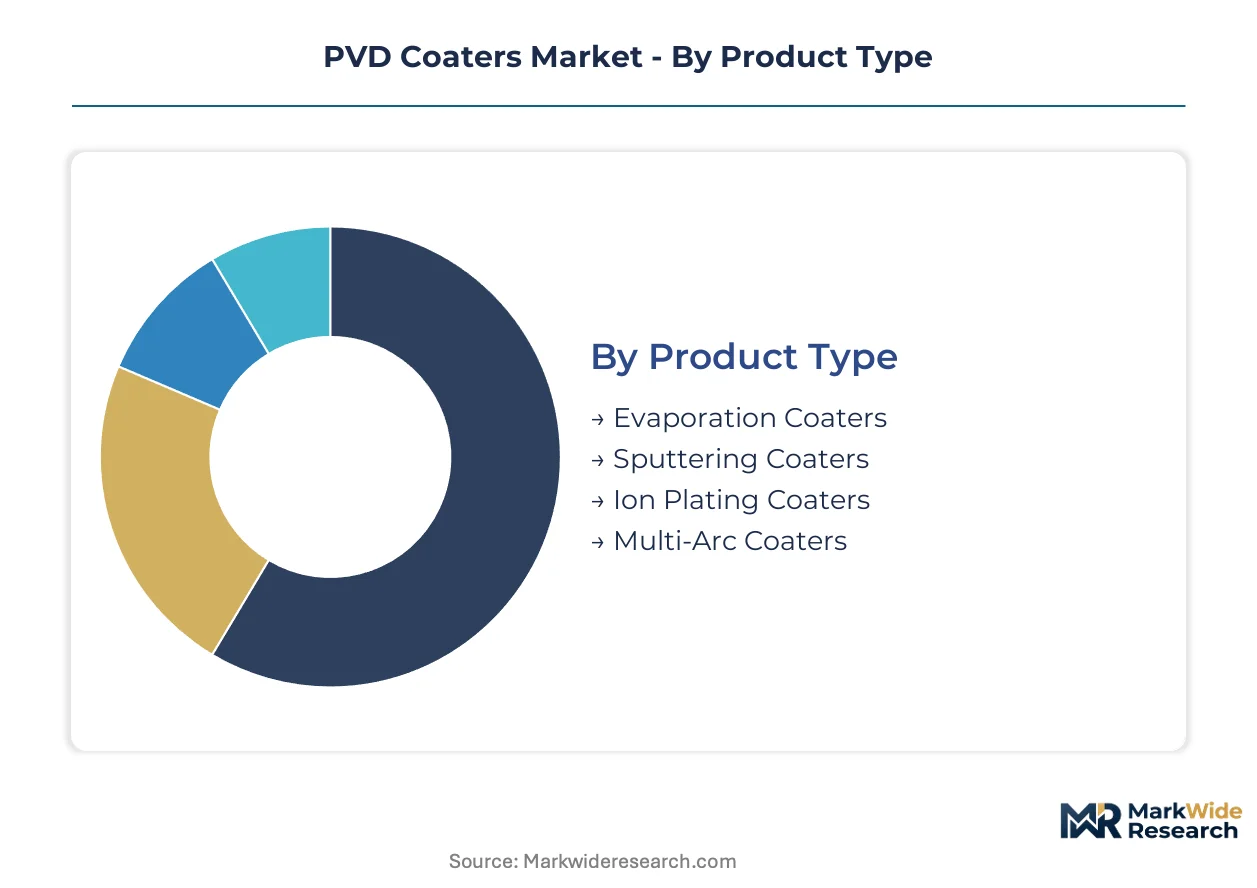
PVD coater procurement patterns diverge sharply across deposition physics, target material compatibility, and end-use certification requirements. Equipment specifications for semiconductor barrier films bear little resemblance to those for orthopedic implant surfaces or architectural glass. Understanding these segment boundaries clarifies where capital deployment yields durable returns versus commodity exposure.
Product Type:
Mature thermal processes coexist with emerging plasma-enhanced architectures across the equipment landscape.
- Sputtering Coaters:Magnetron configurations dominate electronics fabrication through versatile metal, ceramic, and compound target compatibility. Taiwan Semiconductor Manufacturing Company and Samsung Foundry expand captive sputtering capacity for sub-7nm barrier deposition.
- Evaporation Coaters:Resistive and electron-beam thermal sources retain stronghold positions in optical coating applications where thickness uniformity requirements favor simpler process physics. German precision optics houses and Chinese mirror substrate manufacturers specify these systems for anti-reflective and reflective layer stacks.
- Ion Plating Coaters:Plasma-assisted deposition enhances film adhesion for tribological applications.
- Multi-Arc Coaters:Cathodic arc systems deposit dense ceramic coatings for cutting tools and decorative finishes.
Sputtering coaters retain volume leadership; multi-arc coaters hold the steepest expansion curve.
Technology:
Cost tier stratification separates vacuum-based thin-film methods from atmospheric thermal spray alternatives.
- Physical Vapor Deposition:Vacuum chamber systems condense vaporized target material onto substrates below 10^-3 mbar, serving precision manufacturing sectors requiring atomic-scale thickness control. Electronics, medical devices, and aerospace components specify PVD for validated surface enhancement.
- Chemical Vapor Deposition:Reactive gas-phase precursors enable conformal coatings on complex geometries where line-of-sight limitations constrain PVD applicability.
- Plasma Spray:Atmospheric deposition of molten or semi-molten powders suits thick thermal barrier coatings on turbine components.
- Laser Coating:Directed energy deposition repairs worn surfaces through localized melting and material addition.
Physical vapor deposition commands premium pricing tiers; laser coating gains share fastest in maintenance-heavy industrial environments.
End User:
Application-driven margin structures concentrate procurement authority among certification-intensive sectors.
- Electronics:Semiconductor foundries and display panel manufacturers drive capital expenditure through node shrinkage and substrate scaling imperatives. Beijing's dual carbon goals favor PVD over solvent-heavy wet processes for OLED encapsulation.
- Medical Devices:Orthopedic implants and surgical instruments require ISO 13485-validated biocompatible coatings. CDSCO's phased manufacturing program in India creates demand for coating validation services that domestic contract manufacturers cannot fulfill internally.
- Aerospace:Turbine blade thermal barriers and landing gear wear coatings demand aerospace-grade process documentation.
- Automotive:Powertrain components and decorative trim specify PVD for durability and chrome-alternative aesthetics.
Electronics retains procurement volume leadership; medical devices hold the steepest expansion curve.
Application:
Functional performance requirements stratify pricing power across decorative versus mission-critical use cases.
- Functional Coatings:Thermal barriers, electrical conductors, and biocompatible surfaces command premium pricing through validated performance specifications. Medical implant and aerospace turbine applications require extensive certification documentation that locks in supplier relationships.
- Tool Coatings:Cutting inserts and forming dies specify hard ceramic layers for wear resistance.
- Optical Coatings:Anti-reflective lenses and laser mirrors demand nanometer-scale thickness uniformity.
- Decorative Coatings:Architectural hardware and automotive trim substitute titanium nitride gold alternatives for chromium VI compounds facing REACH sunset dates.
Functional coatings retain margin leadership; decorative coatings gain share fastest amid European regulatory displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Semiconductor foundries in Taiwan and South Korea absorb premium pricing for atomic-precision equipment, while Indian job shops and Southeast Asian decorative coaters prioritize capital efficiency over advanced process control.
China
Display panel manufacturers in Beijing and Hefei are commissioning multi-chamber inline coaters for flexible OLED encapsulation. The country's dual carbon goals under MEE guidance favor PVD over solvent-heavy wet processes for reducing volatile organic compound footprints. Yangtze River Delta fabs are scaling capacity for advanced LCD and OLED substrates.
United States
EPA National Emission Standards for Hazardous Air Pollutants are compelling manufacturing facilities to upgrade PVD equipment for solvent-use constraints. Aerospace turbine blade coaters in Connecticut and Ohio demand validated thermal barrier performance documentation. Greater Boston medical device clusters require ISO 13485-compliant biocompatible coating validations.
Germany
Automotive component suppliers in Baden-Württemberg are retrofitting vacuum systems with regenerative energy recovery modules using EU Green Deal industrial funding. ECHA REACH authorization deadlines for chromium VI compounds are forcing decorative coating houses toward trivalent chrome alternatives. Bavarian precision optics houses specify electron-beam evaporation systems for anti-reflective layer stacks.
Japan
Specialized turbine blade applications anchor heavy-industrial coating demand through METI-supported manufacturing programs. Tantalum and titanium sputtering target refining concentrates among domestic suppliers, creating supply chain leverage. Nagoya-area automotive trim manufacturers are accelerating titanium nitride gold substitute deployment ahead of export market regulations.
South Korea
Samsung Foundry and SK Hynix are expanding captive sputtering capacity for sub-7nm barrier deposition as chip architectures shrink. Memory producers now demand uptime-based service contracts with penalty clauses for unplanned downtime. Busan-Ulsan industrial corridors are piloting hybrid PVD-ALD systems for solid-state battery interface engineering.
PVD Coaters Market Vendor Landscape
Integrated process architects and specialized equipment fabricators split the market along capability depth versus geographic breadth. The vendor base concentrates among Swiss-German precision engineering houses, Japanese industrial conglomerates, and American semiconductor equipment platforms. Three archetypes dominate: captive foundry equipment divisions, independent coating service networks, and vacuum technology pure-plays. Consolidation pressure is accelerating through strategic partnerships for digital twin integration and geographic expansion into Indian medical device markets.
Among Swiss-German precision engineering groups, Oerlikon Balzers Coating AG and Buhler AG occupy positions emphasizing global service network density and process validation depth. Applied Materials, Inc. anchors the semiconductor-facing equipment tier through in-house production of process control software. Japanese industrial conglomerates IHI Corporation and ULVAC, Inc. exemplify the heavy-industrial application archetype, with IHI Corporation representing specialized turbine blade coating expertise.
| Leading Market Players |
|---|
| Oerlikon Balzers Coating AG |
| PLATIT AG |
| Applied Materials, Inc. |
| IHI Corporation |
| Buhler AG |
| ULVAC, Inc. |
| Denton Vacuum, LLC |
| Von Ardenne GmbH |
| Veeco Instruments, Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese and Kazakhstani tantalum refiners compresses pricing tier spreads while forcing equipment buyers into long-term offtake commitments. Semiconductor foundries absorb 40-60% lifetime cost premiums for validated target material provenance, whereas decorative coating houses in Southern Europe face margin erosion from spot-market titanium volatility.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture as vendors bundle predictive maintenance subscriptions into original equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-validated medical systems from automotive decorative coaters and job-shop generalists. Cost compression in the economy tier is intensifying because Chinese display panel manufacturers negotiate volume discounts for multi-chamber inline systems. Medical device manufacturers exhibit the lowest price sensitivity due to 18-24 month certification lock-in effects.
Supply Chain Analysis
Extended payment terms from Japanese sputtering target suppliers have become standard for qualified semiconductor fabs, compressing working capital cycles for mid-tier coaters. High-purity tantalum and titanium refining concentrates in Japan and Kazakhstan, with ceramic target fabrication anchored in Germany and the United States. Supply chain risk centers on export licensing delays for dual-use refractory metals. Distribution runs through direct OEM relationships for semiconductor equipment and regional distributor networks for industrial job-shop systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVD Coaters Market is entering a cyclical recovery phase as semiconductor capital expenditure rebounds from node-transition pauses. Foundry expansion for sub-7nm architectures provides the cyclical impetus.
For Market Incumbents: Build certification moats around ISO 13485-validated medical coating workflows to defend against ALD substitution threats in precision barrier applications. Deepen backward integration into high-purity target material refining through offtake partnerships with Kazakhstani and Japanese suppliers. Expand captive service network density in the Yangtze River Delta to guarantee four-hour response windows for uptime-based contracts. For New Entrants and Emerging Players: Indian orthopedic implant contract manufacturers represent the most penetrable entry point, as CDSCO's phased manufacturing program creates demand for equipment-plus-validation service bundles that domestic players cannot fulfill. Solid-state battery pilot lines in Busan-Ulsan corridors offer a second white-space target for hybrid PVD-ALD system deployment. Lead with process engineering partnerships rather than capital equipment sales to bypass incumbent certification timelines. For Investors and Strategic Acquirers: REACH authorization deadlines for chromium VI compounds reshape the acquisition landscape toward European decorative coating houses with titanium nitride gold substitute capabilities. Five-to-ten-year viability favors vendors with installed base scale sufficient to support subscription-based digital twin integration. Watch for EPA enforcement patterns on National Emission Standards for Hazardous Air Pollutants as the signal for U.S. retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time chamber monitoring via IoT sensors enables predictive maintenance subscriptions that transform hardware sales into recurring revenue. |
| Backward Integration into Target Refining | Captive supply of high-purity tantalum and titanium insulates against export licensing delays and secures margin capture. |
| Medical Device Certification Investment | ISO 13485 validation workflows lock in supplier relationships for orthopedic implant coatings with 18-24 month switching costs. |
| Hybrid PVD-ALD System Development | Solid-state battery interface engineering demands ceramic-polymer multilayers that single-physics systems cannot deposit. |
| Service Network Geographic Expansion | Four-hour response window guarantees for uptime-based contracts concentrate procurement among vendors with sufficient density. |
Methodological Framework
Cross-validation between equipment vendor shipment disclosures and foundry capital expenditure filings anchors the qualitative findings in observable demand signals. Primary interviews with vacuum chamber design engineers, semiconductor fab procurement directors, medical device coating validation specialists, and aftermarket service heads were synthesized with secondary sources including EPA enforcement dockets, ECHA REACH authorization registers, and customs trade data for sputtering target imports. Bottom-up equipment unit economics and top-down sectoral capital expenditure patterns were triangulated to constrain variance.
Calibration against historical capacity deployment cycles and foundry node-transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deposition physics, target material compatibility, end-use certification requirements, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle compression. Forecast inputs incorporated OLED substrate scaling trajectories and solid-state battery pilot line commitments.
Stress conditions across tantalum export licensing delays, EPA enforcement intensity, and ALD technology penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding semiconductor node shrinkage continuity and REACH authorization timeline adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Plasma Etch System Market