
 Vision Positioning System Market | 2026-2036
Vision Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Positioning System Market Analytics
East Asian sensor module production is restructuring supply chains for vision positioning hardware. DJI leverages its drone imaging heritage to dominate consumer and commercial aerial navigation segments. Sick AG anchors industrial automation with laser-based localization systems for manufacturing floors. Cognex Corporation specializes in machine vision software that powers robotic guidance across automotive assembly lines.
A vision positioning system computes spatial coordinates through optical sensors, image processing algorithms, and inertial measurement units to enable autonomous navigation without external infrastructure references. These systems typically process visual data at frame rates exceeding 30 Hz to maintain real-time localization accuracy within centimeter-scale tolerances for robotic and vehicular applications. Camera systems capture the largest share of product type revenue due to declining CMOS sensor costs and expanding resolution capabilities. Sensor fusion represents the fastest-growing technology category as manufacturers combine LiDAR, visual odometry, and IMU data to improve reliability in degraded visual environments. Machine vision technology leads deployment volume across automotive end users, where quality inspection and robotic guidance applications demand sub-millimeter precision.
The EU AI Act and CE marking requirements under the Machinery Directive are reshaping compliance obligations for autonomous navigation systems deployed in European industrial settings. The FAA in the United States maintains operational constraints on beyond-visual-line-of-sight drone flights that directly limit commercial scaling of aerial vision positioning networks. Stakeholders must monitor evolving safety certification pathways as regulatory divergence between jurisdictions threatens to fragment product development roadmaps and delay cross-border deployment timelines.
Market Dynamics
Sensor fusion architectures are compressing development timelines for vision positioning hardware as manufacturers race to integrate LiDAR, visual odometry, and inertial measurement units into unified navigation stacks. This convergence is forcing component suppliers to reposition around software-defined localization platforms rather than discrete sensor sales.
Growth Catalysts
- EU AI Act compliance mandates:Automated navigation systems in European industrial settings face mandatory conformity assessments under the Machinery Directive, creating pull for certified vision positioning hardware.
- Automotive quality inspection:Sub-millimeter precision requirements in robotic guidance applications are accelerating machine vision deployments across assembly lines.
- CMOS sensor cost curves:Declining component prices are expanding addressable markets for camera-based systems in mid-tier logistics automation.
Market Restraints
- East Asian supply concentration:Sensor module production clustering in Taiwan and South Korea exposes buyers to geopolitical disruption risks and single-source dependencies.
- FAA operational constraints:Beyond-visual-line-of-sight flight restrictions in the United States directly throttle commercial scaling of aerial vision positioning networks.
- Silicon wafer input volatility:Foundry capacity allocation for automotive-grade image sensors competes with consumer electronics, creating spot price instability.
Strategic Opportunities
- German industrial automation clusters:Automotive manufacturers in Bavaria and Baden-Württemberg are driving sensor fusion pilot programs with captive integration teams.
- Warehouse robotics convergence:Autonomous mobile robot fleets in fulfillment centers are creating demand for camera-based localization without infrastructure retrofits.
- CE marking pathway acceleration:Notified bodies are streamaging certification timelines for vision systems meeting harmonized EN ISO 13849 safety standards.
Industry Challenges
- Embedded vision software talent scarcity:Shortages of engineers proficient in SLAM algorithms and real-time image processing are extending product development cycles.
- Multi-sensor calibration complexity:Integrating LiDAR-to-camera extrinsic parameters with IMU drift compensation demands specialized test facilities and extended validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Positioning System Market |
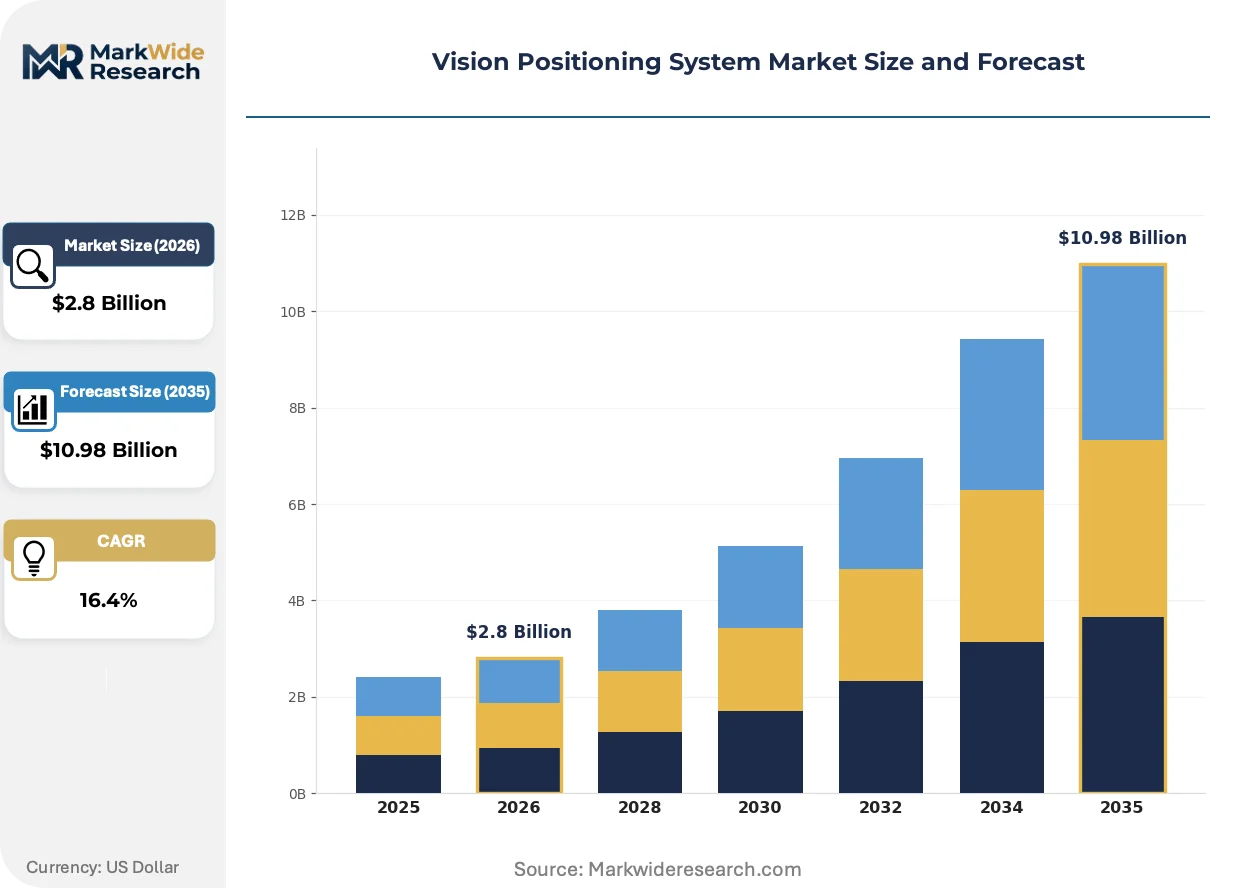
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Camera Systems, Sensor Fusion, GPS Integration Technology: Machine Vision, Depth Sensing, Image Processing, Optical Flow End User: Aerospace, Automotive Manufacturers, Robotics, Agriculture Application: Navigation, Surveillance, Environment Mapping, Object Detection |
| Companies Covered | DJI, Sick AG, ABB, Cognex Corporation, Omron Corporation, Fanuc Corporation, Seegrid Corporation, Qualcomm Technologies, Inc., Zebra Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Positioning System Market Evolving Landscape
Real-time localization architectures are pivoting from hardware-centric to software-defined stacks, compressing the value capture point toward algorithm licensing and fleet management platforms. This shift is redistributing margins across the supply chain and forcing sensor vendors to develop recurring revenue attachments.
Event-based vision sensors are electrifying robotic navigation by enabling microsecond-latency motion detection under extreme lighting variations. Automotive Tier 1 suppliers are piloting these neuromorphic cameras for autonomous parking and low-speed maneuvering in underground structures. The technology is electrifying competitive positioning by decoupling localization performance from frame-rate-dependent processing bottlenecks.
The EU AI Act's risk classification framework is mandating human oversight interfaces and traceability logs for high-risk automated navigation systems. Industrial OEMs in Germany and France are reengineering control software architectures to accommodate real-time intervention capabilities. Machine vision deployments in collaborative robotics are experiencing the steepest compliance cost inflation as manufacturers absorb documentation and conformity assessment burdens.
Fleet operators in logistics and agriculture are consolidating vendor relationships around full-stack navigation providers rather than assembling point solutions. This concentration is displacing discrete sensor distributors in North American and European channels. The pattern is most pronounced in automated warehousing, where buyers prioritize single-source accountability for localization accuracy guarantees over component-level optimization.
Vision Positioning System Market Segmentation
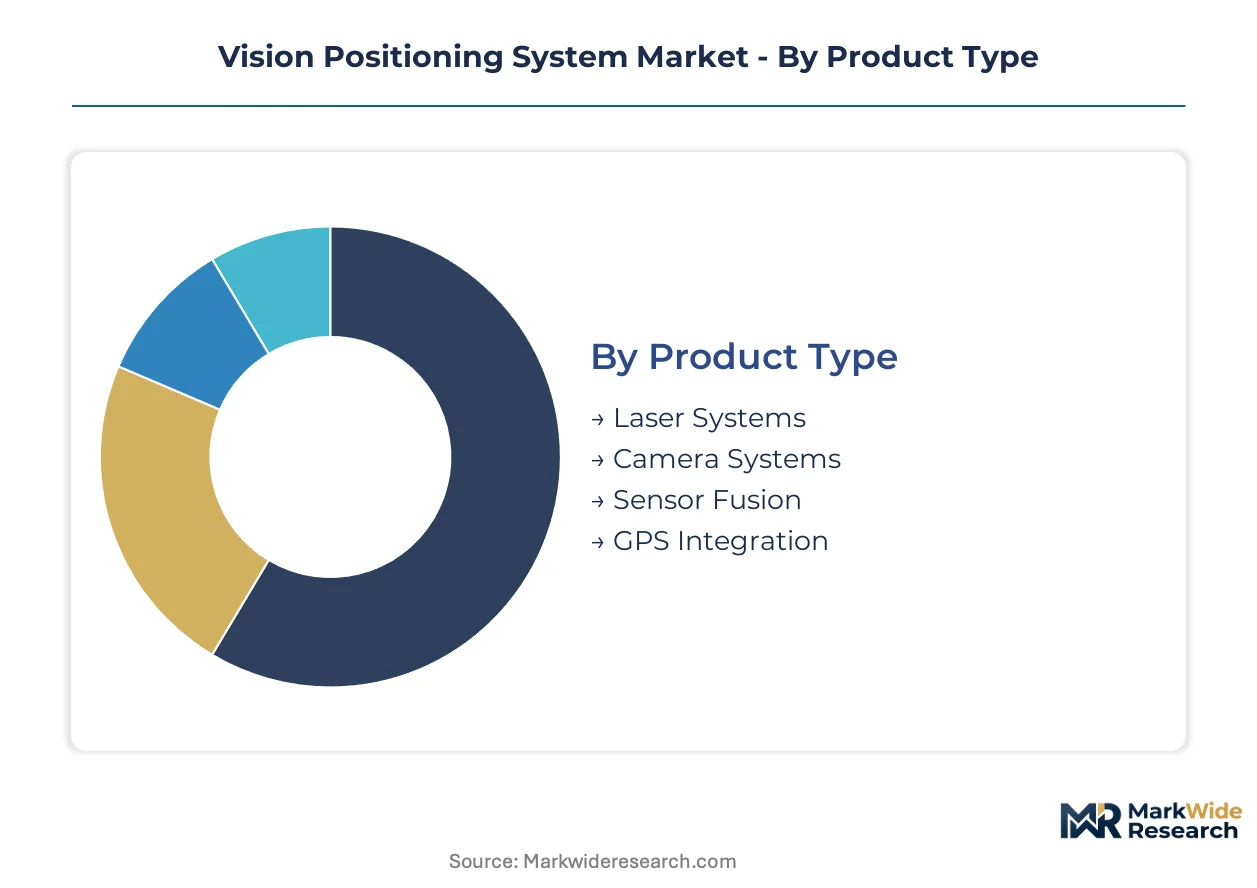
Vision positioning systems fragment across hardware architectures, computational methods, and deployment environments. Each segmentation axis reveals distinct procurement patterns and technical requirements that shape vendor positioning.
Product Type:
Technical specifications define reliability thresholds across optical and hybrid hardware platforms.
- Camera Systems:CMOS image sensors capture visual reference frames for odometry calculations at declining unit costs. Fulfillment centers in Germany deploy these for autonomous mobile robot fleets where infrastructure retrofits are prohibitively expensive.
- Sensor Fusion:LiDAR-to-camera extrinsic calibration combined with IMU drift compensation generates redundant localization data. Bavarian automotive manufacturers pilot these architectures for manufacturing floor navigation in degraded visual environments.
- Laser Systems:Time-of-flight LiDAR modules from Sick AG anchor industrial automation with centimeter-scale precision.
- GPS Integration:Multi-constellation receivers augment visual positioning in outdoor agricultural and surveying applications.
Mature deployment sits with Camera Systems. Newer deployment is concentrated in Sensor Fusion.
Technology:
Computational approaches differentiate by latency tolerance and environmental adaptability.
- Machine Vision:Convolutional neural networks process industrial imagery for sub-millimeter quality inspection. Automotive assembly lines in Baden-Württemberg drive demand for robotic guidance applications requiring deterministic precision.
- Depth Sensing:Structured light and stereo disparity algorithms reconstruct three-dimensional scene geometry. Warehouse automation clusters prioritize these methods for obstacle avoidance in dynamic environments.
- Image Processing:Edge-detection and feature-matching pipelines execute on embedded GPUs with constrained power budgets.
- Optical Flow:Pixel velocity estimation enables real-time ego-motion tracking for aerial navigation platforms.
Machine Vision captures established volume. Depth Sensing exhibits the steepest expansion trajectory.
End User:
Industry verticals impose divergent certification burdens and performance specifications.
- Automotive Manufacturers:Tier 1 suppliers integrate vision positioning for autonomous parking and assembly line robotics under EU AI Act conformity requirements.
- Robotics:Collaborative robot deployments in France absorb documentation burdens for CE marking under EN ISO 13849 safety standards.
- Aerospace:FAA beyond-visual-line-of-sight constraints throttle commercial scaling of aerial vision networks.
- Agriculture:Fleet operators consolidate vendor relationships around full-stack navigation providers for precision spraying and harvesting automation.
Procurement sophistication concentrates with Automotive Manufacturers. Application diversity expands fastest in Agriculture.
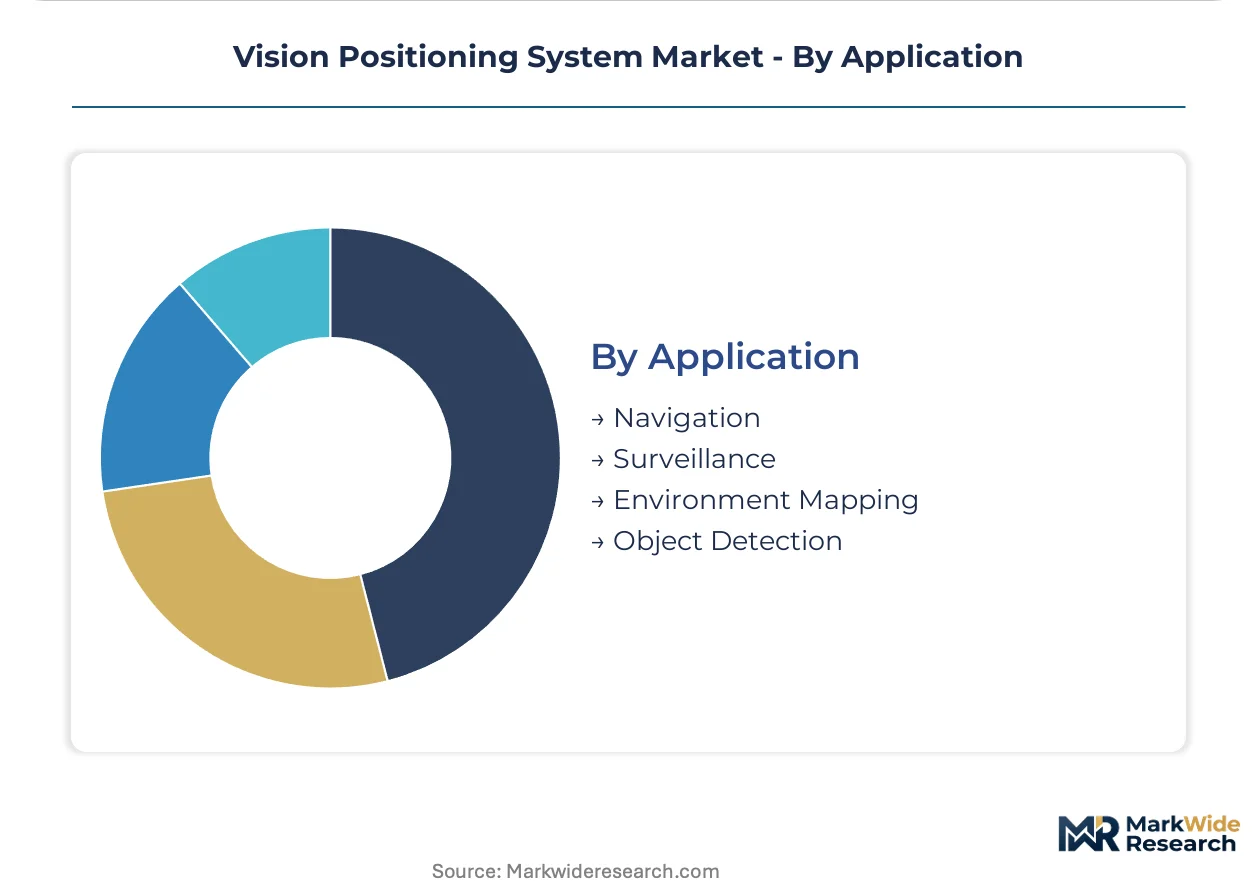
Application:
Use-case architectures determine sensor configuration and software stack requirements.
- Navigation:Real-time localization stacks process visual data exceeding 30 Hz for autonomous vehicular guidance.
- Object Detection:Classification networks identify obstacles and landmarks for collision avoidance systems.
- Environment Mapping:SLAM algorithms construct persistent spatial representations for facility digital twins.
- Surveillance:Pan-tilt-zoom integration with geospatial referencing supports perimeter monitoring installations.
Navigation commands the largest installed base. Environment Mapping is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan and South Korea anchors the upstream supply base for vision positioning hardware. CMOS sensor foundries in Hsinchu and Pyeongtaek feed module assembly lines across East Asia. Component sourcing patterns concentrate procurement decisions in these manufacturing corridors.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg drive sensor fusion pilot programs for manufacturing floor navigation. The EU AI Act mandates conformity assessments for high-risk automated systems under harmonized EN ISO 13849 safety standards. Stuttgart industrial clusters absorb documentation burdens for CE marking on collaborative robotics deployments.
United States
Warehouse robotics operators in California and Illinois consolidate vendor relationships around full-stack navigation providers. FAA beyond-visual-line-of-sight constraints throttle commercial scaling of aerial vision networks in logistics and agriculture. Boston robotics clusters specialize in embedded SLAM software for autonomous mobile robot fleets.
China
Drone manufacturers in Shenzhen leverage domestic CMOS sensor supply chains for consumer aerial navigation platforms. MIIT standards for autonomous vehicle localization guide Tier 1 supplier development roadmaps. Yangtze River Delta electronics corridors integrate vision positioning modules for industrial automation exports.
Japan
Automotive Tier 1 suppliers in Nagoya pilot neuromorphic event-based vision sensors for autonomous parking systems. METI technology roadmaps prioritize real-time localization accuracy for manufacturing robotics. Osaka industrial automation clusters demand sub-millimeter precision for assembly line quality inspection.
South Korea
Display and semiconductor manufacturers in Gyeonggi Province deploy machine vision for defect detection in OLED fabrication. MFDS medical device regulations influence safety architecture for surgical navigation systems. Seoul robotics startups commercialize depth-sensing algorithms for warehouse automation.
Vision Positioning System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined localization platforms and event-based sensor architectures. The vendor base stratifies across three tiers: diversified automation conglomerates with captive navigation divisions, pure-play sensor specialists with hardware-centric revenue models, and software-focused algorithm licensors with recurring platform fees. Competitive moves concentrate on strategic partnerships between sensor vendors and fleet management platforms, plus backward integration into CMOS module fabrication to secure supply.
Within the diversified automation tier, ABB and Fanuc Corporation exemplify conglomerate positioning with integrated robotics and vision system portfolios. DJI represents the aerial navigation specialist archetype, leveraging consumer drone heritage for commercial imaging applications. Sick AG anchors the industrial sensor specialist position with laser-based localization systems for manufacturing floors.
| Leading Market Players |
|---|
| DJI |
| Sick AG |
| ABB |
| Cognex Corporation |
| Omron Corporation |
| Fanuc Corporation |
| Seegrid Corporation |
| Qualcomm Technologies, Inc. |
| Zebra Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CE-marked industrial systems and uncertified consumer-grade hardware manifests in both pricing stratification and procurement geography. Automotive manufacturers in Baden-Württemberg absorb premium positioning for EN ISO 13849-compliant sensor fusion stacks, while logistics operators in Illinois prioritize cost-optimized camera modules from East Asian distributors.
Pricing Analysis
Warranty bundling and calibration service attachments separate premium sensor fusion deployments from transactional camera system sales. Three-tier pricing structure across certified industrial, commercial mid-grade, and consumer-grade economy levels tracks EN ISO 13849 compliance tiers and software update entitlements. Pricing pressure stems from CMOS sensor commoditization in Taiwan and South Korea, compressing margins for standalone camera vendors. Price sensitivity concentrates with warehouse robotics operators seeking fleet-scale volume discounts, while automotive Tier 1 suppliers prioritize deterministic accuracy guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke fulfillment for vision positioning hardware destined to European and Southeast Asian automation clusters. Foundry capacity in Taiwan, South Korea, and China feeds CMOS sensor module assembly, drawing from silicon wafer inputs and precision optics from Japan. Single-source vulnerability concentrates in Hsinchu sensor foundries serving automotive-grade image sensor demand. Distribution runs through authorized industrial automation distributors with captive integration engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a transition from hardware-centric discrete sensor sales toward software-defined localization platforms, with sensor fusion architectures displacing standalone camera systems in precision-critical deployments.
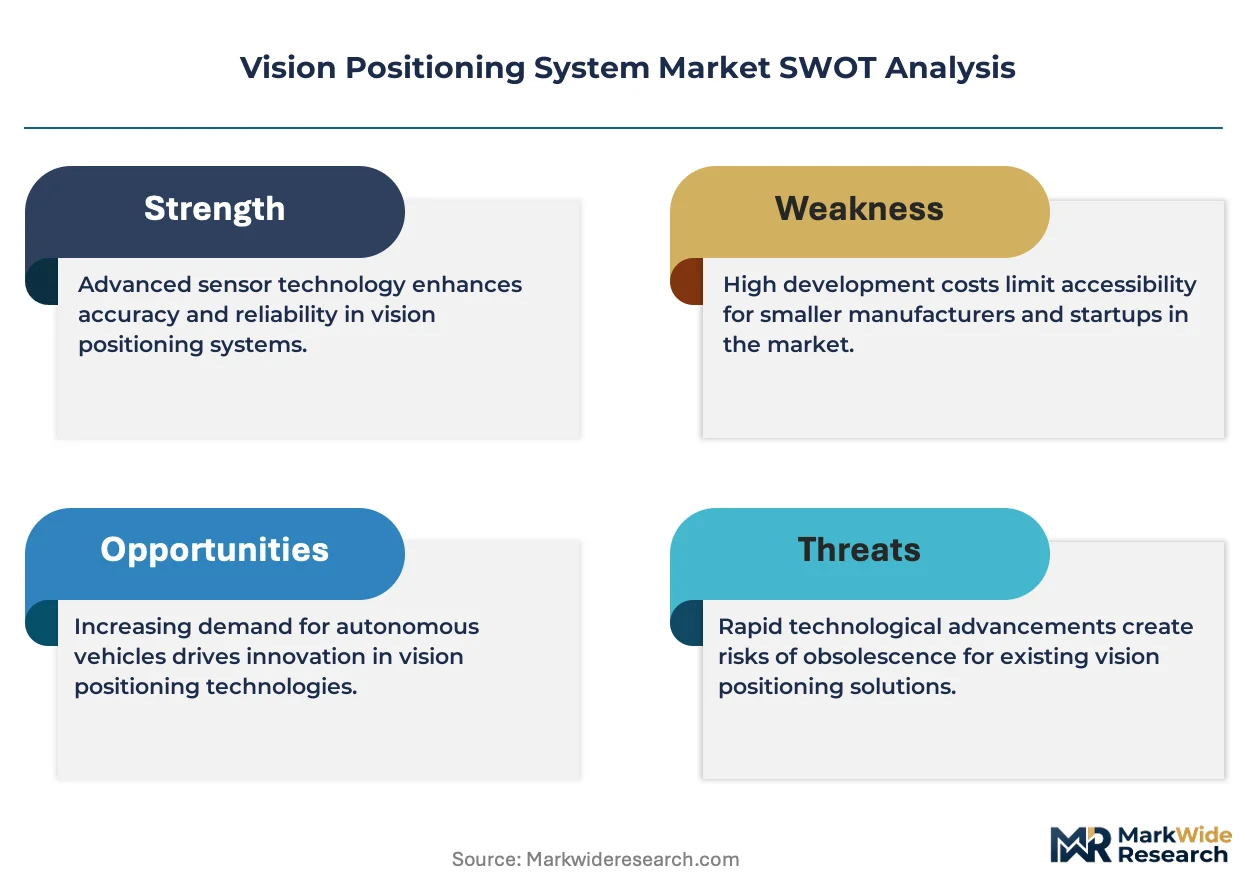
For Market Incumbents: Cement control over calibration IP and fleet management platform subscriptions to defend against pure-play algorithm licensors. Backward integration into automotive-grade CMOS module fabrication secures supply continuity against Taiwan foundry allocation competition. Prioritize EN ISO 13849 certification maintenance as EU AI Act conformity assessments intensify documentation burdens for collaborative robotics deployments. For New Entrants and Emerging Players: Fleet management platform providers represent the most penetrable channel partner type for software-defined localization stacks targeting mid-tier logistics automation. Precision agriculture in the United States offers white-space expansion as FAA beyond-visual-line-of-sight constraints gradually relax for commercial aerial navigation. White-label SLAM algorithm licensing to warehouse robotics OEMs bypasses capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with software-focused algorithm licensors given recurring platform fee attachment to sensor hardware sales. Long-term viability favors vendors with embedded vision software talent depth and CE marking pathway expertise. Watch for EU AI Act enforcement consistency as the inflection signal for compliance-premium capture in European industrial automation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies LiDAR, visual odometry, and IMU data streams for Bavarian automotive manufacturers. |
| CE Marking Pathway Acceleration | Streamlines EN ISO 13849 conformity assessments for Stuttgart collaborative robotics deployments. |
| Backward Integration into CMOS Module Fabrication | Secures captive supply of automotive-grade image sensors against Taiwan foundry allocation volatility. |
| Strategic Partnership with Fleet Management Platforms | Consolidates vendor relationships for warehouse robotics operators in California fulfillment centers. |
| Neuromorphic Sensor Technology Licensing | Enables microsecond-latency motion detection for Nagoya autonomous parking system pilots. |
Research Methodology
Independent corroboration across primary interviews with robotics OEM procurement teams, embedded vision software engineers, and industrial automation distributors, plus secondary validation from SEC filings, EIA manufacturing data, and EU regulatory databases, underwrites the qualitative findings. Bottom-up triangulation across sensor module shipment data and top-down validation against automotive production volumes anchor the market sizing.
Comparable-period anchoring to historical CMOS sensor cost curves and machine vision deployment trajectories structures the forecast framework across the analysis window. Segmentation dimensions modeled include hardware architecture, computational technology, end-user vertical, and application use-case, with sensor fusion adoption rates and EU AI Act compliance timelines as industry-specific forecast inputs. CAGRs derive from regression analysis against industrial automation capital expenditure patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory relaxations on FAA beyond-visual-line-of-sight operations and geopolitical disruptions to Taiwan foundry capacity. Forecasts reflect documented assumptions around CMOS sensor cost compression continuity and EN ISO 13849 certification pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Mobile Laser Scanning Market
Sensors
Cloud Camera Market
Sensors
Indoor Location Market
Sensors
2D Barcode Reader Market
Sensors
Refrigeration Monitoring Market
Sensors
Telemetric Devices Market
Sensors
Automated Weather Observation System Market
Sensors
Transportation Sensors Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Alcohol Sensor Market
Sensors
Connected Smart Thermostats Market
Sensors
Residential Water Leak Detection System Market
Sensors
Digital Olfaction Products Market
Sensors
Low Power Geolocation Market
Sensors
Gesture Recognition in Retail Market
Sensors
Body Area Network Market