
 Bulletproof Helmet Market | 2026-2036
Bulletproof Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Bulletproof Helmet Market Intelligence
Specialized composite-weaving expertise is redrawing competitive boundaries in the bulletproof helmet industry. Gentex Corporation leverages deep aerospace manufacturing heritage to sustain premium positioning in military aviation and ground-force head protection. Ops-Core anchors the high-velocity impact segment through advanced retention system design. MARS Armor competes aggressively on European defense tenders with regionally certified ballistic solutions.
A bulletproof helmet is a personal protective device engineered to defeat ballistic threats, fragmentation, and blunt trauma through layered aramid or ultra-high-molecular-weight polyethylene composites, typically rated against NIJ Level IIIA or equivalent military specifications for handgun and shrapnel resistance. Its primary purpose is preserving cranial integrity under combat, tactical, or civil-disturbance conditions. Ballistic helmets lead material spend due to sustained military modernization budgets, while tactical helmets represent the fastest-growing product category as law enforcement agencies upgrade from legacy riot gear. Kevlar dominates material procurement volumes, though composite laminates capture expanding margin pools where weight reduction commands price premiums.
The U.S. National Institute of Justice (NIJ) sets minimum ballistic resistance and backface deformation thresholds that determine market access for domestic suppliers. The U.S. Army's Program Executive Office Soldier enforces supplemental fragmentation and environmental durability standards that exceed baseline NIJ requirements. Stakeholders must monitor evolving NIJ revision cycles and European EN 397/EN 14052 harmonization efforts, as regulatory divergence between U.S. and European test protocols will shape dual-certification investment decisions.
Market Dynamics
Military modernization cycles and tightening NIJ ballistic standards are compressing helmet replacement timelines while forcing composite material upgrades across NATO procurement programs.
Growth Catalysts
- Enhanced Combat Helmet Program:The U.S. Army's initiative mandates fragmentation resistance thresholds that exceed baseline NIJ Level IIIA requirements, forcing material upgrades across supplier bases.
- Aramid Fiber Advances:Next-generation Kevlar and Twaron weaving techniques reduce backface deformation by double-digit percentages without weight penalties.
- Special Operations Procurement:Tier-one military units in the United States, United Kingdom, and Germany drive premium-tier volume through mission-specific customization requirements.
Market Restraints
- Ultra-High-Molecular-Weight Polyethylene Concentration:Three Asian suppliers control over 70% of UHMWPE fiber feedstock, creating single-source vulnerability for Western armor integrators.
- NIJ Certification Timeline:Backface deformation testing and environmental conditioning protocols extend product approval cycles to 18-24 months, freezing working capital.
- Blunt Trauma Trade-offs:Weight-driven composite optimization often sacrifices multi-hit durability, creating specification tension between mobility and protection mandates.
Strategic Opportunities
- Law Enforcement Modernization:U.S. municipal police departments and federal agencies are retiring 1990s-era riot helmets, opening replacement demand for integrated ballistic-tactical platforms.
- Additive Manufacturing Integration:3D-printed retention system components and custom-fit liner geometries enable mass customization at unit-level procurement scale.
- European EN 14052 Harmonization:Pending alignment between NIJ and European high-performance industrial helmet standards will reduce dual-certification costs for transatlantic suppliers.
Industry Challenges
- Ballistic Composite Engineering Talent:The specialized knowledge base for aramid-PE hybrid layup optimization has concentrated at a handful of aerospace heritage facilities, constraining supplier expansion.
- Legacy System Integration:Night vision mount compatibility and communication headset interface standards vary across NATO member states, fragmenting design requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulletproof Helmet Market |
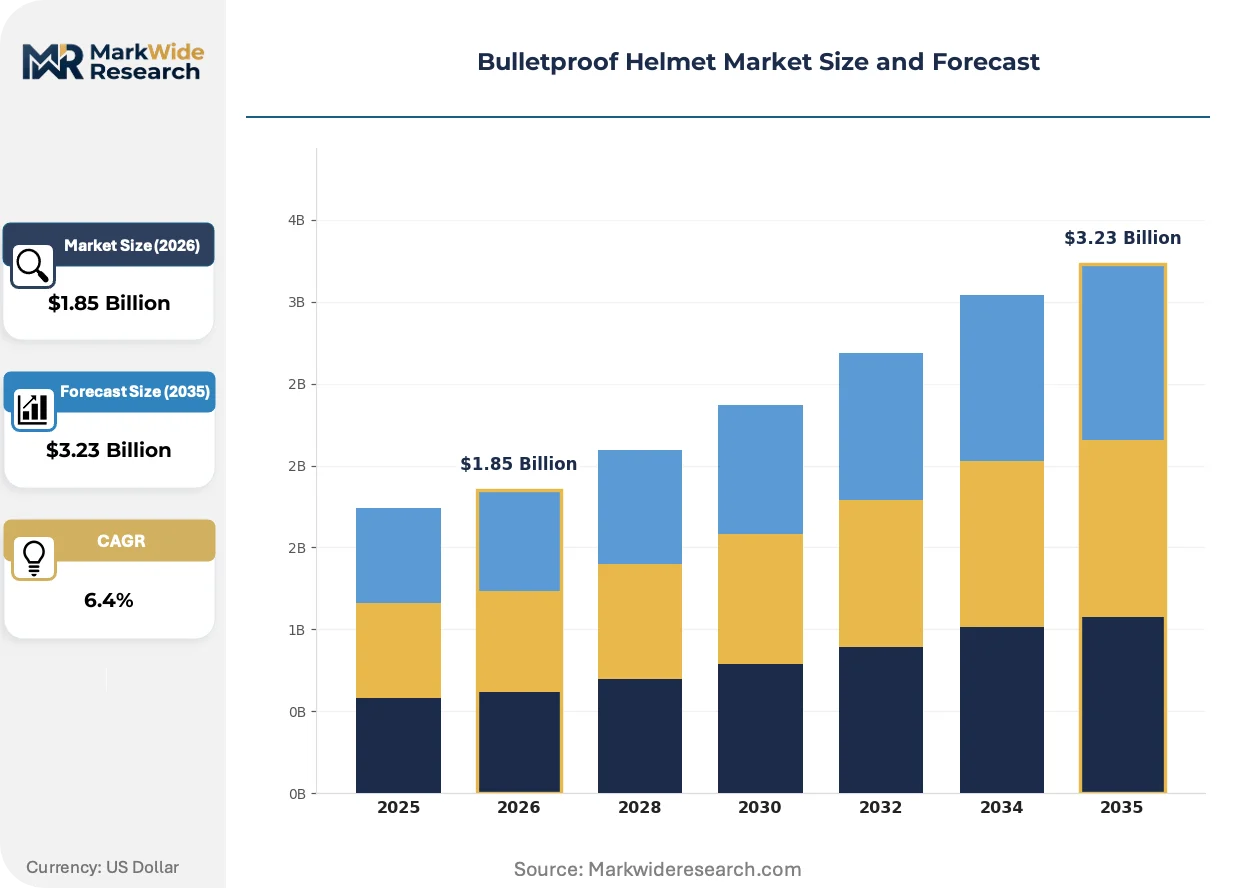
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Combat Helmets, Riot Helmets, Tactical Helmets Material: Kevlar, Polycarbonate, Steel, Composite End User: Military, Law Enforcement, Private Security, Sports Application: Combat, Rescue Operations, Riot Control, Tactical Training |
| Companies Covered | Protection Group Denmark, MARS Armor, Gentex Corporation, EnGarde Body Armor, Schuberth, Ops-Core, Crye Precision, Ballistic Armor Co., Team Wendy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulletproof Helmet Market Strategic Shifts & Innovations
Material science breakthroughs and procurement digitization are compressing product development cycles while fragmenting traditional supplier hierarchies in military head protection.
Ultra-high-molecular-weight polyethylene laminates is supplanting pure aramid constructions in high-velocity threat applications. U.S. special operations forces and select federal law enforcement units have accelerated adoption timelines from experimental to standard-issue within 36 months. This material transition is supplanting legacy Kevlar-dominant supply relationships and compressing margins for weavers without captive PE fiber access.
REACH chemical substance restrictions in Europe are tightening precursor availability for certain aramid curing agents. German and French defense contractors face reformulation mandates that extend qualification timelines by 8-12 months. Military aviation helmet programs are most affected, as aerospace-grade flame resistance requirements conflict with substitutable chemistry profiles.
Unit-level digital procurement portals are displacing centralized defense ministry tender processes for tactical helmet accessories and replacement components. U.S. Army brigade combat teams and Marine expeditionary units now source retention systems and rail adapters through direct vendor interfaces. This channel shift concentrates demand intelligence with end-users rather than prime contractors, compressing aftermarket pricing power.
Bulletproof Helmet Market Segmentation
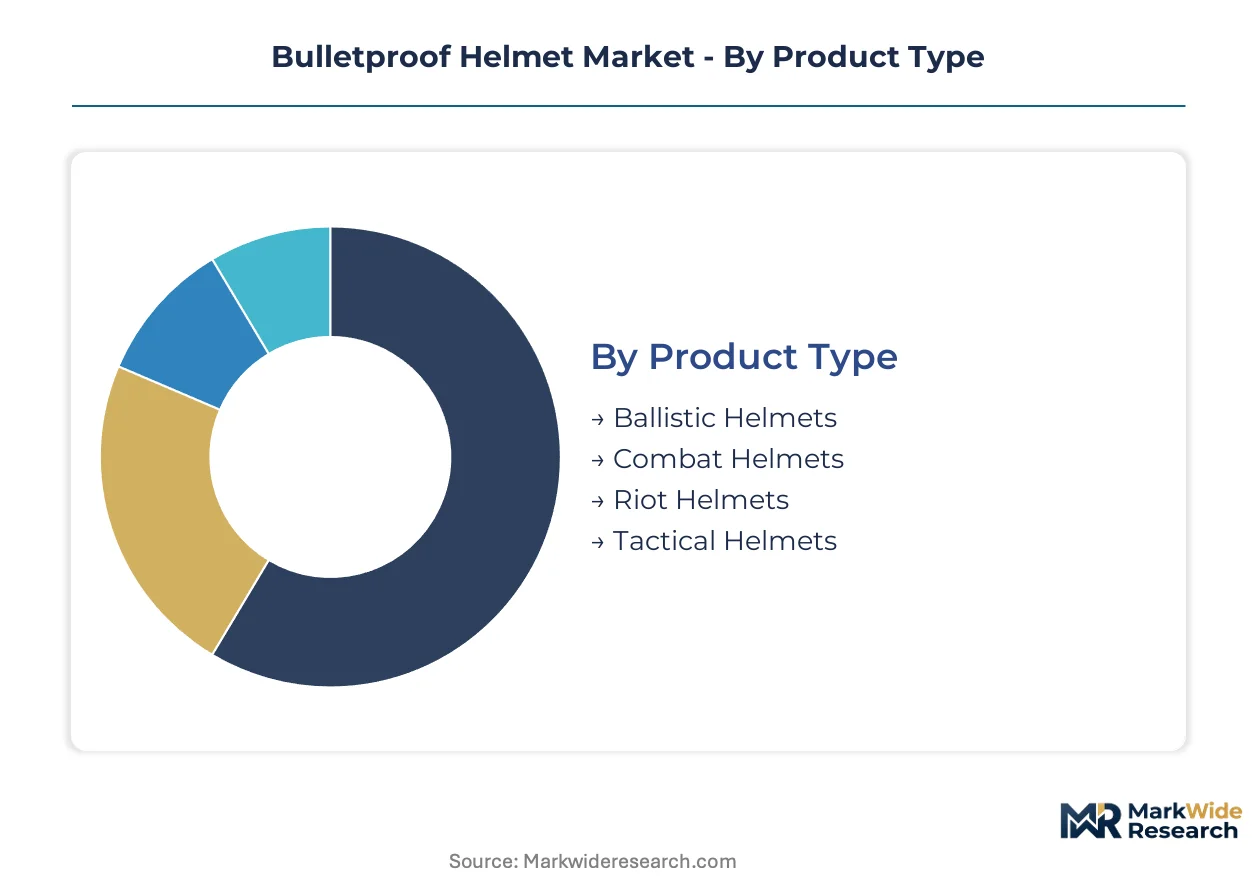
Segmentation in bulletproof helmets reveals how NIJ certification tiers and military specification divergence create distinct procurement channels. Material selection and end-user mission profiles determine price-realization potential across supplier bases.
Product Type:
NIJ Level IIIA certification mandates and military fragmentation standards split procurement between baseline ballistic protection and enhanced threat defeat.
- Ballistic Helmets:Aramid or UHMWPE composite constructions rated for handgun and fragmentation threats per NIJ 0106.01. U.S. Army Program Executive Office Soldier procurement concentrates volume here, with backface deformation thresholds below 25.4 mm driving material selection.
- Tactical Helmets:Modular platforms integrating rail systems, night vision mounts, and communication interfaces. Law enforcement agencies in the United States and Germany are upgrading legacy riot gear, with unit-level customization requirements expanding margin pools.
- Combat Helmets:Military-specification designs exceeding baseline NIJ requirements for multi-hit durability and environmental conditioning.
- Riot Helmets:Face-shield integrated systems for civil disturbance control, prioritizing blunt trauma protection over ballistic defeat.
Established volume favors ballistic helmets; emerging adoption favors tactical helmets.
Material:
Cost tiers stratify around weight-performance trade-offs and fiber supply concentration.
- Kevlar:DuPont aramid fiber dominates procurement volumes through established weaving infrastructure and NIJ qualification heritage. Legacy military contracts and municipal police budgets sustain demand despite weight penalties versus polyethylene alternatives.
- Composite:Hybrid aramid-UHMWPE laminates and advanced weaving techniques command price premiums where weight reduction justifies cost. U.S. special operations forces and select federal agencies drive specification shifts, with fragmentation resistance improvements accelerating substitution timelines.
- Polycarbonate:Transparent face shield and visor applications in riot control configurations.
- Steel:Legacy constructions retained for training and ceremonial applications, largely displaced in operational procurement.
Volume procurement concentrates in Kevlar; performance-driven substitution favors composite laminates.
End User:
Customer type determines specification stringency and replacement cycle frequency.
- Military:NATO procurement programs and U.S. Enhanced Combat Helmet mandates drive premium-tier volume with multi-year replacement cycles. Fragmentation and environmental durability requirements exceed commercial NIJ baselines.
- Law Enforcement:U.S. municipal departments and federal agencies are retiring 1990s-era equipment, opening replacement demand for integrated ballistic-tactical platforms with modular accessory compatibility.
- Private Security:Corporate and executive protection details source NIJ-certified helmets through commercial distributors, with cost sensitivity higher than government procurement.
- Sports:Competitive shooting and extreme sports applications represent niche demand with recreational-grade certification tolerance.
Budget concentration sits with military end users; fastest volume expansion is occurring in law enforcement.
Application:
Mission profile dictates helmet geometry, retention system design, and accessory integration requirements.
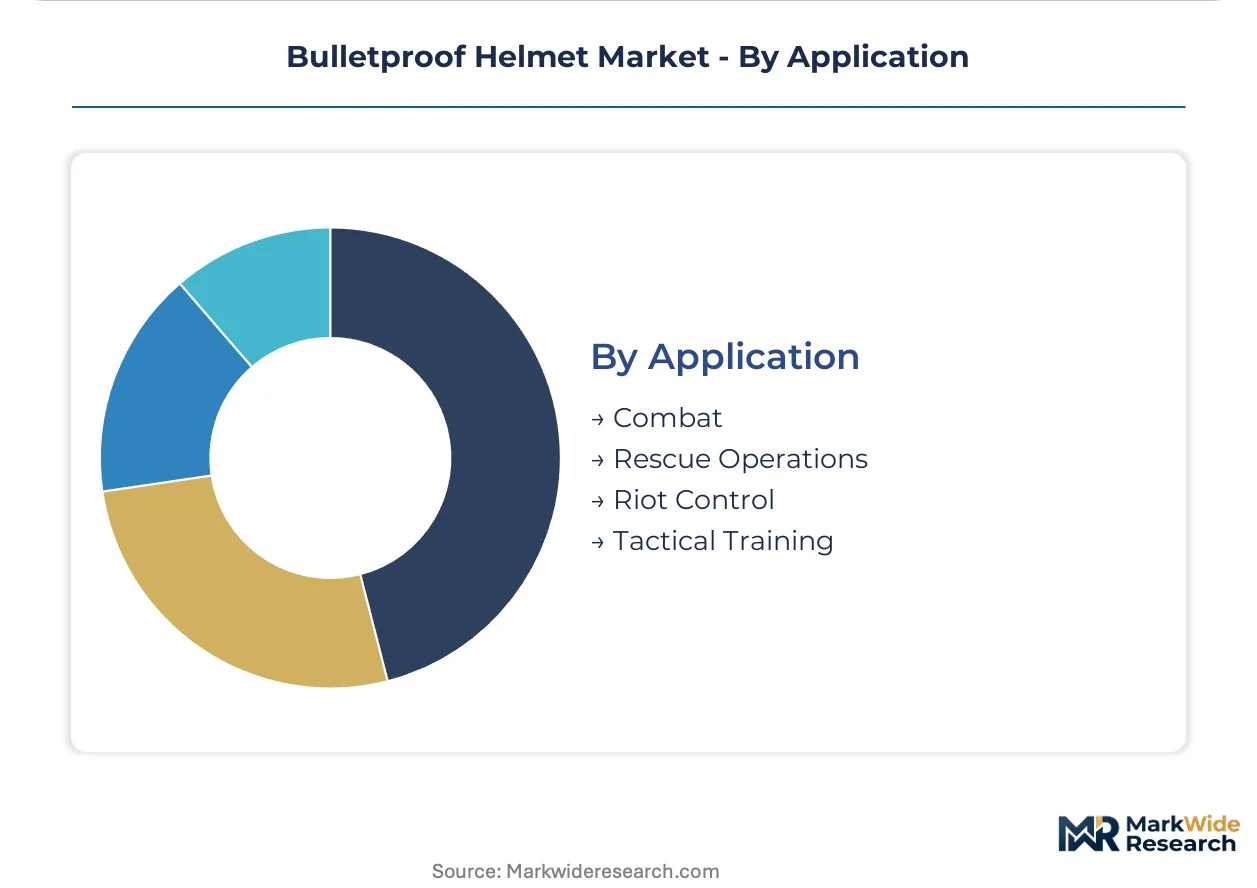
- Combat:Full-spectrum ballistic and fragmentation protection with night vision and communication system integration. U.S. Army and Marine Corps specifications drive design standards across NATO interoperability frameworks.
- Riot Control:Face shield compatibility, neck protection extension, and blunt trauma optimization for civil disturbance scenarios. European EN 397/EN 14052 harmonization efforts are reshaping certification requirements for this segment.
- Rescue Operations:Search-and-recovery and disaster response configurations balancing impact protection with extended wear comfort.
- Tactical Training:Simulation and force-on-force exercise equipment with reduced ballistic ratings and enhanced ventilation.
Specification complexity peaks in combat applications; procurement flexibility is greatest in tactical training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. National Institute of Justice anchors the dominant geography through NIJ 0106.01 certification requirements that shape procurement standards across NATO defense programs. Military modernization cycles and law enforcement equipment replacement programs concentrate demand in specific national markets with distinct regulatory frameworks.
United States
The Enhanced Combat Helmet program and special operations procurement drive premium-tier volume through the U.S. Army Program Executive Office Soldier. NIJ backface deformation thresholds below 25.4 mm enforce material selection standards that exceed baseline commercial requirements. Gentex Corporation and Ops-Core anchor manufacturing capability in Rochester, New Hampshire and New Hampshire's Seacoast region respectively, where aerospace heritage facilities concentrate composite-weaving expertise.
Germany
Bundeswehr helmet replacement cycles and federal police modernization sustain demand for EN 14052-certified platforms with night vision compatibility. The country's national defense procurement office enforces fragmentation resistance standards that diverge from NIJ protocols, requiring dual-certification investment. Schuberth maintains production concentration in Braunschweig, Lower Saxony, where automotive and aerospace supplier networks feed helmet composite fabrication.
United Kingdom
Ministry of Defence Future Soldier program requirements and counter-terrorism police equipment upgrades compress replacement timelines for ballistic head protection. The UK's national standards body maintains BSI certification protocols that partially align with NATO STANAG 2920 fragmentation testing. Crye Precision and Team Wendy distribution networks concentrate around London procurement corridors serving special operations and metropolitan police units.
France
DGA procurement mandates and Gendarmerie nationale riot control modernization create parallel demand channels for combat and civil disturbance configurations. ANSM chemical substance notifications intersect with REACH restrictions to constrain aramid curing agent availability for domestic weavers. MARS Armor competes through regional certification expertise from Bulgarian manufacturing facilities supplying French defense tenders.
Denmark
Scandinavian defense cooperation frameworks and Nordic Battlegroup interoperability requirements standardize helmet specifications across joint procurement programs. The Danish national standardization body participates in EN 397/EN 14052 harmonization efforts that reduce certification friction for regional suppliers. Protection Group Denmark anchors Nordic manufacturing capability from Copenhagen-area facilities serving domestic and Swedish, Norwegian export markets.
Bulletproof Helmet Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with aerospace heritage manufacturers commanding premium positioning through captive composite-weaving capability. The structure concentrates around three strategic archetypes: integrated defense contractors with multi-platform portfolios, pure-play helmet specialists with modular accessory ecosystems, and regional armor fabricators competing on tender proximity. Dominant competitive moves include backward integration into UHMWPE fiber sourcing to escape Asian feedstock concentration, and strategic partnerships with night vision mount standard-setters to lock in accessory compatibility.
Within the integrated defense tier, Gentex Corporation and Schuberth exemplify aerospace-to-ground-force capability transfer, while Ops-Core occupies a position at the high-velocity impact specialization vector. Among Nordic and Eastern European fabricators, Protection Group Denmark and MARS Armor represent regional certification expertise archetypes. Crye Precision and Team Wendy sit within the modular ecosystem tier, where retention system and rail adapter standard-setting determines aftermarket pricing power. The specialist tier fragments across law enforcement and private security channels where NIJ certification heritage serves as primary differentiation.
| Leading Market Players |
|---|
| Protection Group Denmark |
| MARS Armor |
| Gentex Corporation |
| EnGarde Body Armor |
| Schuberth |
| Ops-Core |
| Crye Precision |
| Ballistic Armor Co. |
| Team Wendy |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month NIJ certification timelines compress working capital cycles while concentrating pricing power with suppliers holding captive composite-weaving capability. This lead-time band forces tier-one integrators to pre-position inventory against military procurement windows, amplifying cost pass-through capacity for aramid and UHMWPE fiber producers.
Pricing Analysis
Price spreads between U.S. and European tender awards widen where dual-certification requirements inflate compliance overhead. Three-tier pricing structure across premium, standard, and economy levels segments by NIJ certification tier and fragmentation resistance rating, with special operations specifications commanding substantial premiums over baseline law enforcement configurations. Pricing pressure stems from Asian UHMWPE feedstock concentration that constrains Western integrators' negotiating leverage. Federal law enforcement agencies exhibit lowest price sensitivity due to mission-critical mandates, while municipal police departments and private security contractors drive volume in cost-optimized tiers.
Supply Chain Analysis
Container availability fluctuations on trans-Pacific lanes disrupt just-in-time fiber deliveries to Rochester, New Hampshire and Braunschweig weaving facilities. Raw material sourcing draws from South Korea, Japan, and China for UHMWPE fiber, with aramid precursor supply anchored in the United States and European Union. Single-source vulnerability concentrates in Asian UHMWPE feedstock, where three suppliers control majority Western armor integrator access. Distribution runs through defense ministry tender platforms for military volume, while law enforcement procurement shifts toward unit-level digital portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulletproof helmet market is recovering from compressed replacement cycles triggered by NATO military modernization programs and NIJ standard tightening. Defense budget cyclicality in member states creates procurement wave timing that favors prepared suppliers.
For Market Incumbents: Secure captive UHMWPE fiber sourcing through backward integration or long-term offtake agreements to escape Asian supplier concentration. Lock in night vision mount standard-setting partnerships to defend accessory ecosystem control against modular competitors.
For New Entrants and Emerging Players: Anchor in European EN 14052 certification expertise where dual-standard harmonization reduces barrier to transatlantic tenders. Target municipal law enforcement modernization white space with integrated ballistic-tactical platforms, leveraging direct digital procurement channel emergence to bypass prime contractor gatekeeping.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace heritage manufacturers with dormant composite-weaving capacity applicable to ground-force protection. Long-term viability hinges on material science transition from aramid to polyethylene dominance; monitor UHMWPE adoption velocity in U.S. special operations procurement as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UHMWPE Fiber | Captive supply from Asian feedstock concentration secures margin control for Western armor integrators. |
| Dual-Certification Investment | NIJ and EN 14052 alignment reduces qualification overhead for transatlantic defense tender participation. |
| Additive Manufacturing Adoption | 3D-printed retention components enable mass customization at unit-level procurement scale. |
| Modular Accessory Ecosystem Expansion | Rail adapter and night vision mount standard-setting locks in aftermarket pricing power. |
| Law Enforcement Channel Digitization | Direct vendor interfaces with brigade combat teams concentrate demand intelligence away from prime contractors. |
Research Approach
The analysis maps ballistic helmet, tactical helmet, combat helmet, and riot helmet sub-sectors, each validated through defense procurement officers, composite manufacturing engineers, NIJ certification specialists, and law enforcement equipment coordinators. Primary fieldwork combined structured interviews with secondary validation against U.S. Army Program Executive Office Soldier disclosures, NIJ 0106.01 standard documentation, NATO STANAG 2920 fragmentation protocols, and defense ministry tender databases. Bottom-up unit demand estimation triangulated against top-down military budget allocation analysis.
Consistency checks validated volume and value outputs against external defense expenditure benchmarks and historical procurement cycle patterns across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user category, and application mission profile. CAGRs were derived from replacement cycle compression rates and material substitution timelines, with UHMWPE adoption velocity and NIJ revision cycle timing serving as key forecast inputs.
Underlying assumptions cover sustained NATO military modernization commitment and stable UHMWPE feedstock availability, with deviation risk concentrated in defense budget cyclicality and REACH chemical restriction expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market