
 Anti-Static Safety Clothing Market | 2026-2036
Anti-Static Safety Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Safety Clothing Market Insights
Class 100 cleanroom specification upgrades across semiconductor and pharmaceutical facilities is unwinding procurement patterns toward higher-grade anti-static garments. DuPont de Nemours, Inc. leverages its Tyvek and ProShield material platforms to anchor premium cleanroom coverall supply chains. 3M Company competes through integrated respiratory and body protection systems that bundle anti-static properties with chemical resistance. Teijin Limited specializes in aramid and ultra-high molecular weight polyethylene fibers that reduce particle shedding in controlled environments.
Anti-static safety clothing denotes garments engineered with conductive fibers or surface treatments to dissipate electrostatic charge, typically achieving surface resistivity between 10^5 and 10^11 ohms per square to prevent electrostatic discharge damage to sensitive components. These garments incorporate carbon-suffused yarns, metal fiber blends, or intrinsic conductive polymers woven into base fabrics through shuttleless looms or warp knitting, then finished with topical anti-static agents for controlled decay rates in electronics assembly, explosive atmosphere operations, and pharmaceutical compounding. Coveralls dominate volume throughput across electronics manufacturing cleanrooms where full-body encapsulation prevents human-borne contamination, while gloves command disproportionate margin pools due to precision dexterity requirements and frequent replacement cycles in semiconductor wafer handling. Aerospace applications represent the fastest-growing demand segment as satellite and defense electronics production scales up, with nylon-cotton blends gaining preference over pure synthetics for improved moisture management in extended wear scenarios.
The U.S. Occupational Safety and Health Administration enforces 29 CFR 1910.269 for flame-resistant and anti-static apparel in electric power generation, while the EU's PPE Regulation (EU) 2016/425 mandates CE marking with Module B+C2 conformity assessment for Category III electrostatic risk garments. China's SAMR administers GB 12014-2019 certification for anti-static workwear used in petrochemical and electronics sectors, creating divergent testing protocols that fragment supplier qualification burdens. Stakeholders must monitor evolving IEC 61340-5-1 standard revisions for electrostatic protected areas, as stricter garment charge decay thresholds will force material reformulation investments and reshape competitive positioning among certified manufacturers.
Market Dynamics
Semiconductor fabrication facilities in Taiwan, South Korea, and the United States are driving cleanroom apparel procurement as chip production capacity expands, tightening certification requirements under divergent national standards.
Growth Catalysts
- EU PPE Regulation (EU) 2016/425:CE marking mandates for Category III electrostatic risk garments are forcing procurement upgrades across European electronics manufacturing, expanding addressable market for certified suppliers.
- Carbon-suffused conductive yarns:Advanced fiber integration is achieving surface resistivity targets below 10^9 ohms per square, enabling compliance with IEC 61340-5-1 for electrostatic protected areas.
- East Asian electronics clusters:Concentrated demand from Taiwan, South Korea, and China cleanroom operations is creating volume anchors that amortize R&D costs across production runs.
Market Restraints
- Aramid fiber supply concentration:Teijin Limited and DuPont control upstream para-aramid supply chains, creating input cost volatility for mid-tier garment assemblers without backward integration.
- GB 12014-2019 testing divergence:China's SAMR certification protocols differ from EU Module B+C2 assessment, fragmenting supplier qualification burdens and extending market entry timelines.
- Reusable garment laundering infrastructure:Capital-intensive cleanroom laundry networks concentrate in developed economies, limiting serviceable market penetration in emerging manufacturing regions.
Strategic Opportunities
- Aerospace electronics manufacturing:Satellite and defense electronics production scaling in the United States and Europe is creating fastest-growing demand segment for nylon-cotton blend anti-static coveralls.
- India's PLI scheme for semiconductors:Production-linked incentives for chip fabrication are attracting cleanroom infrastructure investment, opening underpenetrated procurement market for certified apparel suppliers.
- Integrated respiratory-body protection systems:Convergence of anti-static garments with chemical-resistant respiratory equipment is enabling premium bundling strategies in pharmaceutical compounding operations.
Industry Challenges
- IEC 61340-5-1 standard revision timelines:Pending stricter garment charge decay thresholds are forcing material reformulation investments before certification certainty, compressing R&D planning horizons.
- Cleanroom garment technician training pipelines:Specialized skills for conductive fiber handling and contamination-controlled manufacturing face scarcity, constraining production scaling for qualified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Safety Clothing Market |
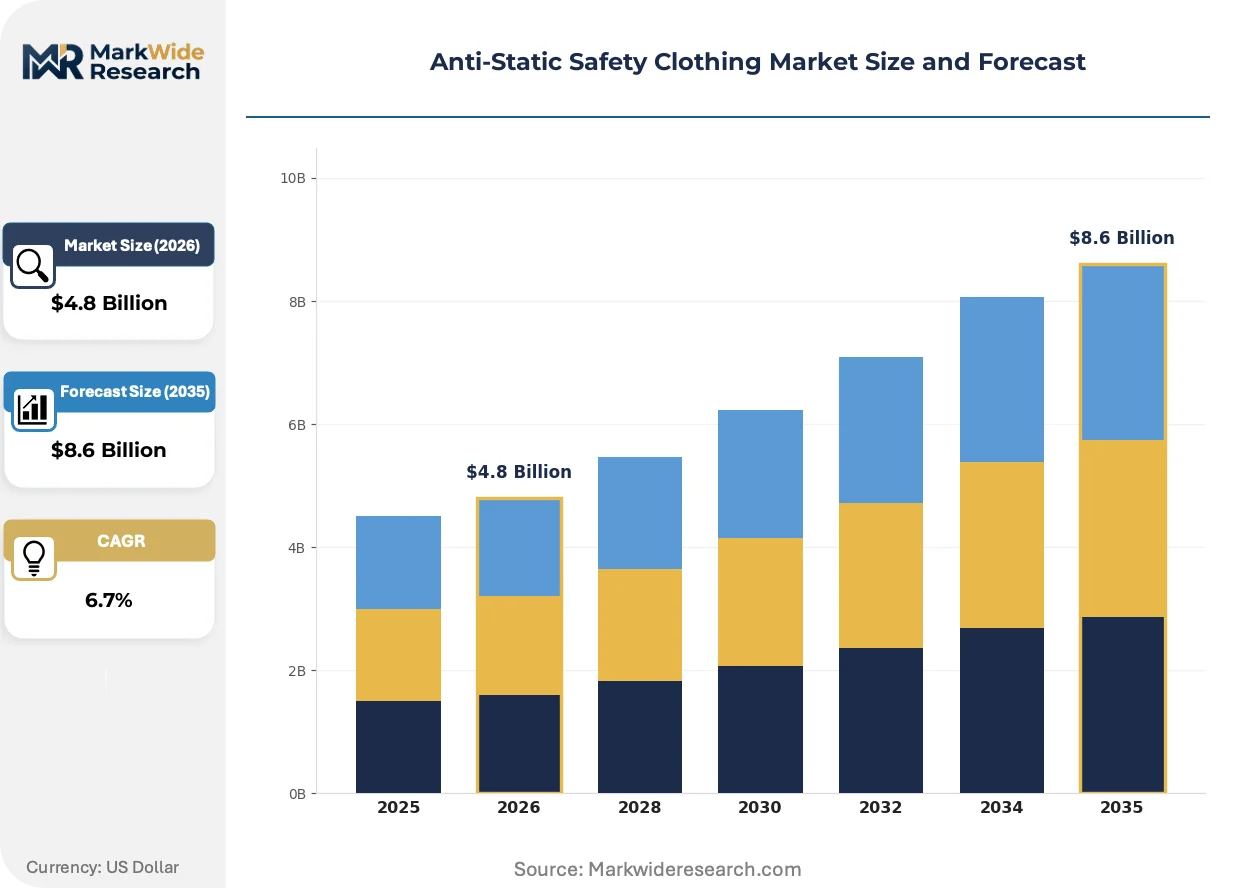
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Jackets, Trousers, Gloves Material: Polyester, Cotton, Nylon, Blends Application: Electronics Manufacturing, Oil & Gas, Pharmaceuticals, Aerospace End User: Manufacturing, Healthcare, Telecommunications, Utilities |
| Companies Covered | DuPont de Nemours, Inc., 3M Company, Teijin Limited, Ansell Limited, Lakeland Industries, Inc., Sioen Industries NV, TenCate Protective Fabrics, Protective Industrial Products, Inc., W. L. Gore & Associates, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Safety Clothing Market Trends and Innovations
Wearable electronics integration and sustainable material transitions are compressing product development cycles while regulatory fragmentation is forcing multi-jurisdictional certification strategies.
Intrinsic conductive polymer weaving is miniaturizing carbon particle dispersion within base fabrics, achieving consistent surface resistivity without compromising textile hand-feel. Semiconductor wafer handling facilities in Taiwan and South Korea are adopting these materials at accelerated replacement cycles. This technology is miniaturizing the trade-off between electrostatic protection and operator comfort, compressing differentiation windows for legacy topical treatment suppliers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating durable water-repellent chemistries previously standard in cleanroom coverall finishing. European pharmaceutical manufacturers must reformulate garment surface treatments or source alternative fluorine-free technologies by compliance deadlines. Electronics manufacturing cleanrooms in Germany and the Netherlands are most affected, accelerating qualification of silicone-based and hydrocarbon repellent substitutes.
Bundled service contracts combining garment supply with cleanroom laundering and lifecycle tracking are displacing transactional procurement in high-volume electronics manufacturing. Taiwan-based semiconductor foundries and South Korean memory chip producers are consolidating vendor relationships around full-service providers. This restructuring is most visible in East Asian electronics clusters where procurement teams prioritize total cost of ownership over unit price in supplier selection criteria.
Anti-Static Safety Clothing Market Segmentation
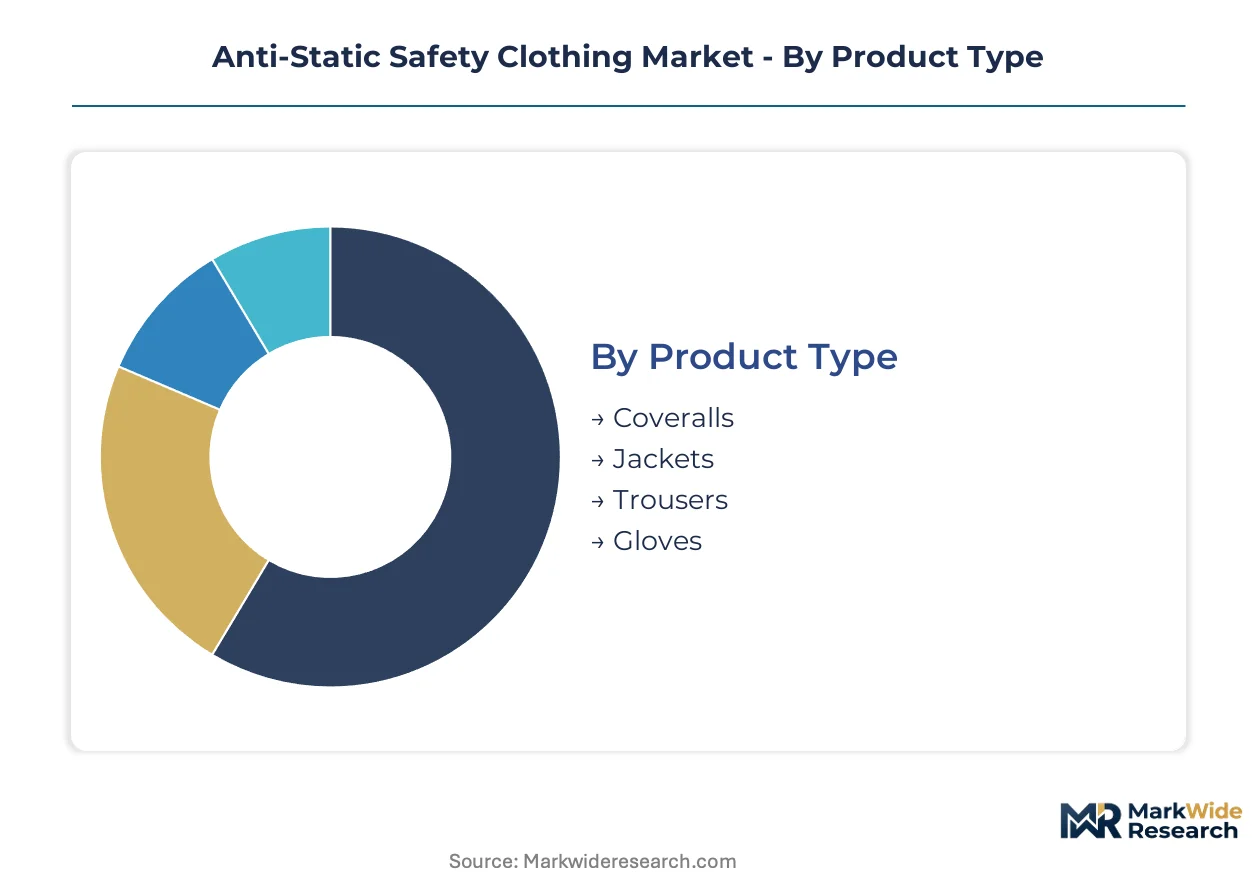
Anti-static safety clothing procurement patterns diverge sharply across product categories, driven by cleanroom grade specifications and replacement cycle economics. Material selection and end-use requirements create tiered compliance obligations that fragment supplier qualification pathways.
Product Type:
CE marking under EU PPE Regulation (EU) 2016/425 and China's GB 12014-2019 impose divergent testing protocols on each garment category, forcing manufacturers to maintain parallel certification portfolios.
- Coveralls:Full-body encapsulation garments incorporate carbon-suffused conductive yarns woven through shuttleless looms to achieve surface resistivity between 10^5 and 10^11 ohms per square. Taiwan and South Korean semiconductor foundries drive volume procurement as wafer fabrication capacity expands, with Class 100 cleanroom specifications mandating frequent replacement cycles.
- Gloves:Precision-dexterity designs utilize ultra-high molecular weight polyethylene fibers to minimize particle shedding during semiconductor wafer handling. Disproportionate margin pools concentrate here due to contamination sensitivity and daily replacement requirements in electronics manufacturing cleanrooms.
- Jackets:Upper-body protection for explosive atmosphere operations in petrochemical facilities combines flame-resistant aramid bases with conductive surface treatments.
- Trousers:Lower-body garments serve electric power generation under OSHA 29 CFR 1910.269, pairing anti-static properties with arc-flash protection.
Established volume favors coveralls; emerging adoption favors gloves.
Material:
Cost tiers stratify around fiber input economics and laundering durability, with premium conductive blends commanding three-to-five-year service lifecycles against single-use disposables.
- Polyester:Synthetic base fabrics dominate electronics manufacturing through carbon particle integration achieving consistent charge decay rates. Taiwan cleanroom laundries prefer polyester for chemical resistance during industrial washing protocols.
- Blends:Nylon-cotton combinations are gaining preference in aerospace electronics production for moisture management during extended wear scenarios. Satellite and defense manufacturing scaling in the United States and Europe drives steepest expansion trajectory for this material category.
- Cotton:Natural fiber bases require topical anti-static agent finishing to meet IEC 61340-5-1 thresholds, limiting reuse cycles.
- Nylon:High-tenacity synthetic serves explosive atmosphere applications where durability under mechanical stress is prioritized.
Polyester anchors current procurement volumes; blend formulations capture premium expansion.
Application:
Customer type segmentation reveals divergent specification intensity, with pharmaceutical compounding demanding integrated respiratory-body protection bundles against electronics assembly's garment-focused procurement.
- Electronics Manufacturing:Semiconductor fabrication facilities in Taiwan, South Korea, and the United States constitute the largest addressable segment, with cleanroom apparel procurement tightening as chip production capacity rises. ESD damage costs drive protective clothing investment across memory chip and logic foundry operations.
- Aerospace:Satellite and defense electronics production scaling creates fastest-growing demand segment, with extended wear scenarios favoring moisture-managing material formulations over pure synthetics.
- Pharmaceuticals:Compounding operations under EU GMP Annex 1 require anti-static garments integrated with chemical-resistant respiratory systems.
- Oil & Gas:Explosive atmosphere operations mandate flame-resistant anti-static combinations under ATEX directives and OSHA process safety management.
Electronics manufacturing commands procurement scale; aerospace applications gain share fastest.
End User:
Supply concentration in East Asian electronics clusters creates volume anchors that amortize R&D costs, while emerging manufacturing regions face capital-intensive cleanroom laundry infrastructure gaps.
- Manufacturing:Electronics and semiconductor production facilities concentrate demand in Taiwan, South Korea, and China cleanroom corridors. Bundled service contracts combining garment supply with lifecycle tracking are displacing transactional procurement.
- Healthcare:Pharmaceutical manufacturing and compounding operations under FDA and EMA oversight require anti-static apparel for sterile processing environments.
- Telecommunications:Network equipment assembly and data center maintenance drives moderate-volume procurement for electrostatic protected areas.
- Utilities:Electric power generation under OSHA 29 CFR 1910.269 mandates flame-resistant anti-static apparel for transmission and distribution work.
Manufacturing dominates procurement volume; healthcare represents emerging specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by geography. Taiwanese and South Korean semiconductor foundries prioritize performance over unit cost, while Indian and Southeast Asian emerging manufacturers face capital constraints that compress procurement budgets.
Taiwan
TSMC and United Microelectronics Corporation are expanding 3nm and 2nm fabrication capacity, driving cleanroom apparel procurement volumes. The Industrial Development Bureau enforces semiconductor facility standards that mandate IEC 61340-5-1 compliant garments. Hsinchu Science Park and Tainan Science Park concentrate the densest cluster of wafer fabrication plants globally.
South Korea
Samsung Electronics and SK Hynix are scaling memory chip production, requiring Class 100 cleanroom specifications for anti-static coveralls. The Ministry of Employment and Labor administers occupational safety standards that align with international electrostatic protection protocols. Pyeongtaek and Icheon host the largest memory semiconductor manufacturing complexes.
United States
Intel, Micron, and Texas Instruments are reshoring advanced logic and memory fabrication under CHIPS Act incentives. OSHA enforces 29 CFR 1910.269 for flame-resistant anti-static apparel in electric power generation alongside semiconductor cleanroom requirements. Arizona, Texas, and Ohio are attracting multi-billion dollar fab investments with bundled cleanroom infrastructure.
China
Domestic semiconductor self-sufficiency targets under the 14th Five-Year Plan are expanding cleanroom garment demand despite export control constraints. SAMR administers GB 12014-2019 certification for anti-static workwear, creating divergent testing protocols from EU standards. Yangtze River Delta and Pearl River Delta electronics manufacturing clusters concentrate procurement volumes.
Germany
Bosch, Infineon, and automotive electronics suppliers are scaling semiconductor production for electric vehicle powertrains. The EU PPE Regulation (EU) 2016/425 mandates CE marking with Module B+C2 conformity assessment for Category III electrostatic risk garments. Dresden and Munich anchor the silicon Saxony and Bavarian semiconductor ecosystems.
Anti-Static Safety Clothing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium material innovators concentrate in Japan, the United States, and Europe, while garment assemblers compete on scale and regional logistics in Asia. The market organizes around three strategic archetypes: integrated material-to-garment specialists, focused fabricators with captive fiber supply, and regional contract manufacturers serving price-sensitive procurement. Dominant competitive moves include backward integration into conductive fiber production and geographic expansion through distribution partnerships in emerging semiconductor manufacturing regions.
Among integrated material specialists, DuPont de Nemours, Inc. and Teijin Limited occupy positions that exemplify the premium-tier archetype through captive control over aramid and ultra-high molecular weight polyethylene fiber platforms. 3M Company represents the systems-integration archetype, bundling respiratory and body protection capabilities that address pharmaceutical and electronics manufacturing demand simultaneously. These three companies anchor the technology-intensive segment where certification breadth and material science capabilities determine competitive position.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| 3M Company |
| Teijin Limited |
| Ansell Limited |
| Lakeland Industries, Inc. |
| Sioen Industries NV |
| TenCate Protective Fabrics |
| Protective Industrial Products, Inc. |
| W. L. Gore & Associates, Inc. |
| Others |
Pricing and Supply Chain Analysis
EU PPE Regulation (EU) 2016/425 and China's GB 12014-2019 simultaneously gate supplier qualification and stratify price tiers across the anti-static safety clothing market, forcing manufacturers to absorb parallel certification costs while buyers segment procurement budgets by compliance grade and regional delivery requirements.
Pricing Analysis
After-sales service contracts combining garment supply with cleanroom laundering and lifecycle tracking now drive lifetime value more than unit sales, with three-tier pricing structure across premium, standard, and economy levels anchored by certification breadth and fiber technology. Price differentiation hinges on IEC 61340-5-1 compliance grade and carbon-suffused yarn integration density, while cost compression in economy tiers intensifies because mid-tier assemblers lack backward integration into conductive fiber production. Semiconductor foundries in Taiwan and South Korea demonstrate least price sensitivity, prioritizing contamination control over procurement cost, whereas emerging Indian manufacturers under PLI scheme incentives face capital constraints that compress apparel budgets toward standard-tier suppliers.
Supply Chain Analysis
Para-aramid fiber supply concentration in Japan and the United States underwrites input cost volatility for garment assemblers without captive fiber platforms, with DuPont and Teijin controlling upstream material flows that downstream manufacturers must negotiate. Raw material dependencies center on carbon-suffused conductive yarns, ultra-high molecular weight polyethylene fibers, and topical anti-static finishing agents, with single-source vulnerability concentrated in aramid supply chains where alternative qualified suppliers remain limited. Distribution runs through certified cleanroom laundry networks concentrated in developed economies, creating service gaps in emerging semiconductor manufacturing regions that transactional garment suppliers cannot address without local laundering partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication capacity expansion across Taiwan, South Korea, and the United States signals cyclical recovery in cleanroom apparel procurement, with chip production reshoring under CHIPS Act incentives and comparable industrial policies creating sustained demand visibility for certified suppliers.
For Market Incumbents: Fortify certification portfolios against pending IEC 61340-5-1 standard revisions by accelerating material reformulation investments in intrinsic conductive polymer weaving, while deepening backward integration into carbon-suffused yarn production to offset aramid supply concentration risks from Teijin and DuPont. Channel control through exclusive cleanroom laundry partnerships in Arizona, Texas, and Ohio defends margin position against regional contract manufacturers entering under CHIPS Act infrastructure buildouts. For New Entrants and Emerging Players: Lead with India's PLI scheme for semiconductors as the most penetrable geography, where cleanroom infrastructure investment is accelerating but certified apparel supplier density remains thin compared to East Asian electronics clusters. Target pharmaceutical compounding operations in Europe with integrated respiratory-body protection bundles, leveraging REACH fluorine-free reformulation deadlines to displace incumbent suppliers dependent on legacy durable water-repellent chemistries. For Investors and Strategic Acquirers: IEC 61340-5-1 standard revision timelines reshape the acquisition landscape by compressing R&D planning horizons and favoring targets with demonstrated conductive fiber handling capabilities and existing multi-jurisdictional certification breadth. Long-term viability across the five-to-ten year window rests on positioning within aerospace electronics manufacturing, where satellite and defense production scaling creates fastest-growing demand segment for moisture-managing nylon-cotton blends. Monitor India's semiconductor fab construction permits as inflection indicator for cleanroom apparel procurement acceleration in underpenetrated South Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Fiber Production | Captive carbon-suffused yarn supply insulates margin pressure from Teijin and DuPont aramid concentration. |
| Multi-Jurisdictional Certification Investment | Parallel EU Module B+C2 and China GB 12014-2019 qualification opens procurement access to TSMC and Samsung foundries. |
| Integrated Service Contract Bundling | Garment-plus-laundry lifecycle tracking displaces transactional procurement at Taiwan semiconductor foundries prioritizing total cost of ownership. |
| Fluorine-Free Surface Treatment Reformulation | Silicone-based repellent qualification ahead of REACH deadlines secures European pharmaceutical manufacturer relationships. |
| Aerospace Electronics Manufacturing Expansion | Nylon-cotton blend development for satellite production addresses fastest-growing demand segment in United States and Europe. |
Research Methodology
The analysis maps coveralls, gloves, jackets, and trousers as product categories alongside polyester, blends, cotton, and nylon material segments, each validated through procurement directors at semiconductor foundries, cleanroom laundry operators, regulatory compliance officers, and conductive fiber R&D leads, combining primary interviews with secondary validation from IEC standard documentation, EU PPE Regulation implementation guidance, SAMR certification registries, and OSHA enforcement data, with bottom-up and top-down triangulation across manufacturer shipment records and end-user procurement databases.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling product type, material composition, application intensity, and end-user procurement scale as segmentation dimensions, deriving CAGRs from semiconductor fabrication capacity expansion trajectories and cleanroom apparel replacement cycle economics, incorporating carbon-suffused yarn adoption rates and Class 100 specification upgrade frequencies as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU PPE Regulation (EU) 2016/425, China GB 12014-2019, and OSHA 29 CFR 1910.269 enforcement regimes; material policy shifts in electrostatic protection thresholds or REACH substance restrictions would require re-modeling. Practitioners should keep alternative scenarios live as IEC 61340-5-1 revision timelines and India PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market