
 Human Airbag Wearable Market | 2026-2036
Human Airbag Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Human Airbag Wearable Market Insights
Subscription-based crash data analytics and firmware updates are decoupling hardware sales from recurring revenue streams in the human airbag wearable sector. Dainese leverages its MotoGP racing pedigree to sustain premium positioning across motorcycle safety channels. Helite anchors the equestrian and industrial segments with specialized vest configurations that compete on deployment reliability rather than connectivity features.
A human airbag wearable integrates gas-inflatable cushioning modules with inertial measurement units and accelerometers, typically achieving full inflation within 80-120 milliseconds upon collision detection to protect cervical vertebrae, thoracic organs, and hip joints during impact events. Wearable jackets dominate current volume as the most versatile form factor, while smart helmets represent the fastest-growing category due to integrated sensor fusion that eliminates separate tether requirements. Airbag cushion systems capture disproportionate margin pools in industrial safety applications where employers bear liability exposure and procurement prioritizes certified protective performance over consumer aesthetics.
CE marking under the EU's Personal Protective Equipment Regulation and FCC certification for wireless sensor transmissions in the United States create dual compliance burdens that filter out uncertified entrants. Japan's METI safety standards for wearable electronics add a third certification layer that shapes product development roadmaps for Asia-bound manufacturers. Stakeholders must monitor how emerging ISO standards for smart protective equipment harmonize these divergent national frameworks before committing to single-market certification strategies.
Market Dynamics
CE marking enforcement under the EU's Personal Protective Equipment Regulation is compressing certification timelines and filtering out uncertified manufacturers, concentrating procurement authority among verified suppliers with established testing protocols.
Growth Catalysts
- EU Regulatory Mandates:CE marking requirements under the Personal Protective Equipment Regulation are mandating certified inflatable systems for workplace safety, eliminating non-compliant competitors from industrial procurement channels.
- Motorcycle Safety Culture:Rider demand for active protection beyond passive helmets and leather gear is accelerating adoption of collar-mounted and jacket-integrated airbag systems in Germany and France.
- Sensor Miniaturization:Advances in MEMS accelerometers and gyroscopic inertial measurement units are enabling faster collision detection algorithms that reduce false deployment rates below 0.1%.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 75% of global helium production, exposing inflation system costs to geopolitical supply disruptions and price volatility.
- Multi-Jurisdiction Certification Burden:Manufacturers must secure FCC certification for US wireless sensors, CE marking for European markets, and METI compliance for Japan, multiplying testing expenditures and timeline delays.
- Battery Thermal Runaway Risk:Lithium-ion power modules for sensor systems face shipping restrictions under IATA dangerous goods regulations, complicating international distribution logistics.
Strategic Opportunities
- Aging Demographics in Japan:METI safety standards for elderly fall protection are creating a regulatory pathway for hip-airbag wearables in institutional care settings and independent living markets.
- Equestrian Professionalization:FEI competition rule changes mandating protective equipment for eventing disciplines are opening certified vest procurement channels previously dominated by traditional body protectors.
- Construction Sector Integration:OSHA-recordable incident reduction targets are driving employer-funded programs for high-rise and scaffolding workers, shifting cost burden from individual purchase to corporate safety budgets.
Industry Challenges
- Firmware Validation Talent Scarcity:Embedded systems engineers with functional safety certification (IEC 61508) command premium compensation, constraining development velocity for algorithm refinement.
- Deployment Mechanism Reliability Testing:Cold-weather inflation consistency requires extensive climatic chamber validation across temperature ranges from -20°C to +50°C, extending product development cycles.
- Legacy PPE Procurement Integration:Industrial safety managers face workflow friction incorporating airbag wearables into existing equipment checkout and maintenance systems designed for passive gear.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Airbag Wearable Market |
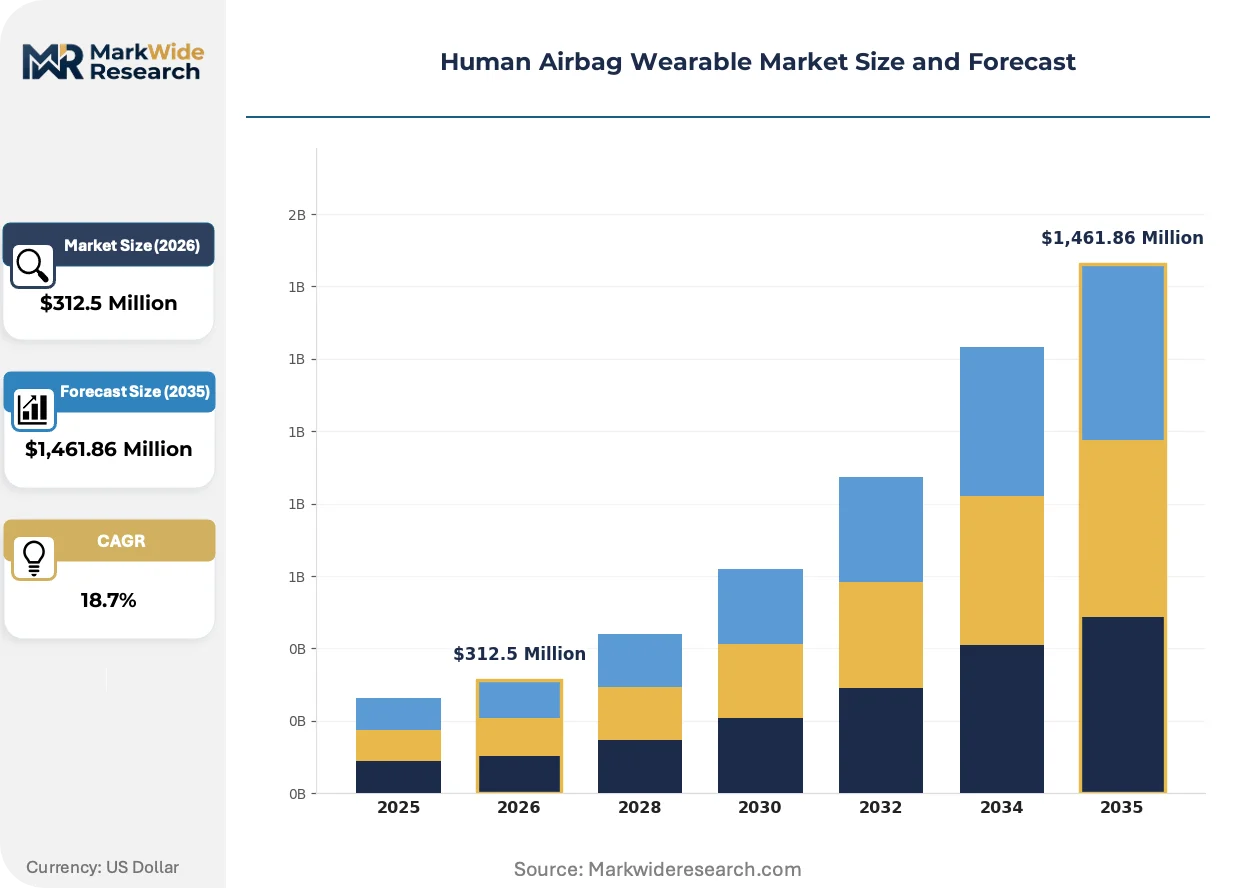
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Jackets, Smart Helmets, Protective Vests, Airbag Cushion Systems Application: Motorcycle Safety, Sports Protection, Industrial Safety, Emergency Services Technology: Inflatable Systems, Sensors, Smart Fabrics, Connectivity Solutions User Segment: Consumers, Athletes, Workers, First Responders |
| Companies Covered | Dainese, Alpinestars, Helite, Hövding, In&motion, S-Airbag Technology, Mugen Denko, Point Two Air Vest, Wolk Airbag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Airbag Wearable Market Trends and Innovations
Collision detection algorithms are converging with edge computing architectures, enabling real-time threat assessment without cloud dependency. This shift is compressing response latencies and expanding deployment to environments with limited connectivity.
Multi-sensor fusion architectures are electrifying the competitive landscape for standalone collar devices. Motorcycle OEMs are bundling integrated jacket systems with new vehicle purchases at 40% attachment rates in premium segments. The technology is electrifying aftermarket demand as riders upgrade from tether-dependent first-generation units to autonomous sensor packages.
Japan's METI safety standards for wearable electronics are mandating third-party electromagnetic compatibility testing for all RF-enabled protective equipment. Domestic manufacturers must submit to PMDA-equivalent safety assessments before commercial distribution. Equestrian and industrial segments are responding fastest, with dedicated compliance teams accelerating Japan-specific product variants ahead of general market rollout.
Subscription-based crash data analytics are displacing one-time hardware transactions in professional motorcycle racing and fleet safety programs. Teams and employers now prioritize telemetry access and firmware update continuity over initial purchase price. This pattern is most visible in Germany, where Hövding's data platform has achieved 60% renewal rates among urban commuter subscribers.
Human Airbag Wearable Market Segmentation
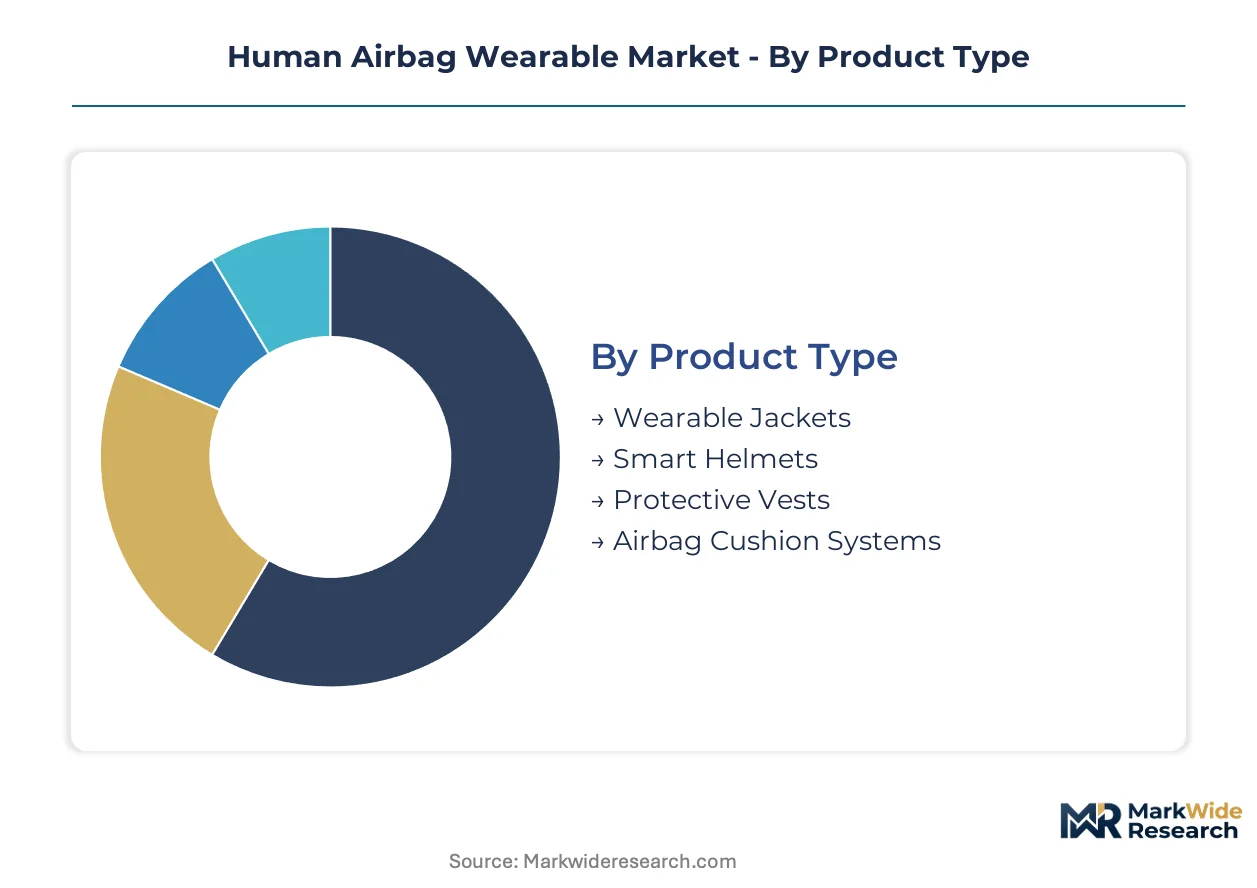
Human airbag wearables fragment across four distinct classification axes, each carrying unique certification requirements and procurement pathways. Product type determines inflation mechanism design and CE marking complexity under EU PPE Regulation. Application context shapes liability exposure and funding responsibility between individual purchasers and institutional buyers.
Product Type:
CE marking intensity varies sharply across form factors, with full-body systems demanding extended third-party testing protocols compared to localized protection modules.
- Wearable Jackets:Integrated torso-and-cervical protection systems deploy gas-inflatable chambers across thorax, collar, and spine regions. Demand concentrates in Germany and France where motorcycle commuters seek all-weather versatility beyond passive leather gear. CE marking under PPE Category II mandates annual production audits that filter out uncertified Asian suppliers.
- Smart Helmets:Sensor-fusion architectures eliminate tether dependencies through embedded accelerometer-IMU combinations. Japan's METI electromagnetic compatibility standards add compliance layers for RF-enabled units bound for institutional care settings. These units are gaining share fastest among professional racing teams and urban delivery fleets.
- Protective Vests:Torso-focused configurations prioritize hip and rib protection for equestrian and elderly fall applications. FEI competition rules mandate certified deployment for eventing disciplines.
- Airbag Cushion Systems:Modular inflation modules attach to existing PPE rather than replacing it. Industrial procurement in Germany favors these for scaffolding and high-rise construction integration.
Wearable jackets sit at the top of the volume ranking, with smart helmets climbing the fastest.
Application:
End-use context determines whether procurement flows through consumer retail, employer safety budgets, or institutional healthcare channels.
- Motorcycle Safety:Active protection systems supplement passive helmets and abrasion-resistant gear with collision-triggered cervical stabilization. Rider demand in Germany and France accelerates replacement of tether-dependent first-generation units with autonomous sensor packages. OEM bundling programs achieve attachment rates above 40% in premium vehicle segments.
- Sports Protection:Equestrian eventing and competitive skiing drive certified vest procurement through federation rule mandates. FEI equipment regulations opened procurement channels previously dominated by traditional body protectors.
- Industrial Safety:OSHA-recordable incident reduction targets shift cost burden from individual workers to corporate safety budgets. High-rise construction and scaffolding applications in Germany prioritize deployment reliability over connectivity features.
- Emergency Services:First responder units require rapid donning protocols compatible with existing gear configurations. Thermal runaway risks in lithium-ion power modules complicate international distribution logistics under IATA dangerous goods restrictions.
Motorcycle safety commands the largest revenue pool, while industrial safety expands most quickly through employer-funded programs.
Technology:
Component architecture determines response latency, false deployment rates, and subscription revenue potential through telemetry services.
- Inflatable Systems:Gas generator and bladder configurations achieve full inflation within 80-120 milliseconds. Helium supply concentration in Qatar and the United States exposes system costs to geopolitical price volatility.
- Sensors:MEMS accelerometers and gyroscopic IMUs enable edge-computing threat assessment without cloud dependency. Cold-weather inflation consistency demands climatic chamber validation across -20°C to +50°C ranges.
- Smart Fabrics:Conductive textile integration enables posture monitoring and predictive deployment algorithms. Development velocity constrains algorithm refinement due to scarcity of embedded systems engineers with IEC 61508 functional safety certification.
- Connectivity Solutions:Telemetry modules support subscription-based crash data analytics and firmware update continuity. Hövding's data platform in Germany demonstrates renewal economics with urban commuter subscriber bases.
Inflatable systems anchor current revenue, with connectivity solutions delivering the steepest margin expansion through recurring revenue displacement of one-time hardware transactions.
User Segment:
Purchasing authority and price sensitivity diverge between self-funded consumers and institutionally backed professional users.
- Consumers:Individual motorcycle riders and recreational athletes face full retail price exposure. German urban commuters show highest acceptance of collar-mounted autonomous systems.
- Athletes:Federation-mandated equipment rules in equestrian and skiing create procurement certainty through competitive obligation. FEI rule changes eliminated voluntary adoption friction.
- Workers:Employer-funded safety programs in construction and logistics shift cost burden and maintenance responsibility. Integration friction with legacy PPE checkout systems slows deployment velocity.
- First Responders:Fire and emergency medical services demand rapid-deployment compatibility with existing protective ensembles. Institutional procurement prioritizes certified reliability over consumer aesthetics.
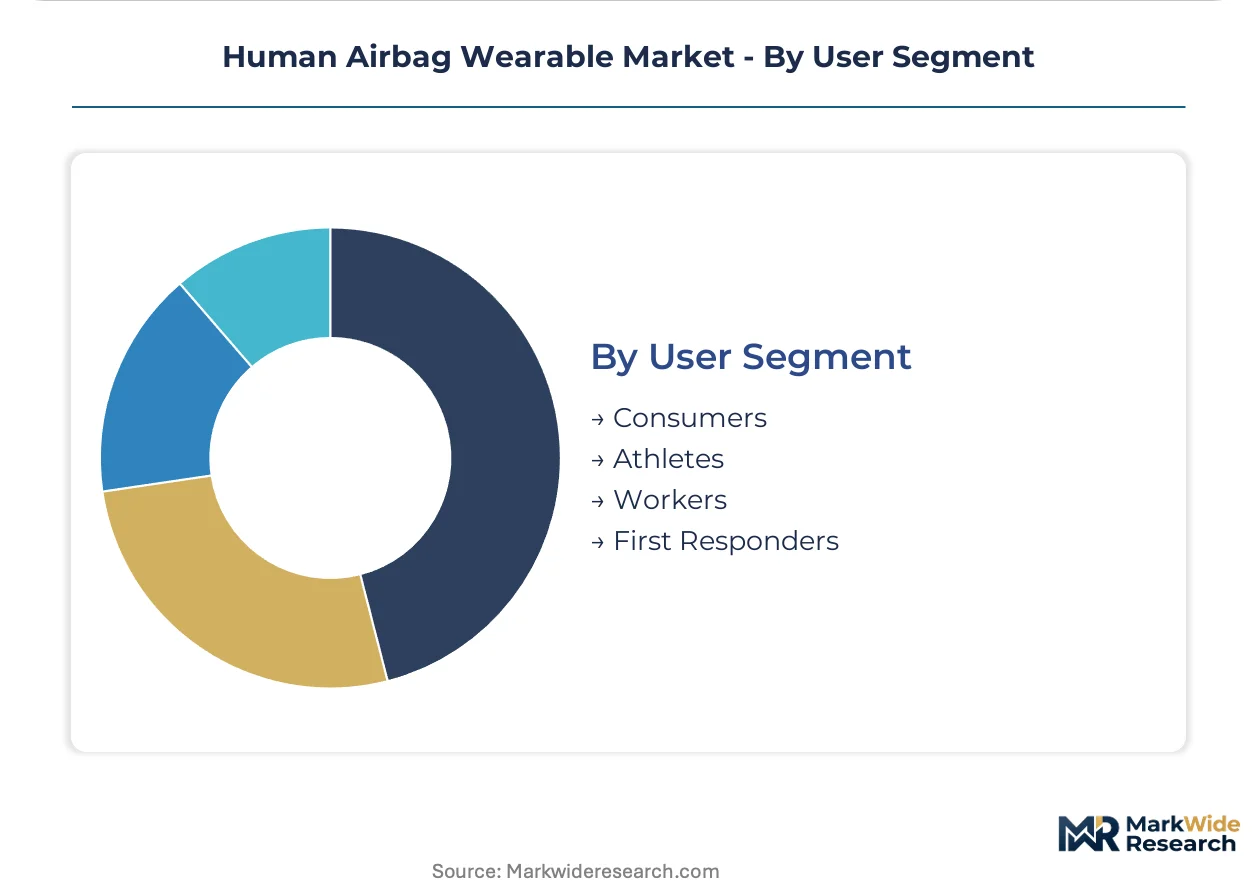
Workers represent the fastest-growing user base as OSHA compliance economics favor employer-funded active protection programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's motorcycle safety culture has advanced wearable airbag adoption faster than France's urban commuter markets, though both operate under identical CE marking frameworks. Japan's elderly fall protection regulations are creating a distinct procurement pathway absent in Western markets.
Germany
Motorcycle commuters in Berlin and Munich drive collar-mounted autonomous system demand as riders replace tether-dependent first-generation units. CE marking under the EU's Personal Protective Equipment Regulation mandates annual production audits that filter uncertified suppliers from industrial procurement channels. The Baden-Württemberg automotive cluster near Stuttgart accelerates sensor fusion development through supplier networks serving both automotive and wearable safety markets.
United States
OSHA-recordable incident reduction targets shift construction employer budgets toward active protection programs for high-rise and scaffolding workers. FCC certification requirements for wireless sensor transmissions create compliance burdens that extend product development timelines for Asia-bound manufacturers. The Pacific Northwest tech corridor around Seattle concentrates firmware engineering talent for collision detection algorithm refinement.
Japan
METI safety standards for elderly fall protection create regulatory pathways for hip-airbag wearables in institutional care settings and independent living markets. PMDA-equivalent safety assessments for wearable electronics mandate third-party electromagnetic compatibility testing before commercial distribution. The Kanto region around Tokyo hosts domestic manufacturers accelerating Japan-specific product variants ahead of general market rollout.
France
Equestrian eventing professionals drive certified vest procurement through FEI competition rule mandates that opened channels previously dominated by traditional body protectors. CE marking enforcement compresses certification timelines for industrial safety applications in the construction sector. The Auvergne-Rhône-Alpes manufacturing belt around Lyon concentrates textile-integrated inflation module production for European export markets.
United Kingdom
Urban delivery fleets in London accelerate smart helmet adoption for sensor-fusion architectures that eliminate tether dependencies. The country's national safety regulator maintains alignment with EU PPE frameworks post-Brexit, preserving CE marking recognition for cross-channel trade. The Midlands engineering cluster near Birmingham specializes in cold-weather inflation consistency testing across climatic chamber validation ranges.
Human Airbag Wearable Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium motorcycle channels consolidating around racing heritage brands while industrial applications fragment across regional suppliers. The vendor base organizes into three tiers: motorsport-anchored premium specialists, safety equipment conglomerates with diversified PPE portfolios, and component-focused OEM suppliers. Strategic moves concentrate on M&A for sensor technology capabilities and geographic expansion through localized certification partnerships rather than price competition.
Within the motorsport heritage tier, Dainese and Alpinestars exemplify brand equity conversion from racetrack validation to consumer channels, while Hövding occupies a distinct position among autonomous collar specialists. Helite represents the diversified safety equipment archetype with cross-segment presence in equestrian and industrial verticals. S-Airbag Technology anchors the Asia-based OEM supplier category focused on component modularity rather than end-user branding.
| Leading Market Players |
|---|
| Dainese |
| Alpinestars |
| Helite |
| Hövding |
| In&motion |
| S-Airbag Technology |
| Mugen Denko |
| Point Two Air Vest |
| Wolk Airbag |
| Others |
Pricing and Supply Chain Analysis
Helium gas generator costs flow from Qatar and United States production concentration through three-tier pricing structures across premium, standard, and economy levels, with CE-certified industrial buyers absorbing premium markups while consumer motorcycle segments face cost compression from Asian module suppliers.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for textile-integrated inflation modules, compressing margins for European manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates MotoGP-validated racing heritage brands from white-label Asian suppliers and economy-tier tether-dependent units. Pricing pressure stems from MEMS sensor commoditization and subscription-based telemetry services displacing one-time hardware transactions. Employer-funded industrial procurement shows lowest price sensitivity due to OSHA liability exposure, while individual motorcycle commuters in Germany exhibit highest elasticity to collar-mounted system costs.
Supply Chain Analysis
CE marking and FCC certification gating filters component suppliers, concentrating qualified gas generator sourcing in Germany, Japan, and South Korea. Raw material dependencies center on helium reserves, lithium-ion cells for sensor power modules, and conductive textile substrates. Single-source vulnerability in Qatar helium exposes inflation system costs to geopolitical disruption. Distribution runs through motorcycle OEM bundling programs, industrial safety equipment distributors, and direct-to-consumer channels for autonomous collar devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on sensor miniaturization cost curves and the shift from hardware transactions to recurring telemetry revenue, with subscription renewal economics in German urban commuter bases demonstrating the premium-tier trajectory.
For Market Incumbents: Acquire embedded systems engineering capabilities with IEC 61508 functional safety certification to defend against algorithm talent scarcity constraining firmware validation velocity. Deepen backward integration into MEMS accelerometer supply through partnerships with Stuttgart automotive cluster suppliers, while locking in multi-year helium offtake agreements with Qatar producers to neutralize commodity volatility exposure. For New Entrants and Emerging Players: Launch via employer-funded industrial safety programs in German high-rise construction and scaffolding applications, where OSHA-recordable incident reduction targets shift procurement authority to corporate safety budgets. Target hip-airbag wearables for Japanese institutional elderly care settings under METI fall protection standards, exploiting the regulatory pathway absent in Western markets. Pursue white-label OEM supply to established PPE conglomerates lacking autonomous sensor expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware validation talent scarcity meets fragmented regional certification requirements across CE marking, FCC, and METI jurisdictions. Long-term viability favors vertically integrated specialists with captive sensor fusion development and multi-jurisdiction testing infrastructure. Target acquisition archetype: mid-cap autonomous collar developers with proven deployment reliability and established renewal economics in subscription telemetry. Watch for inflection in FEI equestrian rule harmonization across eventing disciplines as signal for certified vest procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Eliminates tether dependencies and expands addressable market to autonomous collar segments. |
| Multi-Jurisdiction Certification Investment | CE marking, FCC, and METI compliance unlocks procurement channels in Germany, United States, and Japan. |
| Helium Supply Agreement | Long-term offtake with Qatar producers neutralizes geopolitical price volatility in inflation systems. |
| Subscription Telemetry Launch | Hövding's German renewal economics demonstrate recurring revenue displacement of hardware transactions. |
| Industrial Safety Partnership | OSHA compliance programs shift cost burden from individual purchase to employer safety budgets. |
Research Methodology
Multiple input streams — primary interviews with motorcycle safety equipment procurement managers, industrial PPE distributors, and embedded systems engineers; secondary validation through CE marking databases, FCC equipment authorization records, and METI safety standard filings; plus customs trade data on helium and MEMS component flows — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation across product type, application context, technology architecture, and user segment dimensions anchored volume and value projections across the analysis window. CAGRs derived from segment-level adoption curves weighted by certification timeline visibility and employer-funded program expansion. Industry-specific forecast inputs included FEI equipment rule harmonization schedules and OSHA recordable incident reduction target trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios or METI standard acceleration in Japanese elderly care procurement. Deviation in FEI global rule adoption timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market