
 Healthcare Personal Protective Equipment (PPE) Market | 2026-2036
Healthcare Personal Protective Equipment (PPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Personal Protective Equipment (PPE) Market Analysis
The EU Green Deal's circular economy action plan is rebalancing procurement criteria toward reusable PPE technologies with validated sterilization cycles. Ansell Limited leverages its integrated manufacturing footprint across Malaysia and Sri Lanka to sustain glove supply continuity for European hospital networks. MSA Safety Incorporated anchors its respiratory protection portfolio with NIOSH-certified industrial designs adapted for clinical emergency response. 3M Company competes through proprietary electret media technology that differentiates filtration performance across disposable mask lines.
Healthcare Personal Protective Equipment comprises garments, barriers, and respiratory devices engineered from nonwoven polypropylene, nitrile elastomers, or thermoplastic polyurethane with specified bacterial filtration efficiency thresholds exceeding 95 percent for surgical applications. These products serve primarily to interrupt pathogen transmission between healthcare workers and patients during invasive procedures, aerosol-generating events, or routine clinical contact. Gloves and masks occupy the largest volume positions within the product type dimension, though gowns command premium pricing in surgery applications where ANSI/AAMI liquid barrier ratings determine specification. Disposable technology dominates current procurement flows, yet reusable segments with validated laundering protocols are gaining traction as hospitals confront waste stream costs. End user concentration tilts toward hospitals, where centralized infection control committees standardize purchasing across emergency response and patient care applications.
FDA 510(k) clearance requirements and NIOSH respirator certification shape product development timelines and market access thresholds for manufacturers targeting United States healthcare systems. The EU MDR's strengthened clinical evidence requirements for Class I reusable devices are forcing technical file upgrades across European supply chains. OSHA bloodborne pathogen standards and CDC isolation precaution guidelines directly determine minimum PPE configurations for hospital employers. Stakeholders must monitor how divergent United States and European regulatory timelines for reusable device validation reshape competitive positioning between domestic and import suppliers.
Market Dynamics
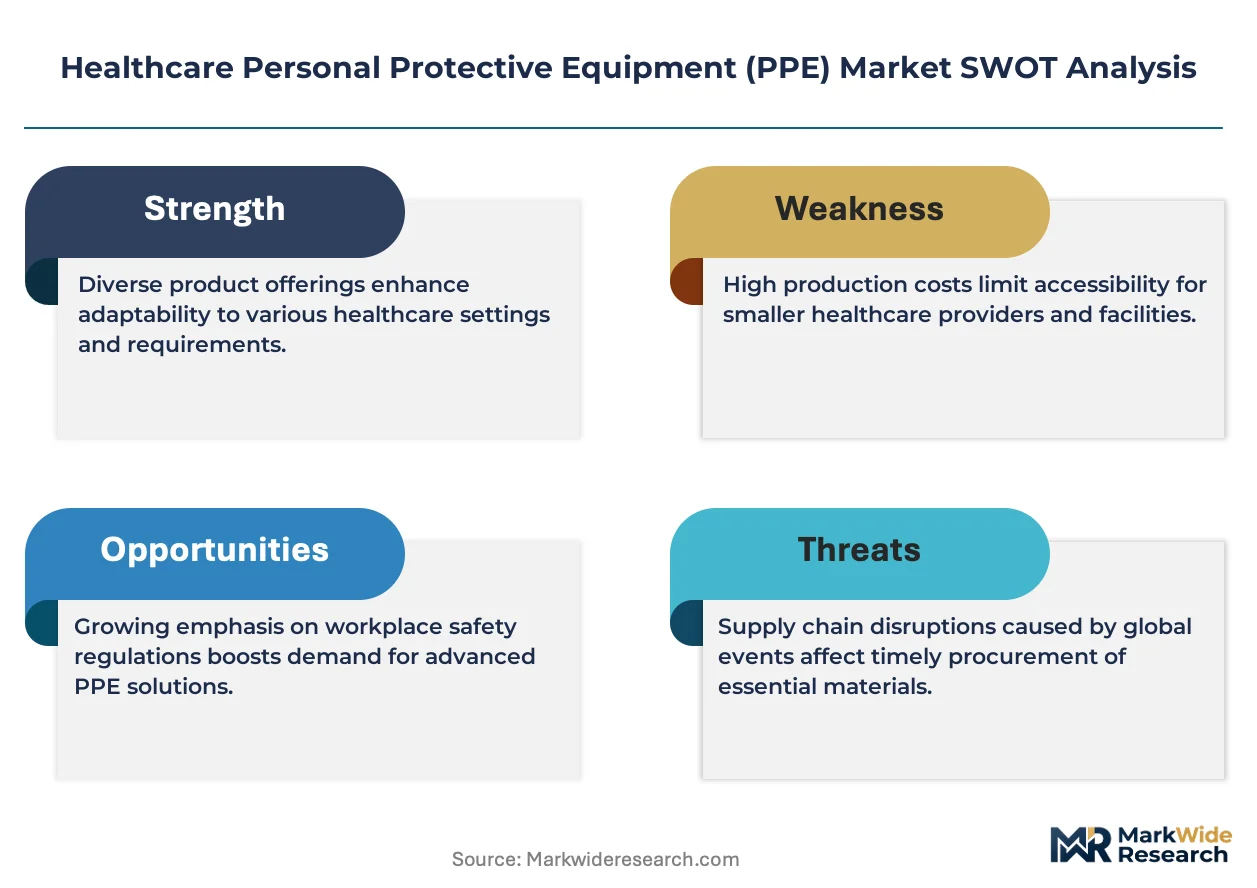
Hospital procurement departments are expanding stockpile mandates for infection control applications, while regulatory tightening around reusable PPE technologies creates parallel pressure on manufacturers to validate sterilization cycles and upgrade technical documentation.
Growth Catalysts
- EU MDR pathway expansion:Strengthened clinical evidence requirements for Class I reusable devices are accelerating technical file upgrades across European supply chains, creating demand for validated laundering protocols.
- Domestic manufacturing capacity buildouts:Germany, India, and Brazil are constructing regional production hubs to reduce import dependency for nitrile gloves and NIOSH-certified respirators.
- Nonwoven polypropylene filtration advances:Electret media technology with bacterial filtration efficiency thresholds exceeding 95 percent is penetrating surgical mask specifications.
Market Restraints
- Nitrile elastomer input volatility:Petrochemical feedstock price swings compress margin predictability for glove manufacturers with Malaysian and Sri Lankan production footprints.
- FDA 510(k) timeline friction:Extended clearance requirements for novel reusable designs delay market access for United States healthcare system suppliers.
- Single-use polymer substitution limits:Thermoplastic polyurethane alternatives face cost barriers in high-volume disposable gown applications where ANSI/AAMI liquid barrier ratings dominate.
Strategic Opportunities
- EU Green Deal circular economy mandates:Procurement criteria rebalancing toward reusable technologies with validated sterilization cycles opens technical service revenue streams.
- Brazilian ANVISA domestic production incentives:Local content requirements for hospital network tenders favor regional manufacturing investments over import-dependent models.
- Smart PPE sensor convergence:Integration of wear-time monitoring with thermoplastic polyurethane garments creates compliance documentation value for infection control committees.
Industry Challenges
- NIOSH respirator certification backlog:Testing capacity constraints extend product launch timelines for industrial designs adapted to clinical emergency response.
- Reusable laundering protocol standardization:Divergent United States and European validation timelines fragment technical development roadmaps for multi-cycle garment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Personal Protective Equipment (PPE) Market |
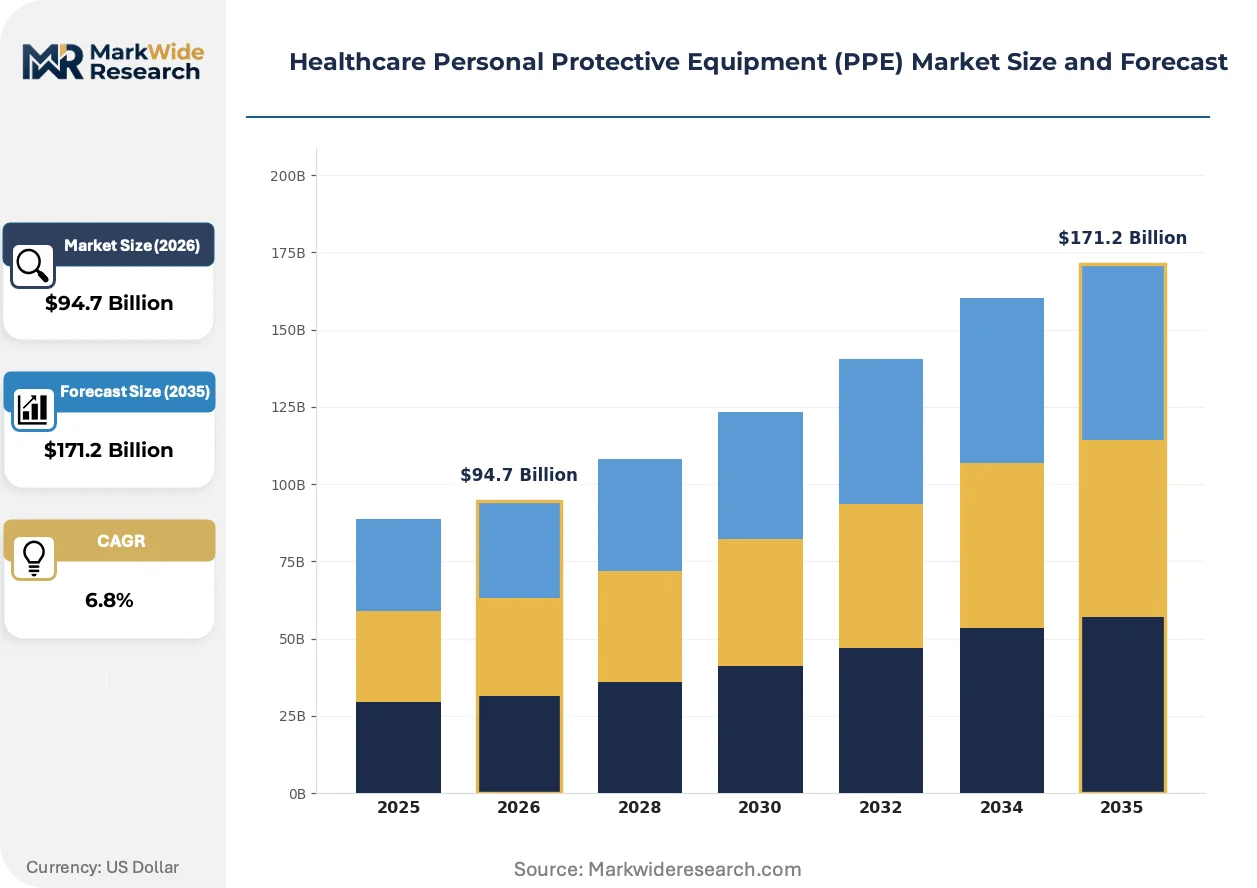
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $171.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masks, Gloves, Gowns, Face Shields Technology: Bacterial Filtration, Viral Filtration, Reusable, Disposable End User: Hospitals, Clinics, Laboratories, Nursing Homes Application: Infection Control, Surgery, Emergency Response, Patient Care |
| Companies Covered | Ansell Limited, MSA Safety Incorporated, 3M Company, Lakeland Industries, Inc., Alpha Pro Tech, Ltd., Honeywell International Inc., Kimberly-Clark Corporation, Cardinal Health, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Personal Protective Equipment (PPE) Market Emerging Trajectories
Material science advances and regulatory convergence are compressing development cycles for next-generation barrier technologies while reshaping how hospitals evaluate total cost of ownership across disposable and reusable categories.
Electret media filtration technology is consolidating performance differentiation in surgical mask lines by embedding permanent electrostatic charge into nonwoven polypropylene matrices. German hospital networks are specifying these materials for aerosol-generating procedure protection. This consolidation is compressing price competition among suppliers lacking proprietary fiber treatment capabilities.
The EU Green Deal's circular economy action plan is mandating lifecycle assessment documentation for public procurement tenders across member states. Reusable gown suppliers must now validate laundering cycle counts exceeding 50 uses to qualify for premium pricing tiers. German and French hospital purchasing consortia are rewriting technical specifications to exclude single-use alternatives where sterilization infrastructure exists.
Centralized infection control committees are consolidating purchasing authority across previously siloed emergency response and patient care departments. United States health systems are unbundling after-sales service contracts from product supply agreements. This concentration is visible most acutely in multi-hospital networks across Texas and California where standardization mandates override individual facility preferences.
Healthcare Personal Protective Equipment (PPE) Market Segmentation
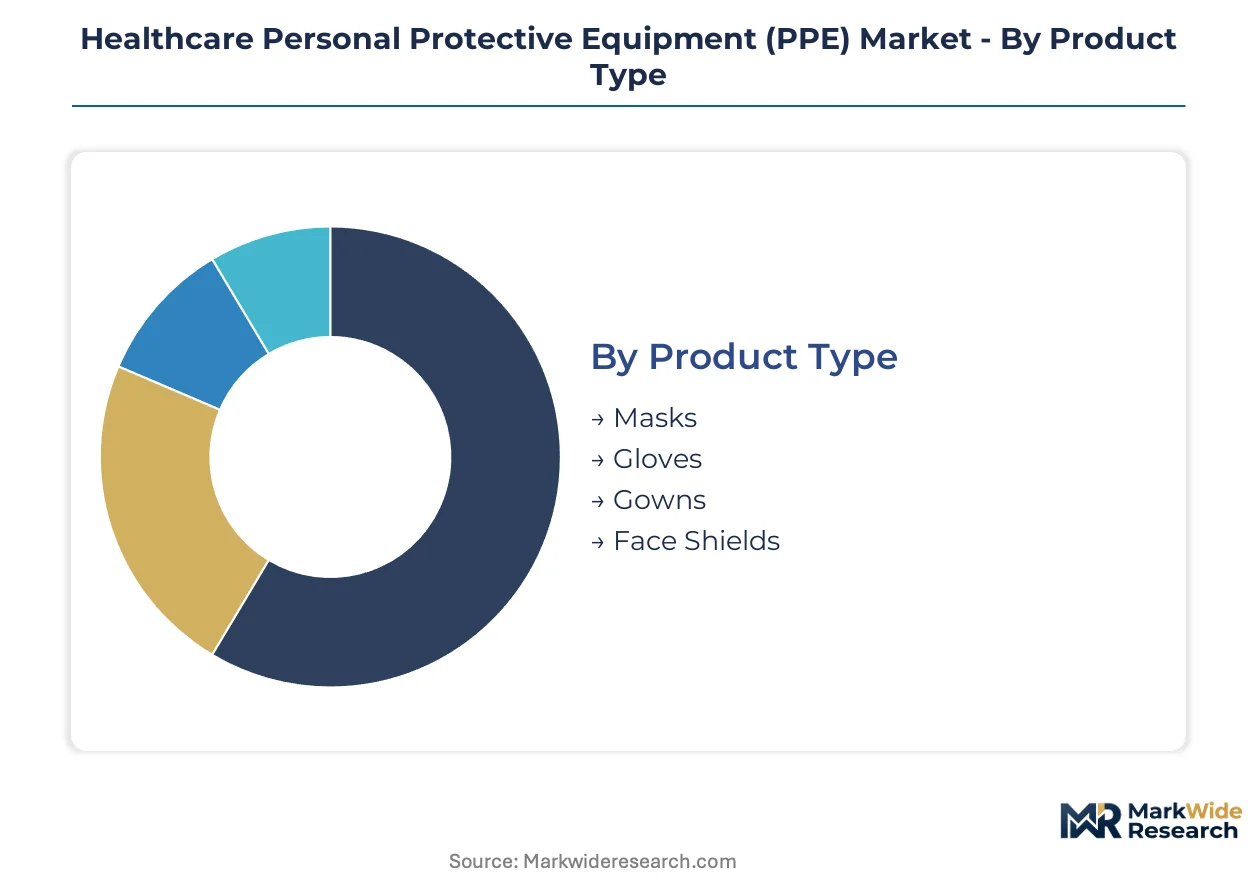
Healthcare PPE procurement committees evaluate segments through distinct lenses: standalone disposables for high-turnover applications versus embedded reusable systems requiring sterilization infrastructure. Technical specifications, total cost of ownership calculations, and regulatory validation timelines vary sharply across these boundaries.
Product Type:
Standalone single-use items dominate high-frequency clinical contact, while embedded respiratory systems integrate with hospital ventilation protocols.
- Masks:Nonwoven polypropylene electret media with bacterial filtration efficiency thresholds exceeding 95 percent anchor surgical lines. German hospital networks specify these for aerosol-generating procedure protection where NIOSH certification or CE marking determines tender eligibility.
- Gloves:Nitrile elastomer formulations processed through chlorination or polymer coating deliver tactile sensitivity for invasive procedures. Malaysian and Sri Lankan manufacturing footprints supply European procurement departments confronting EU MDR technical file upgrade requirements for reusable alternatives.
- Gowns:ANSI/AAMI liquid barrier ratings stratify specifications across surgery applications.
- Face Shields:PET or polycarbonate visors with anti-fog coatings protect against splash exposure in emergency response settings.
Gloves lead volumes today; masks are gaining share fastest on respiratory protection mandate expansions.
Technology:
Cost tier separation runs deepest here: premium validated-reusable systems command service-contract pricing against commoditized disposable flows.
- Bacterial Filtration:Mechanisms targeting 3-micron particles at 95 percent efficiency threshold anchor standard surgical mask specifications.
- Viral Filtration:Sub-micron aerosol capture technologies with enhanced electret charge density address tuberculosis and influenza transmission risks in isolation wards.
- Reusable:Thermoplastic polyurethane garments with validated laundering protocols exceeding 50 cycles qualify for EU Green Deal procurement tiers. French hospital purchasing consortia rewrite technical specifications to exclude single-use alternatives where sterilization infrastructure exists.
- Disposable:Polypropylene spunbond-meltblown-spunbond laminates dominate high-volume applications where waste stream costs remain externalized.
Disposable technology leads volumes today; reusable systems are climbing the fastest on circular economy mandate penetration.
End User:
Customer type concentration tilts toward centralized procurement authority versus fragmented facility-level purchasing.
- Hospitals:Infection control committees standardize configurations across emergency response and patient care departments. Texas and California multi-hospital networks mandate unbundled after-sales service contracts from product supply agreements.
- Clinics:Outpatient settings prioritize compact storage and rapid donning protocols for limited procedure volumes.
- Laboratories:Biosafety level requirements dictate specialized respiratory and barrier combinations for pathogen handling.
- Nursing Homes:Long-term care facilities confront distinct compliance pressures under OSHA bloodborne pathogen standards with lower capital budgets for sterilization infrastructure.
Hospitals lead volumes today; nursing homes are expanding most quickly on regulatory inspection intensity increases.
Application:
Volume concentration varies by procedure invasiveness and aerosol generation risk, with margin structures inversely related to commoditization pressure.
- Infection Control:Isolation precaution configurations under CDC guidelines determine minimum PPE sets for contact, droplet, and airborne transmission scenarios.
- Surgery:Sterile field maintenance demands premium ANSI/AAMI Level 3-4 gown specifications with validated liquid barrier performance.
- Emergency Response:NIOSH-certified respirator designs adapted from industrial portfolios serve clinical emergency departments. MSA Safety Incorporated anchors this segment with industrial-origin respiratory platforms.
- Patient Care:Routine clinical contact drives highest glove consumption volumes with lowest per-unit pricing.
Patient care leads volumes today; emergency response is gaining share fastest on pandemic stockpile mandate expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern PPE manufacturing traces its industrial lineage to Malaysian rubber plantations and American industrial safety equipment foundries established during the early twentieth century. Hospital procurement networks now span five distinct national ecosystems with divergent regulatory timelines and sterilization infrastructure maturity.
United States
Texas and California health systems drive centralized purchasing mandates across multi-hospital networks. FDA 510(k) clearance timelines for reusable gown designs extend market access friction for domestic suppliers. The Ohio River Valley manufacturing corridor hosts NIOSH respirator certification facilities where testing capacity constraints create product launch bottlenecks.
Germany
French and German hospital purchasing consortia rewrite technical specifications to exclude single-use alternatives where autoclave infrastructure exists. EU MDR Class I reusable device requirements force technical file upgrades across Bavarian supply chains. The Rhine-Ruhr industrial cluster concentrates electret media filtration development for surgical mask specifications.
India
Domestic manufacturing capacity buildouts target nitrile glove self-sufficiency under PLI scheme incentives. CDSCO medical device registration pathways tighten for imported reusable technologies. The Tamil Nadu-Karnataka industrial corridor attracts Malaysian joint ventures for chlorinated glove production serving European export markets.
Brazil
ANVISA domestic production incentives reshape hospital network tender eligibility toward local content compliance. São Paulo state health secretariats expand stockpile mandates for infection control applications. The Campinas medical device cluster develops thermoplastic polyurethane garment sterilization protocols for regional supply.
Malaysia
Petrochemical feedstock access sustains nitrile elastomer glove production at global scale. DGFT export licensing requirements intersect with EU MDR technical documentation demands for European-bound shipments. The Klang Valley manufacturing belt integrates chlorination and polymer coating capabilities for invasive procedure glove specifications.
Healthcare Personal Protective Equipment (PPE) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in healthcare PPE. Integrated manufacturers with captive nitrile supply and electret media capabilities command pricing power in surgical mask and glove categories. Three archetypes dominate: Malaysian-Sri Lankan integrated glove producers, American industrial safety conglomerates with clinical adaptation programs, and diversified materials science multinationals with proprietary filtration platforms. Capacity expansion and regulatory certification partnerships constitute the dominant competitive moves as hospitals unbundle after-sales service contracts from product supply agreements.
Within the integrated manufacturing tier, Ansell Limited and MSA Safety Incorporated exemplify divergent strategic positioning. Ansell's Malaysian and Sri Lankan production footprint represents the glove-specialist archetype confronting EU MDR technical file upgrade requirements. MSA Safety occupies the industrial-to-clinical adaptation segment with NIOSH-certified respiratory platforms. 3M Company anchors the materials science archetype through proprietary electret media differentiation.
| Leading Market Players |
|---|
| Ansell Limited |
| MSA Safety Incorporated |
| 3M Company |
| Lakeland Industries, Inc. |
| Alpha Pro Tech, Ltd. |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| Cardinal Health, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Electret media filtration transitions from proprietary fiber treatment to commodity-grade manufacturing simultaneously compressing mask cost structures and concentrating pricing power among integrated materials science producers. This shift tightens margins for non-integrated suppliers while rewarding backward control over polypropylene resin and electrostatic charging equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NIOSH-certified respirators from CE-marked surgical masks from unbranded disposable barriers. Price differentiation hinges on certification grade and volume scale, with German hospital purchasing consortia commanding lowest per-unit rates through centralized tendering. Cost compression in standard surgical masks is intensifying because Malaysian glove producers absorb petrochemical feedstock volatility without pricing power. Nursing home procurement committees exhibit highest price sensitivity; emergency response departments within Texas health systems demonstrate lowest sensitivity due to stockpile mandate requirements.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States health systems and EU hospital networks force qualification of at least two glove suppliers per tender, fragmenting procurement concentration. Geographic supply concentrates in Malaysia, Sri Lanka, and Thailand for nitrile elastomer processing, with the Klang Valley manufacturing belt anchoring global chlorination capacity. Raw material dependencies rest on acrylonitrile-butadiene rubber feedstocks, nonwoven polypropylene resins, and thermoplastic polyurethane films. Single-source vulnerability persists in electret media charging equipment where German and Japanese machinery suppliers dominate. Distribution runs through group purchasing organizations in the United States and regional purchasing consortia in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Malaysian manufacturing cost advantages and EU regulatory compliance burdens, with the spread widest for reusable gown technologies requiring MDR technical file investments.
For Market Incumbents: To counter nitrile feedstock price volatility and emerging Indian domestic capacity, integrated producers should deepen backward integration into acrylonitrile supply and accelerate CE marking pathways for reusable alternatives. Certification investment represents the critical lever for sustaining European hospital network relationships against lower-cost import competition. For New Entrants and Emerging Players: Brazilian nursing home chains present an underserved buyer archetype with limited sterilization infrastructure and growing regulatory inspection intensity. Local ANVISA registration combined with compact disposable gown formats offers the most penetrable entry vector. Direct contracting with São Paulo state health secretariats bypasses established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap reusable garment specialists with validated laundering protocols but incomplete EU MDR technical documentation. Long-term viability centers on circular economy mandate penetration across German and French public procurement. The signal to watch is EU Green Deal tender specification rewrites excluding single-use alternatives where autoclave infrastructure exists.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Upgrade | Accelerates market access for Class I reusable devices across Bavarian supply chains. |
| NIOSH Respirator Certification Investment | Unlocks emergency response procurement within Texas and California health systems. |
| Domestic Manufacturing Joint Venture | Secures Brazilian ANVISA tender eligibility against import-dependent competitors. |
| Electret Media Proprietary Development | Differentiates filtration performance in German aerosol-generating procedure specifications. |
| Hospital System After-Sales Unbundling | Captures technical service revenue from infection control committee standardization. |
Methodological Framework
Coverage spans the United States, Germany, India, Brazil, and Malaysia, with primary inputs from each market's hospital procurement committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ANVISA registration records, CDSCO medical device approvals, and hospital procurement contract disclosures. Bottom-up volume estimates triangulated with top-down market sizing across product type, technology, and end user dimensions.
Granularity-level modeling captured surgical mask electret media specifications, nitrile glove chlorination grades, ANSI/AAMI gown barrier levels, and NIOSH respirator certification tiers throughout the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating sterilization infrastructure buildout rates and circular economy mandate penetration curves. Forecast inputs included petrochemical feedstock price indices, hospital capital expenditure cycles, and regulatory timeline assumptions for reusable device validation.
Underlying measurement precision varies by segment; disposable glove and mask volumes carry tighter precision than emerging reusable gown categories with limited commercial deployment history. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency, NIOSH testing capacity expansion, and Brazilian domestic production incentive continuity. Deviation in nitrile elastomer feedstock pricing or EU Green Deal procurement timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market