
 Road Safety Market | 2026-2036
Road Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Road Safety Market Intelligence
Modular traffic management bundles that combine hardware, software, and data analytics into subscription-style contracts is repositioning how municipal buyers evaluate vendor relationships. Kapsch TrafficCom leverages its end-to-end platform architecture to capture multi-year service agreements. Siemens anchors its position through deep integration of centralized traffic control systems with urban rail networks. Jenoptik competes on specialized speed enforcement and red-light camera manufacturing scale.
Road safety encompasses engineered systems, electronic controls, and data infrastructure designed to prevent collisions, reduce injury severity, and manage traffic flow across roadway networks. Core specifications include millimeter-wave radar operating at 77 GHz for adaptive cruise control, polyurethane foam densities of 25-35 kg/m³ in pedestrian impact zones, and machine-vision algorithms processing 30+ frames per second for real-time hazard detection. Advanced Driver Assistance Systems now absorb disproportionate R&D investment as automakers face homologation requirements for Automatic Emergency Braking under UN R152. Collision Avoidance Systems represent the fastest-expanding technology segment, while centralized traffic control installations in mature European cities generate stable recurring revenue from maintenance and software upgrades.
The US Department of Transportation's National Roadway Safety Strategy, the EU's revised General Safety Regulation mandating intelligent speed assistance, and the UN Economic Commission for Europe's harmonized vehicle standards collectively reshape product certification requirements and procurement criteria. These frameworks force technology suppliers to maintain parallel compliance tracks while creating barriers for non-certified entrants. Stakeholders must monitor how pending updates to FMVSS 127 and the EU AI Act's risk-classification rules for automated enforcement will alter hardware-software bundling economics and vendor qualification timelines.
Market Dynamics
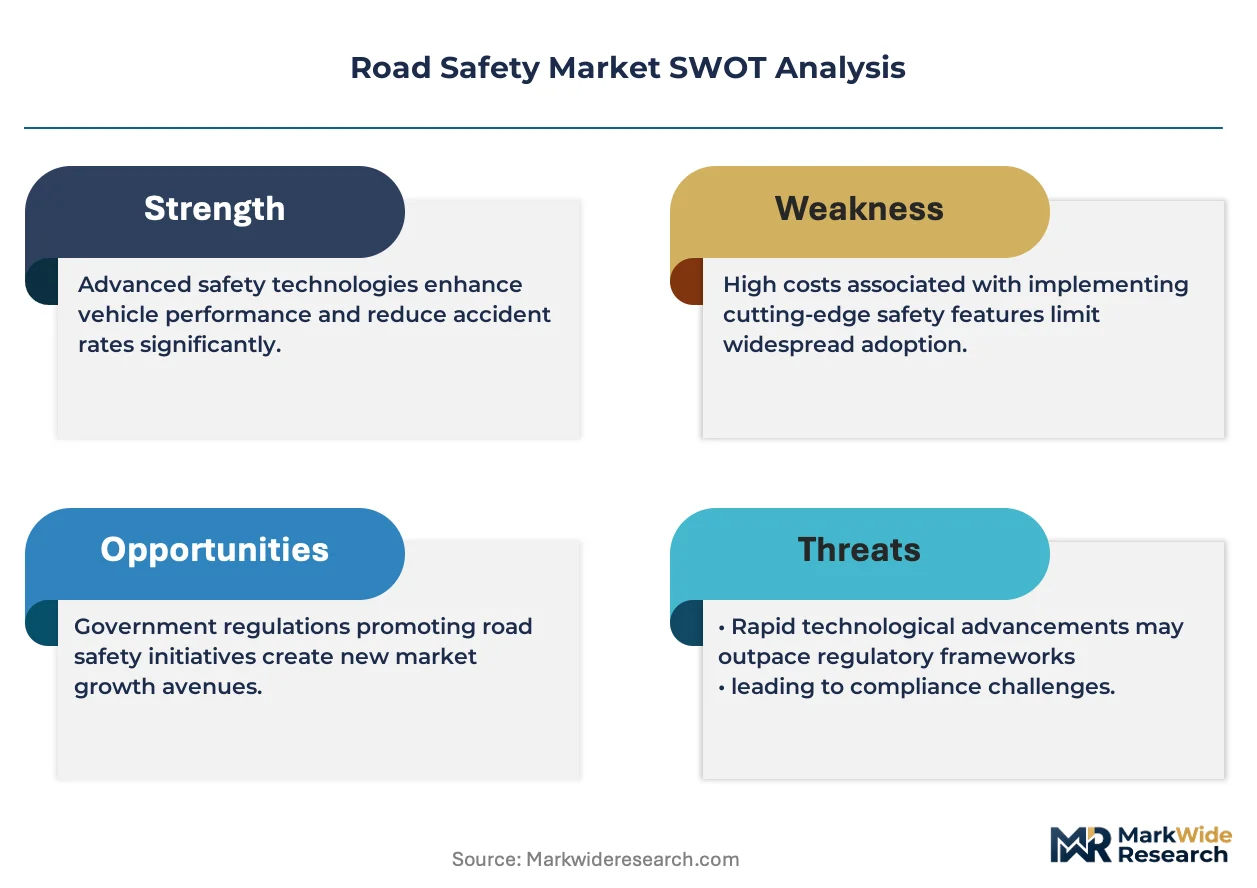
Municipal procurement offices are abandoning capital-heavy hardware purchases in favor of subscription-based traffic management bundles, compressing vendor cash conversion cycles and forcing incumbents to restructure revenue recognition models around multi-year service agreements.
Growth Catalysts
- EU AI Act enforcement tiers:Automated traffic enforcement systems now face mandatory conformity assessments under risk-classification rules, creating certified-vendor preference in German and French municipal tenders.
- US DOT National Roadway Safety Strategy:Federal matching funds for Vision Zero initiatives accelerate replacement of legacy signal controllers in high-crash corridors across metropolitan planning organizations.
- 77 GHz millimeter-wave radar:Sensor miniaturization enables cost-effective retrofit of intersection conflict warning systems onto existing mast arms without full reconstruction.
Market Restraints
- Semiconductor supply concentration:Edge AI processors for real-time video analytics depend on TSMC and Samsung foundry capacity, exposing lead time volatility for camera-integrated detection systems.
- Copper and aluminum price instability:Signal cabinet wiring and pole infrastructure face input cost pressure that municipal budgets struggle to pass through in fixed-price contracts.
- Legacy controller incompatibility:NEMA TS2 standard variations across 1990s-era installations block plug-and-play upgrade paths for centralized adaptive systems.
Strategic Opportunities
- India's Smart Cities Mission:100 designated urban areas lack deployed red-light enforcement infrastructure, creating first-mover advantage for speed-camera-as-a-service providers.
- Vehicle-to-everything (V2X) integration:Convergence of DSRC and C-V2X protocols enables intersection-based collision warning without full vehicle fleet penetration.
- California SB 961 mandate trajectory:Proposed intelligent speed assistance requirements for state fleet procurement establish template for broader US adoption.
Industry Challenges
- Embedded systems firmware engineering:Shortage of developers proficient in real-time operating systems for safety-critical traffic controllers delays product release schedules.
- UN R152 homologation timelines:Automatic Emergency Braking certification for aftermarket retrofit kits requires 18-24 month validation cycles that outpace technology refresh rates.
- Interoperability testing burden:Multi-vendor connected vehicle pilot deployments force redundant protocol verification across incompatible middleware stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Safety Market |
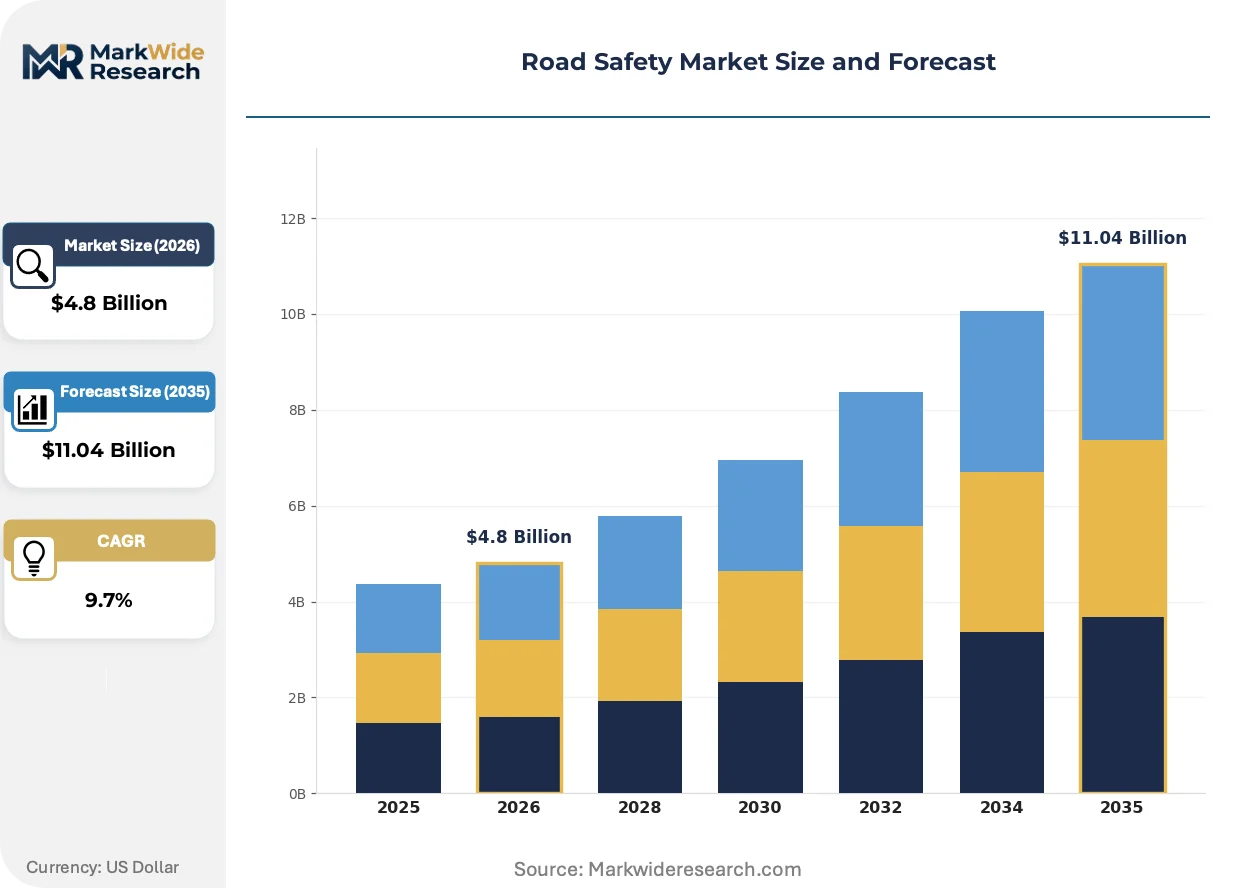
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Signs, Speed Cameras, Seat Belt Systems, Airbags Technology: Advanced Driver Assistance Systems, Automatic Emergency Braking, Lane Keeping Assist, Collision Avoidance Systems End User: Government Agencies, Automotive Manufacturers, Insurance Companies, Fleet Operators Installation: On-Road, In-Vehicle, Centralized Traffic Control, Mobile Solutions |
| Companies Covered | Kapsch TrafficCom, Teledyne FLIR, Verra Mobility, Sensys Gatso, Conduent, Motorola Solutions, Jenoptik, Cubic, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Safety Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing load from centralized traffic management centers to roadside units, enabling sub-100-millisecond response times for hazard detection while reducing backhaul bandwidth requirements.
LiDAR-based intersection monitoring is decentralizing perception tasks previously handled by server-vision systems, allowing mid-sized municipalities in Texas and Florida to deploy automated pedestrian detection without fiber-to-the-cabinet infrastructure. Traffic departments with constrained IT budgets are adopting these units fastest. The shift compresses vendor margin structures by eliminating recurring software license fees for cloud analytics.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of retroreflective sheeting adhesives used in highway signage, compelling 3M and Avery Dennison to validate alternative polymer chemistries ahead of 2025 sunset dates. European road authorities are accelerating procurement of compliant inventory. Sign manufacturers with pre-certified material stocks are capturing accelerated replacement cycles in Germany and the Netherlands.
Municipal fleet managers are unbundling maintenance contracts from initial hardware procurement, separating multi-year service agreements into competitive rebid intervals. This pattern is most visible in United Kingdom county council tenders, where four-year camera maintenance agreements now outnumber decade-long integrated concessions. Vendors with captive service networks retain advantage, but pure-play maintenance specialists are penetrating secondary markets through lower labor rate structures.
Road Safety Market Segmentation
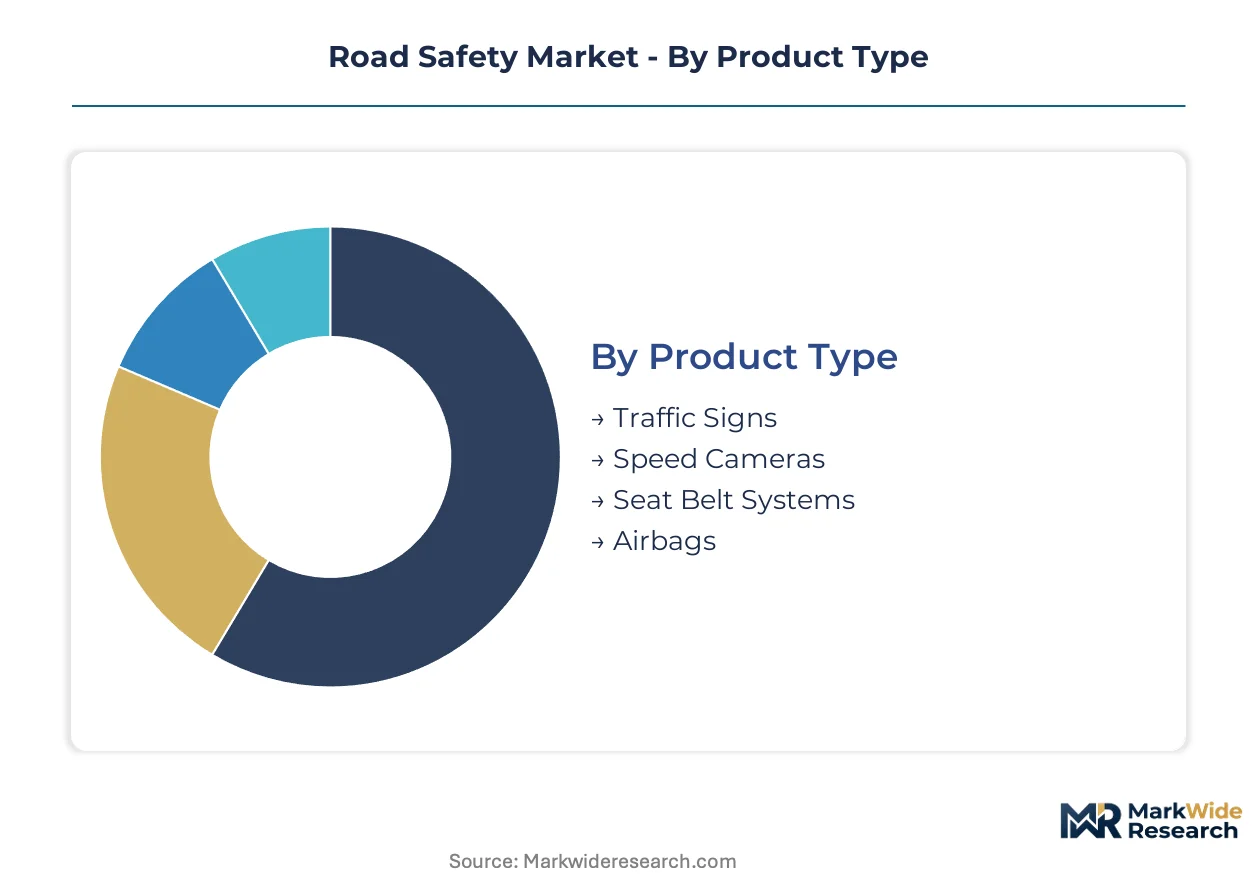
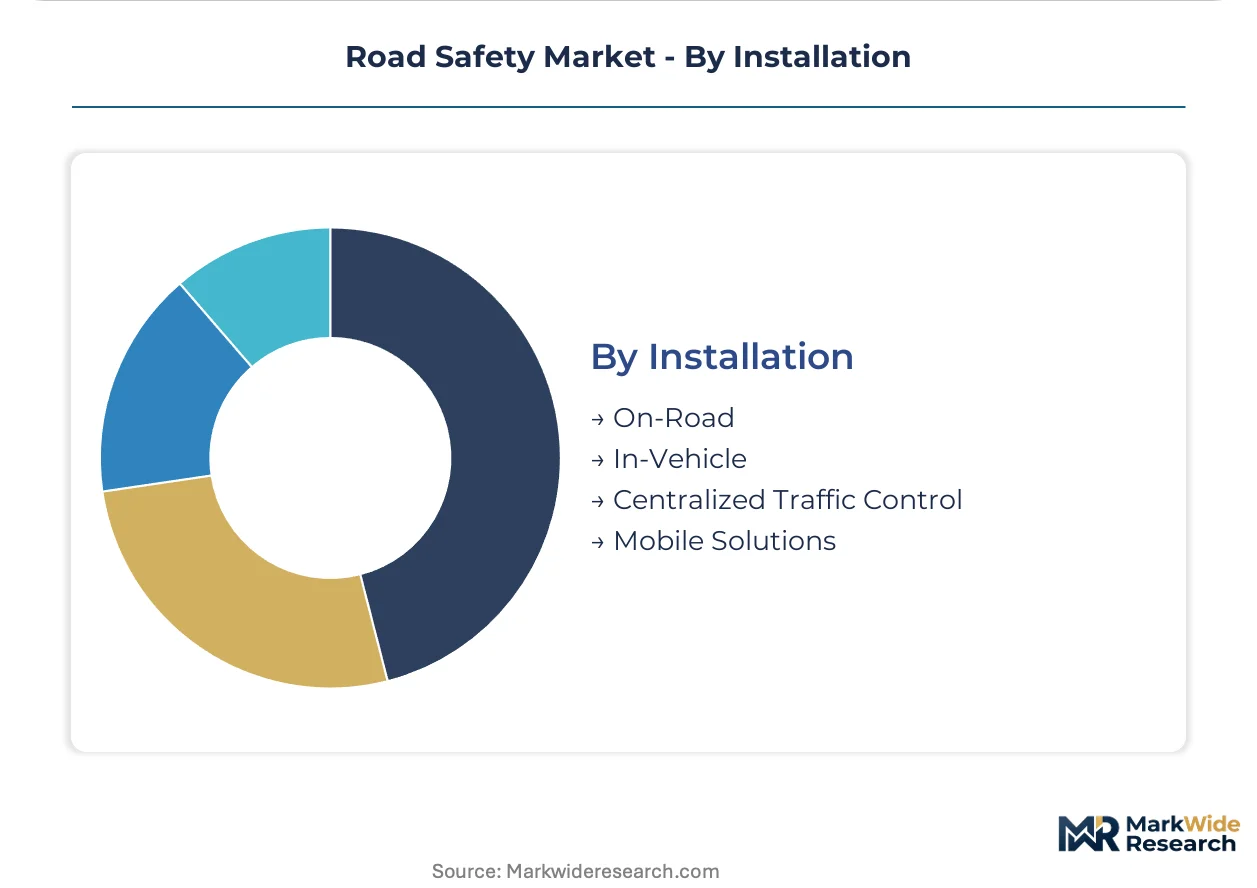
Road safety procurement splits between embedded vehicle systems and standalone infrastructure, with integration depth determining contract structure and vendor qualification requirements. Understanding where segments sit on this spectrum clarifies why automotive manufacturers and government agencies operate on fundamentally different buying cycles and technical standards.
Product Type:
Standalone infrastructure products require municipal procurement cycles and civil engineering coordination, while embedded vehicle systems follow automotive tier-1 supply chains with homologation gates.
- Traffic Signs:Retroreflective sheeting bonded to aluminum substrates delivers nighttime visibility under headlamp illumination. German and Dutch road authorities are accelerating replacement schedules ahead of REACH substance restrictions on legacy adhesive chemistries.
- Speed Cameras:Multi-sensor enclosures combine radar triggering with machine-vision capture for automated enforcement evidence chains. United Kingdom county councils are unbundling decade-long concessions into competitive four-year maintenance rebids, compressing vendor margin structures.
- Seat Belt Systems:Webbing tensioners and retractor mechanisms integrated into B-pillar assemblies. Automotive tier-1 suppliers face UN R16 homologation timelines that gate vehicle platform launches.
- Airbags:Pyrotechnic inflator modules with nylon fabric cushions deployed through steering column or dashboard tear-seams. Deployment algorithms now incorporate multi-stage firing profiles calibrated to occupant position sensors.
Volume placements concentrate in Traffic Signs; the faster expansion belongs to Speed Cameras.
Technology:
Cost tier differentiation separates premium sensor fusion architectures from single-modality systems, with price spreads reflecting compute requirements and calibration complexity.
- Advanced Driver Assistance Systems:Sensor fusion platforms integrating camera, radar, and ultrasonic inputs for unified environmental modeling. NHTSA FMVSS 127 mandates are forcing parallel compliance tracks for US and EU certification.
- Automatic Emergency Braking:Forward-facing radar or camera systems executing autonomous brake actuation when collision probability exceeds calibrated thresholds. UN R152 homologation cycles extend 18-24 months, outpacing technology refresh rates for aftermarket retrofit providers.
- Lane Keeping Assist:Camera-based lane boundary detection with torque overlay steering correction. Mid-market vehicle segments are adopting simplified single-camera implementations to avoid lidar cost premiums.
- Collision Avoidance Systems:V2X-enabled intersection warning architectures communicating hazard states to approaching vehicles via DSRC or C-V2X protocols. Texas and Florida municipalities are deploying these without full fiber backhaul, using edge-processed LiDAR units.
Revenue concentration sits with Advanced Driver Assistance Systems; Collision Avoidance Systems are climbing the fastest as V2X pilot programs scale.
End User:
Customer type determines contract structure, with government agencies favoring subscription bundles and automotive manufacturers locking in multi-year supply agreements.
- Government Agencies:Municipal transportation departments and national road authorities procuring enforcement infrastructure and traffic management systems. EU AI Act risk-classification rules are creating certified-vendor preference in German and French tenders.
- Automotive Manufacturers:OEMs and tier-1 suppliers integrating active safety systems at vehicle assembly. General Safety Regulation mandates for intelligent speed assistance are reshaping product roadmaps.
- Insurance Companies:Telematics providers and risk modelers using driving behavior data to refine policy pricing. Usage-based insurance penetration is driving aftermarket device installations in commercial fleets.
- Fleet Operators:Logistics companies and ride-hail platforms retrofitting legacy vehicles with driver monitoring and collision warning systems. California SB 961 fleet procurement mandates are establishing template requirements for intelligent speed assistance.
Procurement volume clusters with Government Agencies; Insurance Companies are gaining share fastest through telematics integration.
Installation:
Geography of deployment—roadside versus cabin—determines environmental specification, connectivity requirements, and maintenance access protocols.
- On-Road:Pole-mounted or gantry-fixed equipment including signals, cameras, and V2X roadside units. 77 GHz radar miniaturization now enables retrofit onto existing mast arms without full intersection reconstruction.
- In-Vehicle:Embedded systems integrated at manufacturing or aftermarket installation, including ADAS controllers and occupant protection modules. Semiconductor supply concentration at TSMC and Samsung foundries exposes lead time volatility.
- Centralized Traffic Control:Urban traffic management centers coordinating signal timing across corridor networks. Mature European cities generate stable recurring revenue from maintenance and software upgrade contracts.
- Mobile Solutions:Portable enforcement units and temporary traffic management for construction zones or special events. India's Smart Cities Mission is creating first-mover opportunity for speed-camera-as-a-service providers in 100 designated urban areas.
Deployment scale favors On-Road infrastructure; Mobile Solutions are expanding most quickly through service-model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Road safety system manufacturing concentrates in Germany, Japan, and the United States, while deployment demand clusters in congested urban corridors across Western Europe and North American metropolitan regions. Consumption patterns diverge sharply between mature markets replacing legacy infrastructure and emerging economies building first-generation enforcement networks.
United States
Federal matching funds through the US DOT National Roadway Safety Strategy accelerate Vision Zero corridor upgrades in metropolitan planning organizations. NHTSA FMVSS 127 mandates force parallel compliance tracks for automatic emergency braking systems. Texas and Florida municipalities deploy LiDAR-based intersection monitoring without fiber backhaul, compressing vendor margin structures.
Germany
EU AI Act risk-classification rules create certified-vendor preference in automated traffic enforcement tenders issued by municipal authorities. KBA homologation requirements govern aftermarket retrofit kit approvals. Bavaria and Baden-Württemberg host dense clusters of automotive tier-1 suppliers integrating 77 GHz radar modules for adaptive cruise control platforms.
United Kingdom
County councils unbundle decade-long camera maintenance concessions into competitive four-year rebid intervals, restructuring vendor revenue recognition models. REACH substance restrictions on retroreflective sheeting adhesives accelerate signage replacement schedules. Greater Manchester and West Midlands transport authorities pilot subscription-based traffic management bundles.
India
Smart Cities Mission designates 100 urban areas lacking deployed red-light enforcement infrastructure, creating first-mover advantage for speed-camera-as-a-service providers. BIS certification requirements govern traffic signal controller imports. Maharashtra and Karnataka state governments issue tenders for centralized adaptive systems in Bangalore and Mumbai metropolitan regions.
Japan
METI guidelines shape intelligent transport system deployment standards for vehicle-to-infrastructure communication. Domestic automakers face UN R152 homologation timelines for automatic emergency braking that gate platform launches. Kanto and Kansai industrial corridors concentrate sensor fusion R&D for advanced driver assistance systems.
Road Safety Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across contract structures that range from capital-heavy hardware procurement to multi-year service agreements. Siemens and Cubic occupy positions spanning centralized traffic control and urban rail integration, while Kapsch TrafficCom and Jenoptik exemplify traffic management specialization. The vendor base splits between end-to-end platform architects and component-scale manufacturers. Competitive moves center on restructuring revenue models around subscription bundles and capturing maintenance contract unbundling opportunities.
Among European-headquartered platform providers, Kapsch TrafficCom AG and Siemens AG exemplify divergent strategic archetypes. Kapsch represents the pure-play traffic management specialist capturing multi-year service agreements through modular bundle architectures. Siemens occupies the diversified industrial conglomerate position leveraging deep integration between traffic control and rail networks. Jenoptik AG anchors the precision-optics manufacturing tier focused on speed enforcement and red-light camera production scale. Motorola Solutions, Inc. sits within the critical communications infrastructure segment, applying public safety system expertise to intersection monitoring deployments. Verra Mobility Corporation represents the enforcement-as-a-service model, unbundling hardware from violation processing workflows.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| Teledyne FLIR |
| Verra Mobility |
| Sensys Gatso |
| Conduent |
| Motorola Solutions |
| Jenoptik |
| Cubic |
| Siemens |
| Others |
Cost & Logistics Intelligence
Firmware engineering talent concentration in Bavaria and Baden-Württemberg widens labor-cost spreads between premium sensor-fusion platforms and economy-tier single-modality systems, compressing mid-market margins as buyers demand certified compliance without tier-1 pricing.
Pricing Analysis
Cost-down pressure on mid-tier traffic controllers accelerates because municipal procurement offices unbundle hardware from service agreements, forcing vendors to compete on standalone unit economics. Three-tier pricing structure across premium certified, standard compliant, and economy basic levels reflects differentiation by UN R152 homologation status and after-sales bundling depth. Price erosion runs through standard-tier camera systems as pure-play maintenance specialists underbid incumbents on labor rates. Government agencies exhibit highest price sensitivity due to fixed annual budgets, while automotive manufacturers absorb premium tier costs to gate platform launches.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for Smart Cities Mission tenders are reshaping sourcing patterns for signal controllers and enforcement cameras. Manufacturing concentrates in Germany, Japan, and China for 77 GHz radar modules, edge AI processors, and retroreflective sheeting. Critical inputs include TSMC-fabricated neural network accelerators, copper signal cabinet wiring, and polyurethane foam for pedestrian impact zones. Single-source vulnerability at Taiwanese and South Korean foundries exposes lead time volatility. Distribution runs through municipal procurement offices for infrastructure and tier-1 automotive suppliers for embedded systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road safety system supply is tightening around semiconductor foundry capacity and certified firmware engineering pools, with TSMC allocation constraints propping pricing power for vendors with captive chip supply.
For Market Incumbents: Anticipate margin compression from unbundled maintenance contracts by securing multi-year service agreements before competitive rebid intervals accelerate. Deepen backward integration into edge AI processor supply through strategic foundry partnerships to offset TSMC allocation volatility. Prioritize EU AI Act conformity assessment pre-certification to capture German and French municipal preference. For New Entrants and Emerging Players: Enter via speed-camera-as-a-service models in India's 100 Smart Cities Mission urban areas lacking deployed enforcement infrastructure. Target mobile enforcement units for construction zones and special events where incumbent service networks have shallow penetration. Pursue direct municipal relationships bypassing legacy distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play traffic management specialists given subscription-bundle revenue model adoption and recurring maintenance contract visibility. Long-term viability favors vendors with certified-platform scale across multiple regulatory jurisdictions. Monitor California SB 961 fleet procurement mandate progression as signal for broader US intelligent speed assistance adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Captures certified-vendor preference in German and French municipal enforcement tenders ahead of mandatory assessment deadlines. |
| Speed-Camera-as-a-Service Launch | Positions providers for India's Smart Cities Mission procurement cycles without requiring municipal capital budget allocation. |
| Edge AI Processor Supply Agreement | Secures foundry allocation from TSMC or Samsung to mitigate 18-24 month lead time volatility for camera-integrated detection systems. |
| LiDAR-Based Intersection Monitoring Deployment | Enables Texas and Florida municipalities to deploy pedestrian detection without fiber-to-cabinet infrastructure investment. |
| Maintenance Contract Unbundling Response | Restructures revenue recognition around competitive four-year rebid intervals matching United Kingdom county council tender patterns. |
Research Approach
Multi-period observation of municipal procurement patterns, homologation timeline progression, and foundry capacity allocation anchored the trend analysis, supplemented by interviews with traffic management system procurement officers, automotive tier-1 supplier platform engineers, firmware engineering directors, and municipal transportation department officials. Secondary validation drew from NHTSA FMVSS filings, EU AI Act implementation guidance, UN ECE R152 certification databases, and semiconductor foundry utilization disclosures. Bottom-up segment sizing triangulated against top-down market envelope checks.
Input-output matrices mapped sensor unit volumes to intersection deployment counts, vehicle production schedules to ADAS content per vehicle, and maintenance contract rebid intervals to recurring revenue recognition patterns across the projection horizon. Segmentation dimensions modeled include product architecture, technology cost tier, end-user procurement structure, and installation geography. CAGRs derived from regression analysis of historical replacement cycles, regulatory mandate phase-in schedules, and infrastructure investment correlations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption, copper price volatility, or extended UN R152 homologation delays. Forecasts reflect documented assumptions regarding regulatory enforcement timing, municipal budget continuity, and technology refresh rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Global Fall Protection Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Child Leash Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Fall Detection System Market
Personal Safety
Life Jacket Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Smart Home Safety Market
Personal Safety
Smart Personal Safety and Security Device Market