
 Spill Kits Market | 2026-2036
Spill Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Spill Kits Market Analytics
Market Context
Advanced polymer absorbency technology is rewriting material performance benchmarks across industrial containment. New Pig Corporation leverages proprietary melt-blown polypropylene formulations to sustain premium positioning in North American manufacturing channels. Brady Corporation anchors its portfolio through integrated identification and containment systems that dominate safety-conscious procurement workflows. 3M Company competes via deep R&D investment in fluorine-free absorbent media, differentiating against legacy oil-only formulations.
Technical Definition and Segment Structure
Spill kits are pre-assembled response packages containing absorbent pads, booms, socks, and granules engineered to capture and neutralize liquid releases across hydrocarbon, chemical, and universal hazard classes. Polypropylene melt-blown nonwovens remain the dominant absorbent substrate due to oleophilic-hydrophobic selectivity and rapid saturation capacity. Universal kits command the broadest end-user penetration across multi-fluid manufacturing environments, while hazmat kits capture the fastest-growing segment as laboratories and pharmaceutical cleanrooms tighten chemical-handling protocols. Marine end users concentrate demand for boom-intensive configurations, with margin pools shifting toward specialty kits integrating pH-neutralizing agents for acid and caustic response.
Regulatory Frame and Outlook
EPA SPCC rules, OSHA 29 CFR 1910.120 HAZWOPER standards, and REACH chemical registration requirements in Europe collectively mandate documented spill-response readiness across covered facilities. These frameworks shape product certification pathways, absorbent disposal classifications, and facility audit frequency. Stakeholders must monitor fluorine-free material transitions and evolving state-level PFAS restrictions that threaten incumbent polypropylene supply chains.
Market Dynamics
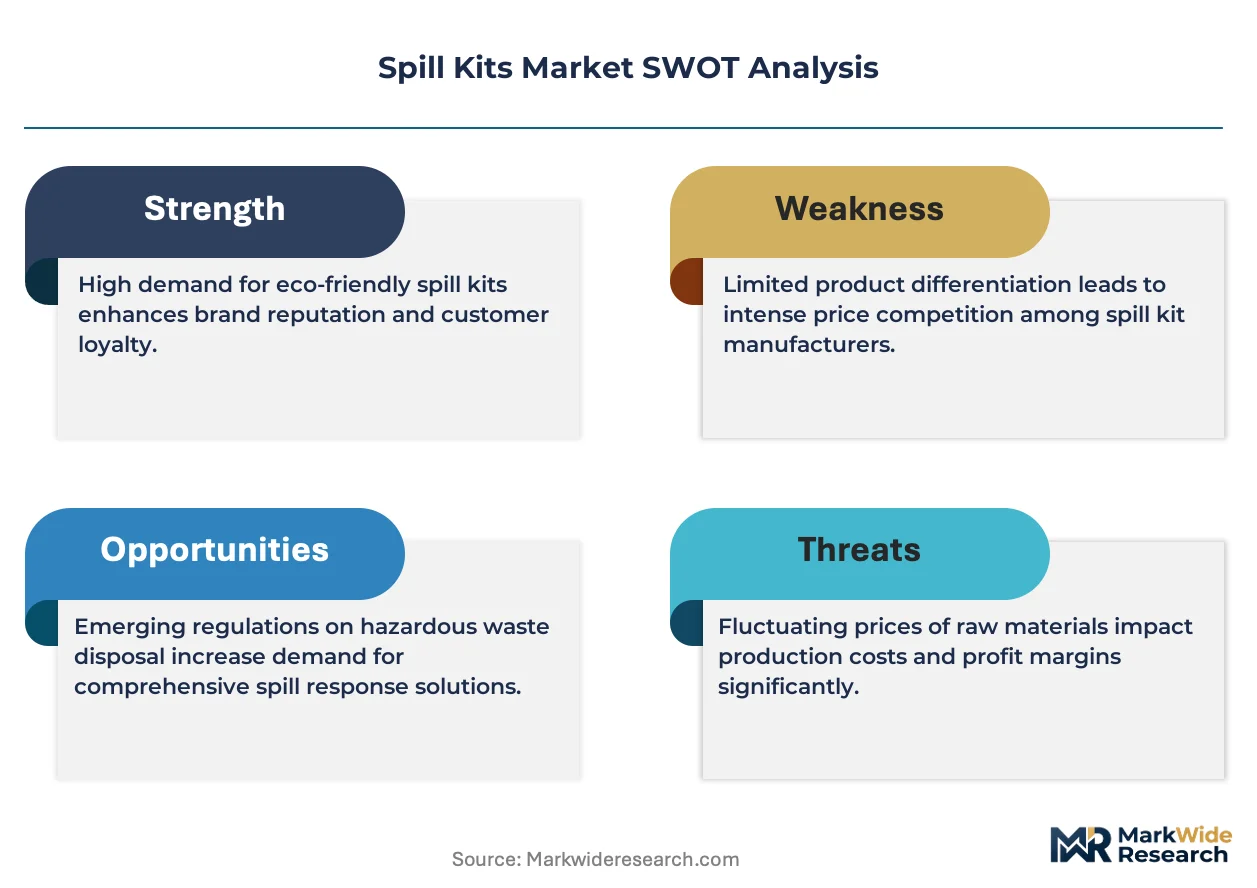
Fluorine-free absorbent formulations are forcing a wholesale substrate transition across industrial spill-response procurement, as state-level PFAS restrictions in the United States and REACH chemical registration requirements in Europe converge to de-certify legacy polypropylene melt-blown products.
Growth Catalysts
- OSHA HAZWOPER mandates:Facility audit frequency is tightening across chemical-handling operations, requiring documented spill-response readiness that drives kit replenishment cycles.
- Pharmaceutical cleanroom expansion:Laboratory and biomanufacturing construction in Germany and China is accelerating demand for hazmat-configured kits with pH-neutralizing agents.
- Marine oil spill liability:Port authorities in Singapore and Rotterdam are mandating boom-intensive configurations for vessel operators, expanding specialty kit deployments.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margins for melt-blown nonwoven producers.
- China concentrate risk:A significant share of polypropylene melt-blown manufacturing capacity clusters in Shandong and Zhejiang provinces, creating single-source vulnerability.
- Incumbent technology lock-in:Fluorinated surfactant treatments in legacy oil-only absorbents face accelerated obsolescence under emerging PFAS restrictions.
Strategic Opportunities
- India manufacturing buildout:PLI scheme incentives for chemical and pharmaceutical production are creating first-mover advantage for spill kit distributors establishing local assembly.
- Biobased absorbent convergence:Cellulosic and mycelium-derived substrates paired with compostable packaging address circular economy procurement criteria.
- E-commerce direct procurement:Industrial maintenance, repair, and operations platforms are disintermediating traditional safety distributors for standard universal kit configurations.
Industry Challenges
- Fluorine-free certification timelines:Third-party validation of new absorbent chemistries against EPA and REACH disposal classifications extends product launch cycles by 12-18 months.
- Retrofit integration complexity:Existing spill-response infrastructure in mature manufacturing facilities requires customized adapter configurations for next-generation kit formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spill Kits Market |
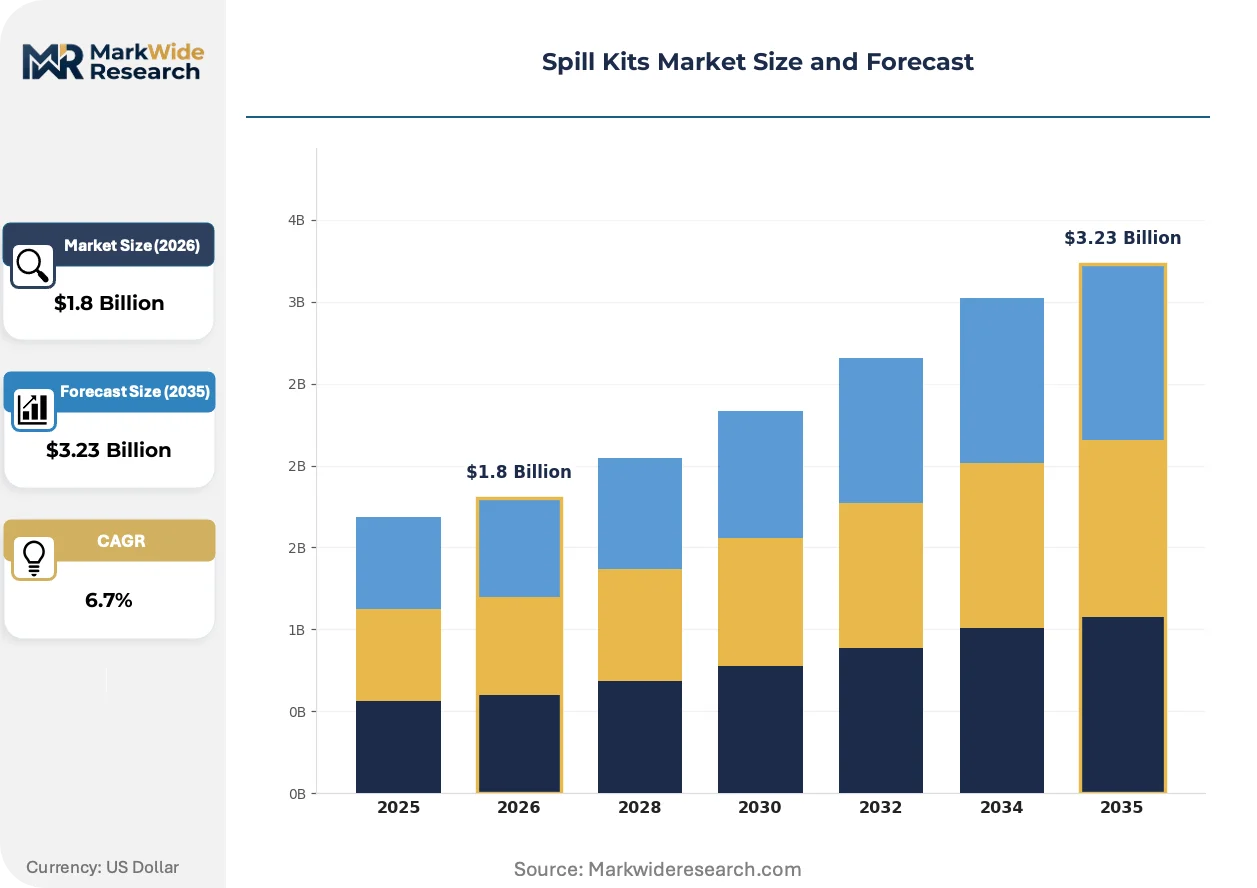
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Kits, Oil Only Kits, Hazmat Kits, Specialty Kits Material: Absorbent Pads, Booms, Granules, Socks End User: Manufacturing Facilities, Hospitals, Laboratories, Marine Distribution Channel: Online Retail, Direct Sales, Distributors, Bulk Purchases |
| Companies Covered | New Pig Corporation, Brady Corporation, Denios AG, 3M Company, SpillTech, Justrite Manufacturing Company, Oil-Dri Corporation of America, ENPAC LLC, Shanghai Weiyi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spill Kits Market Evolving Landscape
Material science breakthroughs and regulatory chemistry bans are compressing product lifecycles while reshaping how industrial buyers evaluate absorbent performance. Three developments are restructuring competitive advantage.
Silica aerogel composites are collapsing the weight-performance tradeoff that has constrained marine and aviation spill-response logistics for decades. Offshore platform operators and cargo carriers are adopting these ultra-lightweight formulations to reduce helicopter transport costs and deck storage footprints. The technology is collapsing minimum order quantity thresholds that previously excluded smaller vessel operators from certified kit procurement.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are triggering a formulation scramble across European absorbent suppliers. Industrial chemical manufacturers in Belgium and the Netherlands are requiring documented fluorine-free supply chains for site-level compliance. Universal kit configurations integrating color-coded absorbent segregation are capturing preference share as facilities retrain response teams on new material handling protocols.
Consolidated national account procurement is displacing branch-level safety purchasing in multi-site manufacturing organizations. Automotive and aerospace original equipment manufacturers are centralizing spill-response specifications through corporate environmental health and safety departments, bypassing traditional distributor relationships. This concentration is most visible in the United States, where tier-one suppliers to Detroit and Seattle manufacturing clusters face mandated kit standardization across their North American facility networks.
Spill Kits Market Segmentation
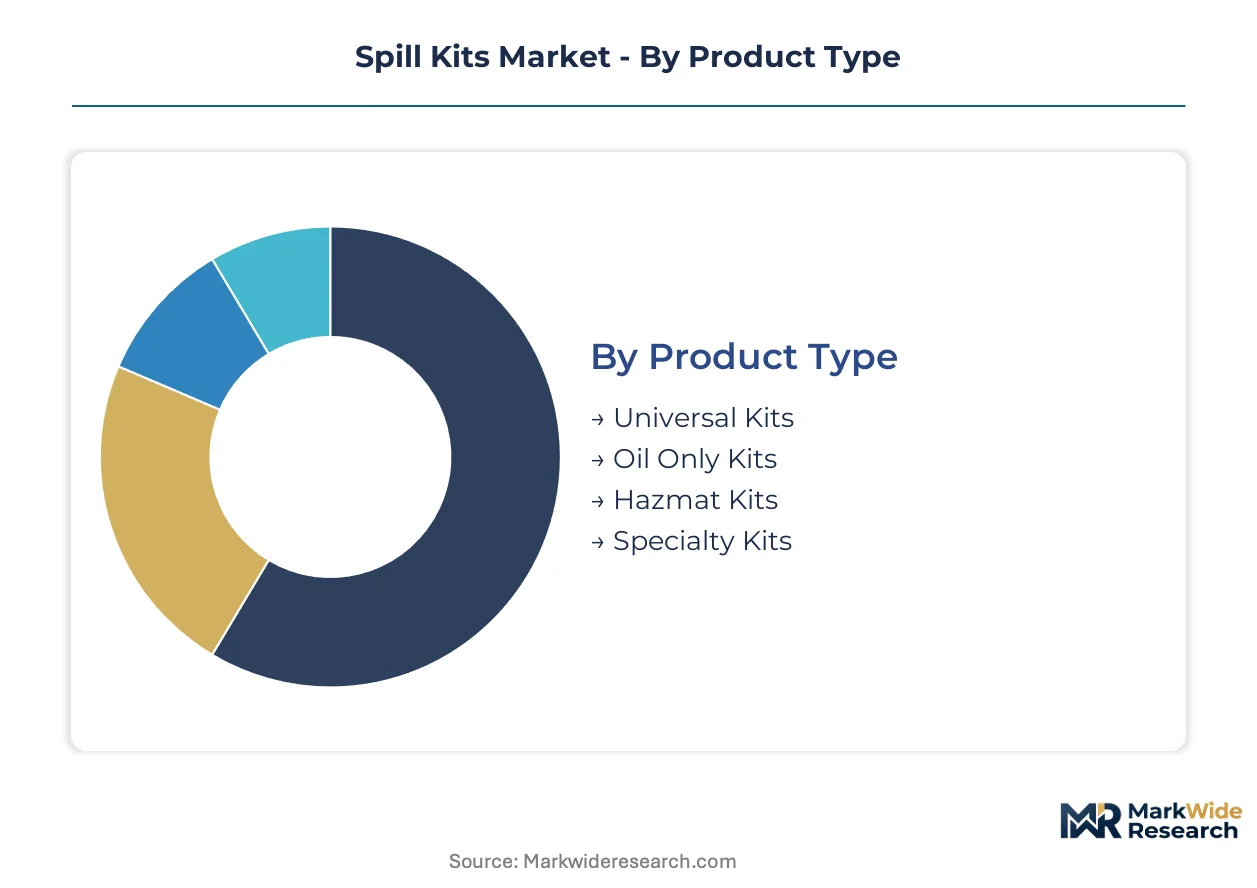
Spill kit procurement patterns diverge sharply across hazard classification, absorbent format, and operational environment. Buyers segment demand by fluid compatibility, deployment speed, and regulatory audit requirements rather than unit cost alone.
Product Type:
Cost tiers separate standard response configurations from certified specialty packages with documented disposal pathways.
- Universal Kits:Multi-fluid absorbent formulations handle oils, coolants, and water-based chemicals without kit swapping. Manufacturing facilities in Germany and the United States standardize on these configurations to reduce SKU complexity across plant floors.
- Hazmat Kits:Integrate pH-neutralizing agents, vapor-suppressing media, and color-coded PPE for corrosive and toxic releases. Pharmaceutical cleanrooms in China and Belgium are mandating these kits as chemical-handling protocols tighten.
- Oil Only Kits:Hydrophobic polypropylene formulations target hydrocarbon containment on water surfaces and maintenance bays.
- Specialty Kits:Custom-configured packages for mercury, battery acid, or biohazard response with certified disposal containers.
Universal kits command the established base. The steepest expansion runs through hazmat configurations.
Material:
Application context dictates format selection based on spill surface geometry, volume capacity, and deployment speed requirements.
- Absorbent Pads:Flat-sheet melt-blown polypropylene delivers rapid saturation for floor-level maintenance spills. Automotive assembly plants in Detroit and Stuttgart deploy pad-intensive kits at workstation density.
- Booms:Cylindrical sock-in-net configurations encircle machinery bases and contain perimeter breaches. Port authorities in Singapore and Rotterdam mandate boom-intensive kits for vessel operators under marine oil spill liability frameworks.
- Granules:Loose particulate media for irregular surfaces and outdoor terrain where pad contact is impractical.
- Socks:Flexible tubular absorbents for linear containment around equipment legs and drain protection.
Absorbent pads anchor manufacturing procurement. Booms are gaining share fastest in marine and heavy industrial channels.
End User:
Customer type determines kit complexity, certification documentation, and replenishment frequency through incident rates and audit intensity.
- Manufacturing Facilities:High-volume universal kit deployment with scheduled replenishment tied to OSHA HAZWOPER audit cycles. Chemical processors and metal fabricators in the United States and Germany drive standardized corporate procurement programs.
- Marine:Boom-dominant configurations with helicopter-transport weight constraints and offshore storage limitations. Cargo carriers and platform operators adopt silica aerogel composites to reduce logistics burden.
- Hospitals:Biohazard and mercury response kits with sharps containment and regulated medical waste integration.
- Laboratories:Compact hazmat kits for fume hood and benchtop chemical handling with minimal storage footprints.
Manufacturing facilities represent the volume core. Marine applications are climbing the fastest on regulatory mandate expansion.
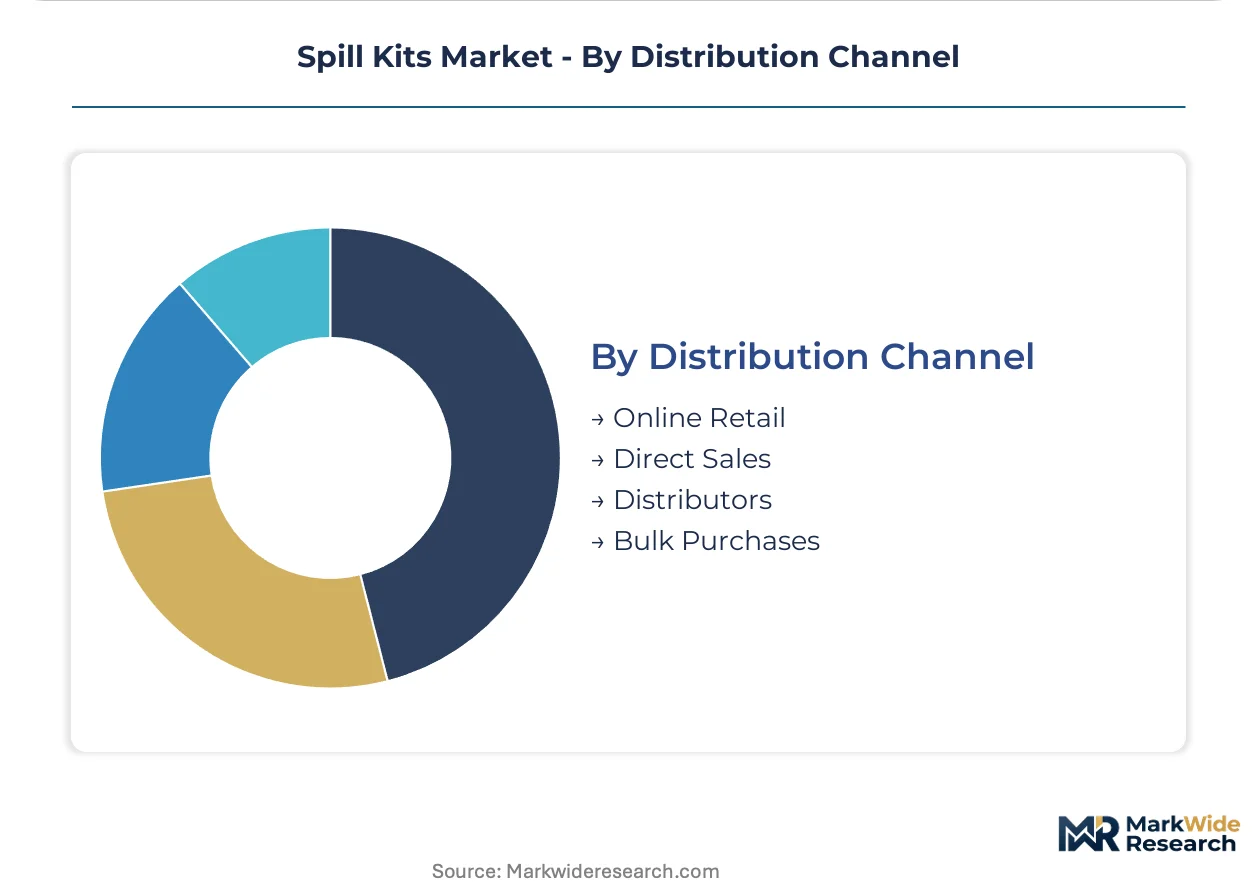
Distribution Channel:
Volume scale and procurement autonomy shape channel selection across facility networks and independent operators.
- Distributors:Traditional safety supply houses dominate multi-site manufacturing relationships with consolidated billing and technical service. Brady Corporation and New Pig Corporation leverage these channels for kit specification and training support.
- Direct Sales:National account procurement through corporate EHS departments bypasses distributor markups for standardized kit configurations. Automotive and aerospace OEMs in the United States centralize specifications across North American facility networks.
- Online Retail:E-commerce platforms disintermediate standard universal kit procurement for small and mid-sized facilities with limited safety staff.
- Bulk Purchases:Volume contracting for absorbent refill components rather than complete kits, common in high-incident chemical processing environments.
Distributors retain the established procurement pathway. Direct sales channels are expanding most quickly through corporate purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German spill kit manufacturers export fluorine-free absorbent formulations to Belgian and Dutch chemical processors facing REACH Annex XVII compliance deadlines. This trade corridor reflects tightening regulatory chemistry bans across northwest European industrial clusters.
United States
OSHA HAZWOPER audit cycles drive scheduled kit replenishment across Texas and Louisiana petrochemical corridors. EPA SPCC rules mandate documented spill-response readiness for above-ground storage tank facilities. Houston-Galveston refining complexes standardize on universal kit configurations to reduce SKU complexity across multi-site operations.
Germany
Pharmaceutical cleanroom construction in Baden-Württemberg accelerates hazmat kit demand with pH-neutralizing agents. REACH chemical registration requirements shape absorbent disposal classifications for industrial chemical manufacturers. BASF Ludwigshafen and Bayer Leverkusen facilities centralize procurement through corporate EHS departments.
China
Dual carbon goals and MEE environmental enforcement tighten chemical-handling protocols in Yangtze River Delta manufacturing zones. Shandong and Zhejiang provinces concentrate polypropylene melt-blown absorbent production capacity. Shanghai port authorities mandate boom-intensive configurations for vessel operators under marine oil spill liability frameworks.
India
PLI scheme incentives for chemical and pharmaceutical production create first-mover advantage for spill kit distributors establishing local assembly. Maharashtra and Gujarat industrial corridors expand absorbent inventory programs as manufacturing capacity scales. CDSCO pharmaceutical regulations tighten cleanroom chemical-handling standards in Mumbai-Pune biomanufacturing clusters.
Singapore
Port authority mandates for marine oil spill readiness drive boom-intensive kit deployment among container carriers and bunker operators. Maritime and Port Authority regulations specify helicopter-transport weight constraints for offshore platform supply vessels. Jurong Island petrochemical complexes integrate silica aerogel composites to reduce logistics burden.
Spill Kits Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification authority in industrial safety procurement. The market structures around three tiers: integrated safety distributors with training services, absorbent material specialists with proprietary formulations, and industrial supply platforms disintermediating standard configurations. Strategic moves concentrate on fluorine-free certification acceleration and national account procurement consolidation.
Within the integrated distributor tier, Brady Corporation and New Pig Corporation occupy positions anchoring multi-site manufacturing relationships with technical service capabilities. Denios AG exemplifies the European specialist archetype with regulatory-driven hazardous materials containment expertise. These three entities represent divergent competitive vectors: North American channel control, premium absorbent technology, and EU regulatory compliance integration.
| Leading Market Players |
|---|
| New Pig Corporation |
| Brady Corporation |
| Denios AG |
| 3M Company |
| SpillTech |
| Justrite Manufacturing Company |
| Oil-Dri Corporation of America |
| ENPAC LLC |
| Shanghai Weiyi |
| Others |
Value Network & Pricing Analysis
Undercapacity in Shandong Province polypropylene melt-blown manufacturing is compressing supplier margins while amplifying pricing power for integrated absorbent producers with captive resin supply. This utilization squeeze forces non-integrated kit assemblers toward spot market exposure or long-term offtake commitments with volatile feedstock clauses.
Pricing Analysis
Fluorine-free next-generation absorbent formulations command premium positioning against legacy fluorinated oil-only substrates and standard universal melt-blown pads. Pricing stratifies across premium, standard, and economy tiers based on certification grade and disposal documentation depth. Cost compression in standard universal kits is intensifying because petrochemical feedstock volatility erodes melt-blown nonwoven margins. Small and mid-sized facilities with limited safety staff exhibit highest price sensitivity, while pharmaceutical cleanrooms with audit-intensive procurement show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for North American kit distributors sourcing absorbent substrates. Manufacturing gravity centers on China, the United States, and Germany for polypropylene melt-blown production, fluorine-free formulation R&D, and regulatory-compliant assembly respectively. Raw material dependencies rest on polypropylene resin, silica aerogel precursors, and pH-neutralizing chemical agents. Single-source vulnerability concentrates in Shandong and Zhejiang provinces where melt-blown capacity clusters. Distribution runs through traditional safety supply houses with technical service capabilities, though e-commerce platforms are disintermediating standard universal kit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spill kits market functions as a service-attach opportunity where training, certification documentation, and scheduled replenishment programs expand faster than hardware unit sales. Recurring revenue from OSHA HAZWOPER compliance audit support and absorbent disposal logistics is capturing preference share in multi-site manufacturing procurement.
For Market Incumbents: Harden fluorine-free certification pipelines against REACH Annex XVII and state-level PFAS restriction timelines to preempt substrate obsolescence. Expand backward integration into polypropylene melt-blown manufacturing to defend margin position against resin price volatility. Channel control through distributor technical service relationships remains the critical lever for specification authority in national account procurement.
For New Entrants and Emerging Players: Mid-market pharmaceutical manufacturing facilities in India represent the most penetrable entry point given PLI scheme capacity buildout and nascent spill-response infrastructure. Biobased absorbent substrates paired with compostable packaging address circular economy procurement criteria in European sustainability-focused buyers. Direct e-commerce procurement of standard universal kits offers a go-to-market angle bypassing incumbent distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fluorine-free formulation development as third-party validation cycles compress and substrate platforms standardize. Acquisition targets with established EPA and REACH disposal documentation capabilities offer durable competitive positioning through regulatory compliance integration. The signal to watch is marine oil spill liability mandate expansion across Southeast Asian port authorities as an inflection indicator for boom-intensive specialty kit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation Certification | REACH Annex XVII compliance locks in European chemical processor procurement specifications ahead of competitors. |
| Backward Integration into Melt-Blown Production | Captive polypropylene resin processing insulates margin structure from crude oil benchmark volatility. |
| Marine Kit Configuration Expansion | Singapore and Rotterdam port authority mandates create boom-intensive specialty kit volume pools. |
| E-Commerce Platform Partnership | Industrial MRO platform integration disintermediates traditional safety distributors for standard universal kits. |
| Biobased Substrate Development | Cellulosic and mycelium-derived absorbents address circular economy criteria in sustainability-driven procurement. |
Research Methodology
A spread of perspectives from plant safety managers, EHS procurement directors, absorbent material R&D leads, and distributor technical sales representatives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with facility-level decision-makers and channel partners across the United States, Germany, China, and India. Secondary validation drew from EPA SPCC guidance documents, OSHA enforcement data, REACH registration databases, and customs trade records for polypropylene nonwoven imports. Bottom-up facility inventory estimates and top-down market sizing triangulated on volume projections.
Demand-supply balance modeling anchored the analytical framework across the analysis window, with segmentation by hazard class, absorbent format, end-use environment, and distribution channel. Patient-level kit replenishment rates, OSHA audit cycle frequencies, and marine liability mandate adoption curves informed the projection mechanics. CAGRs derived from segment-level growth differentials weighted by procurement concentration in chemical processing, pharmaceutical manufacturing, and port authority specifications.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, polypropylene resin availability, or PFAS regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about fluorine-free substrate adoption timelines and REACH disposal classification stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market