
 Hearing Protection Devices Market | 2026-2036
Hearing Protection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Protection Devices Market Analysis
Modular hearing protection bundling is shifting buyer choice toward configurable systems that combine passive attenuation with electronic communication modules. 3M leverages its dual expertise in industrial adhesives and audio electronics to dominate integrated earmuff platforms. Honeywell International Inc. anchors North American distribution through its deep channel relationships with safety distributors. Dynamic Ear Company specializes in custom-molded solutions that differentiate on fit precision for professional musicians.
Hearing protection devices are personal protective equipment designed to attenuate acoustic energy through foam, silicone, or thermoplastic elastomer barriers, typically rated by Noise Reduction Ratio values between 15 and 33 decibels, serving to prevent noise-induced hearing loss in occupational and recreational environments. Earplugs occupy the highest volume tier due to disposability and low unit cost across construction and manufacturing floors. Noise-canceling headsets represent the fastest-expanding margin pool as military and aviation end users prioritize situational awareness alongside hearing conservation. Custom devices command premium positioning where audiologist-fitted solutions serve musicians and competitive shooters requiring precise frequency response.
OSHA mandates permissible exposure limits that compel employers to implement hearing conservation programs when noise exceeds 85 decibels over eight-hour time-weighted averages, directly institutionalizing device procurement. The EU Green Deal and REACH frameworks increasingly scrutinize chemical composition in foam earplug manufacturing, reshaping material selection toward bio-based alternatives. Stakeholders must monitor evolving certification harmonization between ANSI S12.6 and ISO 4869 testing protocols to anticipate which product architectures will secure cross-border market access.
Market Dynamics
OSHA's tightening noise exposure enforcement is compressing procurement cycles across manufacturing and construction sectors, forcing employers to upgrade from passive foam plugs to electronic attenuation systems with integrated communication capabilities.
Growth Catalysts
- OSHA Hearing Conservation Mandates:The Occupational Safety and Health Administration requires employers to implement hearing conservation programs when workplace noise exceeds 85 decibels over eight-hour time-weighted averages, institutionalizing recurring device procurement across heavy industry.
- Smart Earmuff Convergence:Integration of active noise cancellation with two-way radio and Bluetooth communication modules is displacing standalone PPE purchases in defense and aviation maintenance operations.
- REACH Chemical Scrutiny:The European Chemicals Agency's expanding restrictions on polyurethane foam precursors are accelerating bio-based elastomer adoption in disposable earplug manufacturing.
Market Restraints
- Petrochemical Feedstock Volatility:Thermoplastic elastomer and silicone resin prices fluctuate with crude oil indices, compressing margins on custom-molded hearing protection devices.
- Testing Protocol Fragmentation:Divergence between ANSI S12.6 and ISO 4869 certification standards forces manufacturers to maintain dual testing regimens, adding cost to cross-border product launches.
- Reusable Electronic Substitution:Noise-canceling consumer earbuds from Apple and Sony are encroaching on entry-level industrial hearing protection in light-manufacturing environments.
Strategic Opportunities
- India Manufacturing Expansion:Bureau of Indian Standards certification harmonization with ISO frameworks is opening procurement pathways for export-oriented suppliers in automotive and textile hubs near Pune and Chennai.
- Audiologist Channel Integration:Direct partnerships with hearing health clinics create recurring revenue streams through custom-molded device refitting and replacement cycles.
- EU Green Deal Alignment:Bio-based foam formulations qualifying for EU Green Deal procurement preferences secure preferential placement in public-sector construction tenders.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Specialized expertise in psychoacoustic frequency response tuning for situational awareness applications concentrates in defense contractor supply chains.
- Multi-Protocol Certification Timelines:Simultaneous FCC radio approval, OSHA NRR validation, and CE marking for electronic earmuffs extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Protection Devices Market |
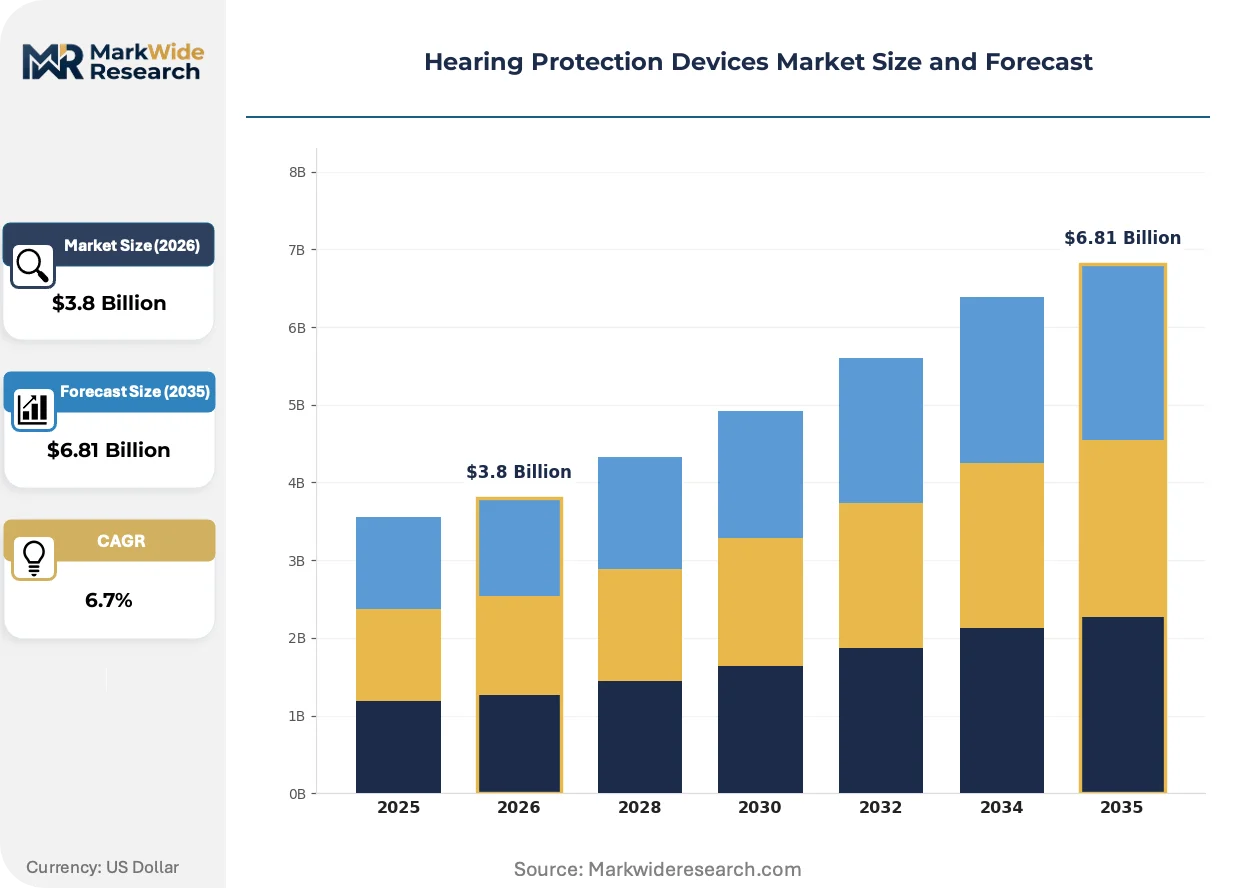
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earplugs, Earmuffs, Noise-Canceling Headsets, Custom Devices End User: Construction Workers, Musicians, Military Personnel, Industrial Workers Application: Noise Reduction, Hearing Conservation, Communication Enhancement, Safety Compliance Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | MSA Safety Incorporated, Dynamic Ear Company, 3M, DELTA PLUS CORP., Amplifon, Honeywell International Inc., Centurion Safety Products Ltd., Etymotic Research, Inc., Moldex-Metric Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Protection Devices Market Emerging Trajectories
Digital signal processing architectures are compressing the performance gap between industrial-grade and consumer hearing protection, enabling new form factors that blend occupational safety with recreational audio functionality.
Directional microphone arrays with AI-driven ambient sound classification are rewriting how military and law enforcement personnel manage auditory situational awareness. Defense procurement offices in the United States and United Kingdom are field-testing systems that attenuate impulse noise while preserving speech intelligibility and environmental cues. This capability compression is collapsing the historical separation between hearing conservation and tactical communication equipment.
REACH framework amendments targeting isocyanate content in polyurethane foams are forcing material substitutions across European manufacturing supply chains. ECHA pre-registration deadlines for alternative elastomer chemistries are compressing R&D timelines for disposable earplug producers. German and French safety distributors are prioritizing inventory positions that anticipate 2026-2027 compliance thresholds.
Buying committees at multinational construction firms are consolidating hearing protection procurement under centralized safety category managers, displacing site-level purchasing autonomy. Tier-1 contractors in the United States are mandating vendor-managed inventory programs with real-time consumption tracking. This concentration pattern is most visible in commercial infrastructure projects across Texas and Florida where general contractors self-perform trade labor.
Hearing Protection Devices Market Segmentation
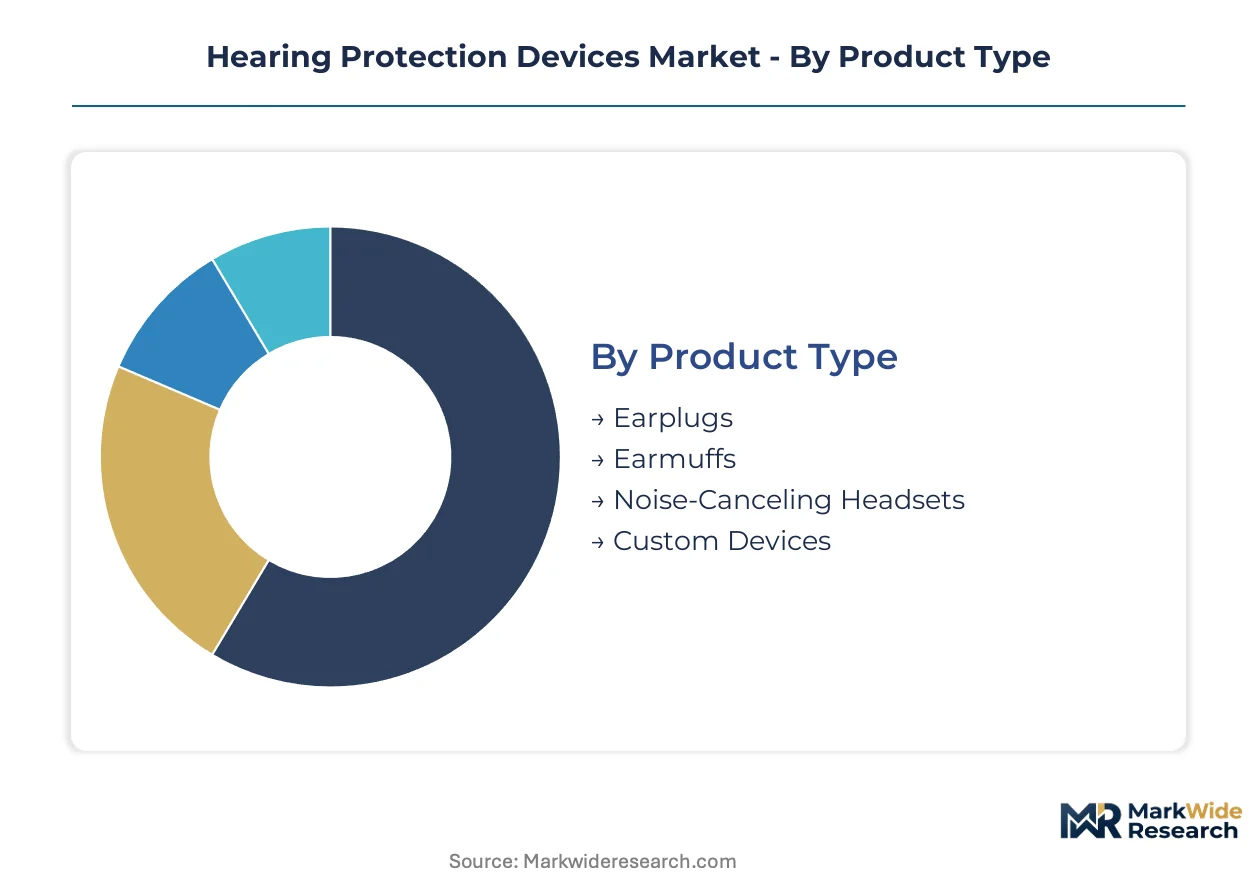
Hearing protection devices fragment across four distinct segmentation axes that reflect divergent procurement economics. Product architecture determines whether buyers prioritize disposability or durability, while end-user identity shapes regulatory compliance requirements and feature specifications.
Product Type:
Volume tiers separate commodity foam disposables from premium electronic systems with integrated communication modules.
- Earplugs:Disposable foam or silicone inserts rated for 15-33 decibel Noise Reduction Ratios dominate procurement volumes across manufacturing floors. Construction contractors in Texas and Florida mandate bulk purchasing programs with real-time consumption tracking, compressing unit economics toward the low end of the price spectrum.
- Noise-Canceling Headsets:Active noise cancellation combined with directional microphone arrays and Bluetooth connectivity commands the steepest expansion trajectory. Defense procurement offices in the United States and United Kingdom field-test systems that attenuate impulse noise while preserving speech intelligibility, collapsing the historical separation between hearing conservation and tactical communication equipment.
- Earmuffs:Passive attenuation devices with thermoplastic or metal headbands serve as the standard-issue solution for intermittent noise exposure. OSHA compliance audits in automotive stamping plants drive replacement cycles for damaged suspension components.
- Custom Devices:Audiologist-fitted silicone or acrylic molds deliver precise frequency response for professional musicians and competitive shooters. Dynamic Ear Company anchors European supply through direct clinic partnerships that create recurring refitting revenue.
Mature deployment sits with earplugs across heavy industry. Newer deployment is concentrated in noise-canceling headsets where defense and aviation maintenance operations converge on integrated platforms.
End User:
Regulatory exposure and injury liability risk stratify buyer sophistication across occupational categories.
- Industrial Workers:Manufacturing plant employees face the most intensive OSHA enforcement scrutiny, institutionalizing recurring device procurement when eight-hour time-weighted averages exceed 85 decibels. Metal fabrication facilities near Detroit and Pittsburgh maintain vendor-managed inventory programs with automated reorder triggers.
- Military Personnel:Impulse noise from firearms and explosive ordnance demands specialized attenuation that preserves situational awareness. Directional microphone arrays with AI-driven ambient sound classification are rewriting tactical auditory management for law enforcement and defense applications.
- Construction Workers:Project-based employment and high turnover favor low-cost disposables over fitted systems. Tier-1 contractors self-performing trade labor in commercial infrastructure are consolidating procurement under centralized safety category managers.
- Musicians:Frequency fidelity requirements distinguish this segment from industrial noise blocking. Custom-molded solutions from audiologist channels command premium positioning where precise acoustic response outweighs maximum attenuation.
Procurement standardization runs deepest among industrial workers with established hearing conservation programs. Capability complexity climbs fastest among military personnel as defense agencies integrate communication and protection functions.
Application:
Use case specificity determines whether buyers prioritize attenuation performance, regulatory documentation, or functional augmentation.
- Noise Reduction:Baseline acoustic attenuation remains the dominant specification across construction and manufacturing procurement. Foam earplugs and passive earmuffs satisfy this requirement at the lowest unit cost.
- Safety Compliance:OSHA-mandated hearing conservation programs require documented fit testing and training records, not merely device provision. Employers upgrade to electronic attenuation systems that log usage data for audit defense.
- Hearing Conservation:Long-term occupational health programs emphasize consistent proper use over maximum rated attenuation. Industrial hygienists specify devices that workers will actually wear throughout full shifts.
- Communication Enhancement:Two-way radio and Bluetooth integration transforms hearing protection from barrier to productivity tool. Aviation maintenance operations and defense field units prioritize this capability over pure attenuation metrics.
Functional complexity concentrates in communication enhancement applications. Baseline noise reduction retains the largest procurement volume.
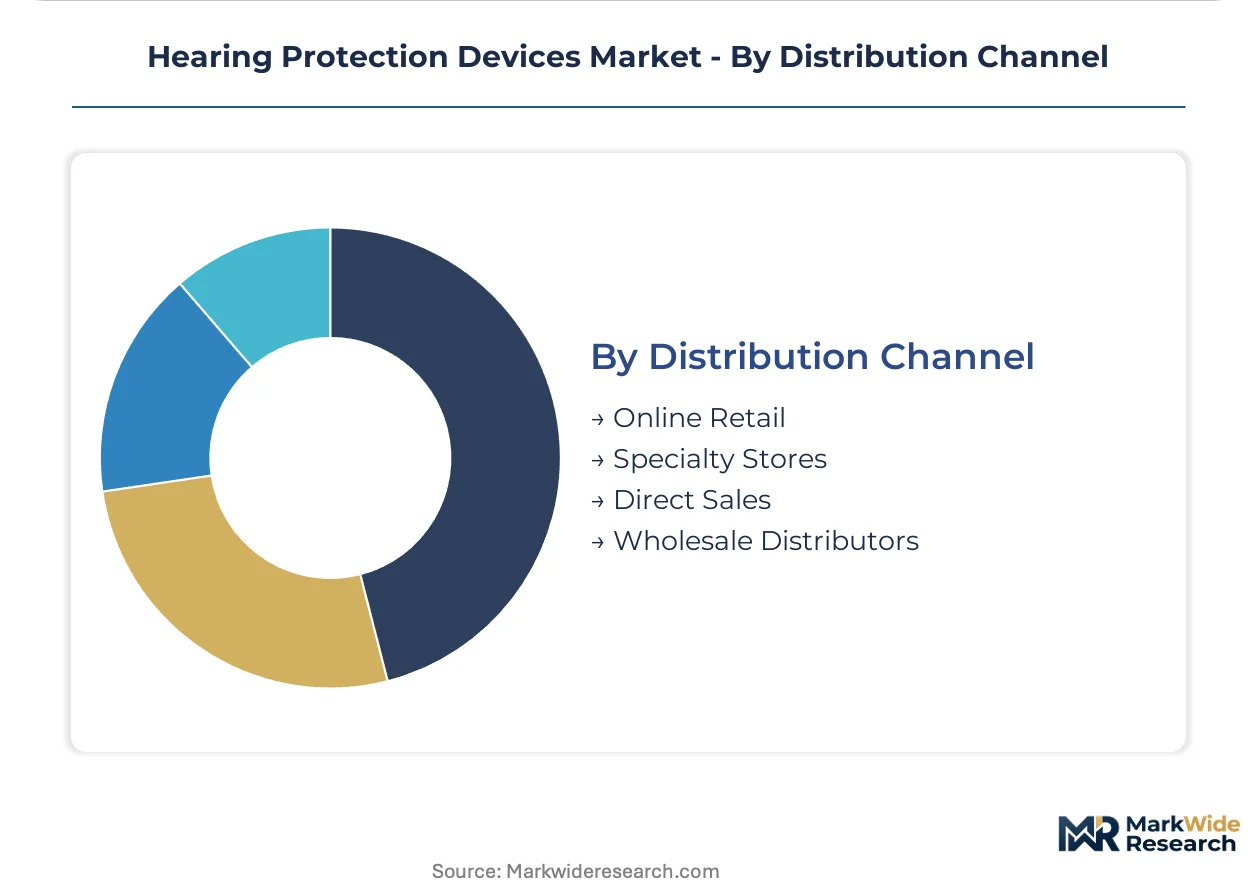
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and inventory management sophistication.
- Wholesale Distributors:Industrial safety distributors with deep channel relationships anchor North American supply for construction and manufacturing accounts. Honeywell International Inc. leverages these partnerships for broad market coverage.
- Direct Sales:Large enterprise accounts with centralized safety management negotiate vendor-managed inventory programs directly with manufacturers. Real-time consumption tracking and automated replenishment characterize these relationships.
- Specialty Stores:Audiologist clinics and professional audio retailers serve the custom-molded and musician segments with fitting services and frequency response testing. Direct partnerships with hearing health clinics create recurring revenue through replacement cycles.
- Online Retail:Consumer-grade electronic hearing protection and replacement foam disposables move through e-commerce platforms. Apple's noise-canceling consumer earbuds encroach on entry-level industrial protection in light-manufacturing environments.
Relationship depth differentiates wholesale distributors and direct sales channels. Transactional efficiency drives online retail for standardized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for hearing protection devices sits in North American and European industrial corridors, while consumption growth accelerates in Asian automotive and defense hubs. Supply chains for foam substrates and electronic modules remain anchored in established chemical and semiconductor ecosystems.
United States
Defense procurement offices and commercial construction drive sophisticated demand for integrated communication-enabled systems. OSHA enforcement tightening across automotive stamping plants near Detroit and Pittsburgh compels employers to upgrade from passive foam to electronic attenuation with usage logging. Texas and Florida infrastructure contractors now mandate vendor-managed inventory programs with automated replenishment triggers.
Germany
REACH framework amendments targeting isocyanate content in polyurethane foams are accelerating bio-based elastomer substitution across disposable earplug supply chains. ECHA pre-registration deadlines for alternative chemistries compress R&D timelines for manufacturers serving EU public-sector construction tenders. Industrial safety distributors in the Ruhr region prioritize inventory positions anticipating 2026-2027 compliance thresholds.
China
Domestic automotive production expansion and military modernization programs are converging demand for noise-canceling headsets with situational awareness capabilities. MIIT standards harmonization with ISO 4869 testing protocols is reshaping which product architectures secure state-owned enterprise procurement. Manufacturing clusters in the Yangtze River Delta are scaling thermoplastic elastomer molding capacity for both domestic use and export-oriented suppliers.
India
Bureau of Indian Standards certification alignment with ISO frameworks is opening procurement pathways for export-oriented suppliers in automotive and textile hubs near Pune and Chennai. Central government industrial safety mandates are institutionalizing hearing conservation program requirements across metal fabrication and heavy machinery sectors. State-level factory inspection intensification in Maharashtra and Gujarat is compressing employer upgrade cycles from basic foam plugs to fitted systems.
United Kingdom
Defense field-testing of directional microphone arrays with AI-driven ambient sound classification is rewriting tactical auditory management specifications for law enforcement and military applications. UK Ministry of Defence procurement convergence with NATO interoperability standards is favoring integrated platforms over standalone hearing protection. Scottish and Northern English manufacturing bases are supplying passive earmuff components for European distribution networks.
Hearing Protection Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven industrial safety conglomerates, audiologist-channel custom molders, and defense-electronics integrators. Three archetypes dominate: diversified PPE platforms leveraging distribution depth, precision-fit specialists capturing premium musician and shooter segments, and tactical communication vendors collapsing protection and connectivity functions. Competitive moves concentrate on certification harmonization investments and audiologist channel partnerships that create recurring replacement revenue.
Within the diversified PPE tier, 3M and Honeywell International Inc. represent scale-driven archetypes with industrial safety distribution anchoring broad market coverage. Dynamic Ear Company exemplifies the precision-fit specialist model through direct clinic partnerships. MSA Safety Incorporated occupies a position bridging industrial and tactical applications. These three entities illustrate how competitive positioning separates commodity volume plays from premium custom solutions and integrated electronic platforms.
| Leading Market Players |
|---|
| MSA Safety Incorporated |
| Dynamic Ear Company |
| 3M |
| DELTA PLUS CORP. |
| Amplifon |
| Honeywell International Inc. |
| Centurion Safety Products Ltd. |
| Etymotic Research, Inc. |
| Moldex-Metric Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into foam substrate production anchors supply security for dominant manufacturers while compressing procurement costs for high-volume disposable earplug lines. 3M and Honeywell International Inc. leverage captive thermoplastic elastomer compounding facilities to buffer margin erosion from petrochemical feedstock volatility, translating upstream control into pricing power against fragmented distributors.
Pricing Analysis
Cost-down pressure on commodity foam disposables accelerates because construction contractors in Texas and Florida mandate vendor-managed inventory programs with automated replenishment triggers. Three-tier pricing structure across premium electronic systems, standard passive earmuffs, and economy foam disposables stratifies by certification tier and communication capability. Margin tightening runs through custom-molded musician segments as audiologist channel fees absorb pricing power. Industrial buyers exhibit highest price sensitivity, while defense procurement offices prioritize situational awareness functionality over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's Bureau of Indian Standards certification are reshaping sourcing patterns for export-oriented suppliers near Pune and Chennai. Thermoplastic elastomer and silicone resin supply concentrates in Germany, China, and the United States, with acoustic foam substrate production anchored in established chemical corridors. Feedstock costs hinge on crude oil indices, exposing margin compression risk. Distribution runs through industrial safety distributors with deep channel relationships, supplemented by direct sales for large enterprise accounts with centralized safety management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active noise cancellation with integrated communication modules is displacing passive foam plugs across defense and aviation maintenance operations, compressing the technology-transition window for legacy manufacturers.
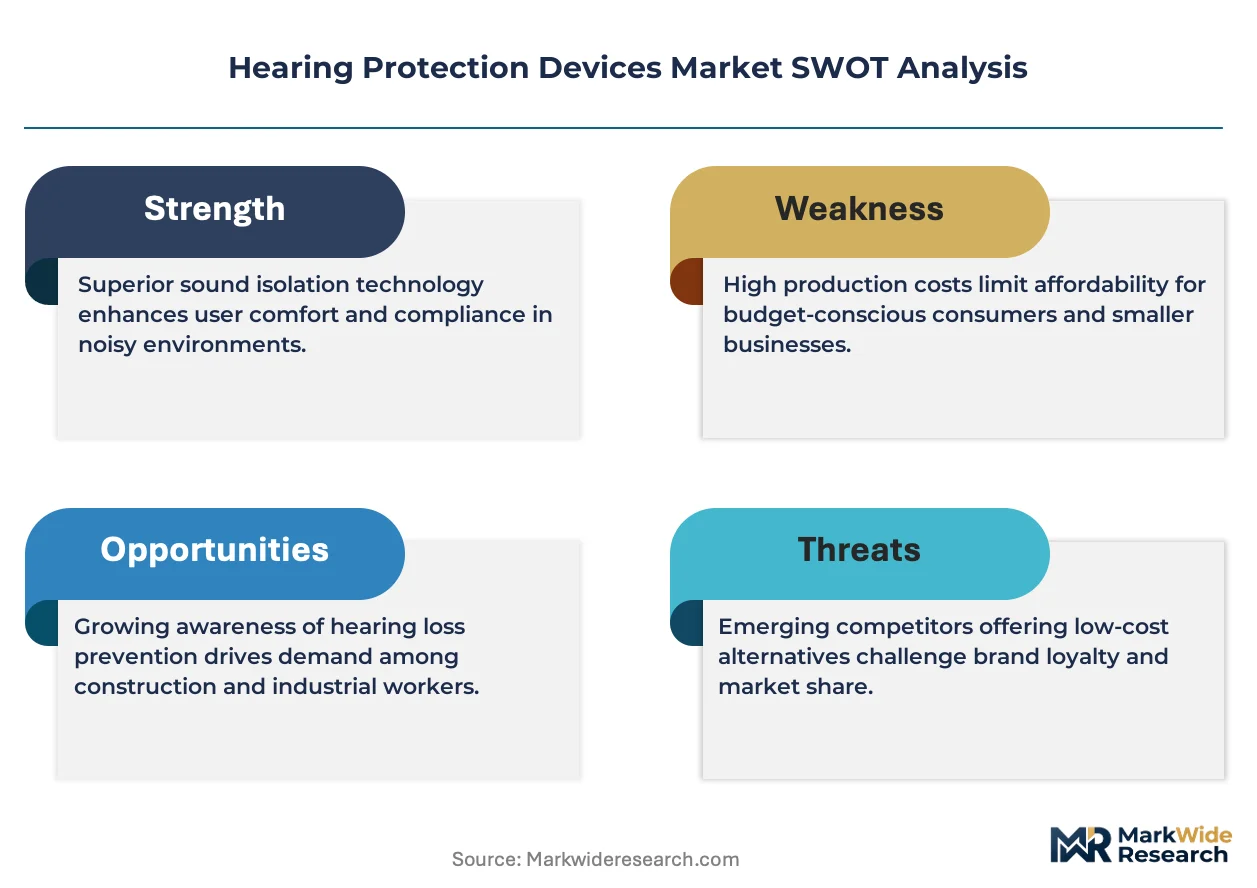
For Market Incumbents: Lock in audiologist channel partnerships through exclusive clinic agreements that create recurring replacement revenue streams. Invest in simultaneous FCC radio approval and OSHA NRR validation to compress multi-protocol certification timelines that currently extend product launch cycles. Defend against consumer electronics encroachment by emphasizing occupational compliance documentation that consumer earbuds cannot provide.
For New Entrants and Emerging Players: AI-driven ambient sound classification technology offers entry into military and law enforcement segments where defense procurement offices field-test next-generation systems. Target India manufacturing expansion as Bureau of Indian Standards harmonization opens procurement pathways in automotive and textile hubs. Pursue direct sales relationships with tier-1 contractors consolidating hearing protection under centralized safety category managers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified PPE platforms seeking electronic integration capabilities or by defense-electronics integrators collapsing protection and communication functions. Long-term viability favors vendors with established certification harmonization investments and audiologist network control. Monitor REACH framework amendment timelines for isocyanate restrictions as inflection indicator for bio-based elastomer substitution winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Simultaneous FCC, OSHA, and CE marking compresses launch timelines for electronic earmuffs. |
| Audiologist Channel Partnership | Direct clinic agreements create recurring revenue through custom-molded device replacement cycles. |
| Bio-Based Foam Formulation | REACH-compliant alternatives secure preferential placement in EU public-sector construction tenders. |
| Defense Communication Integration | Two-way radio and Bluetooth modules transform hearing protection into tactical productivity equipment. |
| Vendor-Managed Inventory Program | Real-time consumption tracking locks in construction contractor procurement consolidation. |
Methodological Framework
Independent corroboration across safety equipment distributors, industrial hygienists, and defense procurement officers underwrites the qualitative findings on buyer behavior and specification trends. Primary interviews with audiologists, plant engineers at automotive stamping facilities, and category managers at tier-1 construction contractors combine with secondary validation from OSHA enforcement records, ECHA pre-registration databases, and Bureau of Indian Standards certification filings. Bottom-up demand modeling triangulates against top-down market sizing across product architecture and end-user segments.
Comparable-period anchoring to historical OSHA compliance audit intensification patterns and defense procurement cycle timing shapes the projection horizon. Segmentation dimensions span product type, end-user identity, application specificity, and distribution channel structure, with regional regulatory cluster as an additional modeled axis. CAGRs derive from fitted trend extrapolation adjusted for technology substitution rates and certification timeline compressions. Industry-specific forecast inputs include petrochemical feedstock price indices and ECHA amendment implementation schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between ANSI S12.6 and ISO 4869 protocols, breakthrough consumer electronics performance parity, and geopolitical disruption of thermoplastic elastomer supply corridors. Forecasts reflect documented assumptions about OSHA enforcement continuity and REACH amendment adherence timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market