
 Cut Resistant Gloves Market | 2026-2036
Cut Resistant Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Cut Resistant Gloves Market Analysis
ANSI/ISEA Level A6 and above specifications is redrawing competitive dynamics in protective handwear. Ansell Limited leverages its integrated fiber-to-glove manufacturing to sustain premium positioning across North American industrial channels. Honeywell International Inc anchors its portfolio through proprietary engineered yarn blends that dominate aerospace and metal fabrication procurement. Superior Glove Works Ltd specializes in made-to-measure programs for oil and gas field operators, occupying a defensible niche against mass-market suppliers.
Cut resistant gloves incorporate high-tenacity fibers such as UHMWPE, para-aramid, or stainless steel wire engineered into knit or woven structures rated by gram-weight blade resistance under EN 388 or ANSI/ISEA protocols, serving primarily to prevent laceration trauma in material handling and assembly operations. UHMWPE-based products are capturing share from traditional steel fiber constructions as manufacturers seek lighter weight with equivalent cut protection ratings. Glass handling and automotive assembly applications are outpacing construction in volume growth due to precision-handling requirements and just-in-time line constraints that penalize injury downtime.
OSHA enforces updated hand protection standards under 29 CFR 1910.138, while the EU PPE Regulation 2016/425 mandates CE marking with EN 388:2016+A1:2018 cut resistance testing for market access. These frameworks compel distributors to maintain certified inventory and push end-users toward documented hazard assessments rather than commodity purchasing. Stakeholders must monitor evolving fiber recycling regulations and emerging bio-based aramid alternatives that could reset material cost structures and supplier qualification timelines.
Market Dynamics
OSHA enforcement of updated 29 CFR 1910.138 hand protection standards is compressing procurement cycles and forcing distributors toward higher-cut-level certified inventory, fundamentally restructuring buyer-supplier relationships across North American industrial channels.
Growth Catalysts
- ANSI/ISEA Level A6+ specification:Automotive assembly lines in Germany and the United States are expanding procurement of higher-cut-level gloves to minimize laceration downtime in just-in-time manufacturing environments.
- East Asian manufacturing clusters:Export-oriented industrial zones in Vietnam and China are driving concentrated demand as foreign direct investment flows into precision assembly operations requiring certified hand protection.
- EU PPE Regulation 2016/425:CE marking mandates with EN 388:2016+A1:2018 testing protocols are compelling documented hazard assessments that favor premium certified products over commodity alternatives.
Market Restraints
- UHMWPE fiber supply concentration:Specialized high-tenacity fiber production concentrates among limited chemical manufacturers, creating input cost volatility and qualification bottlenecks for glove producers.
- Stainless steel wire substitution ceiling:Traditional steel fiber constructions retain cost advantages in heavy metal fabrication where weight penalties are tolerable, limiting full displacement by advanced polymers.
- CE marking compliance friction:Extended third-party testing timelines and notified body capacity constraints delay market entry for new product variants within European distribution channels.
Strategic Opportunities
- Glass handling precision applications:Solar panel manufacturing and architectural glazing operations are creating demand for ultra-thin, high-dexterity cut-resistant gloves that balance protection with tactile sensitivity.
- Bio-based aramid alternatives:Emerging fiber recycling regulations and sustainable material mandates in European jurisdictions are opening qualification pathways for circular-economy compliant product lines.
- Direct-to-industrial procurement platforms:Digital channels are disintermediating traditional safety distributors, enabling manufacturers to capture margin through subscription-based replacement programs.
Industry Challenges
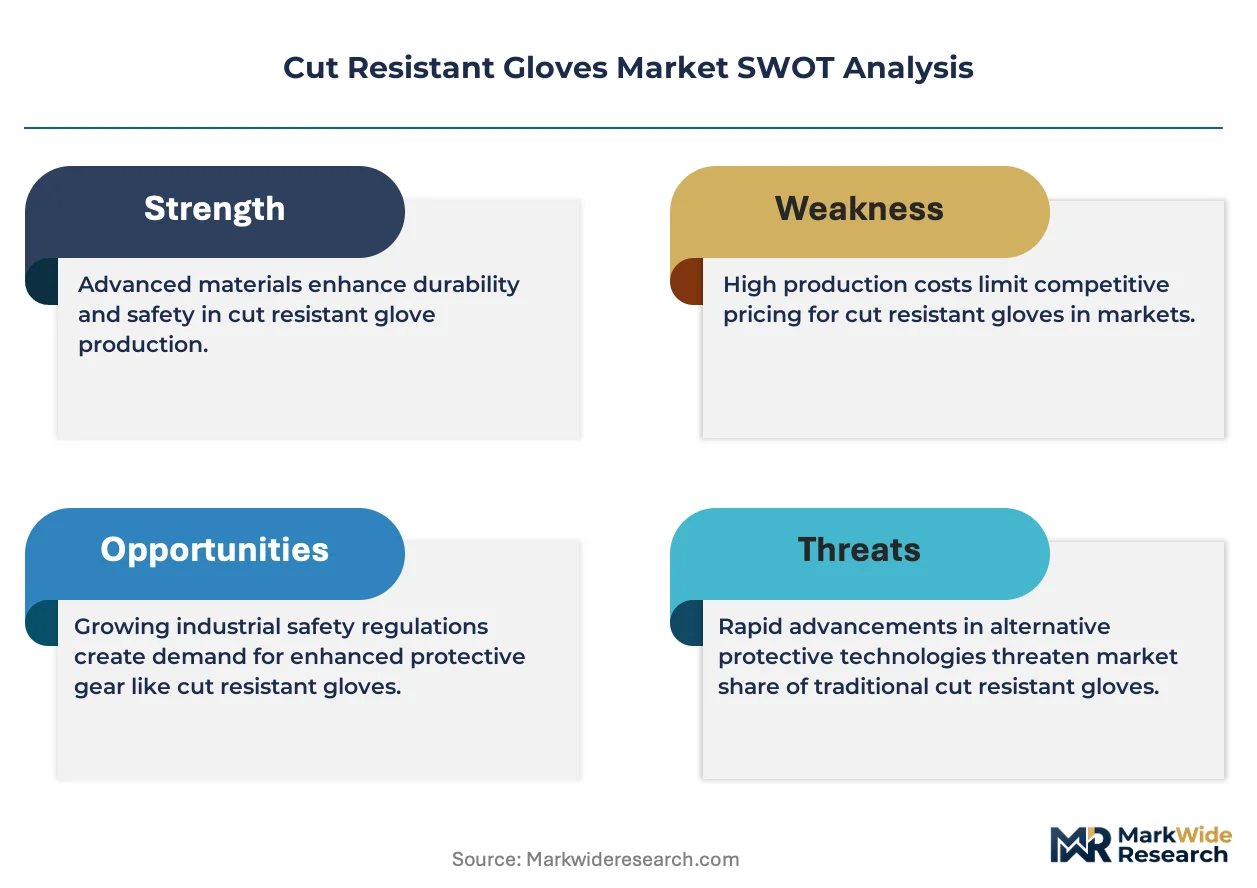
- Multi-standard certification complexity:Concurrent ANSI/ISEA and EN 388 rating systems require dual testing protocols, extending product development timelines and increasing qualification costs for global market access.
- Specialized knitting equipment capex:Precision seamless glove production demands capital-intensive automated knitting machinery, creating barriers for mid-scale entrants seeking to match incumbent manufacturing quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cut Resistant Gloves Market |
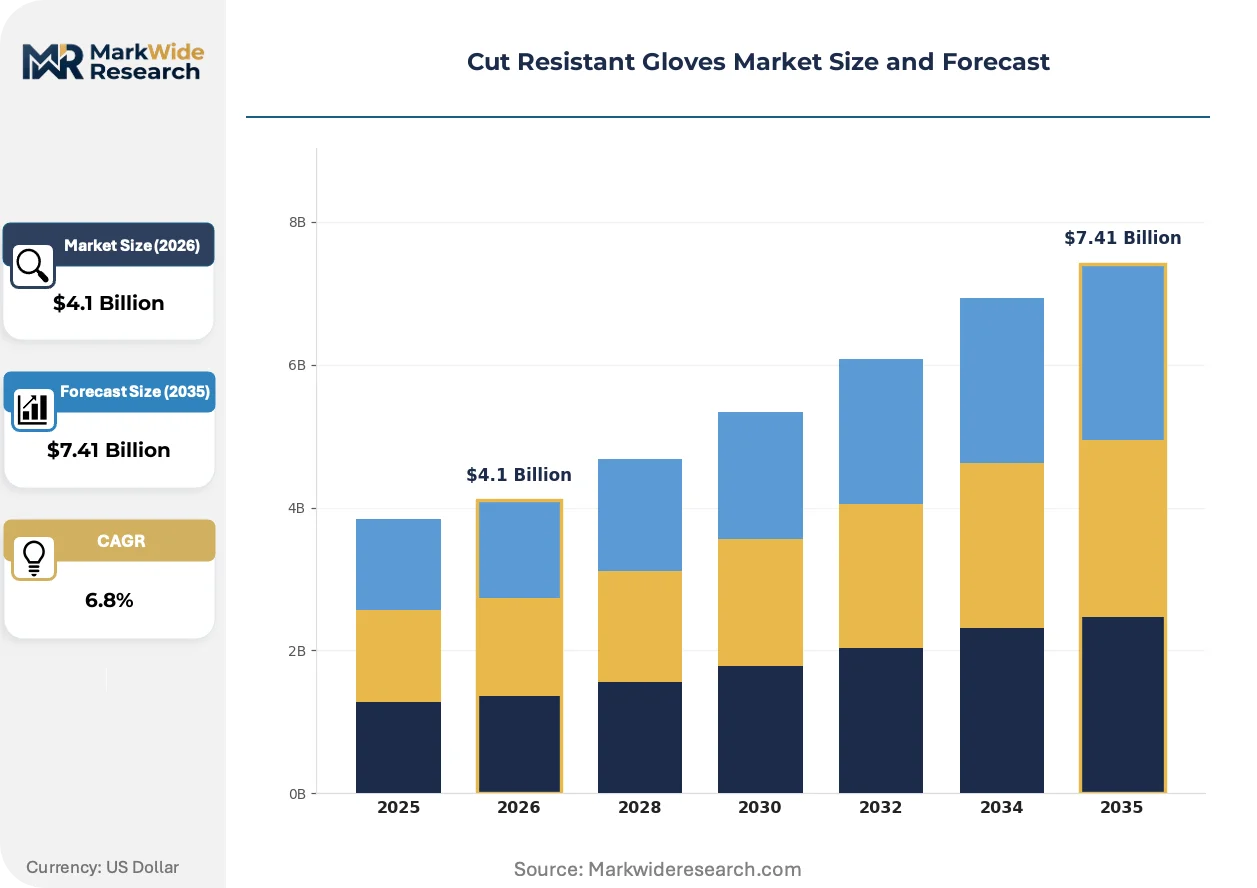
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Kevlar, Steel Fibers, UHMWPE, Nylon Application: Construction, Manufacturing, Automotive, Glass Handling End User: Industrial Workers, Healthcare Professionals, Food Processing, Construction Workers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Ansell Limited, Honeywell International Inc, 3M Company, Superior Glove Works Ltd, SHOWA Group, Magid Glove & Safety Manufacturing Co. LLC, MCR Safety, Kimberly-Clark Corporation, Protective Industrial Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cut Resistant Gloves Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are actively restructuring how cut-resistant hand protection is engineered, certified, and procured across industrial end-uses.
UHMWPE-based engineered yarn technology is bifurcating the protective glove market between lightweight high-performance segments and legacy steel-reinforced alternatives. Aerospace and precision automotive assembly buyers are adopting these advanced polymer constructions at accelerated rates to reduce hand fatigue during extended shift operations. This material transition is compressing demand for traditional steel-wire gloves in weight-sensitive applications while creating premium pricing tiers around gram-weight blade resistance performance.
REACH substance restrictions and evolving EU Green Deal circularity requirements are mandating fiber traceability and end-of-life recyclability disclosures for PPE market access. Industrial buyers in German and French manufacturing clusters now require documented supply chain environmental compliance as a procurement gate. Glove manufacturers are responding by integrating recycled content certifications and chemical hazard disclosures into product data sheets ahead of formal regulatory deadlines.
Certification-driven preference shifts are displacing price-primary procurement models in safety-critical industrial verticals. Oil and gas field operators and metal fabrication shops are unbundling glove purchasing from bundled safety supplier contracts to specify ANSI/ISEA cut levels independently. This behavioral change is most visible across United States Gulf Coast petrochemical corridors where documented hazard assessments now precede volume purchasing decisions.
Cut Resistant Gloves Market Segmentation
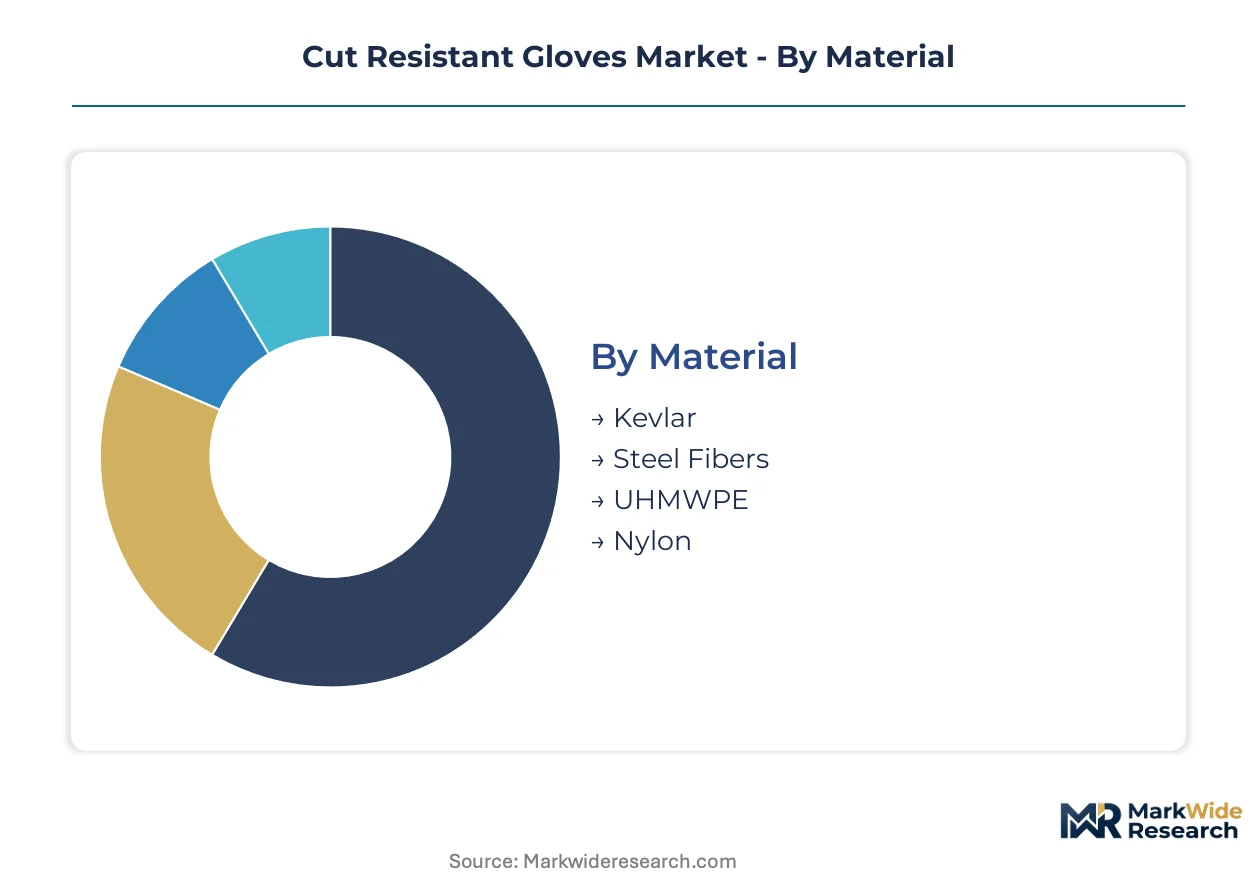
Cut-resistant glove procurement diverges sharply across material technologies and end-use hazards, with substitution dynamics between fiber types and application-specific dexterity requirements driving portfolio decisions. Understanding segment-level demand concentration helps suppliers align certification investments against actual procurement volumes rather than perceived market size.
Material:
UHMWPE formulations are displacing incumbent steel fiber constructions in weight-sensitive applications, while Kevlar retains defensible positions in heat-exposed environments where thermal resistance compounds cut protection requirements.
- Kevlar:Para-aramid fiber construction delivers combined cut and thermal protection rated to 350°C contact temperatures. Demand concentrates in foundry operations and metal forging facilities across German industrial clusters where EN 407 heat resistance certification accompanies cut ratings.
- Steel Fibers:Stainless steel wire knit structures provide economical ANSI A2-A4 protection in heavy metal fabrication where weight penalties are operationally tolerable. Shipbreaking yards in Bangladesh and Pakistani scrap metal processors maintain procurement volume despite polymer substitution pressure in developed markets.
- UHMWPE:Ultra-high molecular weight polyethylene yarns achieve ANSI A5-A9 ratings at 40% lower weight than steel equivalents. Automotive assembly lines in Stuttgart and Detroit have standardized on UHMWPE for precision fastening tasks where hand fatigue accumulates across 10-hour shifts.
- Nylon:Baseline synthetic knit provides minimal cut resistance (ANSI A1-A2) primarily as a comfort liner or low-hazard handling glove. Warehouse picking operations in Vietnamese export zones specify nylon-dominant gloves for carton handling where abrasion rather than laceration dominates injury risk.
Steel fibers anchors the volume base while UHMWPE gains share at the steepest rate.
Application:
Glass handling precision requirements are compressing procurement timelines as solar panel manufacturing scales, while construction site specifications lag in standardization intensity compared to controlled factory environments.
- Construction:General building trades specify mid-tier ANSI A3-A4 gloves for framing, roofing, and masonry work where puncture resistance often supersedes pure cut protection. US residential construction contractors purchase through bundled safety suppliers with limited independent specification authority.
- Manufacturing:Broad industrial assembly spans electronics, textiles, and general fabrication where EN 388 Level C-F ratings suffice. Mexican maquiladora operations along the US border drive concentrated volume through cross-border distributor networks serving just-in-time automotive supply chains.
- Automotive:OEM assembly lines and tier-1 suppliers mandate ANSI A6+ ratings for powertrain and chassis operations involving stamped metal edges. Battery electric vehicle manufacturing in South Carolina and Bavaria is accelerating specification upgrades as new plants commission with elevated safety protocols.
- Glass Handling:Architectural glazing and solar panel production require ultra-thin ANSI A4-A6 gloves balancing tactile sensitivity with edge protection. Chinese photovoltaic manufacturers in Jiangsu province have created dedicated procurement categories for solar wafer handling gloves with sub-1mm thickness specifications.
Construction absorbs the highest absolute unit volume while glass handling commands the most rapid specification escalation.
End User:
Industrial worker procurement is fragmenting between centralized corporate safety programs and site-level purchasing autonomy, creating divergent channel strategies for identical product specifications.
- Industrial Workers:Manufacturing and logistics personnel constitute the core demand base across automotive, aerospace, and general fabrication. German Mittelstand engineering firms maintain strict centralized procurement through specified safety distributors with documented hazard assessment trails.
- Healthcare Professionals:Surgical and laboratory applications require sterile cut-resistant gloves for instrument handling and pathology work. US ambulatory surgery centers are expanding adoption as needlestick prevention protocols extend to scalpel and retractor handling.
- Food Processing:Poultry, meatpacking, and commercial bakery operations specify detectable blue or metal-impregnated gloves for contamination control. USDA-inspected facilities in Nebraska and Iowa mandate color-coded glove programs with documented change protocols.
- Construction Workers:Distributed workforce purchasing through retail channels contrasts with industrial centralized procurement. Australian residential builders purchase through hardware cooperative networks with limited technical specification support.
Industrial workers represent the established revenue core while healthcare professionals emerge as the fastest-expanding specification category.
Distribution Channel:
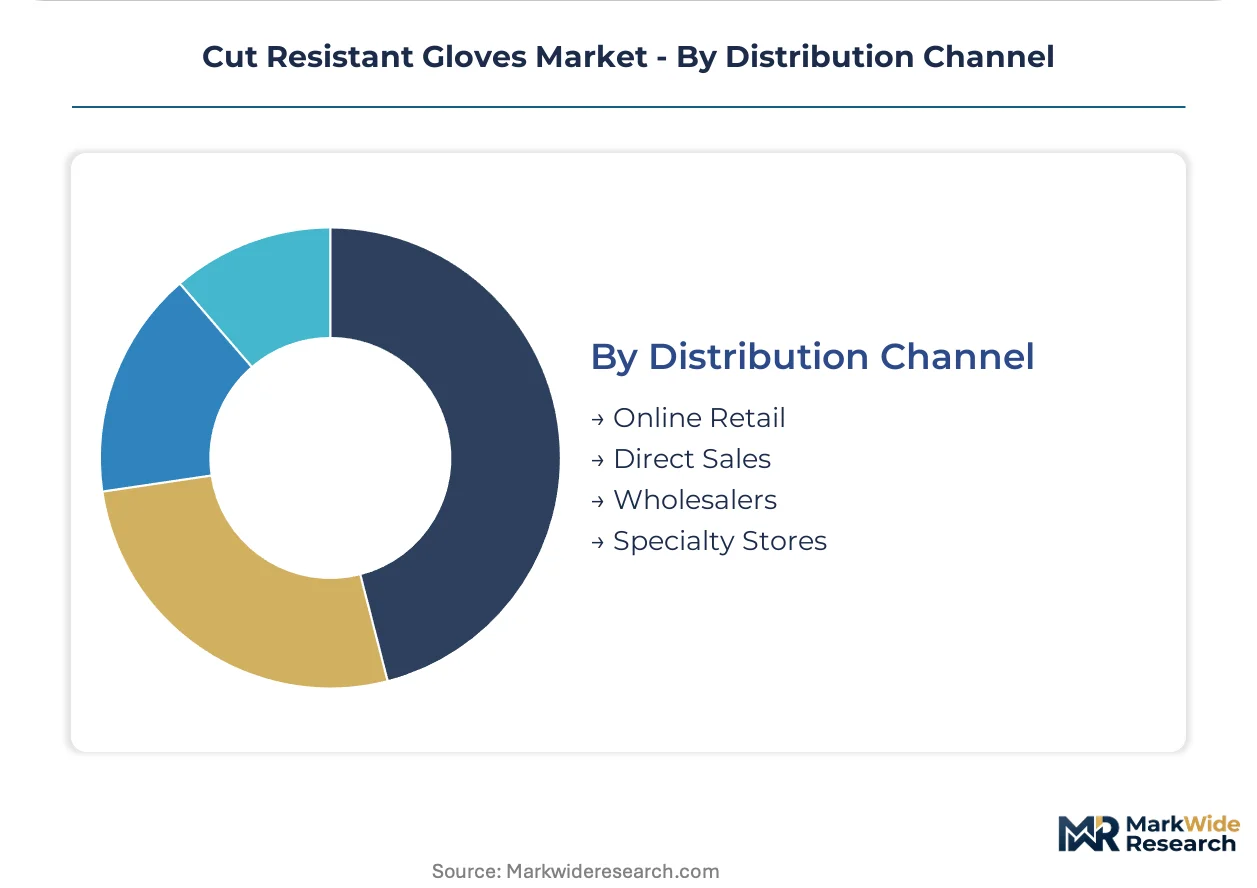
Direct sales relationships are capturing specification authority from traditional distributors as large industrial accounts unbundle safety procurement from general MRO purchasing.
- Online Retail:E-commerce platforms serve small-to-mid contractors and replacement purchasing with limited technical guidance. Amazon Business and Alibaba industrial channels are capturing construction and food service volume through price transparency and rapid replenishment.
- Direct Sales:Manufacturer field representatives engage Fortune 500 safety departments with custom fit programs and usage analytics. Honeywell and Ansell maintain dedicated automotive account teams in Detroit and Wolfsburg with quarterly business reviews.
- Wholesalers:Industrial distributors like Grainger and Würth hold inventory positions across ANSI rating tiers for immediate fulfillment. Their technical sales forces influence specification upgrades during contract renewals.
- Specialty Stores:Local safety equipment dealers provide fitting services and regional regulatory compliance guidance. French industrial zones around Lyon retain independent safety distributors with deep metallurgy sector relationships.
Wholesalers retain the volume foundation while direct sales captures the most rapid relationship deepening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized high-tenacity fiber production concentrates among limited chemical manufacturers in Germany, the United States, and Japan, creating input cost volatility that ripples through glove fabrication networks worldwide. This supply-side tightness shapes regional procurement strategies as buyers seek proximity to certified fiber sources.
United States
OSHA enforcement of updated 29 CFR 1910.138 standards is compressing procurement cycles across automotive assembly lines in Detroit and South Carolina. Battery electric vehicle manufacturing in these corridors is accelerating specification upgrades as new plants commission with elevated safety protocols. Gulf Coast petrochemical corridors now require documented hazard assessments before volume purchasing decisions.
Germany
EU PPE Regulation 2016/425 mandates CE marking with EN 388:2016+A1:2018 testing protocols that favor premium certified products. Stuttgart automotive clusters have standardized on ultra-high molecular weight polyethylene gloves for precision fastening tasks. Mittelstand engineering firms maintain strict centralized procurement through specified safety distributors.
China
Export-oriented industrial zones in Jiangsu province are driving concentrated demand for solar panel manufacturing gloves with sub-1mm thickness specifications. The country's national quality regulator enforces GB standards for occupational hand protection in manufacturing facilities. Photovoltaic manufacturers have created dedicated procurement categories for solar wafer handling applications.
Vietnam
Foreign direct investment flows into precision assembly operations are requiring certified hand protection across northern industrial provinces. Warehouse picking operations in export zones specify synthetic knit gloves for carton handling where abrasion dominates injury risk. Cross-border distributor networks serving just-in-time automotive supply chains are expanding inventory positions.
Cut Resistant Gloves Market Vendor Landscape
Concentration sits with integrated fiber-to-glove manufacturers and diversified industrial safety conglomerates that span multiple PPE categories. The market structure reflects a tiered hierarchy where premium positioning depends on proprietary engineered yarn capabilities and certified manufacturing scale. Two strategic archetypes dominate: vertically integrated specialists controlling upstream fiber supply, and broad-line safety suppliers leveraging distribution breadth. Competitive moves center on capacity expansion in high-cut-level certified production and strategic partnerships with automotive OEMs for direct specification authority.
Among the integrated specialists, Ansell Limited and Superior Glove Works Ltd exemplify divergent positioning strategies within premium industrial channels. Ansell represents the multinational scale archetype with captive fiber manufacturing and dedicated automotive account teams in Detroit and Wolfsburg. Superior Glove occupies a defensible niche as a made-to-measure program specialist for field operators in hazardous extraction environments. Honeywell International Inc anchors the diversified conglomerate tier, leveraging cross-product safety portfolios and proprietary yarn blends to dominate aerospace and metal fabrication procurement decisions.
| Leading Market Players |
|---|
| Ansell Limited |
| Honeywell International Inc |
| 3M Company |
| Superior Glove Works Ltd |
| SHOWA Group |
| Magid Glove & Safety Manufacturing Co. LLC |
| MCR Safety |
| Kimberly-Clark Corporation |
| Protective Industrial Products Inc. |
| Others |
Supply Flow & Price Mechanics
OSHA 29 CFR 1910.138 and EU PPE Regulation 2016/425 simultaneously gate supply qualification and price differentiation, forcing distributors to carry certified inventory that commands measurable premiums over uncertified alternatives while compressing procurement cycles toward higher-cut-level products.
Pricing Analysis
ANSI/ISEA and EN 388 certification tiers dictate the pricing tier structure across the cut resistant gloves market. Three-tier pricing structure across premium, standard, and economy levels separates ANSI A6+ engineered yarn gloves from mid-tier A3-A5 synthetics and baseline A1-A2 cotton blends. Price differentiation centers on gram-weight blade resistance ratings and fiber technology sophistication, with UHMWPE constructions sustaining 25-40% premiums over steel fiber equivalents. Cost compression in economy tiers is intensifying because Vietnamese and Bangladeshi manufacturers are scaling knit capacity for undifferentiated warehouse handling applications. Construction contractors purchasing through retail cooperatives exhibit highest price sensitivity, while German automotive OEMs demonstrate lowest sensitivity due to downtime cost calculus.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo and Los Angeles-Long Beach corridors intermittently extends inbound fiber delivery timelines for glove fabricators dependent on Asian chemical manufacturers. Ultra-high molecular weight polyethylene fiber production concentrates in the United States, Japan, and the Netherlands, while para-aramid supply anchors in the United States and Germany. Stainless steel wire for knit reinforcement draws from Chinese and Indian metallurgical processors. Single-source vulnerability in specialized high-tenacity fiber qualification creates bottleneck risk when notified body testing queues extend. Distribution runs through industrial safety distributors like Grainger and Würth, with direct manufacturer relationships capturing specification authority at Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cut resistant gloves market sits in early-cycle expansion as battery electric vehicle manufacturing commissioning accelerates ANSI A6+ specification upgrades across greenfield automotive assembly corridors.
For Market Incumbents: Compound certification authority through backward integration into UHMWPE fiber production or captive yarn engineering partnerships, eliminating qualification bottlenecks that delay product launches. Add high-cut-level knit capacity in South Carolina or Bavaria to anchor automotive OEM direct specification relationships before competitors secure platform-standard positions. Defend against emerging polymer substitution threats by locking multi-year fiber offtake agreements with DSM or Honeywell Specialty Chemicals. For New Entrants and Emerging Players: EN 388:2016+A1:2018 fast-track certification through notified body pre-submission consultations opens procurement access to EU manufacturing clusters faster than incumbents can extend geographic coverage. Target Vietnamese precision assembly zones where foreign direct investment flows exceed certified glove supply, particularly in electronics contract manufacturing serving Apple and Samsung supply chains. Pursue digital direct-to-industrial procurement platforms with subscription-based replacement programs that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across seamless automated knitting equipment as precision glove production demands seven-figure machinery investments that mid-scale entrants cannot replicate. Long-term viability favors integrated fiber-to-glove manufacturers with captive UHMWPE or para-aramid supply and established automotive account teams. Watch for inflection when Chinese photovoltaic manufacturers begin mandating sub-1mm thickness specifications for solar wafer handling, signaling specification escalation beyond current capacity configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Yarn Production | Captive UHMWPE fiber supply eliminates qualification bottlenecks and secures margin control against chemical manufacturer pricing power. |
| Automotive OEM Direct Specification Partnership | Platform-standard positioning at Volkswagen or BMW locks multi-year volume commitments and blocks competitor access. |
| EN 388 Notified Body Fast-Track Certification | Accelerated CE marking timelines compress market entry duration for new product variants in EU manufacturing corridors. |
| Digital Direct-to-Industrial Procurement Platform | Subscription-based replacement programs disintermediate traditional safety distributors and capture recurring revenue streams. |
| Glass Handling Precision Product Line Expansion | Ultra-thin ANSI A4-A6 gloves for solar panel manufacturing address fastest-specification-escalation application segment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with safety procurement directors at German automotive OEMs, plant managers at Vietnamese electronics contract manufacturers, technical sales leads at industrial distributors, and fiber engineering specialists at chemical manufacturers. Secondary validation incorporated customs trade data for UHMWPE and para-aramid fiber shipments, OSHA enforcement action databases, EN 388 notified body certification registries, and SEC filings from publicly traded PPE conglomerates. Bottom-up segment sizing triangulated against top-down industry association estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by material technology, application hazard intensity, end-user procurement centralization, and distribution channel structure. CAGRs were derived from regression analysis of historical procurement patterns against automotive production forecasts and regulatory enforcement intensity indices. Industry-specific inputs included battery electric vehicle manufacturing capacity pipelines, solar panel installation projections, and notified body testing queue duration trends.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement intensity and continued automotive electrification capital expenditure; material deviation would warrant model refresh. Specific risks include UHMWPE fiber supply disruption, CE marking regulatory revision, or automotive production slowdown. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market