
 Child-Resistant Containers Market | 2026-2036
Child-Resistant Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Child-Resistant Containers Market Analysis
Post-consumer recycled polyethylene terephthalate is recalibrating cost structures across rigid packaging. Berry Global Inc. leverages captive resin sourcing to stabilize input costs. Silgan Holdings Inc. dominates metal closure production for pharmaceutical applications. AptarGroup, Inc. specializes in push-and-twist dispensing systems with integrated child-resistance.
Child-resistant containers are engineered packaging systems incorporating mechanical barriers—torque requirements, dual-action release forces, or deformation thresholds—that prevent access by children under five years while permitting adult operation. Polypropylene and high-density polyethylene dominate injection-molded bodies due to chemical inertness and impact resistance. Closure mechanisms segment by technical complexity: push-and-twist systems anchor pharmaceutical volumes where USP 671 compliance is mandatory, while squeeze-and-turn formats occupy household chemical applications with lower certification burdens. Plastic material type sustains the largest share by unit volume, though glass gains traction in nutritional supplements where oxygen barrier demands exceed polymer capabilities.
FDA 21 CFR 1700 poison prevention packaging standards and EMA child-resistant packaging guidelines shape product development roadmaps for export-oriented manufacturers. The EU Green Deal and emerging US state cannabis regulations are expanding the addressable container population beyond traditional pharmaceuticals. Stakeholders must monitor evolving dual-certification requirements spanning child-resistance and senior-friendly accessibility as demographic aging intersects with stricter safety mandates.
Market Dynamics
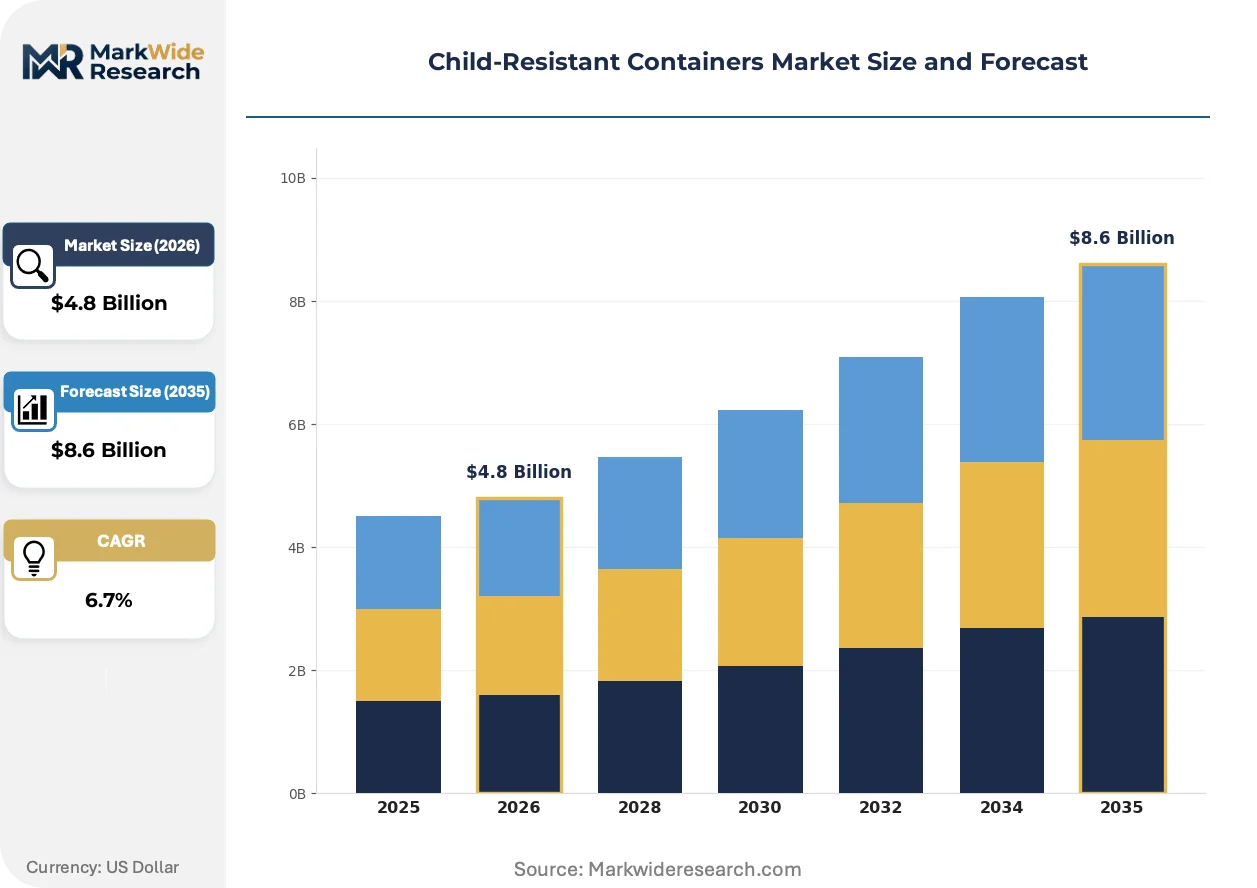
Post-consumer recycled resin mandates and dual-certification requirements for senior-friendly accessibility are compressing supplier margins while forcing closure mechanism redesigns across pharmaceutical and cannabis packaging lines.
Growth Catalysts
- FDA 21 CFR 1700 expansion:Poison prevention packaging standards now cover broader prescription drug categories, compelling container replacement cycles across retail pharmacy networks.
- State-level cannabis legalization:California, Colorado, and Illinois mandate child-resistant packaging for recreational and medical cannabis products, creating specialized procurement demand.
- Injection molding automation:Robotic cavity monitoring and predictive maintenance systems are cutting defect rates in high-torque closure production.
Market Restraints
- Post-consumer rPET supply volatility:Berry Global's captive resin sourcing remains an exception; most converters face input cost swings from recycling infrastructure gaps.
- Dual-action mechanism complexity:Push-and-twist systems require tighter tolerances than squeeze-and-turn formats, elevating tooling amortization per SKU.
- Glass substitution in oxygen-sensitive segments:Nutritional supplement brands are bypassing polymer containers where barrier performance falls short.
Strategic Opportunities
- EU Green Deal packaging mandates:Recycled content thresholds for pharmaceutical containers will favor early movers with validated rPET supply chains.
- Smart closure integration:NFC-enabled child-resistant caps combining tamper evidence with dosing reminders are opening connected packaging revenue streams.
- Direct-to-patient pharmacy channels:Mail-order dispensaries require specialized shipping-tested containers, bypassing traditional retail distribution.
Industry Challenges
- USP 671 certification timelines:Moisture vapor transmission rate testing for pharmaceutical closures extends product development cycles by 8-14 months.
- Senior-friendly accessibility engineering:Arthritis-compliant torque limits often conflict with child-resistance force thresholds, requiring iterative human-factors validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child-Resistant Containers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Paper Closure Mechanism: Push-and-Twist, Squeeze, Pull-Down, Locking End User: Pharmaceuticals, Household Products, Chemicals, Cosmetics Application: Child Safety, Prescription Medications, Cleaning Agents, Nutritional Supplements |
| Companies Covered | Amcor plc, Berry Global Inc., AptarGroup, Inc., Gerresheimer AG, WestRock Company, Smurfit WestRock plc, Silgan Holdings Inc., Comar LLC, Bericap Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child-Resistant Containers Market Emerging Trajectories
Mechanical closure systems are converging with digital traceability and sustainable materials, reshaping how manufacturers balance safety certification with circular economy compliance.
Biobased polypropylene derived from renewable feedstocks is consolidating material strategies for brands targeting carbon-neutral packaging claims. Nutritional supplement manufacturers in Germany and Switzerland are piloting these resins for oxygen-barrier containers. The shift is consolidating supplier relationships around polymer producers with certified mass-balance allocation systems.
EMA child-resistant packaging guidelines are tightening documentation requirements for exported pharmaceutical containers. European manufacturers must now submit third-party test reports for every closure-body combination. Small-batch generic drug producers in Southern Europe are consolidating SKUs to amortize compliance costs across higher volumes.
Hospital and long-term care facilities are consolidating procurement through group purchasing organizations, compressing vendor counts and demanding dual-certification stock. This concentration is displacing smaller regional molders lacking senior-friendly accessibility testing capabilities. The pattern is most visible in United States acute-care networks negotiating three-year container supply agreements.
Child-Resistant Containers Market Segmentation
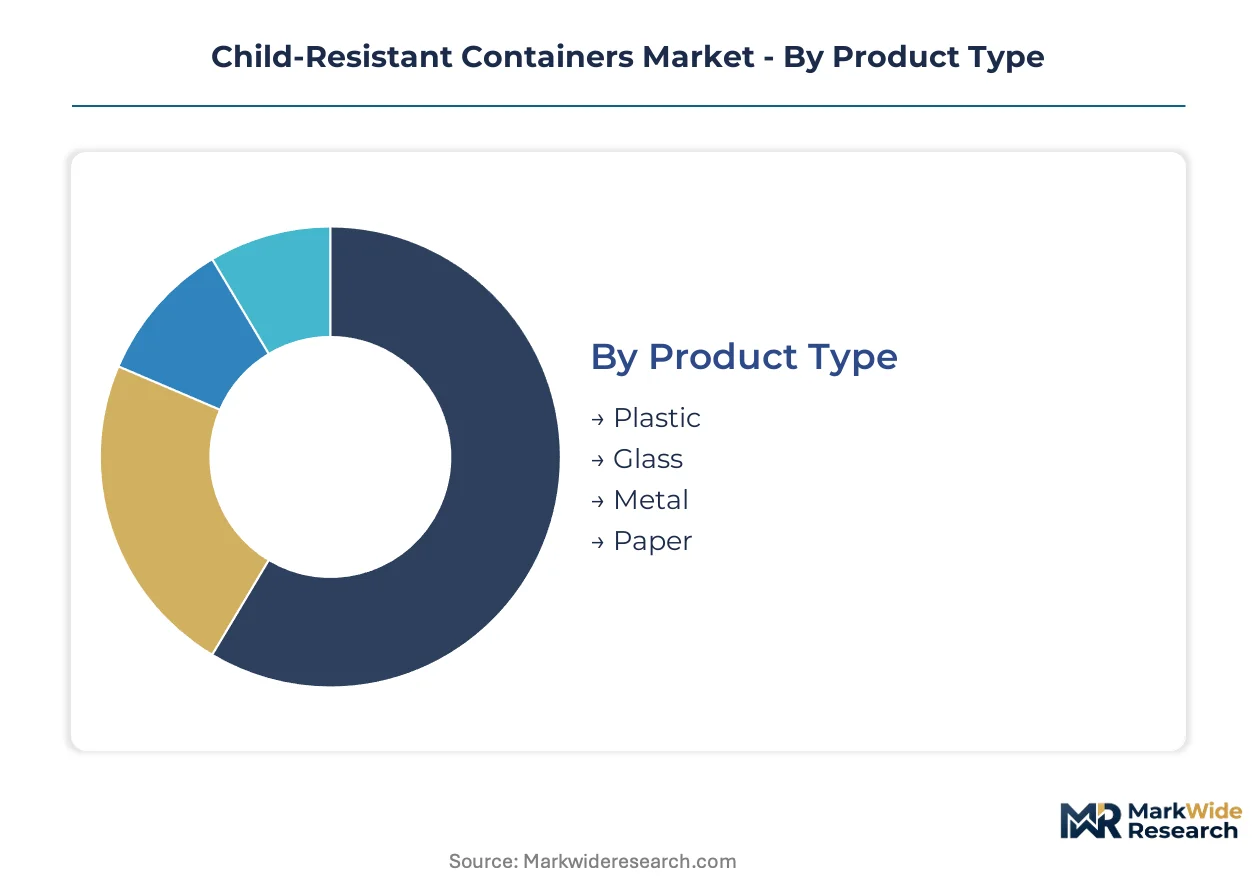
Child-resistant container buyers prioritize distinct performance attributes across pharmaceutical, cannabis, and household chemical channels. Segmentation reveals how material selection, closure complexity, and certification requirements stratify procurement decisions and supplier relationships.
Product Type:
Cost tier separates commodity converters from specialty resin compounders serving FDA-regulated applications.
- Plastic:Polypropylene and high-density polyethylene dominate injection-molded bodies through chemical inertness and impact resistance. Pharmaceutical volumes in the United States concentrate here as USP 671 compliance mandates drive polypropylene adoption for prescription medication bottles.
- Glass:Borosilicate and amber glass variants command premium positioning where oxygen barrier performance exceeds polymer capabilities. Nutritional supplement brands in Switzerland and Germany are expanding glass procurement for oxidation-sensitive formulations.
- Metal:Tinplate and aluminum containers serve industrial chemical segments requiring corrosion resistance beyond plastic capabilities.
- Paper:Fiber-based child-resistant cartons occupy niche pharmaceutical compliance packaging with limited moisture exposure tolerance.
Volume sits with Plastic; growth tilts toward Glass.
Closure Mechanism:
Application severity dictates torque tolerance specifications and human-factors validation investment.
- Push-and-Twist:Dual-action release systems require simultaneous downward pressure and rotational force exceeding child capability. Pharmaceutical applications in the United States mandate this format under FDA 21 CFR 1700, with USP 671 moisture vapor transmission testing extending development cycles.
- Squeeze:Compression-activated openings occupy household chemical segments with lower certification burdens and faster tooling amortization.
- Pull-Down:Vertical displacement mechanisms serve cannabis packaging in California and Colorado state-regulated markets.
- Locking:Key-activated or combination systems protect high-toxicity agricultural chemicals with theft-deterrence requirements.
Revenue concentrates in Push-and-Twist; Squeeze mechanisms are climbing the fastest as private-label household brands expand SKUs.
End User:
Customer type determines certification stringency and procurement consolidation patterns.
- Pharmaceuticals:Brand and generic drug manufacturers face EMA documentation requirements for every closure-body combination exported to Europe. Small-batch producers in Southern Europe are consolidating SKUs to amortize compliance costs.
- Household Products:Bleach and detergent brands leverage squeeze-and-turn formats with reduced torque tolerance testing versus pharmaceutical standards.
- Chemicals:Industrial solvent and pesticide containers require locking mechanisms with theft-deterrence features beyond child-resistance alone.
- Cosmetics:Premium skincare brands are piloting child-resistant dispensing for high-concentration retinol and acid formulations.
Procurement scale favors Pharmaceuticals; Cosmetics represents the fastest-growing trajectory as regulatory attention expands beyond traditional poison categories.
Application:
Geography within the title scope determines which regulatory framework governs container validation.
- Child Safety:General-purpose compliance packaging spans over-the-counter medications and household chemicals under CPSC guidelines in the United States.
- Prescription Medications:FDA 21 CFR 1700 mandates drive specialized procurement through retail pharmacy networks and direct-to-patient mail-order dispensaries.
- Cleaning Agents:State-level poison-prevention laws in Illinois and New York shape container specifications for concentrated laundry pod and drain cleaner packaging.
- Nutritional Supplements:Oxygen barrier demands are displacing polymer containers with glass alternatives in German and Swiss manufacturing clusters.
Unit volume centers on Child Safety; Nutritional Supplements are gaining share fastest as supplement regulation tightens across European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized industrial zones in New Jersey and North Carolina concentrate pharmaceutical packaging capacity through tax-advantaged manufacturing incentives. FDA 21 CFR 1700 compliance mandates drive container procurement across retail pharmacy networks.
United States
State-level cannabis legalization in California, Colorado, and Illinois creates specialized procurement demand for dual-certified containers. FDA poison prevention standards now cover broader prescription drug categories. Injection molding clusters in New Jersey supply high-torque closures to retail pharmacy chains.
Germany
Nutritional supplement manufacturers in Bavaria and Baden-Württemberg pilot biobased polypropylene for oxygen-barrier applications. EMA child-resistant packaging guidelines tighten documentation requirements for exported containers. Stuttgart-area compounders consolidate supplier relationships around mass-balance certified resin systems.
Switzerland
Swissmedic regulations drive premium glass container adoption for oxidation-sensitive formulations. Basel pharmaceutical clusters demand validated moisture vapor transmission performance. Zurich-area packaging converters specialize in amber borosilicate alternatives to polymer systems.
China
NMPA alignment with international child-resistance standards accelerates closure mechanism upgrades for export-oriented manufacturers. Yangtze River Delta injection molders automate cavity monitoring for high-torque production. Shanghai contract manufacturers serve multinational pharmaceutical brands with USP 671-compliant containers.
India
CDSCO tightening of prescription drug packaging rules expands addressable container populations for domestic manufacturers. Maharashtra pharmaceutical zones near Mumbai consolidate procurement through group purchasing organizations. Pune-area molders invest in push-and-twist tooling for generic drug export markets.
Child-Resistant Containers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered supplier access. Consolidation concentrates among resin compounders with captive recycling infrastructure and closure specialists with validated torque-testing protocols. Three archetypes dominate: vertically integrated polymer producers, precision closure engineers, and regional contract molders serving state-regulated cannabis markets. Capacity expansion and strategic partnerships represent the primary competitive vectors as dual-certification requirements compress margins.
Among North American packaging conglomerates, Berry Global Inc., AptarGroup, Inc., and Silgan Holdings Inc. occupy positions across the material-to-closure value chain. Berry Global exemplifies resin-integrated supply stability through captive post-consumer rPET sourcing. AptarGroup represents the precision-engineering archetype for push-and-twist dispensing systems. Silgan Holdings anchors metal closure production for pharmaceutical applications requiring corrosion resistance beyond polymer capabilities.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| AptarGroup, Inc. |
| Gerresheimer AG |
| WestRock Company |
| Smurfit WestRock plc |
| Silgan Holdings Inc. |
| Comar LLC |
| Bericap Holding GmbH |
| Others |
Supply Flow & Price Mechanics
Post-consumer recycled PET bale pricing cascades through converter cost structures into three distinct procurement tiers: pharmaceutical-grade certified containers, dual-certified cannabis packaging, and commodity household chemical formats.
Pricing Analysis
Lead-time-driven pricing separates urgent pharmaceutical procurement from scheduled contract volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by USP 671 certification status and dual-certification for senior-friendly accessibility. Cost compression in standard-tier squeeze-and-turn formats is intensifying because private-label household brands are consolidating SKU volumes. Generic drug manufacturers exhibit highest price sensitivity; Swiss nutritional supplement brands purchasing amber glass show lowest sensitivity due to oxygen-barrier performance premiums.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta injection molders serving multinational pharmaceutical brands. Resin compounding concentrates in the United States, Germany, and China. Closure mechanism production draws from polypropylene pellet feedstocks, high-density polyethylene resin, and post-consumer rPET flake supplies. Tariff exposure on Chinese-manufactured tooling elevates capital expenditure risk for European converters. Distribution runs through group purchasing organizations consolidating hospital and long-term care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The child-resistant containers market is transitioning from mechanical-only closures to smart-enabled dispensing systems integrating NFC tamper evidence and dosing reminders.
For Market Incumbents: Anticipate margin compression from biobased polypropylene pilots in German nutritional supplement manufacturing by securing mass-balance certified resin supply agreements. Invest in dual-certification testing capabilities before hospital GPO consolidation eliminates regional molders lacking senior-friendly accessibility validation. Prioritize push-and-twist mechanism R&D to maintain pharmaceutical volume share against squeeze-format encroachment.
For New Entrants and Emerging Players: Direct-to-patient pharmacy channels offer the most penetrable route, as mail-order dispensaries require shipping-tested containers bypassing traditional retail distribution. Target state-regulated cannabis markets in Illinois and Colorado where dual-certified demand outstrips validated supplier capacity. Pursue white-label manufacturing partnerships with established resin compounders to amortize USP 671 certification costs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier molders in Maharashtra pharmaceutical zones near Mumbai, where CDSCO packaging rule tightening is displacing uncertified competitors. Long-term viability hinges on captive rPET infrastructure and validated torque-testing protocols. Watch NMPA alignment with international child-resistance standards as the inflection signal for Chinese export-oriented manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Closure Integration | NFC-enabled caps combining tamper evidence with dosing reminders open connected packaging revenue streams for pharmaceutical brands. |
| Dual-Certification Investment | USP 671 and senior-friendly accessibility validation secures hospital GPO contracts displacing regional competitors. |
| Captive rPET Sourcing | Post-consumer recycled resin infrastructure insulates margin pressure from recycling infrastructure gaps affecting competitors. |
| Direct-to-Patient Channel Development | Mail-order dispensary partnerships bypass retail pharmacy network concentration and command shipping-tested container premiums. |
| Biobased Polypropylene Partnerships | Mass-balance certified renewable feedstock agreements position brands for EU Green Deal pharmaceutical packaging mandates. |
Methodological Framework
Document review covered FDA 21 CFR 1700 regulatory filings, EMA child-resistant packaging guideline updates, and USP 671 certification databases, complemented by interviews with pharmaceutical packaging procurement directors, injection molding plant managers, resin compounder technical leads, and hospital GPO contracts managers. Secondary validation drew from customs trade data, SEC 10-K packaging segment disclosures, and state-level cannabis regulatory filings. Bottom-up container volume estimates and top-down pharmaceutical packaging spend analysis were triangulated against trade association statistics.
Unit and value projections across the analysis window were generated through segmented modeling by material type, closure mechanism complexity, end-use certification tier, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical pharmaceutical container procurement cycles and forward-projected regulatory expansion timelines. Key inputs included FDA prescription drug category coverage expansion schedules and EU Green Deal recycled content threshold implementation phases.
The model holds under stable resin pricing and regulatory implementation timelines; deviation in post-consumer rPET supply availability or accelerated senior-friendly accessibility mandates would shift volume trajectories. Forecasts reflect documented assumptions regarding certification timeline standardization and automation adoption rates in high-torque closure production. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Takeout Containers Market
Containers
Trays Market
Containers
Thin Wall Containers Market
Containers
Canning Jars Market
Containers
Stock Clamshell Packaging Market
Containers
Food Grade Stainless Steel Container Market
Containers
Canisters Market
Containers
Intermediate Bulk Container Liner Market
Containers
Foldable Large Containers Market
Containers
EPS Container Market
Containers
Aluminum Foil Containers Market
Containers
Feeder Containers Market
Containers
Bulk Containers Market
Containers
Global Container Monitoring Market
Containers
EPS Shippers Market
Containers
Laminated Bulk Bins Market