

EPS Container Market Size, Share, and Industry Trends Forecast 2026-2036
EPS Container Market Insights
China is rewriting capacity dynamics in molded foam packaging as domestic resin integration lowers feedstock costs for regional producers. Dart Container leverages captive polystyrene bead supply to sustain margin stability across North American foodservice accounts. BEWI anchors European insulated logistics through controlled-cell-density manufacturing that meets pharmaceutical cold-chain protocols. Synthos specializes in flame-retardant expandable resin grades that differentiate its container offerings for electronics protection.
EPS containers are rigid cellular structures manufactured from expanded polystyrene beads fused under steam pressure, typically achieving densities of 15–30 kg/m³ with thermal conductivity near 0.035 W/m·K, engineered primarily for temperature-sensitive product protection and shock-absorbent distribution. Foam boxes dominate pharmaceutical and fresh-food cold chains where thermal performance thresholds determine logistics compliance. Foam trays occupy mature supermarket meat and produce display segments with thin-margin, high-volume economics. Medical transport applications are expanding fastest as biologics manufacturers require validated packaging that maintains 2–8°C stability across extended transit durations.
The EPA regulates foam manufacturing emissions under Clean Air Act Title V permitting, while FDA food-contact substance notifications govern resin purity for direct food applications. REACH restrictions on styrene monomer residuals shape import compliance for European-bound container shipments. California's SB 54 extended producer responsibility framework is forcing domestic reformulation timelines. Stakeholders must monitor how fragmented state-level packaging bans interact with federal preemption debates to determine capital allocation between virgin resin lines and recycled-content capacity.
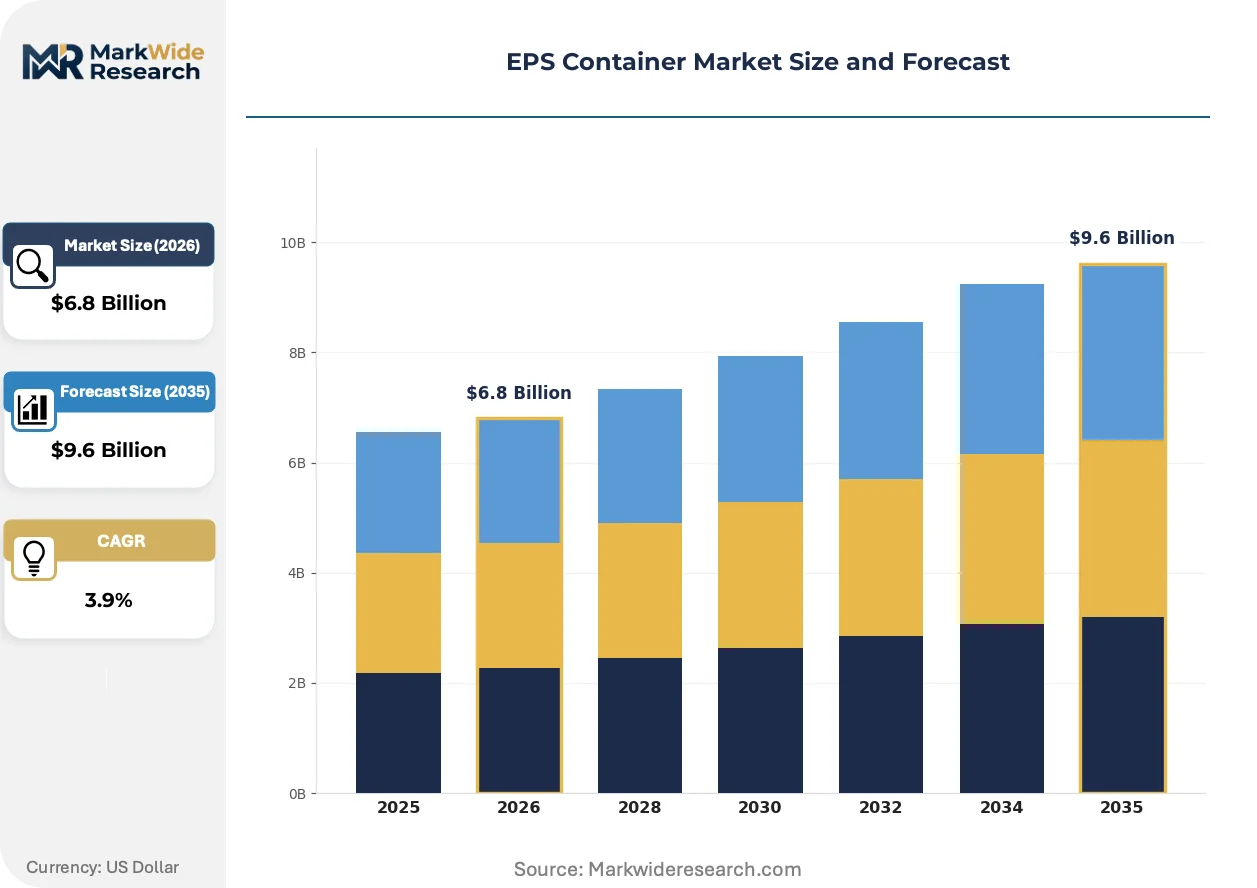
Market Dynamics
Pharmaceutical cold-chain validation requirements are compressing container procurement cycles as biologics manufacturers demand certified thermal performance documentation before vendor qualification. This pressure is forcing foam converters to invest in controlled-atmosphere testing infrastructure and traceability systems that document temperature integrity across extended transit corridors.
Growth Catalysts
- EU Single-Use Plastics Directive:Packaging waste regulations in Germany and France are redirecting R&D investment toward recyclable foam formulations that maintain thermal conductivity near 0.035 W/m·K.
- Biologics cold-chain expansion:Temperature-sensitive pharmaceutical distribution is multiplying demand for validated 2–8°C stability containers across North American and European logistics networks.
- Styrene resin integration:Domestic bead production in China is lowering feedstock costs for regional molded foam manufacturers serving fresh-food export corridors.
Market Restraints
- Feedstock volatility:Benzene and ethylene price swings compress margins for expandable polystyrene bead converters lacking long-term supply contracts.
- Substitution threat:Insulated corrugated alternatives with aerogel liners are capturing premium pharmaceutical accounts requiring collapsible return logistics.
- REACH compliance friction:Styrene monomer residual limits create import barriers for non-European container shipments bound for German distribution centers.
Strategic Opportunities
- Indian pharmaceutical logistics:CDSCO cold-chain mandates for vaccine distribution are opening demand for validated EPS containers in a market with limited domestic insulated packaging capacity.
- Bio-based foam convergence:Integration of PLA-blend beads with conventional EPS is creating compostable thermal packaging for European organic food retail channels.
- Direct-to-patient pharmacy:Specialty drug home delivery networks require small-format insulated containers that bypass traditional wholesale distribution infrastructure.
Industry Challenges
- Controlled-cell-density engineering talent:Pharmaceutical cold-chain protocols require specialized process engineers capable of calibrating bead fusion parameters to achieve uniform thermal resistance.
- Multi-jurisdiction certification timelines:FDA food-contact notifications, EPA Title V permits, and REACH substance registrations must align for container suppliers serving transatlantic accounts.
- Legacy equipment retrofit costs:Steam-pressure molding lines require capital-intensive modifications to process recycled-content bead formulations without density degradation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPS Container Market Trends and Innovations
Material science advances and regulatory compliance automation are compressing product development cycles while expanding the addressable market for temperature-sensitive logistics. These forces are reshaping how foam converters compete on certification depth rather than unit cost alone.
Hybrid bio-foam technology is hybridizing conventional polystyrene matrices with agricultural waste fillers to reduce petrochemical content while preserving thermal conductivity performance. European insulated logistics providers are piloting these formulations for pharmaceutical accounts facing Scope 3 emissions disclosure requirements under CSRD. The structural consequence is a bifurcation between premium certified bio-foam containers and commodity virgin-resin products serving cost-sensitive fresh-food channels.
California's SB 54 extended producer responsibility framework is mandating post-consumer recycled content thresholds that reshape resin sourcing strategies for West Coast foodservice distribution. Container manufacturers must now document mass-balance chain of custody from flake collection through re-pelletization to maintain market access. Fresh-produce export packers in the Central Valley are accelerating supplier audits to verify compliance before the 2030 phased mandates take full effect.
Biologics manufacturers are consolidating vendor panels around packaging partners offering integrated temperature monitoring and IoT-enabled track-and-trace documentation. This procurement compression is displacing standalone foam converters lacking digital logistics partnerships or in-house validation laboratory capabilities. The shift is most visible in German and Swiss pharmaceutical clusters where centralized distribution networks prioritize single-source accountability for cold-chain integrity failures.
EPS Container Market Segmentation
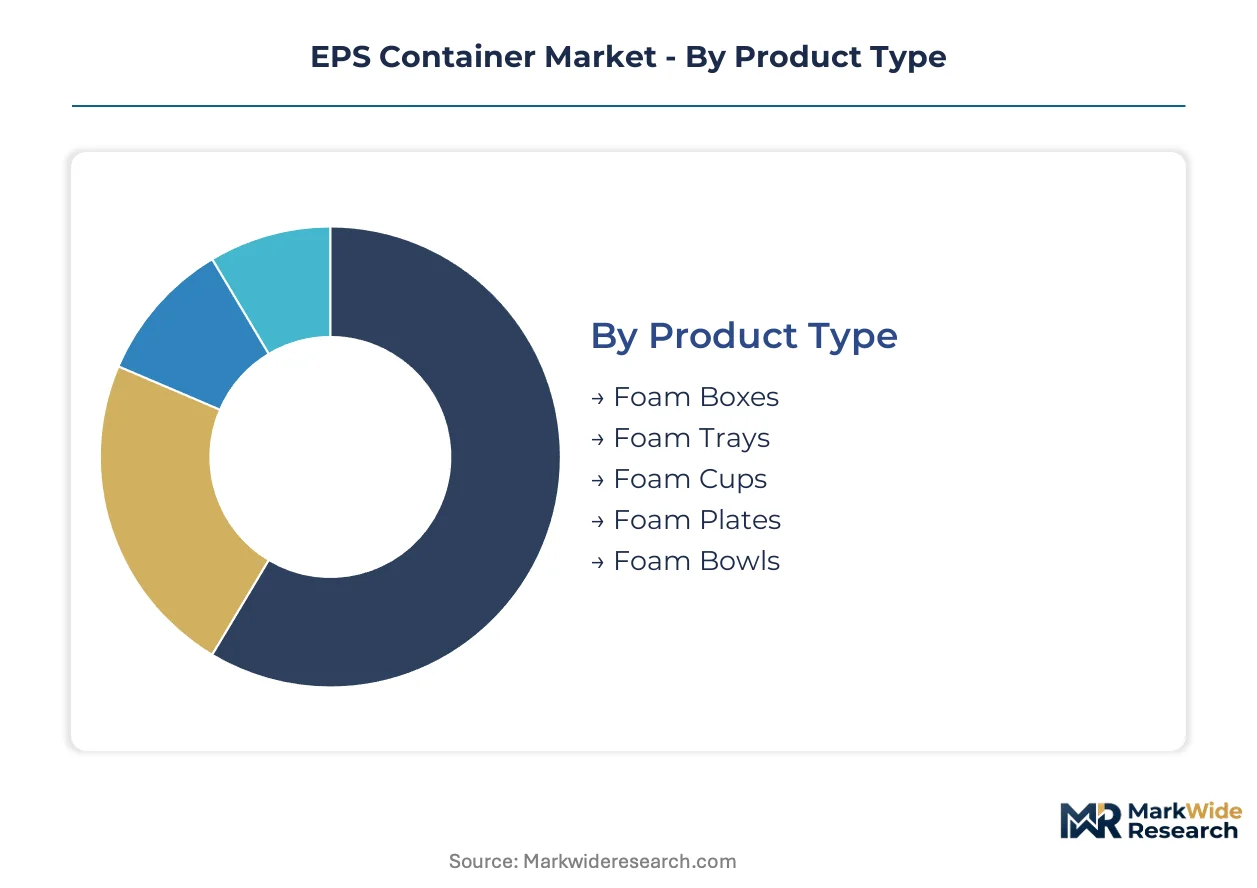
EPS container segmentation reveals divergent margin structures across product geometries and regulatory exposure profiles. Pharmaceutical cold-chain applications command premium pricing tied to validation documentation, while foodservice disposables compete on resin conversion efficiency and logistics density.
Product Type:
After-sales-service intensity varies dramatically across product geometries, with pharmaceutical-grade foam boxes requiring thermal validation support versus commodity foam plates sold through distributor self-service.
- Foam Boxes:Rigid cellular structures engineered for 2–8°C thermal stability across extended transit corridors, typically achieving densities of 15–30 kg/m³. Demand concentrates in German pharmaceutical distribution networks where centralized cold-chain hubs require certified performance documentation for biologics transport.
- Foam Trays:Thin-walled cellular platforms designed for supermarket meat and produce display applications with high-volume, thin-margin economics. German and French retail consolidation is compressing supplier margins while mandating recyclable-content thresholds under EU Single-Use Plastics Directive timelines.
- Foam Cups:Cylindrical bead-fusion vessels serving hot and cold beverage foodservice channels with standardized rim diameters for lid interoperability.
- Foam Plates:Flat cellular substrates for disposable foodservice applications where California SB 54 recycled-content mandates are accelerating reformulation investments.
- Foam Bowls:Deep-drawn cellular containers for prepared food delivery, encountering substitution pressure from fiber-based alternatives in European organic retail channels.
By volume, Foam Trays leads. By growth pace, Foam Boxes is ahead.
Application:
Cost tier stratification separates validated pharmaceutical applications from commodity food packaging, with certification depth determining supplier qualification barriers.
- Food Packaging:Temperature maintenance for fresh-produce export corridors and prepared meal distribution, where Chinese domestic resin integration is lowering regional feedstock costs for molded foam converters.
- Medical Transport:Validated cold-chain containers maintaining 2–8°C stability for biologics and vaccine distribution, requiring controlled-cell-density manufacturing and traceability documentation. CDSCO mandates in India are opening demand in a market with limited domestic insulated packaging capacity.
- Electronics Packaging:Shock-absorbent cellular structures protecting sensitive components during distribution, with flame-retardant resin grades differentiating offerings for high-value device protection.
- Industrial Insulation:Large-format cellular blocks for temperature-sensitive material storage and process equipment protection.
- Consumer Goods Protection:Custom-molded cellular inserts for fragile product distribution through e-commerce channels.
Food Packaging dominates volume throughput. Medical Transport is expanding most quickly as biologics multiply.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding integrated validation services versus foodservice providers purchasing through distributor catalogs.
- Foodservice Providers:High-volume disposable container purchasers operating on contract pricing tied to resin index movements and logistics consolidation.
- Pharmaceutical Companies:Biologics manufacturers requiring vendor consolidation around partners offering temperature monitoring integration and IoT-enabled track-and-trace documentation, particularly visible in German and Swiss pharmaceutical clusters.
- Electronics Manufacturers:Precision packaging purchasers specifying flame-retardant and anti-static cellular formulations for component protection.
- Logistics Companies:Third-party cold-chain operators selecting containers based on thermal performance certification and reverse logistics compatibility.
- Packaging Suppliers:Converter and distributor intermediaries serving fragmented end-user bases with inventory-managed programs.
Foodservice Providers move the highest unit volumes. Pharmaceutical Companies are driving the steepest expansion trajectory through vendor panel consolidation.
Distribution Channel:
Supply concentration patterns favor direct relationships for pharmaceutical accounts while commodity foodservice flows through layered distributor networks.
- Direct Sales:Account-managed relationships for pharmaceutical and large foodservice chains requiring thermal validation support and customized specification development.
- Distributors:Inventory-carrying intermediaries serving fragmented foodservice and consumer goods accounts with standardized product catalogs.
- Online Retailers:Digital channels capturing small-format insulated container demand from direct-to-patient pharmacy networks and specialty drug home delivery.
- Wholesalers:Volume aggregators for standardized foam trays and cups serving supermarket and institutional foodservice procurement.
- Exporters:Specialized channels managing REACH compliance documentation for European-bound container shipments from non-European manufacturing origins.
Distributors handle the greatest transaction volume. Direct Sales is gaining share fastest as pharmaceutical procurement compresses around single-source accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin integration advantages concentrate manufacturing capacity in China, while regulatory stringency in Germany and California redirects investment toward recyclable formulations. Pharmaceutical cold-chain mandates in India and extended producer responsibility frameworks in France are fragmenting regional competitive dynamics.
China
Domestic expandable polystyrene bead production lowers feedstock costs for regional molded foam converters serving fresh-food export corridors. The Ministry of Ecology and Environment enforces dual carbon goals that pressure coastal manufacturers toward cleaner steam-pressure molding processes. The Yangtze River Delta hosts dense clusters of packaging converters supplying pharmaceutical and agricultural cold-chain logistics.
Germany
Centralized pharmaceutical distribution networks demand validated 2–8°C thermal performance documentation from insulated container suppliers. REACH restrictions on styrene monomer residuals shape import compliance for European-bound shipments, favoring domestic converters. The Rhine-Main logistics corridor concentrates cold-chain validation laboratories and controlled-cell-density manufacturing expertise.
United States
Biologics manufacturers consolidate vendor panels around packaging partners offering integrated temperature monitoring and IoT-enabled track-and-trace documentation. California's SB 54 extended producer responsibility framework mandates post-consumer recycled content thresholds that reshape West Coast resin sourcing strategies. The Central Valley fresh-produce export sector accelerates supplier audits to verify compliance before 2030 phased mandates.
India
CDSCO cold-chain mandates for vaccine distribution open demand for validated EPS containers in a market with limited domestic insulated packaging capacity. The country's national pharmaceutical regulator enforces temperature integrity requirements that favor imported validation expertise. Mumbai and Hyderabad pharmaceutical clusters drive procurement of certified thermal packaging for biologics distribution.
France
EU Single-Use Plastics Directive timelines compress supplier margins while mandating recyclable-content thresholds for supermarket meat and produce display applications. ECHA substance registration requirements create compliance friction for non-European container shipments. The Paris Basin retail consolidation centers demand thin-margin, high-volume foam tray supply with documented circular economy credentials.
EPS Container Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on resin and bead supply. The vendor base organizes around three structural tiers: captive resin producers with backward integration into polystyrene bead manufacturing, independent foam converters serving fragmented foodservice accounts, and certified cold-chain specialists with validation laboratory infrastructure. Consolidation pressure concentrates among pharmaceutical-grade suppliers as biologics manufacturers reduce vendor panels. Capacity expansion and strategic partnerships dominate competitive moves, with converters partnering with digital logistics providers to embed temperature monitoring capabilities.
Within the captive resin tier, Dart Container exemplifies margin stability through in-house polystyrene bead supply across North American foodservice accounts. BEWI anchors European insulated logistics positioning through controlled-cell-density manufacturing capabilities. Synthos occupies a specialist position in flame-retardant expandable resin grades that differentiate offerings for electronics protection applications. These three entities represent distinct archetypes: backward-integrated volume producer, regional cold-chain validator, and material-grade specialist respectively.
| Leading Market Players |
|---|
| Genpak |
| Dart Container |
| Berry Global |
| Pactiv Evergreen |
| BEWI |
| Styropek |
| Insulfoam |
| Foamex |
| Synthos |
| Others |
Pricing and Supply Chain Analysis
China's captive polystyrene bead production anchors feedstock economics for regional converters, compressing margin pools for European and North American molders lacking equivalent resin integration. Pharmaceutical-grade cold-chain containers command sustained premiums where validation documentation creates procurement stickiness, while foodservice disposables compete on resin conversion efficiency alone.
Pricing Analysis
California's SB 54 extended producer responsibility framework dictates the pricing tier structure across West Coast distribution. Three-tier pricing structure across premium, standard, and economy levels separates certified pharmaceutical containers with IoT traceability from commodity foam boxes and thin-margin foodservice disposables. Pricing pressure stems from insulated corrugated alternatives capturing premium pharmaceutical accounts with collapsible return logistics. Foodservice providers exhibit highest price sensitivity, while biologics manufacturers prioritize certification depth over unit cost.
Supply Chain Analysis
Expandable polystyrene bead supply draws from concentrated production clusters in China, Germany, and the United States. Feedstock hinges on benzene and ethylene derivatives, steam-pressure molding equipment, and flame-retardant additive formulations. Single-source vulnerability runs through Chinese resin integration advantages that disadvantage non-integrated converters. Distribution runs through direct account management for pharmaceutical validation requirements and layered distributor networks for standardized foodservice products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-cell-density engineering talent scarcity defines competitive positioning, as pharmaceutical cold-chain protocols demand specialized process calibration capabilities that outstrip available technical labor pools. This capability gap separates validated container suppliers from commodity converters.
For Market Incumbents: Pre-empt substitution threats from aerogel-lined corrugated alternatives by embedding temperature monitoring partnerships with digital logistics providers. Deepen backward integration into recycled-content bead processing to meet California SB 54 mandates before 2030 compliance deadlines. Lock pharmaceutical accounts through integrated validation laboratory services that create switching costs.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical logistics where CDSCO cold-chain mandates outpace domestic insulated packaging capacity. Target direct-to-patient pharmacy distribution with small-format containers bypassing traditional wholesale infrastructure. Lead with IoT-enabled track-and-trace documentation as a differentiated procurement wedge against legacy foam converters.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European cold-chain specialists possessing validation infrastructure but limited geographic scale. Long-term viability favors converters with dual capability in virgin and recycled-content formulations across the analysis window. Monitor EU Single-Use Plastics Directive enforcement intensity as the inflection signal for recyclable foam adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Bead Supply | California SB 54 compliance secures West Coast market access against 2030 mandates. |
| Validation Laboratory Infrastructure Buildout | FDA food-contact notifications and REACH registrations align for transatlantic pharmaceutical accounts. |
| Digital Logistics Partnership Formation | IoT-enabled track-and-trace documentation meets German biologics manufacturer vendor consolidation requirements. |
| Controlled-Cell-Density Manufacturing Scale-Up | Pharmaceutical cold-chain protocols demand uniform thermal resistance calibration expertise. |
| Bio-Based Foam Formulation Development | PLA-blend bead integration addresses CSRD Scope 3 emissions disclosure requirements for European organic retail. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Plant managers at molded foam converters, procurement leads at pharmaceutical distribution networks, technical R&D directors at resin manufacturers, and channel partners in foodservice distribution provided operational perspective. Secondary sources included EPA Title V permitting records, ECHA REACH substance registrations, FDA food-contact substance notifications, and customs trade data for expandable polystyrene bead flows. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level estimates.
Forecast inputs considered product geometry, application regulatory exposure, end-user procurement sophistication, and regional resin integration advantages across the projection horizon. Pharmaceutical-grade foam boxes, commodity foodservice disposables, and emerging bio-based formulations were modeled separately with distinct margin assumptions. CAGRs were derived from segment-level growth drivers rather than aggregate extrapolation. Styrene monomer price volatility and EU Single-Use Plastics Directive implementation timelines shaped scenario boundaries.
Stress conditions across benzene-ethylene feedstock spreads, REACH compliance friction, and pharmaceutical vendor panel consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against ECHA substance registration databases and CDSCO cold-chain mandate enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.