
 Thermoformed Shallow Trays Market | 2026-2036
Thermoformed Shallow Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Shallow Trays Market Intelligence
A capital-intensity divergence between integrated resin producers and specialized thermoforming job shops is reorganizing competitive tiers in the tray sector. Pactiv Evergreen leverages captive resin sourcing and broad foodservice distribution to sustain margin stability across volatile polymer cycles. Sonoco Products Company anchors its position through fiber-based hybrid tray technologies that compete with conventional plastic formats. Amcor differentiates via global preform-to-tray conversion networks that control specification consistency for pharmaceutical and food clients.
Thermoformed shallow trays are thin-gauge plastic containers produced by heating a polymer sheet to its forming temperature, then vacuum- or pressure-forming it over a mold to create precise cavity dimensions typically ranging from 0.010 to 0.080 inches in wall thickness. These trays function primarily as protective, display-ready platforms for unitized products in automated filling and retail presentation environments. PET dominates material type selection due to its clarity, recyclability infrastructure, and compatibility with modified-atmosphere food packaging, while PLA represents the fastest-expanding structural category as brand owners pursue compostable credentials. Food packaging anchors application demand through protein, produce, and ready-meal segments where shelf visibility and barrier performance command premium positioning.
FDA food contact regulations and EPA recycled content mandates in the United States, alongside EU REACH chemical restrictions and F-Gas Regulation compliance requirements for barrier foam technologies, collectively elevate compliance costs while steering investment toward verified sustainable material streams. ISO 9001 and BRC packaging standards further condition market access for suppliers serving multinational food processors and pharmaceutical manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer traceability protocols to align capital allocation with emerging compliance thresholds.
Market Dynamics
Material substitution mandates under the EU Single-Use Plastics Directive are forcing tray manufacturers to requalify entire product lines for rPET and PLA substrates, compressing development cycles and elevating capital requirements for mold retooling.
Growth Catalysts
- EU Packaging Waste Regulation:Mandatory recycled content thresholds for food contact plastics are pulling rPET tray volumes upward as retailers pre-empt enforcement timelines.
- Ready-meal automation:Protein processors in Germany and France are standardizing tray formats to match high-speed filling equipment, locking in multi-year supply agreements.
- Modified-atmosphere barrier films:Oxygen-scavenging laminate integration with PET trays is extending fresh produce shelf life, opening premium positioning in retail produce departments.
Market Restraints
- rPET feedstock volatility:Collection infrastructure gaps in Southern Europe create price instability for food-grade recycled flake, squeezing converter margins.
- PLA thermal limitation:Polylactic acid's 55°C heat deflection temperature blocks hot-fill applications, restricting penetration into soup and sauce segments.
- German distributor concentration:Three retail buying cooperatives control 60% of standardized tray procurement, extracting annual price concessions through tender aggregation.
Strategic Opportunities
- Pharmaceutical serialization:EU Falsified Medicines Directive compliance is creating demand for tamper-evident shallow trays with integrated RFID pockets.
- Netherlands circular hubs:Rotterdam's chemical recycling cluster offers proximity to both rPET supply and North Sea export logistics for tray converters.
- Direct-to-retail digital portals:Specialized thermoformers are bypassing traditional packaging distributors by offering CAD-to-mold rapid prototyping services online.
Industry Challenges
- Multi-material separation:Barrier-coated PET trays require advanced near-infrared sorting infrastructure that remains underdeployed across European municipal recycling streams.
- BRC certification backlog:Third-party audit capacity constraints are delaying food safety approvals for new PLA tray lines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Shallow Trays Market |
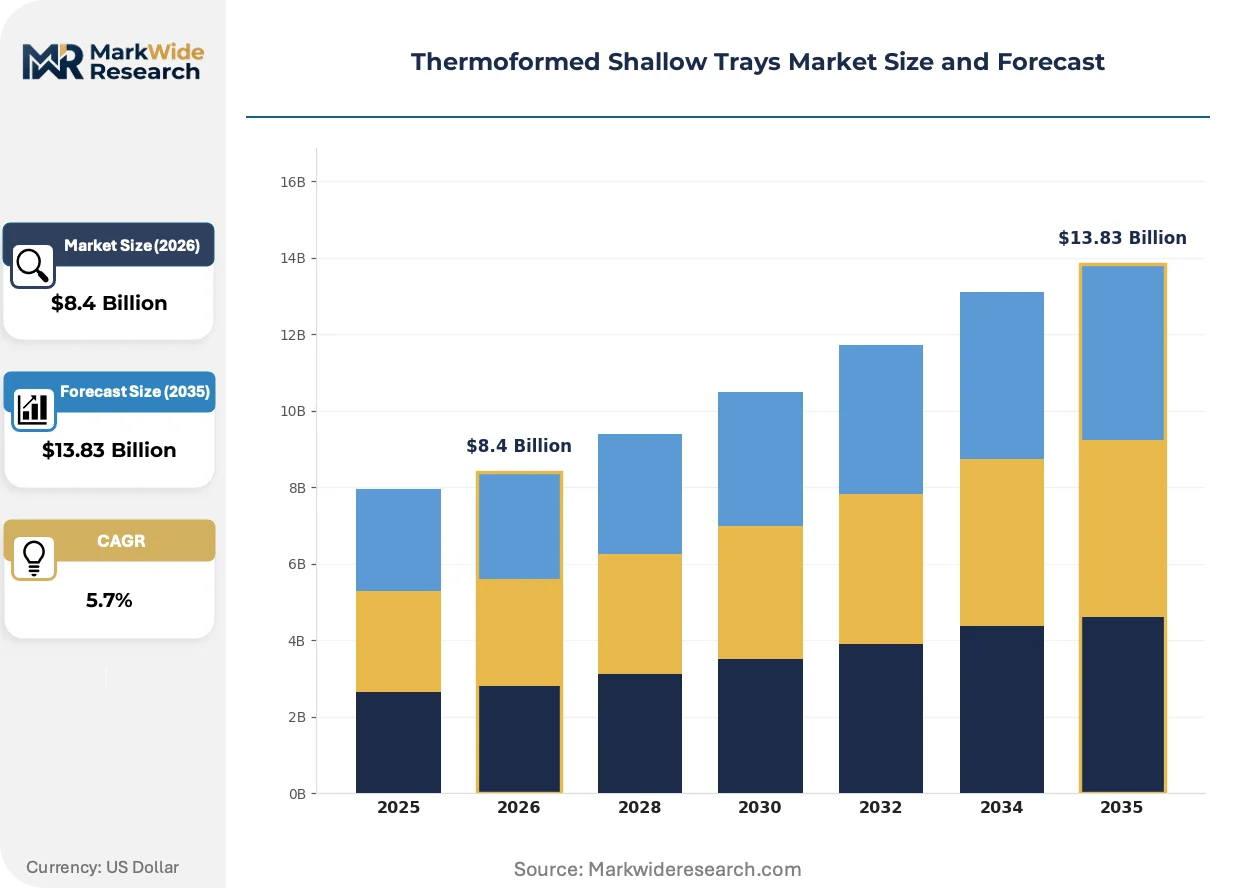
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PET, PVC, PP, PS, PLA, PETG Packaging Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Electronics Protection, Medical Devices, Stationery End User Industry: Food Processing Units, Pharmaceutical Manufacturers, Personal Care Brands, Electronics Assemblers, Healthcare Providers, Educational Institutions Product Design: Rectangular, Square, Circular, Custom Molded, Compartmentalized, Embossed |
| Companies Covered | Pactiv Evergreen, Sonoco Products Company, Amcor, Jamestown Plastics, Indepak, Berry Global, Faerch Group, Nefab, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Shallow Trays Market Strategic Shifts & Innovations
Active barrier technologies and digital printing integration are compressing product development timelines while enabling batch-level customization previously reserved for premium segments.
Mono-material PET structures with built-in oxygen scavengers are miniaturizing the functional role of external laminate films, allowing converters to eliminate secondary lamination steps. Ready-meal processors in Germany are qualifying these structures for twelve-month shelf-life targets. The technology is miniaturizing the barrier film supply chain by collapsing multi-layer specifications into single-substrate solutions.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings from food tray specifications. ECHA's 2023 proposal for universal PFAS bans is accelerating migration to silicone-based and bio-wax alternatives. Fresh bakery and fried protein segments face the steepest reformulation curves as existing tray inventories approach compliance deadlines.
Retail buying cooperatives are consolidating specification authority into centralized technical teams, displacing decentralized procurement by individual store formats. This concentration is compressing the number of approved tray suppliers per category from twelve to four in major German chains. The shift is most visible in produce and protein segments where shelf-ready packaging standardization delivers logistics savings.
Thermoformed Shallow Trays Market Segmentation
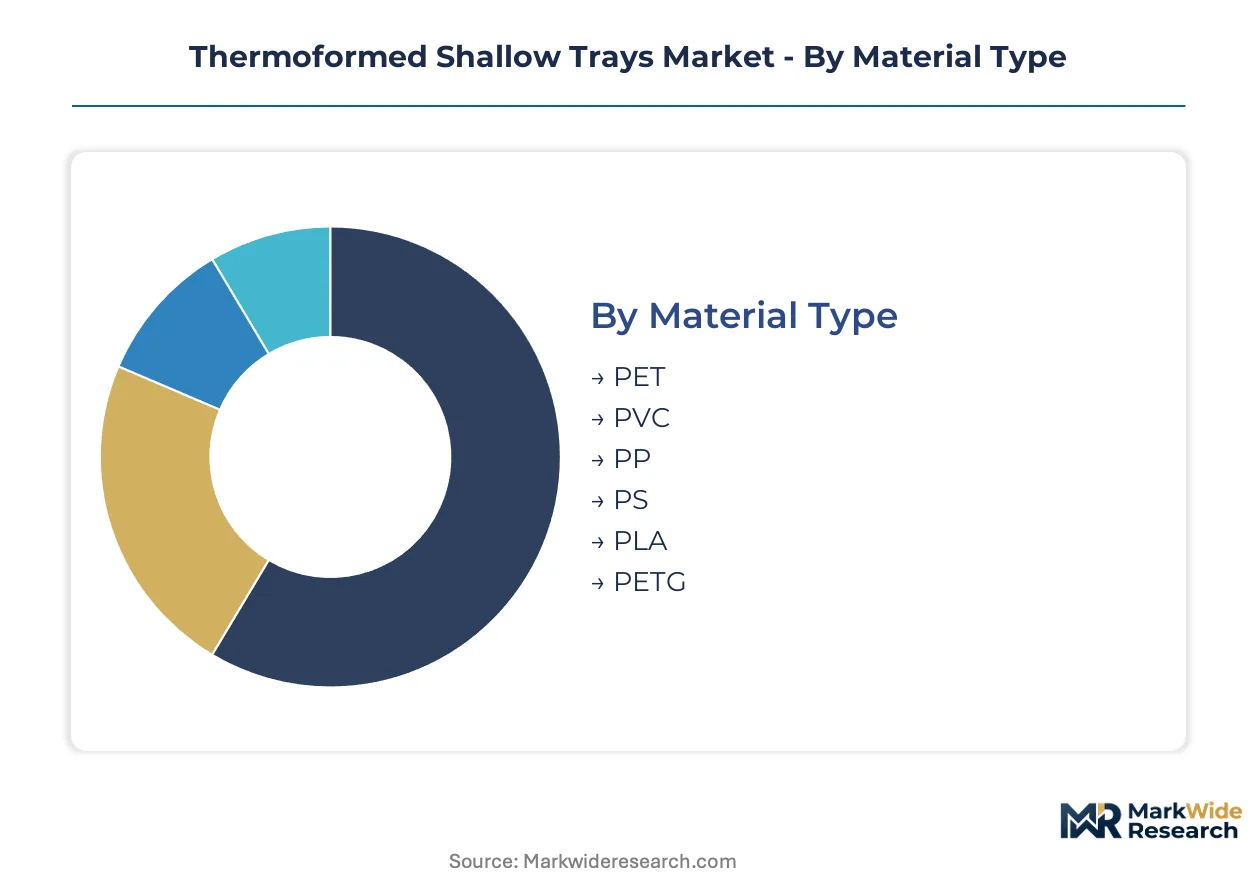
Segmentation in thermoformed shallow trays reveals how material chemistry, barrier specifications, and automation compatibility partition margin capture across converter tiers. Trays serving modified-atmosphere protein packaging command premium positioning through oxygen-scavenging substrate integration, while standardized produce formats compete on cycle time and mold efficiency.
Material Type:
PET and rPET variants concentrate the highest margin pools due to food-contact certification complexity and retailer sustainability mandates.
- PET:Virgin and recycled polyethylene terephthalate delivers optical clarity, mechanical rigidity, and established recycling infrastructure compatibility. German retailers are locking in multi-year rPET tray contracts ahead of EU Packaging Waste Regulation enforcement, squeezing converter capacity for food-grade flake.
- PLA:Polylactic acid provides compostable credentials for organic produce and limited-shelf-life applications. The 55°C heat deflection ceiling blocks hot-fill soups and sauces, restricting penetration to cold-chain protein and fresh-cut segments where thermal exposure remains minimal.
- PVC:Polyvinyl chloride retains cost advantages in blister packs and medical device protection where clarity and thermoformability outweigh sustainability concerns.
- PP:Polypropylene serves microwaveable ready-meal trays through elevated temperature resistance, though opacity limits retail display applications.
- PS:Polystyrene dominates low-cost produce and egg packaging in price-sensitive retail tiers, facing displacement pressure from rPET substitution mandates.
- PETG:Glycol-modified PET offers deep-draw formability for complex medical device geometries and pharmaceutical blister formats requiring impact resistance.
PET holds installed capacity across European food-contact lines. PLA is rotating up the share rankings as compostable packaging premiums widen.
Packaging Application:
Volume concentration follows automation intensity, with protein and produce lines running at highest throughput and locking in standardized tray formats.
- Food Packaging:Protein, produce, and ready-meal segments drive tray volumes through modified-atmosphere barrier integration and shelf-ready presentation requirements. German protein processors are standardizing cavity dimensions to match high-speed filling equipment, consolidating supplier rosters.
- Pharmaceutical Packaging:Blister packs and unit-dose trays for solid oral dosage forms demand ISO 15378 compliance and tamper-evident features. EU Falsified Medicines Directive serialization requirements are pulling RFID-integrated tray designs into qualification pipelines.
- Cosmetic Packaging:Premium skincare and fragrance presentation trays emphasize tactile surface finishes and brand-differentiated color matching over barrier performance.
- Electronics Protection:Antistatic and conductive formulations protect circuit boards and components during assembly and shipment, with ESD specifications conditioning material selection.
- Medical Devices:Sterile barrier trays for surgical instruments and implants require validated sealing surfaces and particulate control, extending qualification timelines.
- Stationery:Low-specification trays for pens, pencils, and office supplies compete on unit cost with minimal barrier or aesthetic requirements.
Food packaging holds installed capacity across automated filling networks. Pharmaceutical packaging is climbing the fastest as serialization mandates expand addressable demand.
End User Industry:
Procurement authority concentrates in centralized technical teams at multinational food processors and pharmaceutical manufacturers, compressing approved supplier lists.
- Food Processing Units:Protein packagers in Germany and France aggregate tray demand through retail cooperative specifications, extracting annual price concessions via tender aggregation.
- Pharmaceutical Manufacturers:Big pharma and generic houses drive barrier tray innovation through serialization compliance and cold-chain distribution requirements.
- Personal Care Brands:Premium cosmetics houses specify custom-molded trays with soft-touch finishes and metallic effects for unboxing experience differentiation.
- Electronics Assemblers:OEM and contract manufacturers in Netherlands industrial corridors source antistatic trays for component protection and automated handling compatibility.
- Healthcare Providers:Hospital systems and surgical centers demand sterile procedure trays with validated seal integrity and lot traceability.
- Educational Institutions:Bulk stationery and art supply distributors represent price-sensitive, specification-loose demand with minimal loyalty.
Food processing units hold installed capacity across standardized format lines. Pharmaceutical manufacturers are gaining share fastest as compliance complexity raises switching costs.
Product Design:
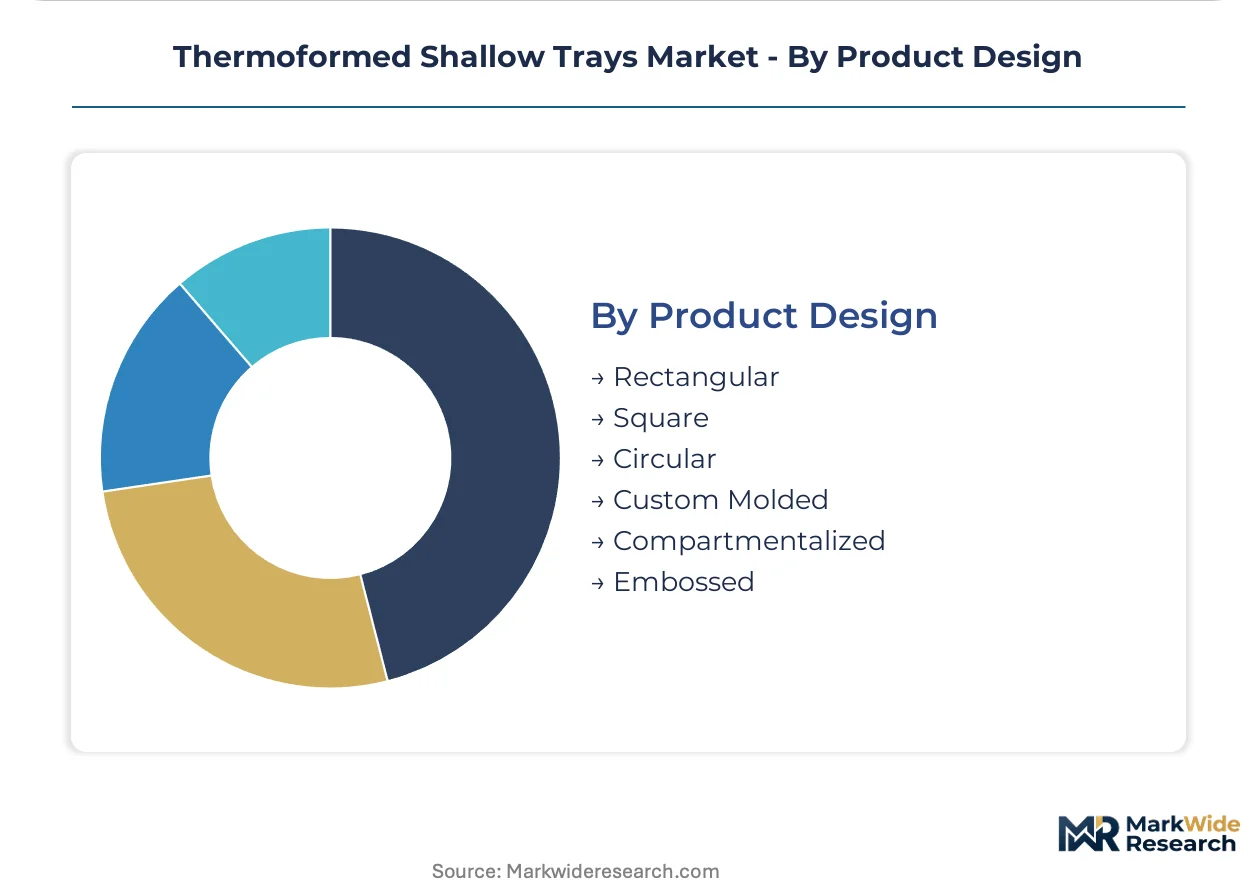
Geometric complexity determines mold capital intensity and cycle economics, with rectangular formats amortizing tooling across highest volumes.
- Rectangular:Standardized length-width ratios dominate protein and produce segments, optimizing pallet cube utilization and retail shelf placement. German retail cooperatives have consolidated procurement around four primary rectangular formats, displacing bespoke dimensions.
- Custom Molded:Proprietary cavity geometries for medical devices and premium cosmetics carry 3-5x mold premiums but lock in sole-source relationships through design registration.
- Square:Balanced footprint suits bakery, confectionery, and portion-controlled ready-meal applications where rotational symmetry simplifies automated filling.
- Circular:Radial symmetry serves pie, tart, and single-serve dessert packaging, with rim specifications tailored to lidding film sealing profiles.
- Compartmentalized:Multi-cavity designs separate protein, starch, and vegetable components in meal-kit and airline catering trays, demanding precise tolerance control for lid sealing.
- Embossed:Surface texture and logo relief enhance brand differentiation in premium cosmetic and gift packaging segments with minimal functional barrier requirements.
Rectangular designs hold installed capacity across retail cooperative specifications. Custom molded formats are climbing the fastest as medical device and premium cosmetic volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in thermoformed shallow trays tilt toward net outflows from resin-rich manufacturing clusters toward consumption centers in retail-dense economies. Germany and the Netherlands maintain surplus positions through integrated converter networks, while Southern European markets absorb cross-border tray volumes amid domestic collection infrastructure gaps.
Germany
Centralized retail distribution through buying cooperatives concentrates tray procurement authority, locking in multi-year supply agreements with standardized format specifications. The EU Packaging Waste Regulation mandates recycled content thresholds that retailers are pre-empting through rPET contract commitments. The Rhine-Ruhr industrial corridor hosts dense thermoforming capacity serving protein processors with high-speed filling compatibility.
France
Protein packagers in the Paris Basin and Lyon region are standardizing cavity dimensions to match automated equipment, consolidating supplier rosters around fewer approved vendors. REACH restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings, forcing reformulation of bakery and fried protein tray lines. The Grand Est region hosts specialized converters qualifying PLA substrates for organic produce channels.
Netherlands
Rotterdam's chemical recycling cluster offers proximity to both rPET supply streams and North Sea export logistics for tray converters serving Northwest European markets. The country's national packaging waste regulator enforces extended producer responsibility frameworks that elevate compliance costs for imported tray volumes. Eindhoven's materials science corridor supports barrier film integration with mono-material PET structures.
United States
FDA food contact regulations and EPA recycled content mandates steer investment toward verified sustainable material streams for foodservice and retail applications. The Southeast industrial corridor concentrates thermoforming capacity serving quick-service restaurant chains with standardized shallow tray formats. California's state-level packaging regulations are accelerating rPET qualification timelines ahead of federal enforcement.
China
Dual carbon goals and national packaging standards are reshaping material specifications for export-oriented tray production serving European and North American brand owners. The Yangtze River Delta hosts integrated resin-to-converter operations capturing scale efficiencies in PET sheet extrusion. Shenzhen's electronics assembly clusters generate specialized demand for antistatic thermoformed protection trays with ESD specifications.
Thermoformed Shallow Trays Market Key Industry Players
Concentration sits with integrated resin producers and specialized thermoforming job shops reorganizing competitive tiers through capital-intensity divergence. The vendor base spans captive resin converters sustaining margin stability across polymer cycles, fiber-based hybrid specialists competing with conventional plastic formats, and global preform-to-tray networks controlling specification consistency. Dominant competitive moves include backward integration into rPET flake sourcing and rapid CAD-to-mold prototyping services that bypass traditional packaging distributors.
Within the integrated converter tier, Pactiv Evergreen and Amcor exemplify archetypes leveraging captive supply chains and global conversion networks respectively. Among specialized European fabricators, Faerch Group occupies a position representing compostable substrate qualification expertise. These three companies anchor the competitive structure through differentiated approaches to resin access, geographic coverage, and sustainability certification depth.
| Leading Market Players |
|---|
| Pactiv Evergreen |
| Sonoco Products Company |
| Amcor |
| Jamestown Plastics |
| Indepak |
| Berry Global |
| Faerch Group |
| Nefab |
| Huhtamaki |
| Others |
Cost & Logistics Intelligence
EU REACH chemical restrictions gate both supplier qualification timelines and price differentiation across food-contact and pharmaceutical tray tiers simultaneously. Food-grade rPET certification complexity creates tiered margin pools where verified flake sourcing commands premiums over generic recycled feedstock.
Pricing Analysis
Configured-to-order pricing for custom-molded pharmaceutical trays spreads 40-60% above standardized rectangular produce formats. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with BRC-registered lines capturing sustained premiums over uncertified competitors. Pricing pressure stems from German retail cooperative tender aggregation extracting annual concessions from approved suppliers. Price-sensitive demand concentrates in polystyrene produce and egg packaging, while pharmaceutical serialization trays show minimal elasticity.
Supply Chain Analysis
Just-in-time resin delivery dominates food packaging converters serving automated filling lines, while pharmaceutical tray fabricators maintain strategic stockpiles of food-grade PETG for qualification continuity. Supply concentrates in Germany, the Netherlands, and China's Yangtze River Delta, with rPET flake sourcing increasingly tethered to Rotterdam's chemical recycling cluster. Raw material dependencies center on virgin PET resin, food-grade recycled flake, and PLA biopolymer pellets. Single-source vulnerability runs through Southern Europe's underdeveloped collection infrastructure. Distribution runs through retail buying cooperatives in Germany and quick-service restaurant supply chains in the US Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU packaging regulations fragment demand into rPET-qualified, PLA-compostable, and conventional virgin-material tiers. Sustainability mandates create niche entry points for substrate specialists.
For Market Incumbents: Consolidate backward into rPET flake sourcing to defend margin stability against feedstock volatility. Lock in multi-year contracts with German retail cooperatives before EU Packaging Waste Regulation enforcement tightens approved supplier rosters. Capacity expansion in the Netherlands' Rotterdam corridor captures proximity to chemical recycling supply and North Sea export logistics. For New Entrants and Emerging Players: Rapid CAD-to-mold prototyping services represent a service-layer gap where incumbents under-serve small-batch pharmaceutical and premium cosmetic clients. Penetrate pharmaceutical serialization tray demand created by EU Falsified Medicines Directive compliance timelines. Target Netherlands-based converters with barrier film integration partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mono-material PET barrier technology lines as oxygen-scavenger substrate development demands specialized extrusion equipment. Long-term viability favors converters with integrated resin sourcing or proprietary compostable substrate qualification. Watch rPET food-grade flake price spreads as the inflection indicator for converter margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Sourcing | Captures margin stability across volatile polymer feedstock cycles for food-contact lines. |
| Pharmaceutical Serialization Tray Qualification | Locks in multi-year supply agreements under EU Falsified Medicines Directive mandates. |
| PLA Substrate Certification Investment | Opens organic produce channel access as compostable packaging premiums widen. |
| Rotterdam Corridor Capacity Expansion | Positions converters adjacent to chemical recycling supply and North Sea export routes. |
| Rapid CAD-to-Mold Prototyping Services | Bypasses traditional packaging distributors for small-batch pharmaceutical and cosmetic clients. |
Research Approach
Cross-validation between converter production data and retail procurement records anchors the qualitative findings. Primary interviews with thermoforming plant managers, retail category buyers, resin procurement leads, and pharmaceutical packaging engineers combined with secondary validation from EU Packaging Waste Regulation filings, FDA food-contact substance notifications, customs trade data, and SEC filings from listed packaging converters. Bottom-up capacity modeling and top-down demand estimation triangulate volume estimates.
Sensitivity analysis tested forecast outputs against rPET feedstock availability scenarios and PLA thermal performance limitations. Segmentation dimensions modeled include material chemistry, barrier specification tier, automation compatibility, and end-use industry regulatory cluster. CAGRs derived from installed capacity expansion timelines and retail cooperative contract renewal patterns. Forecast inputs incorporate modified-atmosphere barrier film adoption curves and pharmaceutical serialization mandate compliance deadlines.
Forecasts assume regulatory continuity in EU REACH, FDA food contact, and EPA recycled content mandates; material policy shifts would require re-modeling. Specific risk factors include PFAS ban acceleration, BRC audit capacity constraints, and Southern European collection infrastructure gaps. Revision becomes warranted when rPET food-grade flake price volatility crosses thresholds that compress converter margins below qualification sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Concentrate Containers Market
Containers
Global Multi Pack Carriers Market
Containers
Cubitainer Market
Containers
Popcorn Containers Market
Containers
Jerry Cans Market
Containers
Collapsible Sleeve Containers Market
Containers
Acrylic Container Market
Containers
Modular Container Market
Containers
Sanitary Cans Market
Containers
Stack and Nest Containers Market
Containers
Container Liner Market
Containers
Shipping Container Liners Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
HDPE Containers Market
Containers
Vials Market
Containers
USA and Canada Packer Bottle Market