
 Wheat Gluten Market | 2026-2036
Wheat Gluten Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Gluten Market Outlook
Multi-source wheat protein procurement is consolidating around vertically integrated grain processors with captive milling assets. Cargill, Incorporated leverages its North American grain origination network to secure low-cost durum and hard red wheat streams for gluten extraction. Tereos sustains European market presence through co-located ethanol and protein recovery plants in France and Belgium. Manildra Group anchors Asia-Pacific supply from Australian wheat belts, competing on freight-advantaged export volumes into Southeast Asian noodle manufacturers.
Wheat gluten comprises the insoluble protein complex—primarily gliadin and glutenin fractions—recovered through dough washing and centrifugal separation of wheat flour slurry, yielding a tan powder with protein content typically between 75% and 85% on a dry basis. Its primary industrial purpose centers on viscoelastic network formation in dough systems and texturization in restructured meat and fish analogues. Vital wheat gluten dominates volume flows into commercial baking and instant noodle production where elasticity and water absorption drive formulation economics. Modified wheat gluten commands narrower but higher-margin positions in plant-based meat applications where thermoset gelation and fibrous texture alignment justify premium positioning over commodity grades.
The USDA and FDA govern wheat gluten labeling, allergen declaration, and GRAS status in the United States, while the EU Green Deal and EFSA protein quality assessments shape European import and carbon intensity requirements. China's SAMR and GB standards impose foreign manufacturer registration and residue testing protocols that filter market access for non-domestic suppliers. Stakeholders must monitor evolving allergen threshold harmonization between Codex Alimentarius and national food safety agencies, as well as the pace of EU deforestation-free supply chain due diligence rules that will recertify wheat sourcing geographies.
Market Dynamics
The EU Green Deal's tightening carbon accounting for protein ingredients is forcing plant-based meat formulators toward premium-grade vital wheat gluten procurement, consolidating supply relationships around vertically integrated grain processors with verified low-carbon milling assets.
Growth Catalysts
- EU Green Deal carbon intensity rules:Protein ingredient sourcing now requires documented lifecycle emissions, driving bakery and meat-alternative manufacturers toward certified low-carbon wheat gluten suppliers in Germany and France.
- Plant-based meat texturization demand:Thermoset gelation properties of modified wheat gluten enable fibrous texture alignment in restructured protein products, creating specification pull from European and North American formulators.
- Hard red wheat belt concentration:North American durum and hard red wheat streams offer protein content advantages for gluten extraction, anchoring supply security for large-scale bakery operations.
Market Restraints
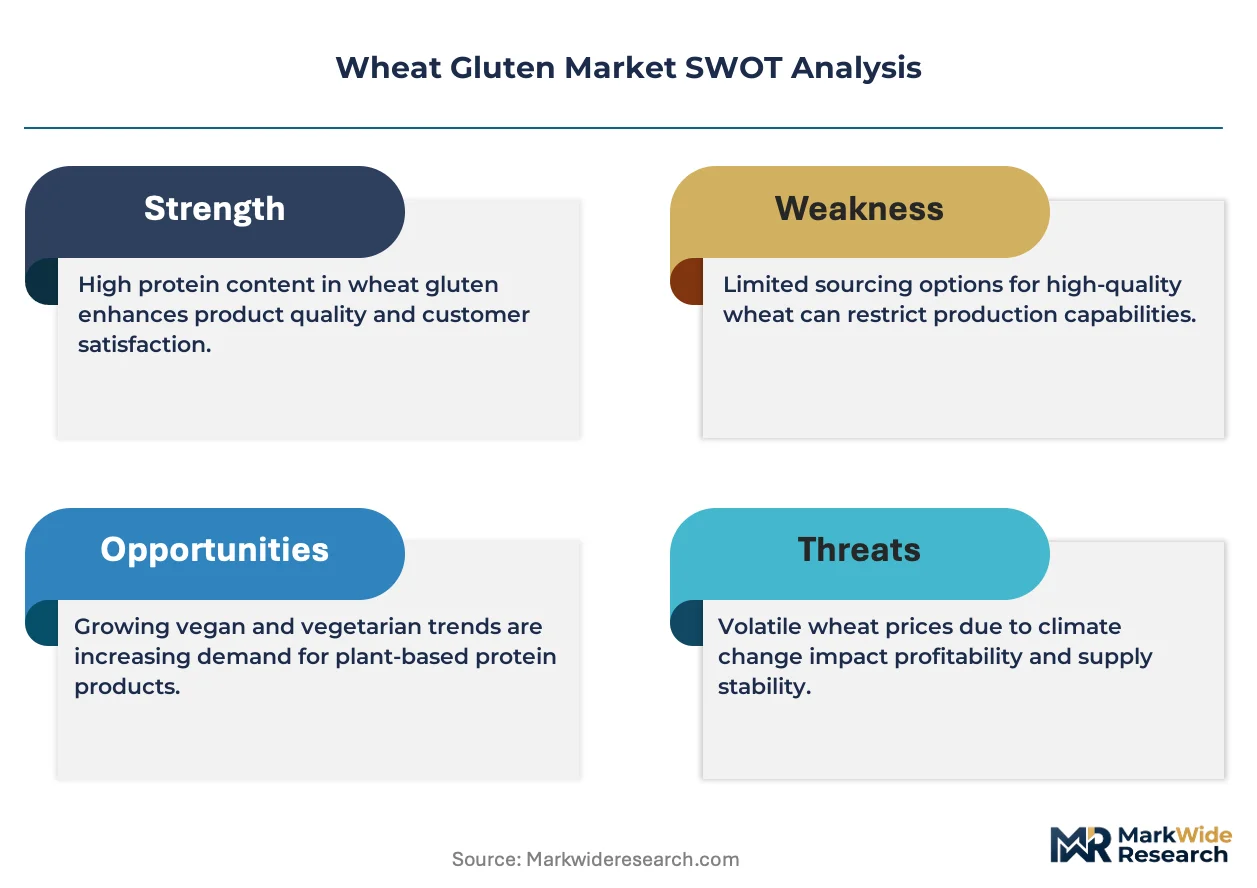
- Input cost volatility in wheat futures:Weather-driven yield fluctuations in Australian and North American wheat belts transmit directly to gluten extraction economics, compressing processor margins during drought cycles.
- Supply concentration in captive milling networks:Vertically integrated grain processors control origination-to-extraction pipelines, limiting spot market liquidity for independent bakery procurement teams.
- Technical limitation in thermoset gelation:Modified wheat gluten's narrow moisture-window processing requirements constrain adoption among mid-scale meat-alternative manufacturers lacking precision extrusion equipment.
Strategic Opportunities
- Underpenetrated Southeast Asian noodle markets:Freight-advantaged Australian wheat gluten exports compete with domestic Chinese supply for premium instant noodle elasticity specifications in Indonesia and Vietnam.
- Regulatory tailwind from EU deforestation-free rules:Due diligence requirements on wheat sourcing geographies will recertify supply chains, creating first-mover advantage for processors with traceable North American and Australian grain origination.
- Technology convergence in protein recovery:Co-location of ethanol fermentation and gluten extraction at integrated biorefineries yields energy and water efficiencies that standalone mills cannot replicate.
Industry Challenges
- Allergen threshold harmonization complexity:Divergence between Codex Alimentarius guidance and national food safety agency implementations complicates labeling compliance for exporters serving multiple jurisdictions.
- Certification timeline compression:China's SAMR foreign manufacturer registration and residue testing protocols filter market access, requiring 12-18 month qualification cycles for non-domestic suppliers.
- Capex intensity in precision extrusion:Meat-alternative texture alignment requires capital-intensive twin-screw extrusion systems that mid-scale formulators struggle to justify at current volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Gluten Market |
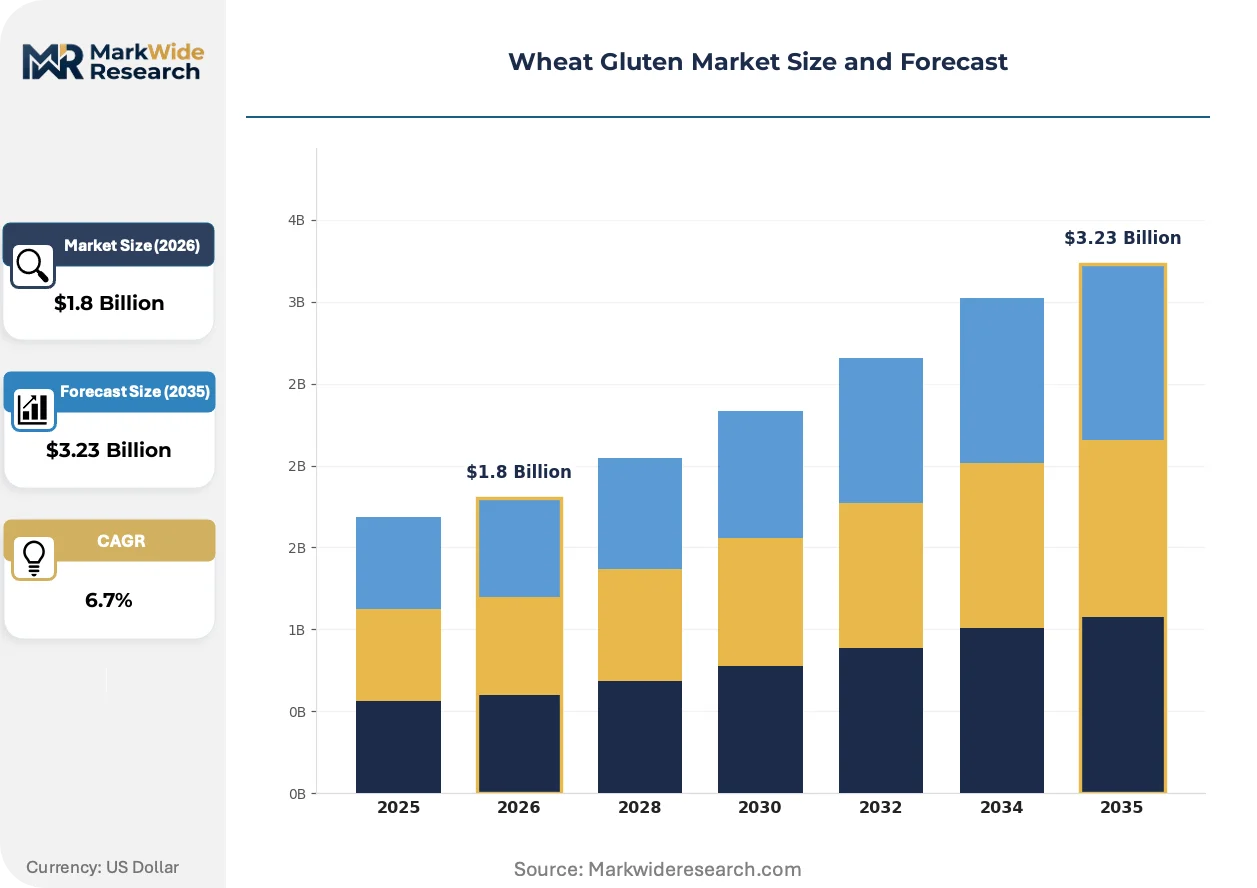
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vital Wheat Gluten, Regular Wheat Gluten, Modified Wheat Gluten, Instant Wheat Gluten Application: Baking, Confectionery, Meat Products, Noodles End User: Food Manufacturers, Retailers, Foodservice Providers, Home Bakers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tereos, Roquette Frères, MGP Ingredients, Manildra Group, Crespel & Deiters GmbH, Royal Ingredients Group, Pioneer Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Gluten Market Strategic Shifts
Protein extraction technology and regulatory carbon accounting are converging to reshape competitive positioning in wheat gluten supply chains. Three developments warrant particular attention from procurement strategists and processing investors.
Enzymatic modification of glutenin fractions is consolidating control over thermoset gelation properties in high-value meat-analogue applications. European plant-based meat formulators are adopting these modified grades at accelerated specification rates. The technology is consolidating premium pricing power among processors with captive R&D capabilities, compressing commodity-grade margin pools.
REACH and EU Green Deal due diligence frameworks are mandating deforestation-free wheat sourcing documentation. Industrial consequence includes mandatory geolocation verification for grain origination. German and French bakery manufacturers are most affected, responding by locking multi-year supply contracts with North American processors offering certified traceability.
Buyer concentration among multinational meat-alternative brands is shortening switching cycles for protein ingredient suppliers. Direct procurement relationships are displacing traditional distributor intermediaries in premium-grade transactions. This pattern is most visible in the United States, where Impossible Foods and Beyond Meat procurement teams negotiate specification-grade contracts directly with Tereos and Cargill protein divisions.
Wheat Gluten Market Segmentation
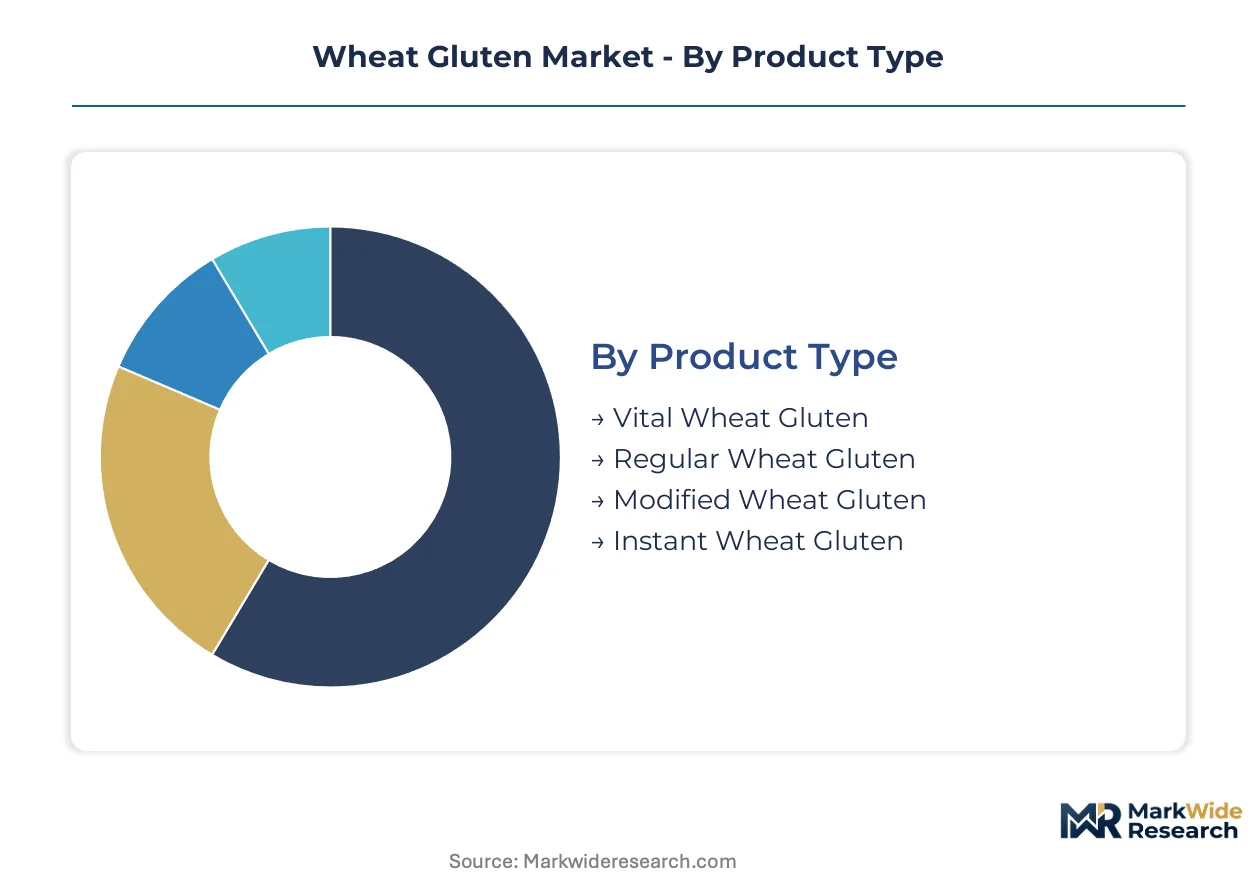
Wheat gluten procurement strategies diverge sharply across product grades and end-use specifications. Supply relationships consolidate around processors capable of certifying protein content, carbon intensity, and allergen compliance for each distinct segment.
Product Type:
Supply concentration clusters around extraction technologies that separate protein fractions with precision.
- Vital Wheat Gluten:The insoluble protein complex—gliadin and glutenin fractions recovered through dough washing and centrifugal separation—typically assays 75% to 85% protein on a dry basis. Commercial bakeries in Germany and France lock multi-year contracts for elasticity-critical applications, with EU Green Deal carbon accounting favoring processors with verified low-carbon milling assets.
- Modified Wheat Gluten:Enzymatic or chemical alteration of glutenin fractions enables thermoset gelation and fibrous texture alignment in restructured meat analogues. Plant-based meat formulators in the United States negotiate specification-grade contracts directly with integrated processors, bypassing traditional distribution channels.
- Regular Wheat Gluten:Standard-grade extraction serves cost-sensitive noodle manufacturers in Southeast Asia where freight-advantaged Australian supply competes on landed cost.
- Instant Wheat Gluten:Pre-hydrated or agglomerated formats target small-scale foodservice operations and home baking segments with simplified handling requirements.
Vital wheat gluten absorbs the bulk of installed capacity; modified wheat gluten is expanding most quickly.
Application:
Cost tier separation between commodity elasticity applications and premium texturization specifications drives procurement channel selection.
- Baking:Viscoelastic network formation in dough systems demands consistent protein content and water absorption indices. Large-scale European bakery operations command premium-grade supply contracts with carbon-verified processors.
- Meat Products:Restructured protein applications require modified gluten with narrow moisture-window processing parameters. Mid-scale manufacturers face capital constraints in precision extrusion equipment adoption.
- Noodles:Instant noodle elasticity specifications in Indonesia and Vietnam absorb freight-advantaged Australian export volumes competing with domestic Chinese supply.
- Confectionery:Lower-volume applications utilize gluten for binding and texture modification in specialized candy and pastry formulations.
Baking commands the largest share of volume flows; meat products applications are climbing the fastest.
End User:
Customer type determines contract structure, with direct procurement displacing intermediaries in premium-grade transactions.
- Food Manufacturers:Industrial-scale formulators in bakery, meat-alternative, and noodle segments negotiate specification-grade contracts with integrated grain processors. FDA allergen labeling and EU deforestation-free due diligence requirements filter supplier qualification.
- Foodservice Providers:Restaurant chains and institutional kitchens procure through wholesale channels with emphasis on consistent hydration performance and simplified inventory management.
- Retailers:Private-label and branded packaged goods distribution concentrates in supermarket and specialty store channels with regional protein content labeling compliance.
- Home Bakers:Small-format retail packaging serves consumer segments with convenience-oriented instant or pre-measured gluten products.
Food manufacturers absorb the bulk of procurement volume; foodservice providers are gaining share fastest.
Distribution Channel:
Margin structure varies with channel control over specification verification and logistics coordination.
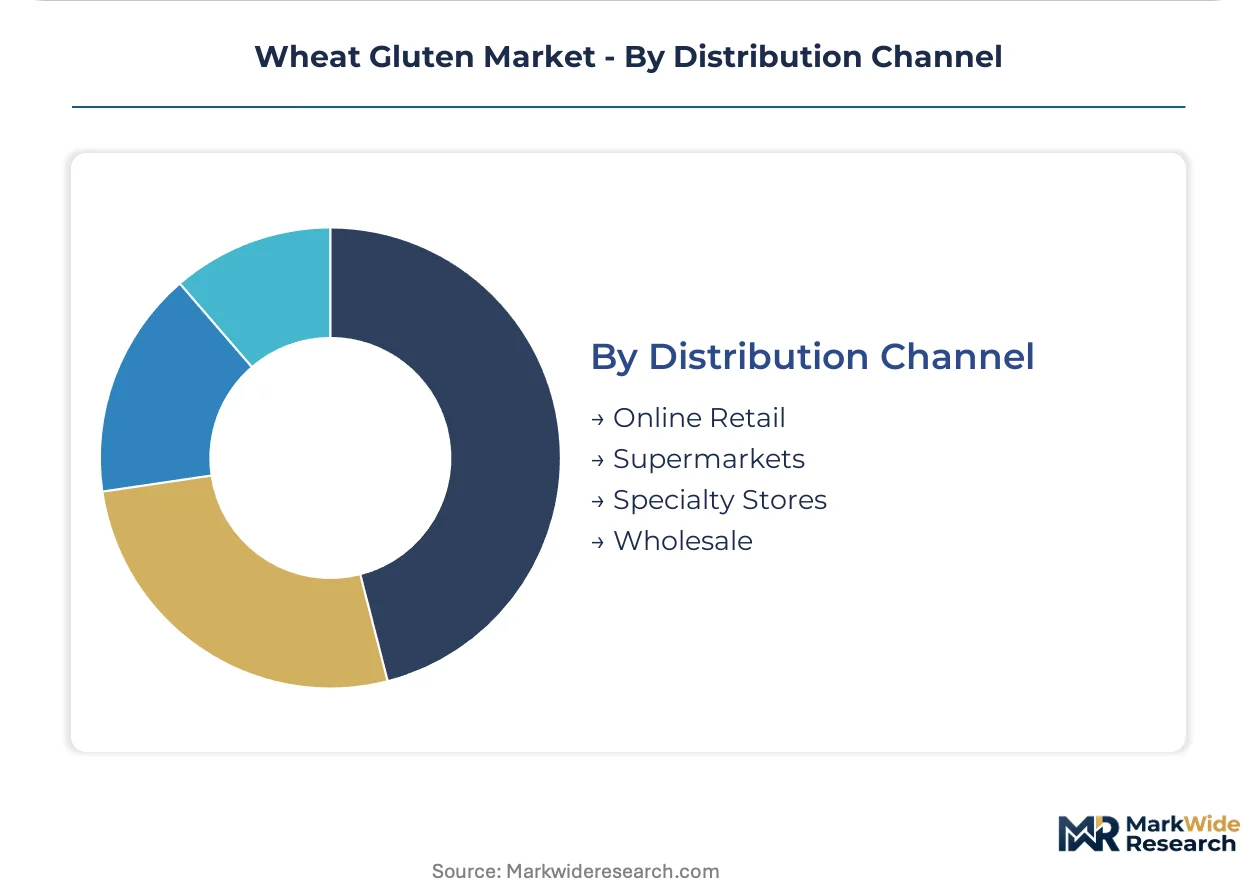
- Wholesale:Bulk volume flows to industrial food manufacturers through processor-direct relationships or specialized ingredient distributors. Contract terms incorporate protein content guarantees and carbon intensity documentation.
- Supermarkets:Packaged consumer and small-format professional products reach retail shelves with regional allergen labeling compliance and shelf-stable packaging requirements.
- Online Retail:Direct-to-consumer and small-business procurement platforms serve home bakers and specialty food producers with fragmented order sizes.
- Specialty Stores:Professional baking supply and health food channels cater to niche segments seeking organic or non-GMO certified gluten grades.
Wholesale channels handle the bulk of tonnage; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard red wheat cultivation across the North American Great Plains, the Paris Basin, and Australia's Murray-Darling Basin anchors gluten extraction capacity. Protein content differentials between these grain belts shape regional supply economics and export competitiveness.
United States
Plant-based meat formulators in Chicago and Minneapolis-St. Paul drive specification-grade procurement of modified wheat gluten. FDA allergen labeling requirements and GRAS status protocols filter supplier qualification for domestic and export-bound production. Cargill's North American grain origination network secures low-cost durum and hard red wheat streams for captive gluten extraction.
Germany
Commercial bakeries in Munich and Hamburg command premium-grade vital wheat gluten contracts with carbon-verified processors. EU Green Deal lifecycle emissions documentation now mandates certified low-carbon milling assets for protein ingredient sourcing. The Rhine-Ruhr industrial corridor concentrates co-located ethanol fermentation and gluten extraction capacity at integrated biorefineries.
France
Meat-alternative manufacturers in Lyon and Paris negotiate direct procurement relationships bypassing traditional distribution channels. EFSA protein quality assessments and REACH due diligence frameworks shape import requirements and deforestation-free supply chain certification. Tereos sustains market presence through protein recovery plants in the Hauts-de-France region.
Australia
Freight-advantaged export volumes from the Murray-Darling Basin compete for premium instant noodle elasticity specifications in Indonesia and Vietnam. TGA-equivalent food safety protocols and residue testing standards govern export certification for Southeast Asian markets. Manildra Group anchors Asia-Pacific supply from New South Wales and Victorian wheat belts.
China
Domestic noodle manufacturers in Henan and Shandong provinces absorb local gluten supply while importing premium grades for high-protein applications. SAMR foreign manufacturer registration and GB standards impose 12-18 month qualification cycles that filter non-domestic supplier market access. Yangtze River Delta food processors drive demand for consistent water absorption indices in commercial baking.
Wheat Gluten Market Competitive Environment
Global majors compete with regional champions across origination-to-extraction pipelines. Supply relationships consolidate around vertically integrated grain processors with captive milling assets and verified carbon accounting. Three archetypes dominate: North American agricultural conglomerates with continental grain networks, European cooperative processors with biorefinery integration, and Asia-Pacific specialists with freight-advantaged export positioning. Competitive moves center on multi-year supply contract lock-ins with carbon documentation and precision modification capability for meat-analogue applications.
Among North American agricultural conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven origination-to-extraction control. European cooperative processors find representation in Tereos and Roquette Frères, occupying positions defined by biorefinery co-location and EU regulatory compliance. Crespel & Deiters GmbH anchors the specialist tier, representing German precision-processing heritage in modified gluten fractions. These named entities sit within a structure where direct procurement relationships increasingly displace distributor intermediaries in premium-grade transactions.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tereos |
| Roquette Frères |
| MGP Ingredients |
| Manildra Group |
| Crespel & Deiters GmbH |
| Royal Ingredients Group |
| Pioneer Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned grain processors with multi-generational milling heritage anchor supply discipline through long-term origination contracts that buffer spot-market volatility and sustain premium-grade pricing power against commodity traders.
Pricing Analysis
Warranty-bundled carbon certification and protein-content guarantees separate premium vital wheat gluten contracts from unbundled standard-grade spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects EU Green Deal compliance tiers, volume scale, and after-sales technical support inclusion. Cost compression in standard-grade segments is intensifying because Australian freight-advantaged exports compete on landed cost in Southeast Asian noodle markets. Mid-scale meat-alternative manufacturers lacking precision extrusion equipment exhibit highest price sensitivity; large European bakery operations with multi-year carbon-verified contracts show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Chicago anchor hub-and-spoke patterns that consolidate Australian, North American, and European originations into processor-direct delivery lanes. Wheat gluten supply concentrates in the United States, France, and Australia where hard red wheat belts feed captive milling assets. Extraction economics rest on durum and hard red wheat futures, energy costs at co-located biorefineries, and carbon certification audit expenses. Single-source vulnerability runs through vertically integrated grain processors controlling origination-to-extraction pipelines. Distribution runs through processor-direct bulk contracts for industrial manufacturers, with spot-market liquidity limited for independent bakery procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU deforestation-free supply chain recertification will force smaller processors lacking traceable grain origination systems to exit or sell.
For Market Incumbents: Extend carbon-verified supply contract lock-ins with German and French bakery manufacturers before EU Green Deal due diligence rules fully phase in. Acquire distressed Australian export-oriented processors to secure freight-advantaged positioning into Indonesian and Vietnamese noodle markets. Cargill and Tereos already demonstrate this pattern through multi-year specification-grade agreements that displace distributor intermediaries.
For New Entrants and Emerging Players: Specialty distributors serving mid-scale meat-alternative manufacturers represent the most accessible channel entry point given incumbent concentration in direct industrial relationships. Target Southeast Asian instant noodle producers seeking elasticity-grade alternatives to domestic Chinese supply. Lead with modified wheat gluten technical support services that justify premium positioning over commodity-grade competitors lacking precision extrusion guidance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian mid-cap processors with Murray-Darling Basin origination assets and existing SAMR registration progress for Chinese market access. Long-term viability over a multi-year horizon rests on biorefinery co-location economics and carbon-accounting compliance infrastructure. Watch for EU deforestation-free rule implementation timelines as the inflection signal triggering accelerated contract renegotiation and processor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's North American network secures low-cost hard red wheat streams for captive gluten extraction. |
| Biorefinery Co-location Investment | Tereos sustains European presence through energy-efficient ethanol fermentation and protein recovery integration. |
| Carbon Certification Program | EU Green Deal compliance creates first-mover advantage for processors with verified low-carbon milling assets. |
| Direct Procurement Relationship Expansion | Impossible Foods and Beyond Meat negotiate specification-grade contracts bypassing traditional distribution channels. |
| SAMR Registration Acceleration | Foreign manufacturer qualification protocols filter market access for 12-18 month cycles in Chinese noodle markets. |
Study Parameters
Multi-period observation of wheat futures volatility, protein content spreads, and carbon certification adoption rates anchored the trend analysis, supplemented by interviews with grain procurement directors at European bakery conglomerates, plant-based meat formulation scientists, and integrated biorefinery operations managers. Secondary validation drew from USDA crop reports, EU Green Deal regulatory filings, EFSA protein quality assessments, and customs trade data for Australian wheat gluten exports. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Segment-weighting across product grades, application specifications, and end-user contract structures informed the analytical framework throughout the projection horizon. Modeled dimensions included vital versus modified gluten fractions, baking versus meat-alternative versus noodle end-uses, and food manufacturer versus foodservice versus retail channel splits. CAGRs derived from protein ingredient substitution elasticities and regulatory-driven procurement shift assumptions. Wheat yield variance in Australian and North American belts, plus EU deforestation-free rule implementation pace, served as key forecast sensitivity inputs.
Caveats apply where weather-driven yield collapses, accelerated EU due diligence timelines, or SAMR registration delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
US Plant-Based Oils Market
Ingredients
Brewer's Yeast Market
Ingredients
North America Feed Yeast Market
Ingredients
Mastic Gum Market
Ingredients
Seaweed Extracts Market
Ingredients
Bay Leaf Oil Market
Ingredients
Pig Protein Concentrate Market
Ingredients
PHO Oils Market
Ingredients
Pea Starch Market
Ingredients
Biotech Ingredients Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Non-GMO Soya Market
Ingredients
Sweet Almond Oil Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Bulk Food Ingredients Market