
 Marine Ingredients Market | 2026-2036
Marine Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Ingredients Market Outlook
Peruvian reduction fishery quotas is realigning global fish meal availability and pressuring buyers toward alternative sourcing. Aker BioMarine leverages Antarctic krill harvesting to secure a differentiated position in omega-3 supply. Hofseth BioCare ASA specializes in enzymatic processing of salmon rest raw material, converting waste streams into high-value protein and oil fractions. TripleNine Group A/S anchors North Sea sourcing through its Danish reduction operations, competing on proximity to European aquaculture demand.
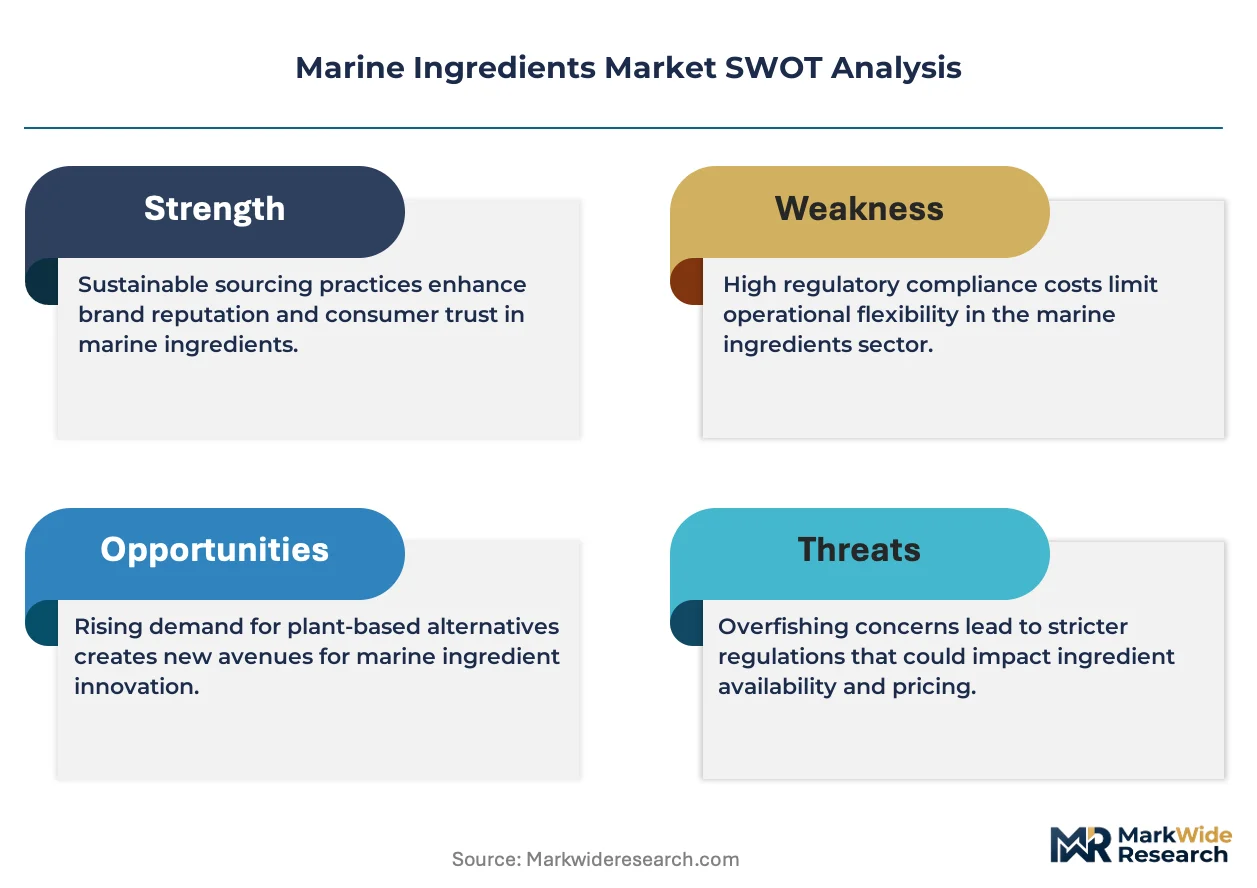
Marine ingredients comprise proteins, lipids, and bioactive compounds extracted from fish, shellfish, and macroalgae through reduction, enzymatic hydrolysis, or solvent extraction, typically yielding meals with 60-72% crude protein or oils with 15-30% omega-3 fatty acid content by weight. These inputs serve as essential nutritional building blocks for formulated animal diets, human supplements, and functional cosmetic bases. Fish oil retains dominance in dietary supplements due to established EPA/DHA clinical validation, while seaweed extracts are gaining fastest in personal care formulations where algae-derived polysaccharides replace petrochemical humectants. Krill powder occupies a premium niche in nutraceutical applications, commanding margin pools tied to phospholipid-bound omega-3 bioavailability claims.
The EU Green Deal and F-Gas Regulation shape sourcing compliance costs for European processors, while Peru's national fishery regulator sets annual anchovy total allowable catch that ripples through global fish meal pricing. The Marine Stewardship Council certification and ASC feed standards increasingly gate market access for premium aquaculture supply chains. Stakeholders must monitor how Antarctic Treaty System negotiations affect krill harvest zones and whether enzymatic hydrolysis investments can offset raw material scarcity in established reduction fisheries.
Market Dynamics
Peru's anchovy quota regime concentrates global fish meal supply control in a single national regulator, forcing downstream buyers to absorb volatility or pivot to alternative omega-3 sources. This supply chokepoint reshapes procurement strategies across aquaculture feed, human nutraceuticals, and pet nutrition verticals.
Growth Catalysts
- Aquaculture feed certification:ASC feed standards mandate marine ingredient traceability, pulling premium salmon and shrimp producers toward certified fish oil and meal suppliers in Norway and Chile.
- EU Green Deal sustainability mandates:The EU F-Gas Regulation and circular economy action plan accelerate demand for enzymatically processed salmon rest raw material as a lower-carbon input alternative.
- Antarctic krill harvesting:Antarctic Treaty System harvest zones offer quota-backed supply security that omega-3 extractors leverage to differentiate from volatile reduction fisheries.
Market Restraints
- Anchovy catch concentration:Peru's IMARPE-set total allowable catch governs roughly one-third of global fish meal volume, creating single-point supply risk.
- Omega-3 algal oil substitution:Fermentation-derived DHA from Schizochytrium strains displaces fish oil in infant formula and vegan supplement applications.
- EU regulatory compliance costs:REACH registration and EFSA novel food approvals impose capital barriers for new marine ingredient entrants.
Strategic Opportunities
- Seaweed bioactive expansion:Algae-derived fucoidan and phlorotannin extracts penetrate cosmeceutical formulations as petrochemical humectant replacements.
- Enzymatic hydrolysis scale-up:Cold-processing technology unlocks protein and oil fractions from fish processing waste streams at lower thermal cost than traditional reduction.
- India aquaculture feed growth:Shrimp farming expansion in Andhra Pradesh and Gujarat generates demand for imported fish meal beyond domestic supply capacity.
Industry Challenges
- MSC certification timeline compression:Fishery assessment and chain-of-custody audits require 12-18 month lead times that conflict with just-in-time procurement cycles.
- Antarctic krill block licensing:CCAMLR conservation measures restrict harvest zones, forcing operators to navigate spatial competition and seasonal ice constraints.
- Salmon rest raw material logistics:Enzymatic processing requires fresh substrate delivery within 24 hours of filleting, straining cold-chain infrastructure in remote Norwegian and Chilean farming regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Ingredients Market |
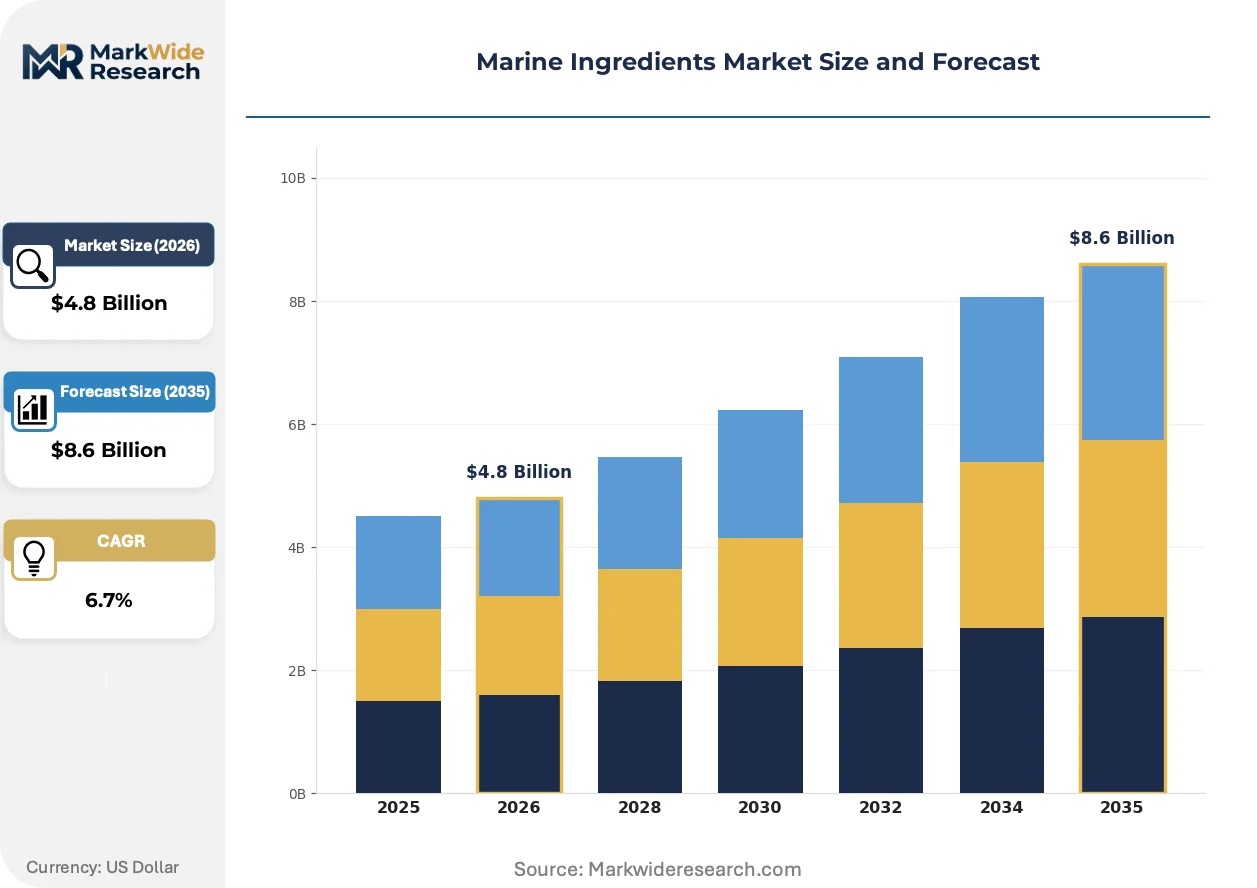
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Meal, Fish Oil, Seaweed Extracts, Krill Powder Application: Animal Feed, Dietary Supplements, Cosmetics, Pet Food End User: Aquaculture, Nutraceutical, Personal Care, Food Processing Distribution Channel: Online Sales, Direct Sales, Retail, Wholesale |
| Companies Covered | Cargill Incorporated, Hofseth BioCare ASA, Aker BioMarine, Symrise AG, Omega Protein Corporation, Bio-marine Ingredients Ireland Ltd, TripleNine Group A/S, SA Copalis, Gelita AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Ingredients Market Strategic Shifts
Marine ingredient extraction technology is fragmenting from centralized reduction plants toward distributed enzymatic processing units co-located with fishing and aquaculture operations. This geographic redistribution of processing capacity reshapes supply economics and raw material competition.
Membrane filtration and low-temperature enzymatic hydrolysis is decentralizing protein and oil recovery from fish processing waste. Norwegian salmon farmers and Chilean aquaculture operators install on-site hydrolysis units to capture value from rest raw material previously sold to reduction plants. This distributed model shortens supply chains and reduces thermal degradation of heat-sensitive bioactives.
The EU Green Deal's F-Gas Regulation and CSRD reporting requirements tighten carbon footprint disclosure for marine ingredient imports. European aquaculture feed compounders now demand batch-level sustainability documentation that Peruvian and North African suppliers struggle to provide. This compliance gap favors Antarctic krill and enzymatically processed inputs with established lifecycle assessments.
Long-term offtake contracting is displacing spot market purchasing among major aquaculture feed producers. Buyers in Norway, Chile, and Vietnam lock in multi-year omega-3 supply agreements to hedge against Peruvian quota volatility. This procurement consolidation concentrates purchasing power with vertically integrated salmon farming groups and compresses margins for speculative traders.
Marine Ingredients Market Segmentation
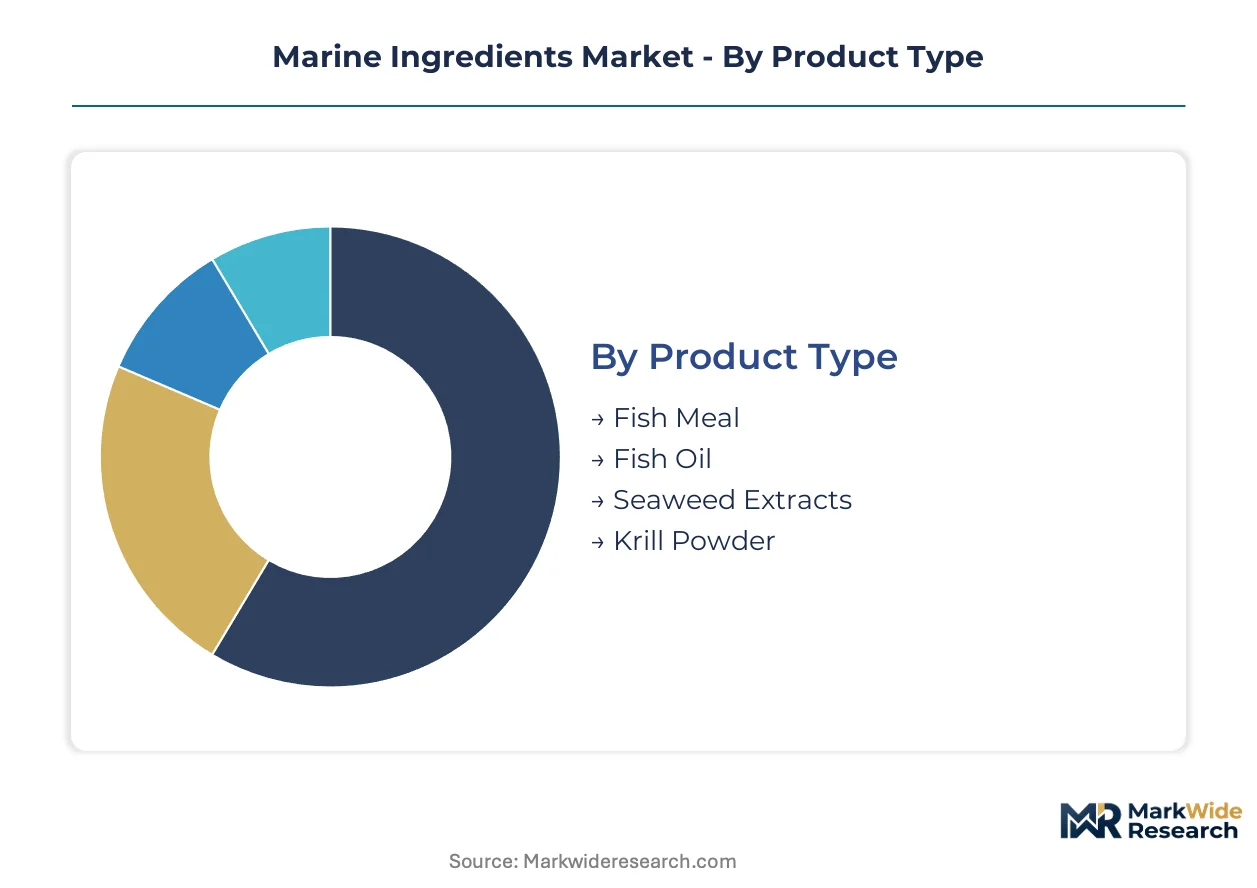
Marine ingredient processors configure their asset bases around distinct input streams and extraction technologies. Segmentation reveals where capital deployment concentrates and which product lines command premium positioning.
Product Type:
Fish meal production demands the heaviest upfront investment, with reduction plants requiring dedicated vessel fleets, drying infrastructure, and energy-intensive thermal processing. Krill extraction and enzymatic hydrolysis systems carry lower fixed costs but higher per-unit technology licensing fees.
- Fish Meal:Dried ground powder from whole fish or trimmings containing 60-72% crude protein by weight. Demand concentrates in Norwegian and Chilean salmon feed operations where ASC certification mandates traceable marine inputs. Peruvian quota volatility forces buyers toward long-term contracting or alternative sourcing.
- Fish Oil:Refined lipid fraction with 15-30% EPA/DHA omega-3 content extracted via wet pressing or solvent methods. Human nutraceutical manufacturers in Germany and Spain source pharmaceutical-grade batches for encapsulation, though algal DHA fermentation erodes infant formula market share.
- Seaweed Extracts:Polysaccharide and bioactive concentrates from macroalgae harvesting.
- Krill Powder:Antarctic-sourced phospholipid-bound omega-3 meal commanding premium positioning in nutraceutical applications.
Most installed capacity flows through fish meal. Expansion is steepest in krill powder.
Application:
Volume scale separates animal feed from higher-margin human consumption segments. Feed applications absorb raw material unpredictability through formula adjustments, while cosmetic and supplement lines require batch consistency that constrains supplier pools.
- Animal Feed:Formulated protein and lipid inputs for aquaculture, livestock, and poultry diets. Norwegian salmon farmers and Vietnamese shrimp producers drive procurement, with EU Green Deal carbon accounting favoring enzymatically processed rest raw material over conventional reduction meal.
- Dietary Supplements:Encapsulated omega-3 oils and powders for human consumption. German and Italian pharmaceutical compounders demand IFOS-certified batches with contaminant testing documentation, narrowing supplier eligibility.
- Cosmetics:Algae-derived humectants and bioactive bases for skincare formulations.
- Pet Food:Premium canine and feline nutrition incorporating marine protein fractions.
Animal feed dominates volume throughput. Dietary supplements deliver the steepest margin expansion trajectory.
End User:
Customer technical sophistication determines service intensity and contract structure. Aquaculture operators negotiate formula-specific supply agreements while personal care manufacturers prioritize sensory and stability specifications.
- Aquaculture:Salmon, shrimp, and finfish farming operations requiring protein-dense feed inputs. Chilean and Norwegian producers integrate backward into enzymatic processing to secure captive supply from harvest waste streams.
- Nutraceutical:Supplement manufacturers and functional food compounders sourcing EPA/DHA for cognitive and cardiovascular positioning.
- Personal Care:Cosmetic formulators replacing petrochemical moisturizers with algae-derived polysaccharides.
- Food Processing:Ingredient suppliers fortifying packaged foods with marine-derived proteins and lipids.
Aquaculture commands the largest procurement volumes. Nutraceutical applications are climbing fastest on per-kilogram value metrics.
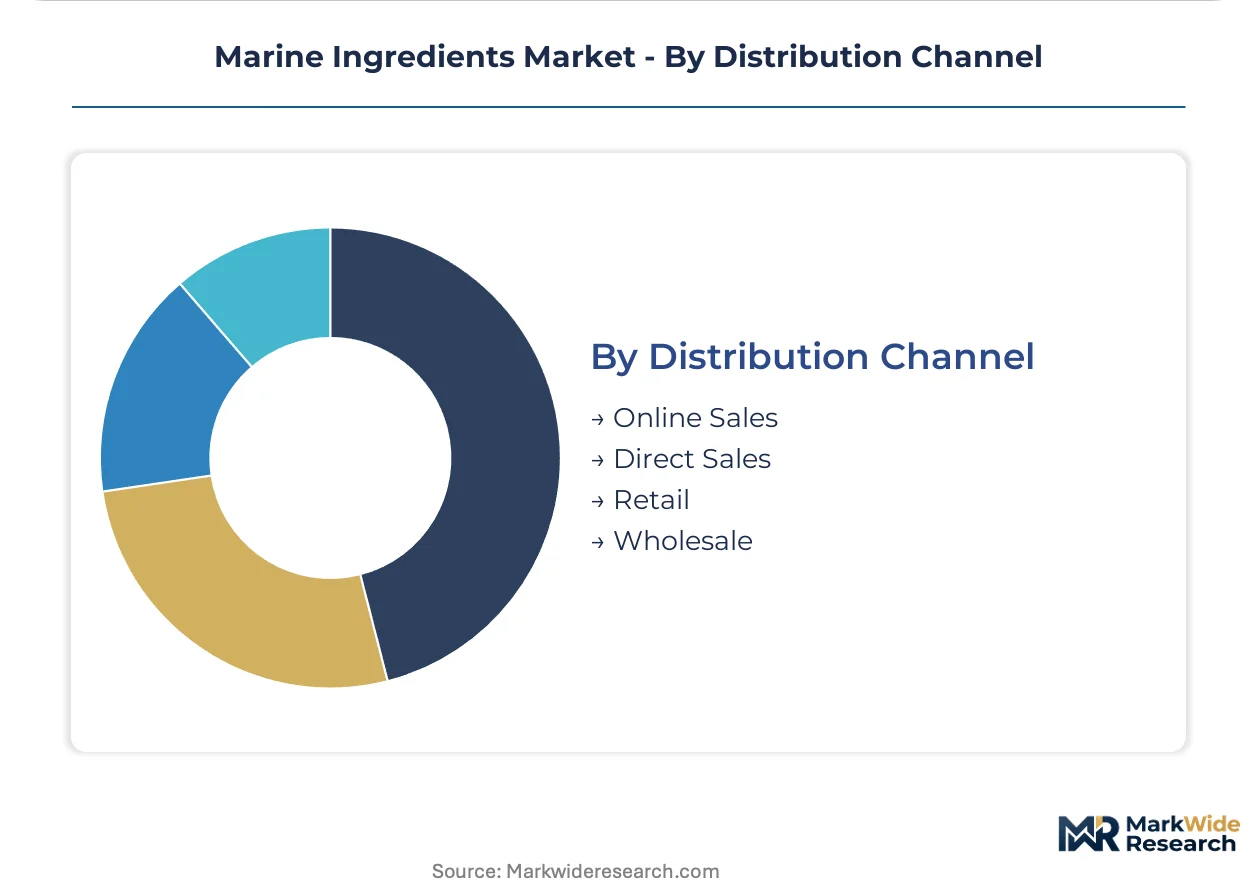
Distribution Channel:
Channel selection reflects buyer scale and technical requirements. Large compounders bypass intermediaries for price transparency, while smaller formulators depend on distributor technical support.
- Direct Sales:Long-term offtake contracts between producers and major aquaculture feed compounders. TripleNine Group and Hofseth BioCare lock in Norwegian and Danish salmon farming groups through multi-year supply agreements with indexed pricing.
- Online Sales:E-commerce platforms serving small-scale nutraceutical and pet food formulators.
- Retail:Branded consumer-facing marine ingredient products through pharmacy and specialty channels.
- Wholesale:Distributor networks aggregating spot market purchases for mid-tier processors.
Direct sales channels carry the largest contracted volumes. Online sales are gaining share fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting marine ingredient investment toward jurisdictions with streamlined sustainability certification pathways. The EU Green Deal's carbon accounting requirements impose compliance costs that Peru and Norway navigate differently, creating divergent production economics across extraction zones.
Peru
Anchovy reduction fisheries supply roughly one-third of global fish meal volume through IMARPE-regulated catch quotas. The national fishery regulator's annual total allowable catch decisions transmit immediate price volatility to aquaculture feed compounders in Norway and Chile. Callao and Chimbote harbor the densest concentration of reduction plants, where operators now invest in batch-level traceability systems to satisfy European ASC feed standards.
Norway
Salmon farming groups drive enzymatic processing adoption to convert rest raw material into certified marine ingredients. The country's implementation of EU F-Gas Regulation and national carbon disclosure rules accelerates demand for lower-thermal-extraction technologies. Bergen and Ålesund clusters host co-located hydrolysis units at major farming operations, capturing value from filleting waste previously shipped to reduction plants.
Chile
Aquaculture feed producers expand long-term offtake contracting to hedge against Peruvian quota instability. Subpesca fisheries administration enforces harvest traceability that aligns with EU import documentation requirements. Puerto Montt and Chiloé Island processing hubs integrate backward into enzymatic systems, mirroring the Norwegian distributed processing model for rest raw material valorization.
Germany
Pharmaceutical-grade omega-3 encapsulation demand concentrates in Hamburg and Frankfurt chemical processing corridors. EFSA novel food approval pathways and REACH registration requirements filter supplier eligibility to established fish oil refiners. German compounders now require IFOS-certified batches with full contaminant testing documentation, narrowing procurement pools to Antarctic krill and North Sea reduction sources.
India
Shrimp farming expansion in Andhra Pradesh and Gujarat generates import demand for fish meal beyond domestic supply capacity. FSSAI feed safety regulations and DGFT import licensing shape procurement logistics for aquaculture operators. Visakhapatnam and Surat ports handle rising volumes of Peruvian and Southeast Asian marine ingredient shipments, with local distributors aggregating spot purchases for mid-tier feed compounders.
Marine Ingredients Market Competitive Environment
North Sea and Antarctic producers anchor one tier; enzymatic processing specialists in Scandinavia hold differentiated positioning through waste-stream valorization. The market structures around three archetypes: quota-backed reduction operators, enzymatic hydrolysis technology licensors, and fermentation-based alternative suppliers. Competitive moves concentrate on multi-year offtake contracting with salmon farming groups and geographic expansion of distributed processing capacity.
Within the enzymatic processing tier, Hofseth BioCare ASA exemplifies waste-stream valorization through salmon rest raw material conversion. Aker BioMarine occupies a position tied to Antarctic Treaty System harvest security. TripleNine Group A/S anchors North Sea reduction operations with proximity advantages to European aquaculture demand. Cargill Incorporated represents diversified agribusiness integration spanning multiple ingredient categories.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Hofseth BioCare ASA |
| Aker BioMarine |
| Symrise AG |
| Omega Protein Corporation |
| Bio-marine Ingredients Ireland Ltd |
| TripleNine Group A/S |
| SA Copalis |
| Gelita AG |
| Others |
Value Chain & Pricing Dynamics
Captive supply of enzymatic processing capacity anchors both procurement security and pricing power for Norwegian salmon farming groups converting rest raw material into certified marine ingredients. This backward integration shields integrated operators from Peruvian quota volatility while compressing margins for speculative traders dependent on spot market anchovy meal.
Pricing Analysis
Distributor margins on Peruvian fish meal compress under ASC certification documentation demands, while direct-to-feed-compounder contracts command indexed pricing premiums tied to IMARPE quota announcements. Three-tier pricing structure across MSC-certified premium, standard North Sea reduction, and economy-grade Southeast Asian meal segments reflects traceability grade and carbon disclosure depth. Cost compression in economy tiers intensifies because algal DHA fermentation erodes infant formula market share. Vietnamese shrimp feed compounders exhibit highest price sensitivity, while German pharmaceutical encapsulators prioritize batch consistency over unit cost.
Supply Chain Analysis
MSC and ASC certification gating restricts supplier eligibility for European aquaculture feed procurement, filtering raw material flows through audited chain-of-custody systems. Geographic supply concentrates in Peru, Norway, and Chile, with enzymatic processing units drawing from salmon rest raw material in Scandinavian and Patagonian farming zones. Raw material dependencies rest on Antarctic krill harvest quotas, anchovy catch volumes, and fresh substrate logistics within 24-hour filleting windows. Single-source vulnerability runs through Peru's IMARPE quota regime governing one-third of global fish meal volume. Distribution feeds from reduction plants and co-located hydrolysis units through long-term offtake contracts and wholesale spot aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon accounting mandates and ASC feed standards accelerate demand for traceable, lower-thermal-extraction marine ingredients.
For Market Incumbents: Acquire enzymatic hydrolysis technology licensors to secure captive processing capacity for rest raw material valorization. Lock multi-year offtake contracts with Norwegian and Chilean salmon farming groups before Antarctic krill operators expand harvest block allocations. Algal DHA fermentation substitution in infant formula threatens fish oil margin pools; counter by deepening phospholipid-bound omega-3 positioning in nutraceutical applications. For New Entrants and Emerging Players: EU F-Gas Regulation and CSRD reporting requirements in Europe open a window for distributed enzymatic processing units with established lifecycle assessments. Target India aquaculture feed growth in Andhra Pradesh and Gujarat where shrimp farming expansion outpaces domestic fish meal supply. Penetrate through wholesale distributor partnerships aggregating spot purchases for mid-tier compounders lacking direct import licensing. For Investors and Strategic Acquirers: Roll-up economics work for enzymatic processing specialists because salmon farming waste streams remain underutilized in remote Norwegian and Chilean regions lacking cold-chain infrastructure. Five-to-ten-year viability hinges on Antarctic Treaty System harvest zone stability and enzymatic technology licensing fee trajectories. Monitor CCAMLR conservation measure negotiations as inflection indicator for krill-based supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks Norwegian salmon farmers against Peruvian IMARPE quota volatility through indexed pricing. |
| Backward Integration | Chilean aquaculture groups capture rest raw material value previously shipped to reduction plants. |
| Capacity Expansion | Distributed enzymatic units in Bergen and Puerto Montt clusters shorten fresh substrate logistics. |
| Green Certification Program | MSC chain-of-custody audits gate European ASC feed standard compliance for premium supply chains. |
| Joint Venture | Antarctic krill operators share spatial competition risks under CCAMLR conservation measure constraints. |
Study Parameters
Multiple input streams — executive interviews with aquaculture feed procurement directors, regulatory affairs leads at marine ingredient processors, and sustainability certification auditors — were reconciled against secondary validation from FAO capture fisheries databases, IMARPE quota announcements, and EU EFSA novel food approval records. Bottom-up capacity assessments at Peruvian reduction plants and Norwegian enzymatic processing units were triangulated with top-down demand modeling across salmon farming operations in Chile and shrimp producers in Vietnam.
Historical catch volume trajectories were cross-referenced against panel input from industry stakeholders to construct projection frameworks across the analysis window. Segmentation dimensions modeled include extraction technology type, application vertical, end-user technical sophistication, and distribution channel structure. CAGRs were derived through regression analysis of quota-constrained supply growth against aquaculture feed certification expansion. Industry-specific forecast inputs incorporated Antarctic Treaty System harvest zone negotiations and EU Green Deal carbon accounting implementation timelines.
Revisions become necessary when IMARPE quota announcements diverge from modeled anchovy biomass assessments or when algal DHA fermentation achieves cost parity in pharmaceutical-grade applications. Forecasts reflect assumptions regarding CCAMLR conservation measure continuity and enzymatic processing technology licensing fee stability. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or ASC feed standard traceability requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Protein Concentrate Market
Ingredients
Citrus Fiber Market
Ingredients
Edible Oils and Fats Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Colombia Food Ingredients Market
Ingredients
L-Arabinose Market
Ingredients
Food Colors Market
Ingredients
Rice Starch Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Immunity Support Ingredients Market
Ingredients
North America Milk Protein Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
India Olive Oil Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Chickpea Flour Market