
 Pea Flour Market | 2026-2036
Pea Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Flour Market Analytics
Subscription-based ingredient formulation services is hardening around pea flour portfolios as food manufacturers seek turnkey clean-label solutions. AGT Food and Ingredients leverages its vertical integration from prairie sourcing to milling to sustain price stability across North American supply chains. Roquette Frères anchors its competitive position through decades of pulse-processing expertise and European distribution density. Ingredion competes by extending its specialty ingredient platform into plant-based texturizers that incorporate pea flour as a core input.
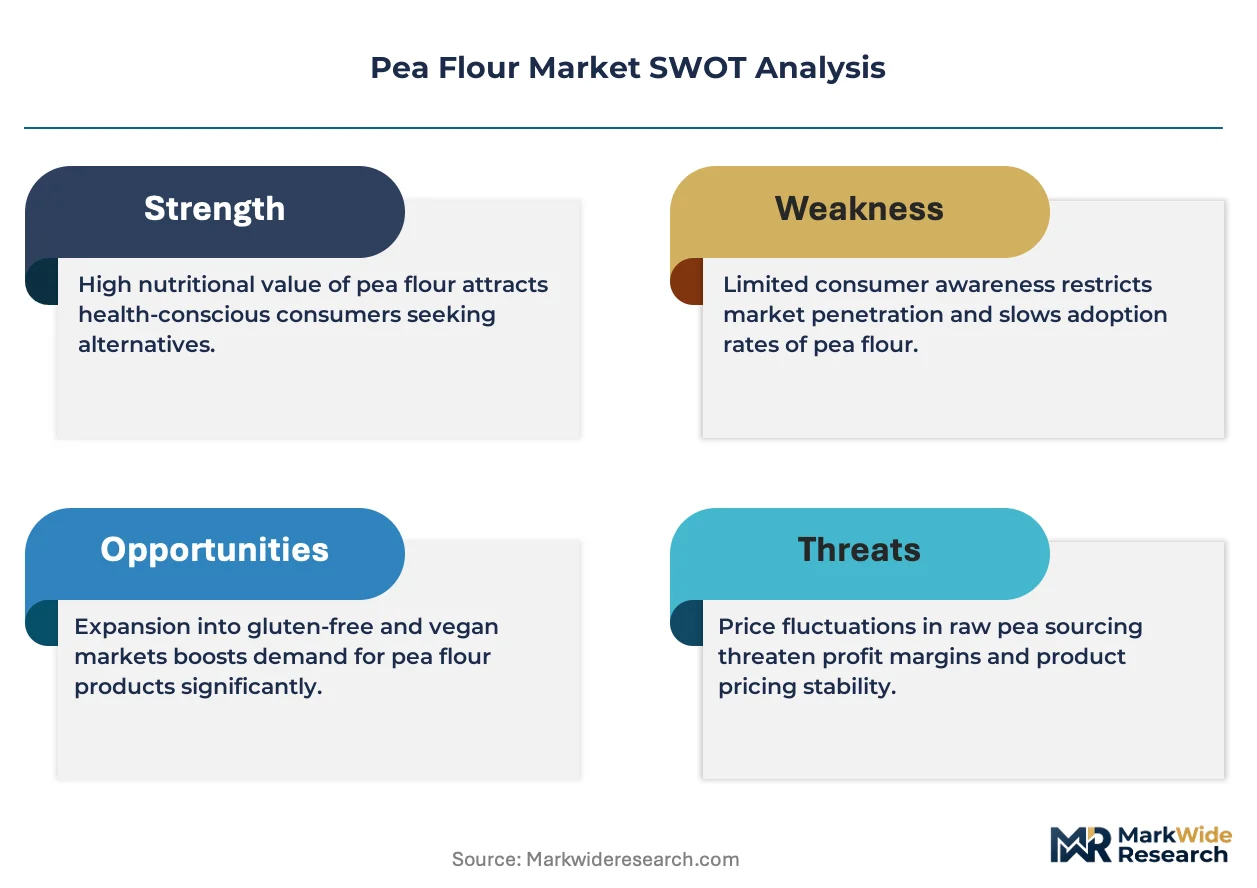
Pea flour consists of finely milled dried pea seeds, typically containing 20-25% protein and 40-50% starch by weight, produced through either air classification or conventional hammer milling followed by sifting. The material functions primarily as a protein fortifier, binding agent, and gluten-free structure builder in formulated foods. Organic pea flour commands premium positioning among health food stores and clean-label bakers, while yellow pea flour dominates volume flows into snack manufacturing due to its neutral flavor profile and superior emulsification properties. Conventional pea flour retains cost advantages in wholesale channels serving mainstream food manufacturers.
The FDA oversees allergen disclosure requirements for pea-derived ingredients under the Food Allergen Labeling and Consumer Protection Act, while USDA organic certification governs premium tier product claims. The EPA regulates agricultural runoff standards that affect pea cultivation practices in major growing regions, indirectly influencing raw material availability. Stakeholders must monitor evolving FDA guidance on pea as a major allergen alongside state-level clean-label legislation that could accelerate or constrain formulation shifts.
Market Dynamics
Plant-based bakery formulations are expanding adoption among food manufacturers as the FDA's updated guidance on allergen labeling for legume ingredients reshapes ingredient declarations across formulated food categories.
Growth Catalysts
- Clean-label mandates:State-level clean-label legislation in California and New York accelerates formulation shifts away from synthetic additives toward pea flour as a recognizable ingredient.
- Snack food integration:Pea protein and flour adoption into extruded snack foods has accelerated significantly in the United States as manufacturers seek protein fortification without allergen concerns.
- Air classification technology:Advanced milling processes enable precise protein-starch separation, improving functional performance in gluten-free structure building applications.
Market Restraints
- Pea cultivation concentration:Raw material availability concentrates in Canadian prairie provinces and North Dakota, exposing supply chains to regional weather volatility and EPA agricultural runoff enforcement.
- Legume allergen classification:Evolving FDA guidance on pea as a major allergen creates labeling uncertainty that slows mainstream food manufacturer adoption.
- Wheat flour substitution economics:Conventional wheat flour retains substantial cost advantages in price-sensitive wholesale channels serving mass-market baked goods.
Strategic Opportunities
- Organic certification premium tier:USDA organic certification governs clean-label bakers and health food stores willing to pay significant markups for certified organic pea flour.
- Yellow pea neutral flavor applications:Yellow pea flour's superior emulsification properties open formulation opportunities in plant-based dairy alternatives and beverage systems.
- Turnkey formulation services:Subscription-based ingredient formulation services harden around pea flour portfolios as manufacturers seek complete clean-label solutions without internal R&D investment.
Industry Challenges
- Cross-contamination protocols:Food manufacturers must implement stringent allergen control systems when integrating pea flour into facilities processing wheat, soy, or tree nuts.
- Functional consistency:Batch-to-batch variability in protein content and starch gelatinization properties requires continuous quality adjustment during scale-up production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Flour Market |
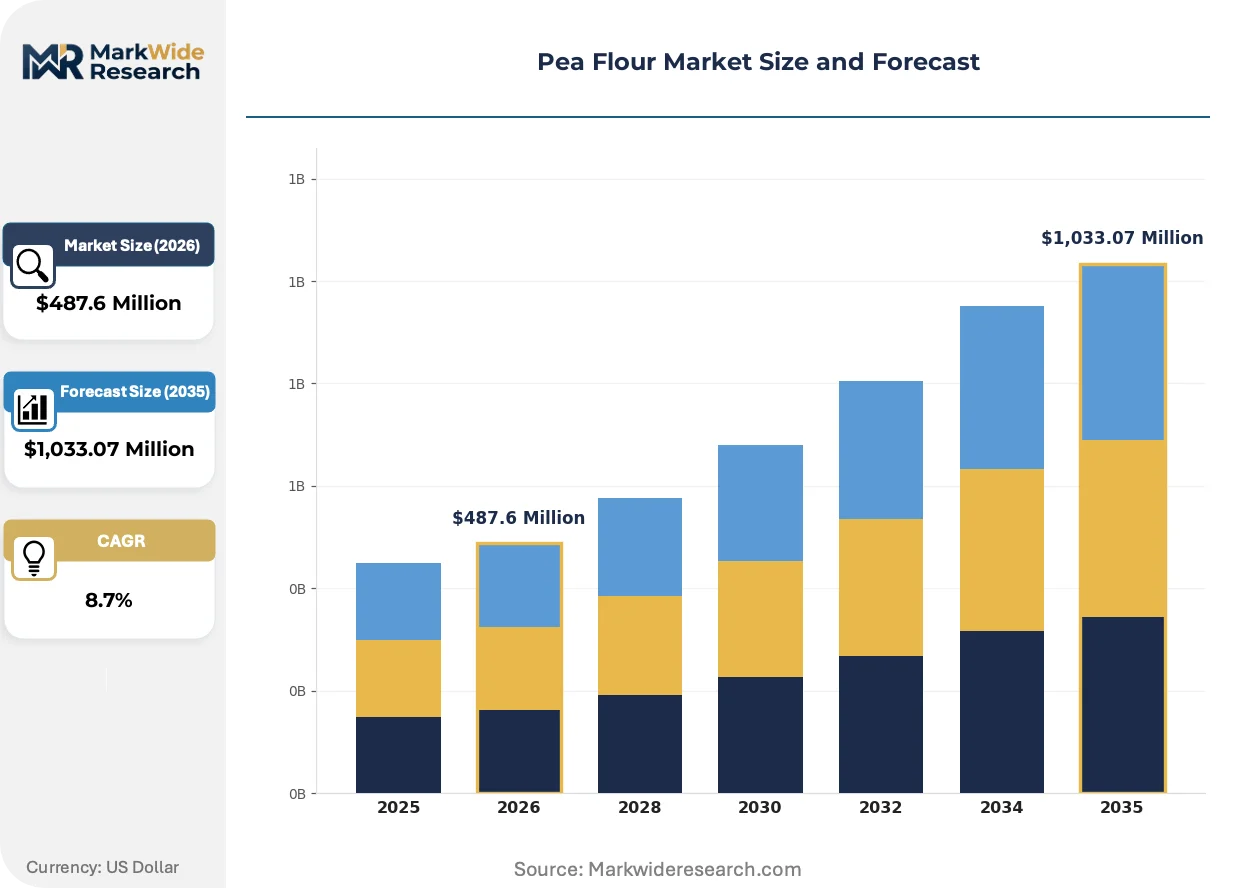
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pea Flour, Conventional Pea Flour, Yellow Pea Flour, Green Pea Flour Application: Baking, Snacks, Smoothies, Chilled Foods Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Wholesale End User: Food Manufacturers, Bakers, Health Enthusiasts, Restaurants |
| Companies Covered | Ingredion, AGT Food and Ingredients, Archer Daniels Midland Company, Roquette Frères, Bob's Red Mill Natural Foods, Golden Grain Mills, Grain Millers, Inc., Barry Farm Foods, Avena Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Flour Market Evolving Landscape
Precision milling technologies and evolving regulatory frameworks are compressing formulation cycles while expanding addressable applications for pulse-derived ingredients across packaged food categories.
Air classification milling is rewriting the technical specifications available to food formulators. This technology separates pea flour into protein-rich and starch-rich fractions with precision previously unattainable through conventional hammer milling. Clean-label snack manufacturers in the United States are adopting these fractionated ingredients at accelerating rates. The structural consequence is compressing the performance gap between plant-based and conventional gluten-containing formulations in extruded products.
REACH registration requirements for novel food ingredients in the European Union are tightening disclosure standards for imported pulse-derived materials. The industrial consequence is forcing non-European suppliers to invest in comprehensive toxicological dossiers and supply chain traceability systems. Organic and conventional pea flour exporters to Germany, France, and the Netherlands are responding by consolidating sourcing relationships with certified European importers who maintain pre-registered substance portfolios.
Ingredient-as-a-service procurement models are displacing traditional spot-market purchasing among mid-sized food manufacturers. These arrangements bundle technical support, formulation consulting, and guaranteed supply allocation into multi-year contracts. The shift is most visible in United States regional bakery cooperatives and emerging plant-based meat startups seeking to outsource supply risk and regulatory compliance expertise.
Pea Flour Market Segmentation
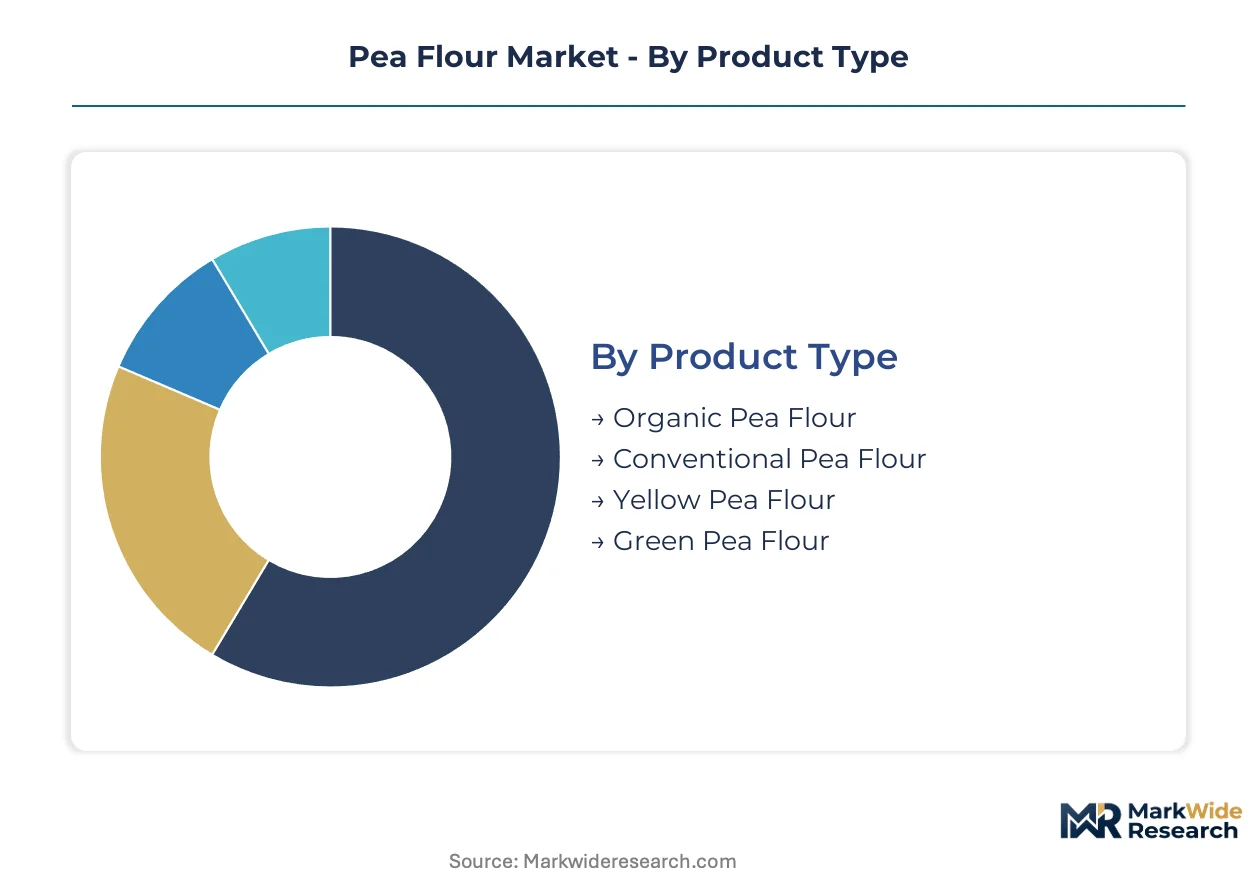
Pea flour segmentation reveals how capital requirements, certification tiers, and channel economics partition the market into distinct competitive arenas. Manufacturers configure production assets and sourcing strategies around these boundaries to capture margin premiums or volume scale.
Product Type:
Capital intensity varies sharply across milling configurations, with organic certification and fractionation technology demanding the heaviest upfront investment.
- Yellow Pea Flour:Neutral flavor profile and superior emulsification properties make this the default choice for extruded snack manufacturing in the United States. Demand concentrates among clean-label snack producers seeking protein fortification without sensory trade-offs.
- Organic Pea Flour:USDA certification mandates dedicated handling infrastructure, segregated supply chains, and multi-year field conversion timelines. Health food stores and premium clean-label bakers in California absorb the bulk of available supply despite significant markups over conventional grades.
- Conventional Pea Flour:Standard hammer milling keeps capital barriers low, enabling price-competitive positioning in wholesale channels serving mainstream food manufacturers.
- Green Pea Flour:Distinctive color and stronger flavor profile limit application scope to specialty baked goods and artisanal pasta where visual differentiation commands premium positioning.
Yellow pea flour absorbs the bulk of installed capacity; organic certification is expanding most quickly as state-level clean-label legislation accelerates.
Application:
Volume concentration and margin structure diverge across use cases, with formulation complexity and regulatory exposure driving segment selection.
- Snacks:Extruded and puffed formats have become the dominant vector for pea protein and flour integration in the United States. Manufacturers leverage air-classified fractions to achieve structural integrity previously unattainable with conventional pulse ingredients.
- Baking:Gluten-free structure building and protein fortification in artisanal and industrial bakeries. The segment demands consistent protein content and starch gelatinization properties that batch variability continues to complicate.
- Smoothies:Beverage applications exploit yellow pea's neutral flavor and dispersibility in plant-based dairy alternatives. Functional beverage startups represent the most dynamic customer cohort.
- Chilled Foods:Ready-to-eat meal components and refrigerated pasta where binding and moisture retention properties substitute for modified starches.
Snacks command the largest production footprint; smoothies are climbing the fastest as beverage manufacturers reformulate around clean-label mandates.
Distribution Channel:
Channel selection determines working capital requirements, with direct-to-retail and subscription models demanding fundamentally different balance sheet structures than commodity wholesale.
- Wholesale:Bulk shipments to food manufacturers and industrial bakeries dominate volume flows. Price transparency and contract terms favor suppliers with backward integration into prairie sourcing.
- Health Food Stores:Specialty retail commands organic and small-batch premiums. Shelf placement depends on third-party certifications and regional clean-label credibility.
- Supermarkets:Mainstream retail penetration remains limited by allergen labeling uncertainty and consumer familiarity gaps relative to established gluten-free alternatives.
- Online Retailers:Direct-to-consumer and ingredient-as-a-service platforms are displacing traditional spot purchasing among mid-sized manufacturers and artisanal bakers.
Wholesale channels absorb the bulk of throughput; online retail is gaining share fastest as procurement patterns shift toward bundled technical support and guaranteed allocation.
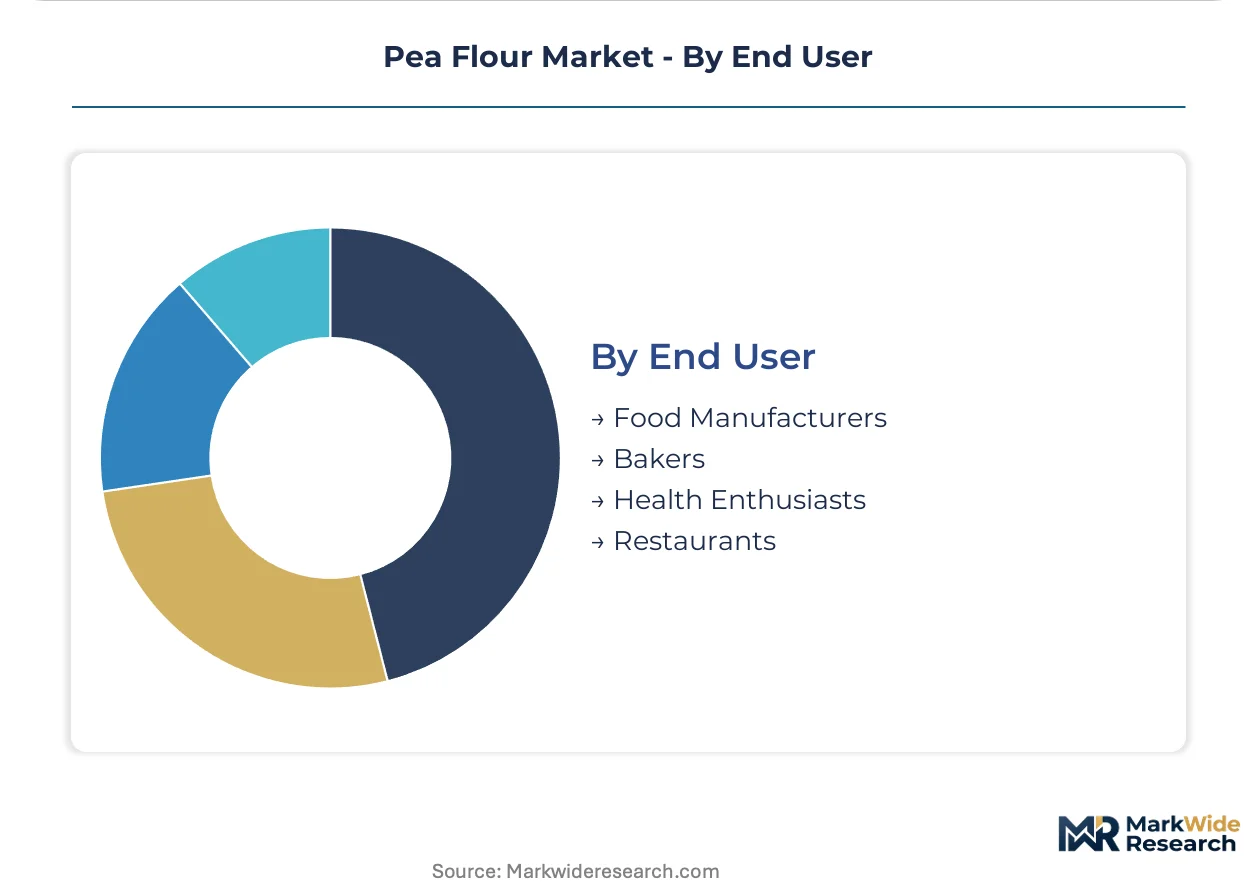
End User:
Customer scale and technical sophistication create distinct service requirements, from formulation consulting for startups to consistent spec delivery for industrial buyers.
- Food Manufacturers:Industrial scale buyers demand batch consistency, regulatory documentation, and multi-year supply security. Cross-contamination protocols represent a significant operational burden when integrating pea flour into facilities processing wheat or tree nuts.
- Bakers:Artisanal and regional bakery cooperatives seek turnkey clean-label solutions without internal R&D investment. Subscription-based formulation services are hardening around this cohort.
- Health Enthusiasts:Direct purchasers through specialty retail and online channels drive organic premium tier demand. Price sensitivity is low relative to certification credibility.
- Restaurants:Foodservice applications remain nascent, concentrated in plant-forward independent operators and institutional catering where allergen management systems are already mature.
Food manufacturers absorb the bulk of supply; bakers represent the steepest expansion trajectory as ingredient-as-a-service models reduce barriers to adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea flour production clusters in the Canadian prairies and North Dakota while consumption concentrates in coastal United States markets and Western European food manufacturing hubs. This geographic mismatch creates distinct supply chain configurations across major demand centers.
United States
Clean-label snack manufacturing drives demand concentration in California and New York state food corridors. FDA allergen labeling guidance under FALCPA creates compliance complexity for manufacturers integrating pea-derived ingredients. Chicago and Minneapolis-St. Paul anchor Midwest processing and distribution infrastructure serving extruded food producers.
Canada
Prairie provinces Saskatchewan and Manitoba supply the bulk of North American yellow pea raw material. Canadian Grain Commission standards govern quality specifications for export-oriented milling operations. AGT Food and Ingredients maintains backward integration from prairie sourcing through milling in Regina and Portage la Prairie facilities.
Germany
REACH registration requirements for novel food ingredients tighten disclosure standards for imported pulse materials. EFSA evaluations govern health claim substantiation for protein fortification applications. Hamburg and Bremen port clusters handle bulk import flows for Central European snack and bakery manufacturers.
France
Roquette Frères anchors European pulse-processing expertise through decades of specialty ingredient development. ANSM monitors food additive classifications affecting pea protein isolate regulatory status. Lille and Paris basin manufacturing corridors concentrate plant-based dairy alternative formulation activity.
Netherlands
Rotterdam port infrastructure enables transshipment of North American and Baltic pea flour into Continental markets. Dutch food ingredient traders maintain pre-registered substance portfolios easing REACH compliance for downstream manufacturers. Wageningen food research cluster drives application development in plant-based meat analogs.
Pea Flour Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pea flour value chain. Prairie-integrated millers with captive raw material sourcing face specialty ingredient formulators who outsource primary processing. Three archetypes dominate: vertically integrated agricultural processors, diversified global ingredient platforms, and artisanal organic specialists. Capacity expansion in air classification technology and strategic partnerships with snack food manufacturers represent the dominant competitive vectors.
Among North American agricultural processors, AGT Food and Ingredients exemplifies prairie-integrated supply chain control. Ingredion and Archer Daniels Midland occupy positions within diversified ingredient platforms extending into plant-based texturizers. Roquette Frères anchors European pulse-processing density through decades of fractionation expertise. These three represent distinct strategic postures: upstream raw material capture, downstream formulation integration, and regional processing specialization.
| Leading Market Players |
|---|
| Ingredion |
| AGT Food and Ingredients |
| Archer Daniels Midland Company |
| Roquette Frères |
| Bob's Red Mill Natural Foods |
| Golden Grain Mills |
| Grain Millers, Inc. |
| Barry Farm Foods |
| Avena Foods |
| Others |
Value Network & Pricing Analysis
Canadian prairie yellow pea prices transmit directly through three downstream pricing tiers, with organic certification premiums absorbing multi-year field conversion costs and air-classification technology investments separating protein-rich fractions from commodity grades.
Pricing Analysis
Margin tightening in conventional grades reflects wheat flour substitution economics and EPA agricultural runoff enforcement pressures on prairie cultivation. Three-tier pricing structure across organic, air-classified, and conventional hammer-milled grades tracks certification burden and functional performance. Price differentiation centers on USDA organic credibility and protein content consistency. Mass-market baked goods manufacturers exhibit highest price sensitivity; health food stores and clean-label bakers show lowest sensitivity.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle industrial-scale volume, with subscription-based ingredient-as-a-service platforms gaining share among mid-sized buyers. Raw material sourcing concentrates in Saskatchewan, Manitoba, and North Dakota prairie provinces. Milling operations draw from prairie pea cultivation, air classification equipment, and organic certification infrastructure. Single-source vulnerability to regional weather volatility and Canadian Grain Commission quality standards enforcement represents structural supply risk. Distribution runs through Minneapolis-St. Paul and Chicago processing hubs serving United States snack manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in pea flour is hardening around backward integration into prairie sourcing and downstream formulation services, with captive raw material control and turnkey clean-label solutions emerging as the decisive leverage points.
For Market Incumbents: Acquire air classification milling assets and organic-certified prairie acreage to lock in protein fraction supply and certification tier access. Defend against emerging ingredient-as-a-service competitors by embedding formulation consulting into multi-year supply contracts. Capacity expansion in Regina and Portage la Prairie preserves proximity to Canadian Grain Commission export infrastructure. For New Entrants and Emerging Players: Begin with beverage applications and plant-based dairy alternatives where yellow pea's neutral flavor and dispersibility advantages remain underexploited. Target functional beverage startups in California and New York corridors seeking clean-label protein fortification without internal R&D investment. Lead with subscription-based technical support bundled with guaranteed supply allocation. For Investors and Strategic Acquirers: FDA guidance elevation of pea to major allergen status is the leading indicator that labeling clarity will either accelerate mainstream adoption or freeze formulation shifts pending compliance certainty. Prairie-integrated millers with pre-registered European REACH dossiers represent the most defensible acquisition profile across the projection horizon. Monitor EPA agricultural runoff enforcement intensity as a signal of raw material cost pressure direction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Sourcing | Captive yellow pea supply from Saskatchewan and Manitoba insulates against Canadian Grain Commission quality volatility. |
| Air Classification Capacity Expansion | Precision protein-starch separation technology closes performance gaps with gluten-containing formulations in extruded snacks. |
| Organic Certification Investment | USDA-certified handling infrastructure unlocks California and New York clean-label legislation-driven premium tiers. |
| Ingredient-as-a-Service Platform Launch | Subscription-based formulation consulting captures mid-sized bakery cooperatives seeking outsourced R&D and regulatory compliance. |
| REACH Registration Completion | Pre-registered toxicological dossiers enable uninterrupted export flows into Hamburg and Rotterdam port clusters. |
Research Methodology
Document review covered FDA allergen labeling guidance, EPA agricultural runoff standards, Canadian Grain Commission quality specifications, and REACH registration requirements, complemented by interviews with prairie grain elevator operators, air classification mill engineers, clean-label snack formulators, organic certification auditors, and wholesale food ingredient procurement managers. Secondary sources included USDA organic certification databases, FALCPA regulatory filings, customs trade data on pulse ingredient flows, and SEC disclosures from diversified ingredient platforms. Bottom-up volume modeling from application segments and top-down cross-checks against prairie production capacity established analytical anchors.
Historical volume trajectories were cross-referenced against panel input from milling equipment suppliers and snack food manufacturers to calibrate adoption curves across the projection horizon. Segmentation modeling tracked product type, application, distribution channel, and end user dimensions alongside protein content tier and certification grade. CAGRs were derived from regression analysis of prairie planting intentions, air classification capacity expansion schedules, and clean-label legislation implementation timelines.
Underlying measurement precision varies by segment; organic certification tiers and air-classified fractions carry tighter precision than conventional hammer-milled grades due to dedicated handling infrastructure and protein content standardization. Forecasts reflect assumptions regarding FDA allergen classification resolution, EPA enforcement intensity, and state-level clean-label legislation adoption that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Dark Yeast Extract Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
China Cane Sugar Market
Ingredients
Grape Skin Extract Market
Ingredients
Specialty Feed Additives Market
Ingredients
Wheat Malt Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Almond Flour Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market