
 South America Agar Market | 2026-2036
South America Agar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agar Market Analytics
Pharmaceutical microbiology is realigning South American agar procurement patterns as regional vaccine and biosimilar production expands. Hispanagar S.A. anchors European supply lines into Mercosur through its specialized bacteriological grade portfolio. Merck KGaA leverages its distribution density in Brazilian research clusters to sustain premium positioning. Thermo Fisher Scientific competes on bulk contract terms with multinational hospital networks.
Agar denotes a gelatinous polysaccharide extracted primarily from red algae of the Rhodophyta class, with gelation temperatures typically between 32°C and 45°C and melting points spanning 80°C to 90°C, functioning as an inert gelling matrix for microbial culture media, food stabilization, and molecular separation protocols. Powder format dominates microbiology procurement due to dissolution efficiency and shelf stability, while flake and sheet variants retain stronger traction in traditional food processing segments across Peru and Colombia. Pharmaceutical-grade agar commands the most stringent certification overhead, concentrating margin pools with suppliers possessing in-house extraction and refining capabilities.
ANVISA governs pharmaceutical and food-grade agar purity thresholds in Brazil, while Argentina's national food safety authority enforces additive labeling and origin traceability rules that shape import documentation burdens. Chile's Ministry of Health aligns with Mercosur technical regulations for cross-border harmonization, though divergence in heavy metal limits still fragments compliance costs. Stakeholders must monitor pending updates to Mercosur GMC resolutions on hydrocolloid specifications, as these will determine whether regional blending facilities gain cost advantages over direct importers.
Market Dynamics
Pharmaceutical microbiology is realigning South American agar procurement patterns as regional vaccine and biosimilar production expands. ANVISA's updated food additive purity standards are tightening import specifications and reshaping supplier qualification timelines across Brazil's Southeast industrial corridor.
Growth Catalysts
- Brazilian vaccine manufacturing scale-up:Pharmaceutical laboratories in São Paulo and Minas Gerais states are expanding culture media preparation capacity for domestic vaccine and biosimilar production, pulling bacteriological-grade agar volumes upward.
- Mercosur GMC resolution harmonization:Pending updates to regional hydrocolloid technical regulations are creating pathways for blending facilities to gain cost advantages over direct importers, concentrating investment in Argentina and Uruguay processing hubs.
- Cell culture media sophistication:Advanced therapeutic development in Brazilian research clusters is driving specification upgrades toward low-endotoxin, high-clarity agar variants for stem cell and tissue engineering applications.
Market Restraints
- Red algae supply concentration:Raw material dependency on Chilean and Peruvian coastal harvesting operations creates input volatility when El Niño events disrupt Gelidium and Gracilaria seasonal yields.
- ANVISA import documentation burdens:Tightened food-grade purity thresholds and origin traceability requirements are extending customs clearance timelines for European and Asian suppliers without in-house Brazilian certification.
- Carrageenan substitution in food stabilization:Cost-sensitive processed food manufacturers in Colombia and Ecuador are pivoting toward carrageenan gelling systems for dairy and confectionery applications where gel strength requirements permit.
Strategic Opportunities
- Uruguay blending facility development:Mercosur tariff advantages and Montevideo port infrastructure position Uruguay as a regional agar reformulation and distribution hub serving Argentine and Paraguayan food processors.
- Plant-based meat analog formulation:Texture engineering demands from Brazilian alt-protein startups are opening specialty agar-agar applications for fat mimicry and bite structure in extruded protein matrices.
- ANVISA pharmaceutical-grade fast-track certification:Streamlined approval pathways for suppliers with ISO 13485 quality management systems are enabling premium positioning for culture media producers targeting Brazilian cell therapy contract manufacturers.
Industry Challenges
- Phycocolloid extraction technician scarcity:Specialized knowledge of red algae harvesting, alkali pretreatment, and freeze-thaw purification cycles is concentrated among aging workforces in southern Chile, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous compliance with ANVISA pharmaceutical standards, Argentina's national food safety authority labeling rules, and Chile's Ministry of Health heavy metal limits fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agar Market |
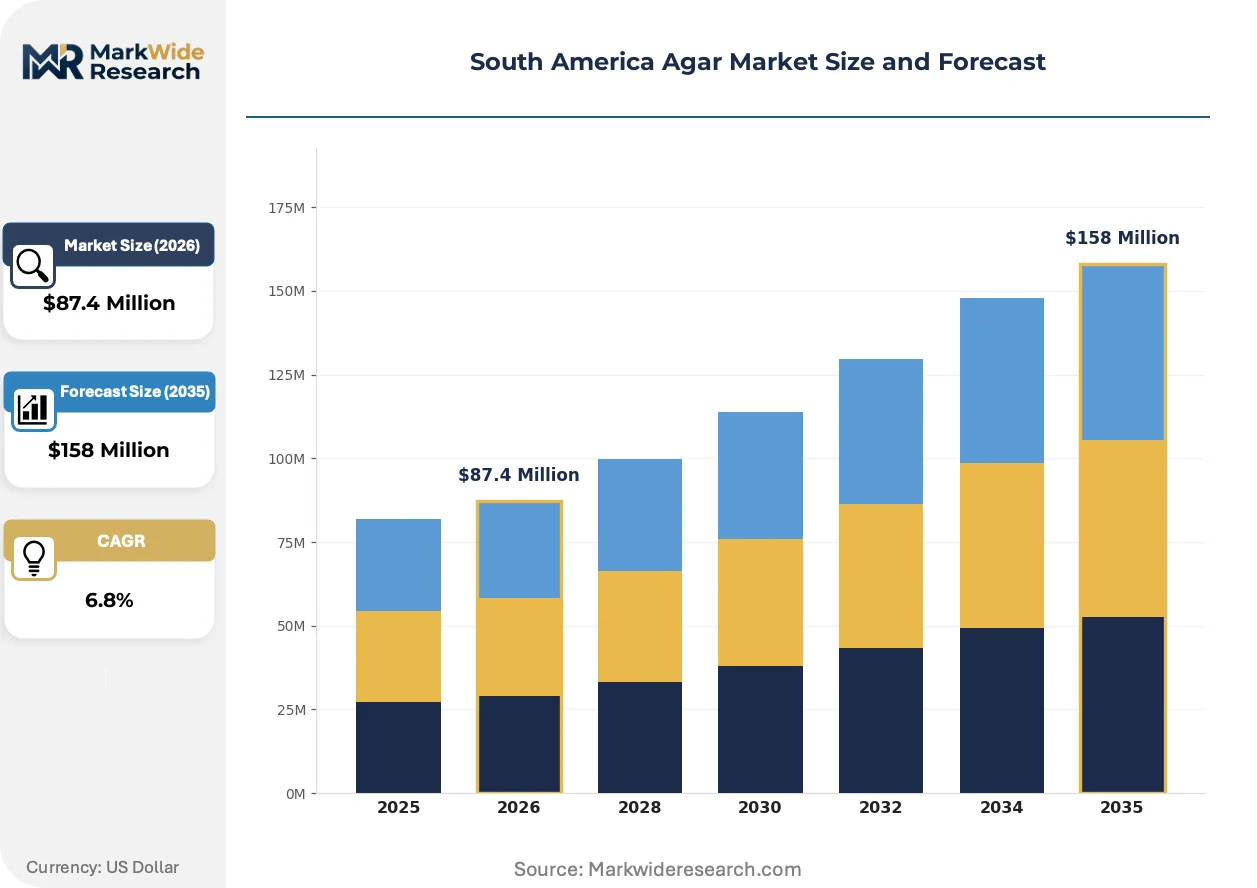
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Sheet, Gel Application: Food, Pharmaceuticals, Microbiology, Cosmetics End User: Food Industry, Research Institutions, Hospitals, Cosmetic Manufacturers Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Hispanagar S.A., PT Agarindo Bogatama, Merck KGaA, Thermo Fisher Scientific, FUJIFILM Wako Pure Chemical Corporation, B&V S.r.l., Marine Hydrocolloids, Agarmex, Neogen Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agar Market Evolving Landscape
Extraction technology refinement and regulatory convergence are compressing traditional supply hierarchies while opening new application vectors across pharmaceutical and food-grade segments.
Enzymatic extraction protocols are decentralizing agar production economics by enabling smaller-scale processors to achieve gel strength parity with industrial alkali methods. Mid-sized Peruvian and Chilean operators are adopting cellulase-assisted cell wall degradation to reduce extraction temperatures and processing time. This technology is decentralizing margin capture away from concentrated European refiners toward coastal Latin American harvester-processors.
ANVISA's 2023 pharmaceutical-grade agar purity protocol revision is mandating endotoxin thresholds below 10 EU/g for injectable culture media applications. Brazilian contract manufacturers are disqualifying suppliers lacking in-house LAL testing capability, compressing the approved vendor list for parenteral-grade material. São Paulo state research hospitals and biosimilar producers are absorbing qualification costs to secure supply continuity.
Consolidated procurement through multinational hospital networks is displacing fragmented laboratory purchasing in Brazil's Southeast corridor. Hospital federations in São Paulo and Rio de Janeiro are negotiating multi-year agar supply contracts with integrated distributors, extracting volume discounts and technical service bundling. This concentration is most visible in tertiary care institutions with centralized microbiology and pathology departments.
South America Agar Market Segmentation
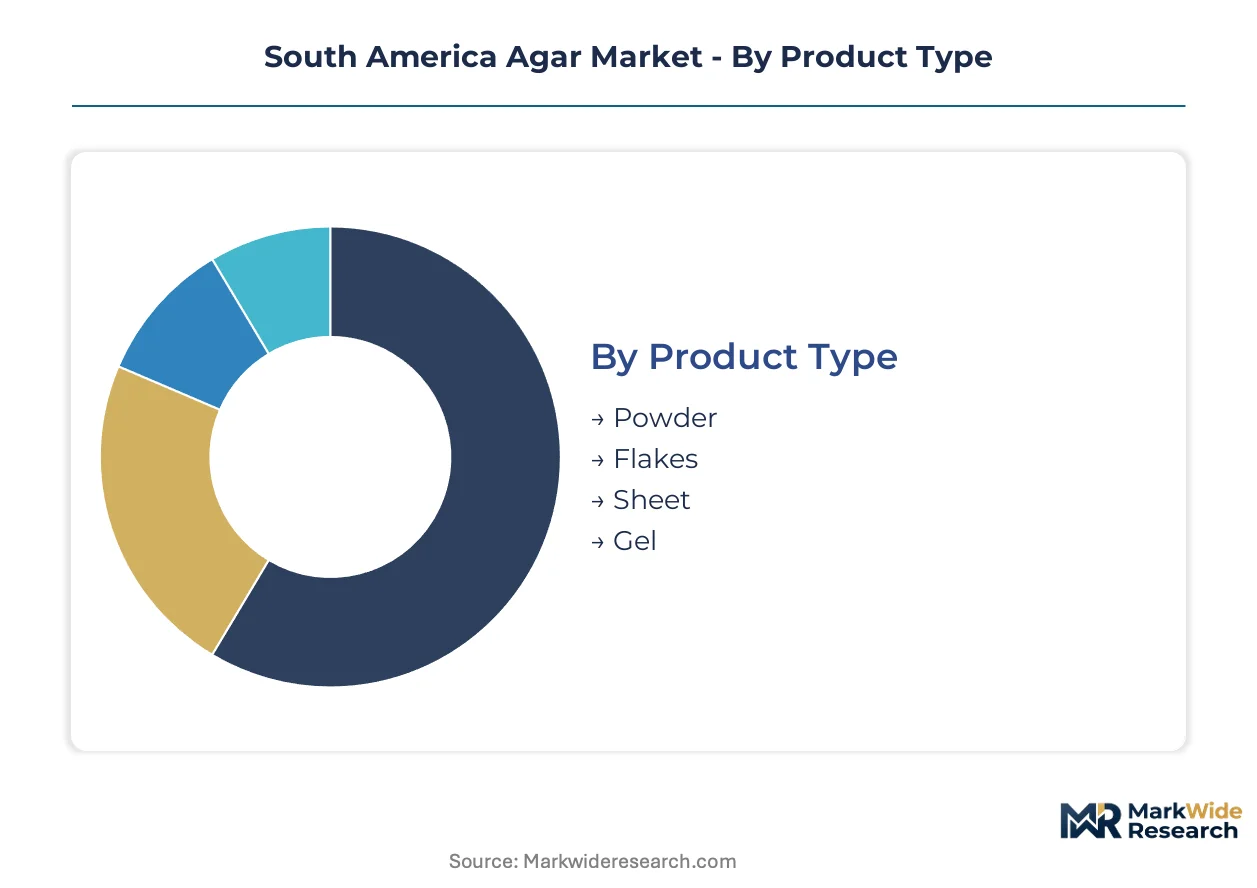
Agar procurement patterns across South America diverge sharply between high-volume food stabilization contracts and premium pharmaceutical-grade specifications. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economies dominate competitive positioning.
Product Type:
Powder formats command microbiology procurement volumes while flake and sheet variants retain food-processing loyalty in traditional manufacturing clusters.
- Powder:Fine granulation enables rapid dissolution in autoclave preparation protocols, with dissolution efficiency driving adoption across São Paulo state pharmaceutical laboratories and Brazilian biosimilar production facilities where batch consistency is non-negotiable.
- Flakes:Traditional red algae extraction yields irregular fragments preferred in Peruvian and Colombian food processing for texture control in dairy gels and confectionery applications where visual particulate identity carries brand value.
- Sheet:Compressed layers serve niche gastronomy and artisanal food segments across Argentina and Chile, with premium positioning in chef-driven applications limiting volume scale.
- Gel:Pre-hydrated formats reduce preparation labor in hospital network central kitchens and ready-meal manufacturing, finding traction in Brazilian Southeast industrial corridor convenience food operations.
Today's leader: Powder. Tomorrow's challenger: Gel.
Application:
End-use requirements stratify agar purity thresholds from food-grade stabilization to endotoxin-controlled cell culture matrices.
- Microbiology:Bacteriological-grade agar with defined gel strength and clarity specifications anchors culture media preparation for Brazilian vaccine manufacturing scale-up in São Paulo and Minas Gerais research clusters, with ANVISA pharmaceutical-grade certification requirements compressing qualified supplier lists.
- Food:Stabilization applications in processed dairy, confectionery, and meat products consume volume across Brazil's Southeast corridor and Argentine Pampas food manufacturing belts, though carrageenan substitution pressure intensifies in cost-sensitive Colombian and Ecuadorian operations.
- Pharmaceuticals:Low-endotoxin, high-clarity variants for stem cell and tissue engineering applications command premium positioning in Brazilian cell therapy contract manufacturing, with ISO 13485 quality management certification enabling fast-track ANVISA approval pathways.
- Cosmetics:Texture modification in skincare and haircare formulations drives modest volumes through Brazilian and Argentine cosmetic manufacturers, with natural positioning claims supporting niche premium pricing.
Microbiology captures current margin concentration. Food holds volume dominance. Pharmaceuticals are climbing the fastest.
End User:
Procurement concentration patterns split between consolidated hospital network contracts and fragmented research institution purchasing.
- Food Industry:Brazilian Southeast industrial corridor processors and Argentine food manufacturing clusters drive bulk contract volumes, with Mercosur tariff advantages shaping sourcing decisions toward Uruguay blending facilities.
- Research Institutions:São Paulo state universities and Brazilian federal research centers maintain specialized culture media preparation capacity, though consolidated procurement through hospital federations is displacing fragmented laboratory purchasing in tertiary care settings.
- Hospitals:Multinational hospital networks in Rio de Janeiro and São Paulo negotiate multi-year supply contracts with integrated distributors, extracting technical service bundling and volume discounts most visible in centralized microbiology departments.
- Cosmetic Manufacturers:Brazilian personal care formulators and Argentine skincare producers source modest agar volumes for natural positioning claims, with specification requirements less stringent than pharmaceutical tiers.
Food Industry anchors volume. Research Institutions defend specification intensity. Hospital consolidation is reshaping procurement leverage.
Distribution Channel:
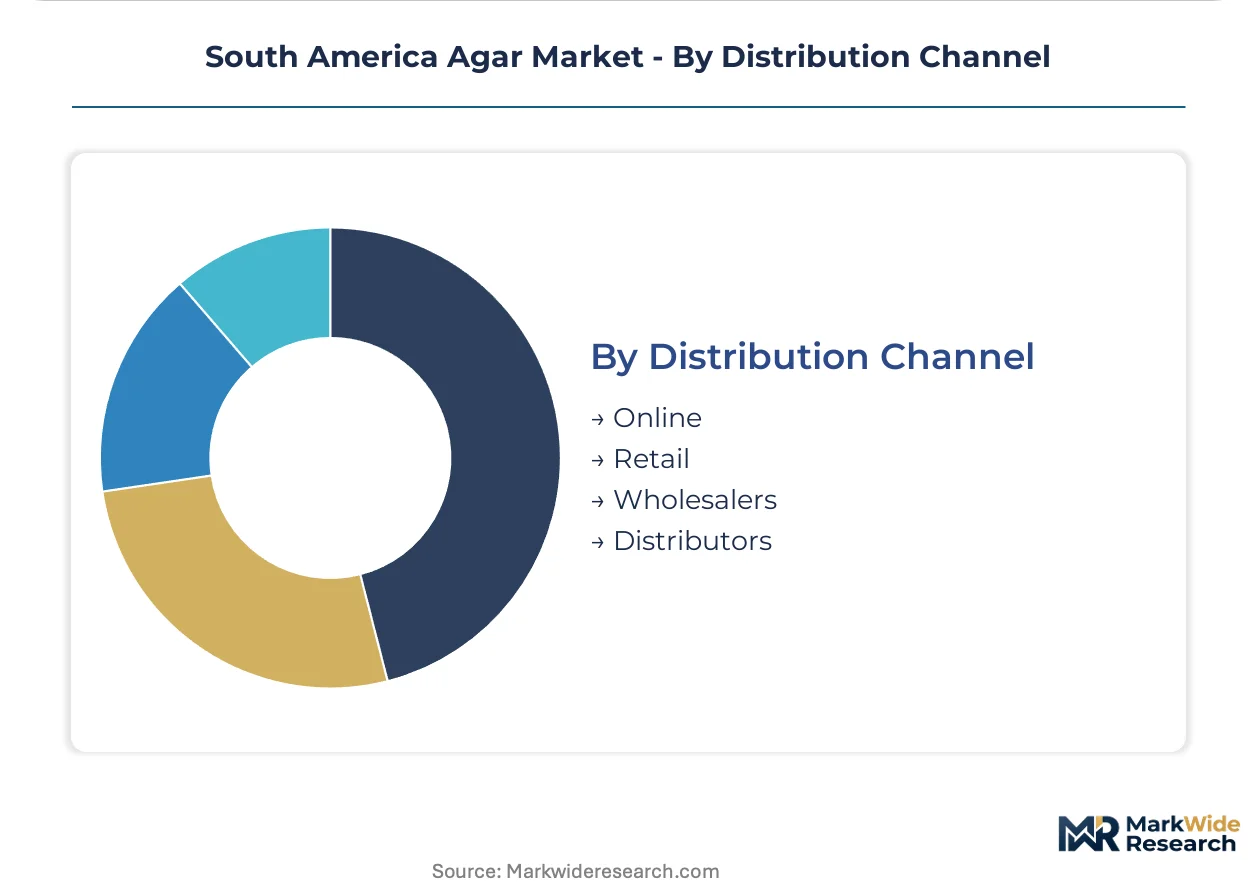
Channel selection tracks customer scale and technical service requirements from bulk wholesaler volumes to certified distributor relationships.
- Distributors:Integrated technical service providers with in-house ANVISA certification capability dominate pharmaceutical-grade supply to Brazilian vaccine manufacturers and cell therapy contract producers, bundling quality documentation and logistics.
- Wholesalers:Bulk volume handlers serve food industry procurement across Brazil's Southeast corridor and Argentine processing hubs, with Mercosur cross-border harmonization enabling regional consolidation.
- Online:E-procurement platforms gain traction in research institution and small-scale cosmetic manufacturer segments, though pharmaceutical-grade material remains distributor-dependent due to certification verification requirements.
- Retail:Direct-to-consumer and small commercial formats serve artisanal food producers and educational laboratory segments, with limited scale in professional procurement.
Distributors command premium positioning. Wholesalers capture food volume. Online channels are expanding most quickly in research segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting agar processing investment toward Uruguay as Brazilian import documentation burdens widen the cost-of-compliance gap with Mercosur neighbors. Blending facilities in Montevideo exploit tariff advantages to serve Argentine and Paraguayan food processors while avoiding ANVISA's tightened purity verification timelines.
Brazil
Vaccine manufacturing scale-up in São Paulo and Minas Gerais states is pulling bacteriological-grade agar volumes upward for culture media preparation. ANVISA's 2023 pharmaceutical-grade purity protocol revision mandates endotoxin thresholds below 10 EU/g for injectable applications. São Paulo state research hospitals are absorbing qualification costs to secure supply continuity from certified distributors.
Argentina
Food stabilization contracts across the Pampas manufacturing belt drive bulk procurement volumes for processed dairy and confectionery applications. The national food safety authority enforces additive labeling and origin traceability rules that shape import documentation burdens for European suppliers. Buenos Aires province processors are consolidating procurement through regional blending facilities to exploit Mercosur tariff advantages.
Chile
Red algae harvesting operations along coastal zones supply raw material for regional extraction, though El Niño events disrupt Gelidium and Gracilaria seasonal yields. The Ministry of Health aligns with Mercosur technical regulations for cross-border harmonization while maintaining divergent heavy metal limits. Southern Chile's aging phycocolloid extraction technician workforce constrains capacity expansion despite enzymatic extraction technology adoption.
Uruguay
Montevideo port infrastructure positions the country as a regional agar reformulation and distribution hub serving Mercosur food processors. Pending updates to Mercosur GMC resolutions on hydrocolloid specifications are creating pathways for blending facilities to gain cost advantages over direct importers. Free zone operators are consolidating regional procurement to extract volume discounts from Asian and European refiners.
Colombia
Cost-sensitive processed food manufacturers are pivoting toward carrageenan gelling systems for dairy and confectionery applications where gel strength requirements permit. Traditional flake agar retains loyalty in artisanal food segments where visual particulate identity carries brand value. Bogotá industrial corridor processors are negotiating multi-year supply contracts with integrated distributors to hedge raw material volatility.
South America Agar Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade procurement concentrating around distributors possessing in-house ANVISA certification while food-grade volumes fragment across bulk wholesalers. The market structure exhibits tiered concentration: premium bacteriological-grade supply compresses around certified European and North American suppliers, mid-tier food-grade procurement disperses across regional blending operations, and economy segments face carrageenan substitution pressure. Three archetypes dominate: extraction-integrated harvester-processors in Chile and Peru, European refiners with Mercosur distribution density, and regional blenders exploiting tariff arbitrage in Uruguay and Argentina. Competitive moves center on backward integration into red algae harvesting and strategic partnerships with Brazilian hospital federations for multi-year supply contracts.
Among European-based specialists, Hispanagar S.A. and Merck KGaA occupy positions anchoring high-purity supply lines into Mercosur pharmaceutical markets. Thermo Fisher Scientific exemplifies the scale-driven archetype competing on bulk contract terms with consolidated hospital networks. These three represent the premium-tier vector where ISO 13485 certification and in-house LAL testing capability determine vendor list inclusion for Brazilian cell therapy contract manufacturers.
| Leading Market Players |
|---|
| Hispanagar S.A. |
| PT Agarindo Bogatama |
| Merck KGaA |
| Thermo Fisher Scientific |
| FUJIFILM Wako Pure Chemical Corporation |
| B&V S.r.l. |
| Marine Hydrocolloids |
| Agarmex |
| Neogen Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned Chilean harvester-processors anchor upstream supply, translating coastal extraction heritage into pricing discipline that resists commodity erosion despite carrageenan substitution threats in Colombian dairy applications. Their captive control over Gelidium beds near La Serena insulates premium-grade agar from spot-market volatility, while Brazilian hospital federation consolidation extracts volume discounts downstream.
Pricing Analysis
Distributor margin layering separates pharmaceutical-grade certification premiums from food-grade commodity handling. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 compliance status, with ANVISA fast-track certification commanding 15-20 point spreads over uncertified imports. Cost compression in food-grade flake agar is intensifying because Colombian processors are pivoting toward carrageenan where gel strength permits. Research institutions show highest price sensitivity due to fragmented purchasing, while Brazilian cell therapy contract manufacturers absorb premiums for endotoxin-controlled supply security.
Supply Chain Analysis
ANVISA's domestic-content verification protocols for pharmaceutical-grade imports are reshaping sourcing toward Mercosur blending facilities with in-house certification capability. Raw material extraction concentrates in Chile, Peru, and southern Argentina coastal zones, drawing from Gelidium and Gracilaria seasonal harvests. Supply chain risk centers on El Niño disruption to red algae yields, which fragments input planning for São Paulo vaccine manufacturers. Distribution runs through Montevideo free-zone operators serving Argentine and Paraguayan food processors with tariff-advantaged reformulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic extraction adoption is compressing processing costs for mid-tier operators, opening margin expansion as coastal Peruvian processors achieve gel strength parity with traditional alkali methods without European refiner overhead.
For Market Incumbents: Extend backward integration into Chilean harvesting concessions to secure Gelidium supply against El Niño volatility, while accelerating ISO 13485 certification investment to defend distributor relationships against European refiners targeting Brazilian hospital federation contracts. Carrageenan substitution in Colombian dairy stabilization demands specification differentiation through clarity and gel strength guarantees that commodity alternatives cannot match. For New Entrants and Emerging Players: E-procurement platforms targeting São Paulo state university laboratories offer the most penetrable entry vector, bypassing consolidated hospital network purchasing that incumbents lock through multi-year technical service bundling. Uruguay blending facility partnerships provide Mercosur tariff arbitrage without ANVISA pharmaceutical-grade compliance overhead, enabling food-grade volume accumulation before specification upgrades. For Investors and Strategic Acquirers: Brazilian pharmaceutical distributors with in-house ANVISA certification capability are the most active acquirer in this space, consolidating fragmented technical service providers to capture vaccine manufacturing procurement concentration. Acquisition target archetype: mid-cap enzymatic extraction operators in Peru with coastal harvesting relationships and unexploited capacity for pharmaceutical-grade upgrading. Watch pending Mercosur GMC hydrocolloid resolution updates as the inflection signal determining whether regional blending facilities gain sustainable cost advantages over direct importers.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pharmaceutical-Grade Certification Investment | Fast-track approval pathways enable premium positioning for Brazilian cell therapy contract manufacturers requiring endotoxin thresholds below 10 EU/g. |
| Uruguay Blending Facility Development | Montevideo port infrastructure and Mercosur tariff advantages position regional reformulation hubs serving Argentine and Paraguayan food processors. |
| Enzymatic Extraction Technology Adoption | Cellulase-assisted protocols decentralize margin capture from European refiners toward coastal Latin American harvester-processors. |
| Backward Integration into Chilean Harvesting | Captive Gelidium supply insulates against El Niño yield disruption for São Paulo vaccine manufacturing scale-up. |
| Hospital Federation Multi-Year Supply Contracts | Consolidated procurement through São Paulo and Rio de Janeiro networks extracts volume discounts and technical service bundling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with phycocolloid extraction technicians, ANVISA regulatory affairs specialists, Brazilian hospital procurement managers, and Mercosur trade compliance officers with secondary validation from customs records, ANVISA pharmaceutical-grade purity protocol documentation, Chilean Ministry of Health heavy metal limit filings, and SEC disclosures from listed agar refiners. Bottom-up segment sizing and top-down market envelope triangulation cross-checked volume estimates.
Segment-weighting across product type, application tier, and end-user concentration shaped the analytical framework over the projection horizon. Modeled dimensions included powder versus flake format splits, microbiology versus food versus pharmaceutical purity grades, and consolidated hospital network versus fragmented research institution procurement patterns. CAGRs derived from elasticity-adjusted demand curves incorporating Brazilian vaccine manufacturing capacity expansion and carrageenan substitution elasticity in Colombian dairy applications.
The model assumes a particular technology adoption path; alternative pathways for enzymatic extraction scale-up would alter the outlook if cellulase-assisted processing achieves cost parity faster than projected. Forecasts reflect assumptions around ANVISA regulatory stability, Mercosur GMC resolution timing, and El Niño frequency patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Glycomacropeptide Market
Ingredients
Clean Label Flour Market
Ingredients
Global Tomato Powder Market
Ingredients
North America Soy Protein Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Waxy Maize Starch Market
Ingredients
South America Vegetable Oil Market
Ingredients
Campesterol Market
Ingredients
Africa Fats and Oil Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Ground-Nut Oil Market
Ingredients
Bay Leaf Oil Market
Ingredients
Global Gelatin Market