
 Honeycomb Panel for Aircraft Market | 2026-2036
Honeycomb Panel for Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Honeycomb Panel for Aircraft Market Insights
Aerospace tier-1 supplier networks is reshaping how honeycomb panels reach final assembly lines, with consolidation among distributors favoring vertically integrated channels. Hexcel Corporation leverages captive carbon fiber and resin capacity to control upstream material costs. Toray Advanced Composites sustains Japanese manufacturing scale while extending North American finishing operations. Plascore specializes in aluminum and aramid honeycomb cores, occupying a niche between commodity metals and advanced composites.
A honeycomb panel for aircraft consists of a cellular core structure bonded between face sheets, typically achieving specific strength-to-weight ratios exceeding 50 kN·m/kg in optimized configurations, with cell sizes ranging from 3 mm to 25 mm depending on load-bearing requirements. Its primary purpose is to reduce aircraft structural weight while maintaining stiffness for floors, bulkheads, and control surfaces. Nomex honeycomb dominates passenger cabin interiors due to inherent flame resistance and low smoke emission properties. Composite honeycomb represents the fastest-expanding product category as co-curing and resin transfer molding technologies mature. Structural components application captures the deepest margin pools because certification cycles and performance testing create barriers for new entrants.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern flammability, smoke density, and toxic gas emission limits for aircraft interior materials, directly determining which core and facing combinations achieve market access. EPA regulations on adhesive solvent emissions and REACH restrictions on hexavalent chromium surface treatments are forcing shifts in bonding chemistry and corrosion protection processes. Stakeholders must monitor evolving sustainability mandates from regulators and OEM procurement policies that increasingly weight lifecycle carbon footprint alongside performance metrics.
Market Dynamics
Co-curing manufacturing processes are compressing production cycles for composite honeycomb panels, enabling Boeing and Airbus to reduce structural assembly lead times while FAA certification requirements for flammability testing extend qualification timelines for new material combinations.
Growth Catalysts
- Lightweighting mandates:Commercial aircraft OEM procurement specifications now prioritize specific strength-to-weight ratios above 50 kN·m/kg for floor panels and bulkheads, accelerating Nomex and aluminum core substitutions for solid metal structures.
- FAA Part 25 amendments:Updated airworthiness standards for smoke toxicity and flammability are disqualifying legacy thermoplastic cores from passenger cabin applications, creating qualified supplier scarcity for compliant aramid honeycomb.
- Resin transfer molding maturation:Automated RTM cell production is reducing composite panel labor content by half, enabling tier-1 suppliers to meet Airbus A320 family rate increases without proportional headcount expansion.
Market Restraints
- Carbon fiber feedstock concentration:Precursor supply chains cluster in Japan, the United States, and Hungary, exposing panel fabricators to geopolitical disruption and currency volatility on raw material imports.
- REACH hexavalent chromium restrictions:ECHA corrosion protection mandates are forcing adhesive formulation changes that extend bonding process development cycles by 18-24 months for European-qualified suppliers.
- Thermoplastic composite substitution:Continuous fiber-reinforced thermoplastic panels from Toray and Teijin are penetrating non-structural aircraft interiors, compressing addressable volume for traditional honeycomb in sidewall applications.
Strategic Opportunities
- Unmanned aerial systems:Military drone programs in Israel and Turkey are specifying honeycomb sandwich structures for payload bays and fuel tanks, creating demand outside commercial aviation certification frameworks.
- Sustainability-linked procurement:Boeing's sustainable aviation fuel commitments now extend to supplier lifecycle carbon assessments, favoring panel producers with renewable energy-powered autoclave operations and bio-based resin options.
- Urban air mobility:eVTOL airframe developers in California and Germany are adopting automotive-scale composite manufacturing, opening volume contracts for standardized honeycomb core sheets without aircraft-grade certification overhead.
Industry Challenges
- Autoclave operator scarcity:Skilled technicians capable of managing temperature-pressure profiles for co-cured composite panels command wage premiums exceeding 40% above general manufacturing rates in Wichita and Toulouse clusters.
- FAA PMA certification timelines:Supplemental type certificate approvals for replacement interior panels now average 14 months, freezing aftermarket product development roadmaps for distributors serving aging narrowbody fleets.
- Legacy fleet material traceability:MRO providers struggle to document core cell density and adhesive batch records for 1990s-era installations, blocking derivative certification paths for structural repair stations.
Report Scope
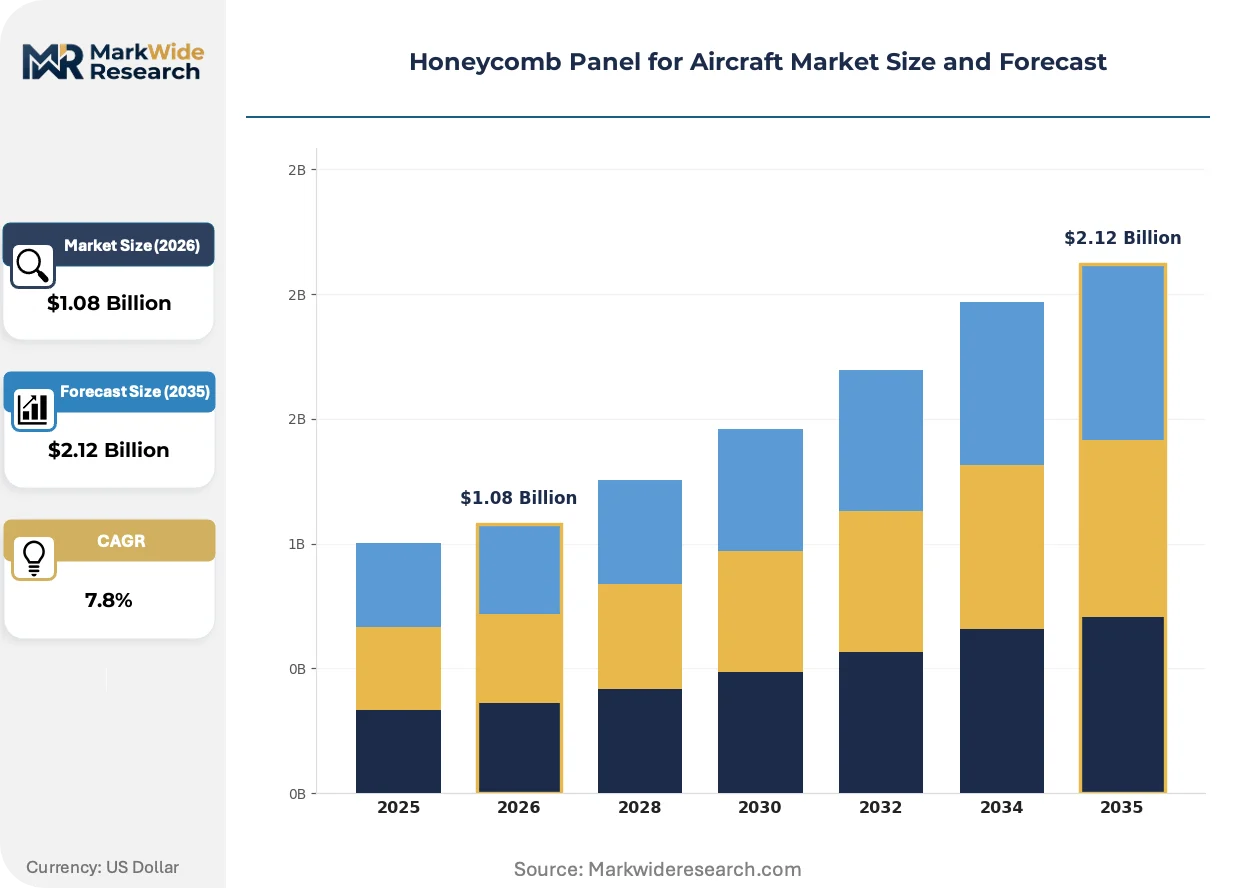
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honeycomb Panel for Aircraft Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Honeycomb, Nomex Honeycomb, Composite Honeycomb, Thermoplastic Honeycomb, Paper Honeycomb Application: Passenger Cabin Interiors, Cargo Flooring, Structural Components, Control Surfaces, Partition Walls End User: Commercial Aircraft Manufacturers, Defense Contractors, Maintenance Providers, Private Jet Builders, Aerospace Tier-1 Suppliers Technology: Adhesive Bonding, Mechanical Fastening, Co-curing, Sandwich Construction, Resin Transfer Molding |
| Companies Covered | Hexcel Corporation, Toray Advanced Composites, Plascore, Rel Core, Euro-Composites, The Gill Corporation, Oerlikon Metco, Argosy International, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeycomb Panel for Aircraft Market Trends and Innovations
Manufacturing automation and regulatory chemistry shifts are restructuring how honeycomb panels achieve cost competitiveness against emerging thermoplastic alternatives. Material qualification pathways are lengthening even as production throughput accelerates.
Thermoplastic resin systems are migrating from experimental R&D programs into qualified production lines for secondary aircraft structures. Tier-1 suppliers in Japan and Germany are retrofitting existing autoclaves for polyetherketoneketone processing, targeting wing-to-body fairings and cargo liners where damage tolerance requirements are moderate. This technology migration is compressing the cost gap between thermoset and thermoplastic sandwich panels from 3:1 to 1.5:1 over five years.
EPA National Emission Standards for Hazardous Air Pollutants are tightening volatile organic compound limits on adhesive solvent formulations used in core-to-facing bonding operations. Manufacturing facilities in Kansas and Washington State face capital expenditure requirements for thermal oxidizer installations or water-based adhesive conversion programs. Suppliers serving Boeing 787 aftermarket programs are consolidating finishing operations into EPA-compliant regional hubs rather than maintaining distributed repair station networks.
Airline technical procurement teams are consolidating vendor lists around vertically integrated core-to-panel suppliers capable of delivering finished floor panels with FAA 8110-3 design approval. Maintenance organizations in Miami and Singapore are shifting from component-level purchasing to module contracts encompassing core supply, machining, and installation kit packaging. This consolidation pattern favors producers with captive Nomex core capacity and in-house CNC contouring equipment over specialized core-only manufacturers.
Honeycomb Panel for Aircraft Market Segmentation
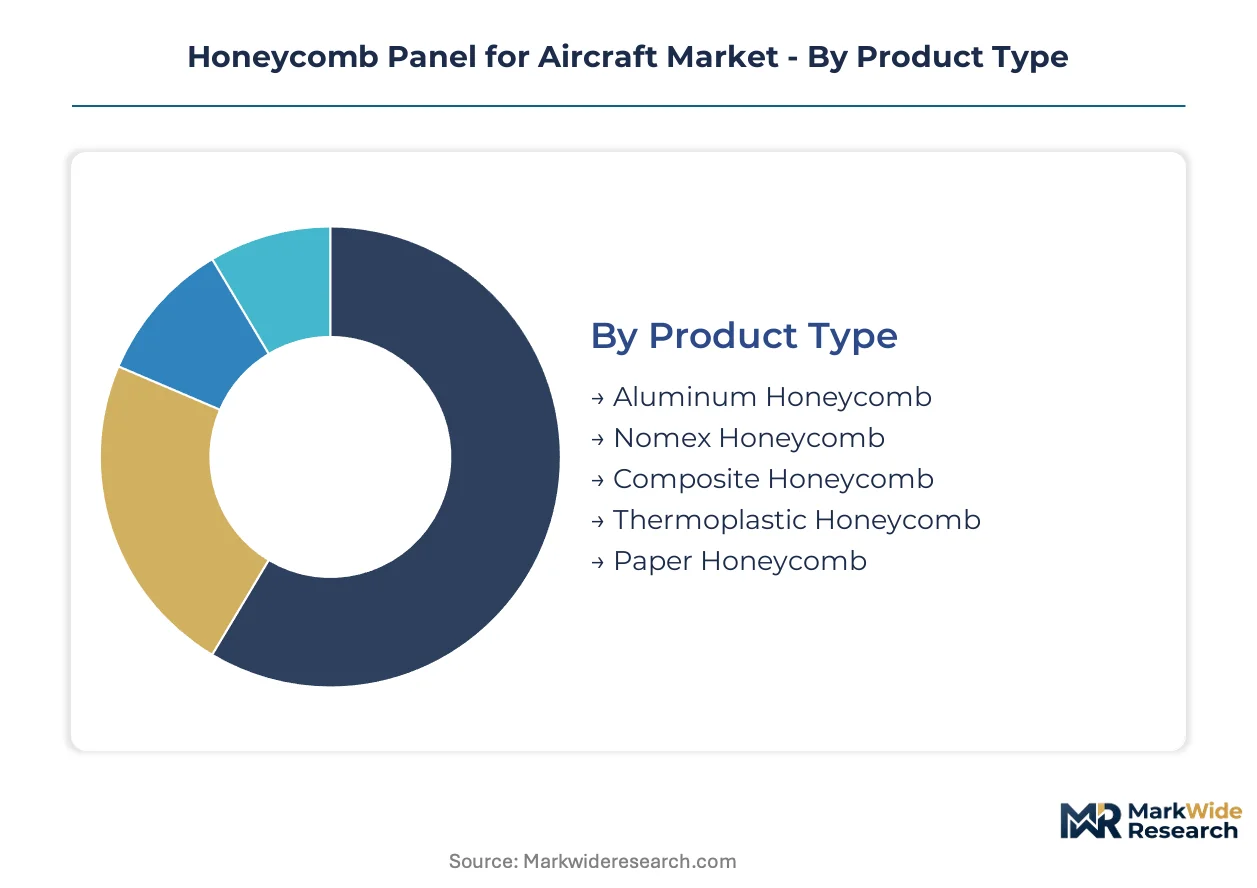
Honeycomb panel procurement cycles vary dramatically by certification burden and structural criticality. Segmentation reveals where inventory velocity concentrates versus where qualification timelines lock in supplier relationships for years.
Product Type:
Replacement cycle timing separates commodity cores from aerospace-qualified materials, with uncertified products turning inventory quarterly while FAA-approved variants sit in qualification for eighteen months.
- Nomex Honeycomb:Aramid fiber cores achieve flame resistance without additional treatments, making them indispensable for passenger cabin floors and bulkheads where FAA Part 25 governs smoke toxicity. Boeing and Airbus specification control limits qualified suppliers to a narrow tier, concentrating procurement through Hexcel and Plascore captive production lines in Washington State and Michigan.
- Composite Honeycomb:Carbon fiber-reinforced cores bonded with epoxy or BMI resins deliver the highest specific stiffness for control surfaces and primary structure. Demand concentrates in Airbus A350 and Boeing 787 programs, where co-curing automation at Toray's Tacoma facility and Hexcel's Salt Lake City plant compresses panel delivery from twelve weeks to four.
- Aluminum Honeycomb:5052 and 5056 alloy cores dominate cargo flooring and galley structures where impact resistance trumps weight savings. Reliance on aerospace-grade foil from Kaiser Aluminum in Spokane locks supply chains into North American smelter networks.
- Thermoplastic Honeycomb:Polypropylene and PEEK cores are penetrating non-structural applications where thermoformability enables rapid contouring without autoclave curing. Automotive-scale production at Lanxess's Antwerp facility is pulling unit costs below aerospace thermoset equivalents.
- Paper Honeycomb:Recycled kraft cores serve shipping dunnage and temporary protection during assembly, never achieving airworthiness certification but capturing volume in ground support equipment.
Nomex honeycomb anchors the volume base while composite honeycomb gains share at the steepest rate.
Application:
Margin structure inverts between cosmetic interiors and flight-critical structure, with certification overhead consuming sixty percent of production cost in primary load paths versus fifteen percent in sidewall panels.
- Structural Components:Wing ribs, spars, and empennage boxes demand damage tolerance certification under FAA AC 20-107B, creating qualification archives that incumbent suppliers leverage to block entrants. Boeing 777X and Airbus A321XLR programs are absorbing expanded composite honeycomb tonnage as metallic structures retire.
- Passenger Cabin Interiors:Ceiling panels, sidewalls, and overhead bins prioritize flammability performance over mechanical load, with Nomex cores specified universally for smoke emission compliance. Lufthansa Technik and ST Engineering are consolidating refurbishment contracts around module-level suppliers who deliver finished kits rather than raw core.
- Cargo Flooring:Roller deck and fixed floor panels combine aluminum honeycomb with phenolic or epoxy facings to withstand forklift impact and tie-down loads. E-commerce freight growth is extending cargo conversion demand for aging 767-300ER and A330-300 passenger frames.
- Control Surfaces:Ailerons, flaps, and spoilers require fatigue-resistant sandwich construction with lightning strike protection integrated into facing layups. Gulfstream and Dassault business jet programs specify these panels at premium certification multiples over commercial equivalents.
- Partition Walls:Class dividers and cockpit barriers balance acoustic damping with minimal weight, often employing paper or thermoplastic cores where fire regulations permit. Aftermarket refurbishment cycles run three to five years versus twenty for structural panels.
Passenger cabin interiors anchor the volume base while structural components command the widest margin spreads.
End User:
Procurement sophistication varies from OEM engineering-directed specifications to MRO price-driven spot buying, with certification ownership determining who bears qualification cost and timeline risk.
- Commercial Aircraft Manufacturers:Boeing, Airbus, and Embraer dictate material specifications through purchase agreements that lock suppliers into decade-long supply commitments with inflation-indexed pricing. Their technical teams control design approval under FAA 8110-3 and EASA DOA frameworks.
- Aerospace Tier-1 Suppliers:Spirit AeroSystems, GKN Aerospace, and FACC manufacture finished assemblies under risk-sharing contracts, procuring honeycomb core as raw material rather than finished panels. Their Wichita, Bristol, and Ottobrunn facilities concentrate bonding and machining operations close to final assembly.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and BAE Systems specify military-grade honeycomb for fighter fuel tanks and payload bays where MIL-STD-401B governs sandwich construction. Classified programs bypass commercial certification, accelerating material substitution cycles.
- Maintenance Providers:Lufthansa Technik, AAR, and ST Engineering source replacement panels through PMA or DER-approved paths, facing fourteen-month average certification timelines that strain aging fleet support economics.
- Private Jet Builders:Gulfstream, Bombardier, and Dassault procure at lower volumes with higher customization, accepting premium pricing for rapid-turnaround panel contouring at dedicated finishing shops in Savannah and Montreal.
Commercial aircraft manufacturers anchor the volume base while defense contractors are expanding procurement most quickly outside FAA commercial frameworks.
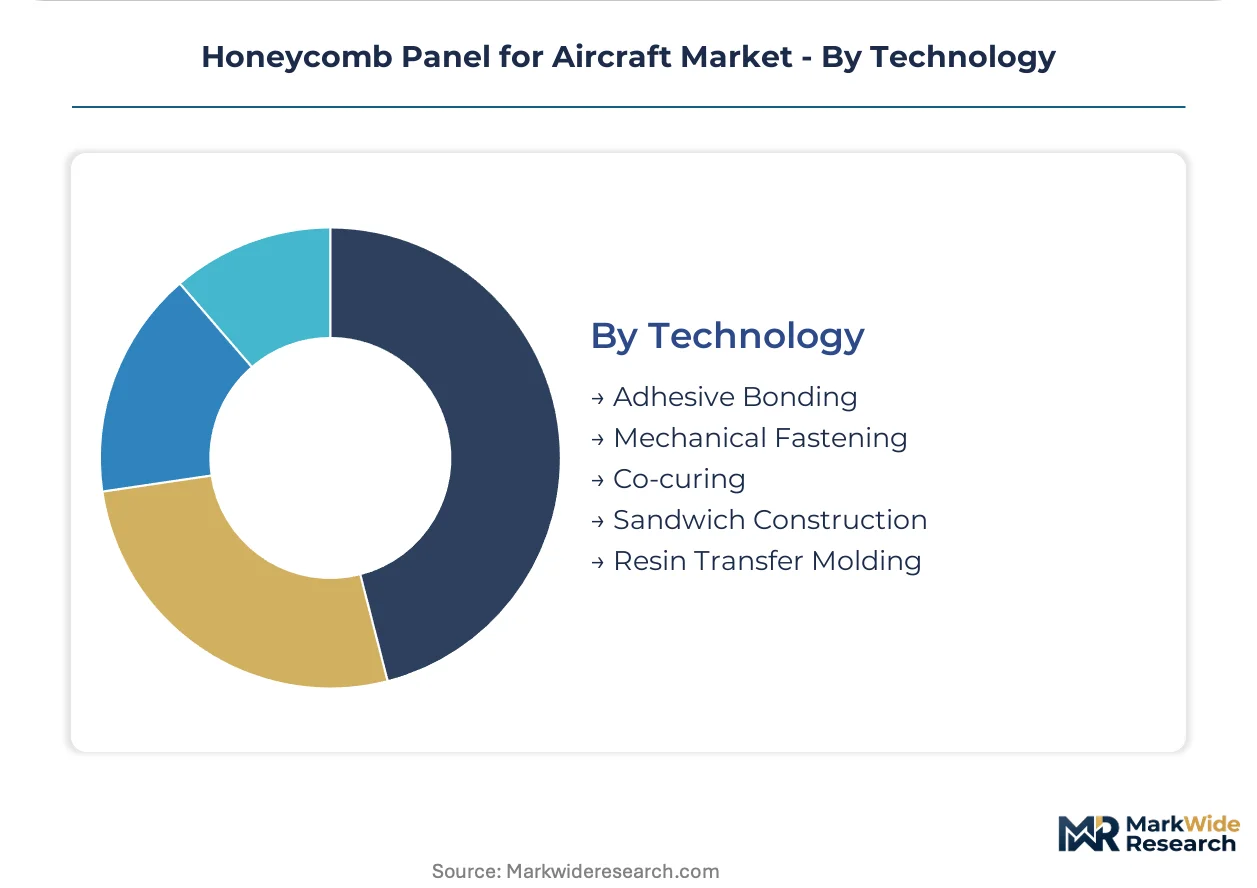
Technology:
Process selection determines labor content, capital intensity, and regulatory exposure, with adhesive chemistry facing the most severe environmental compliance pressure.
- Co-curing:Simultaneous curing of core and facings in autoclaves eliminates secondary bonding operations, achieving the lightest panels for primary structure. Boeing 787 wing-to-body fairings exemplify this approach at Spirit AeroSystems's Kinston facility.
- Resin Transfer Molding:Automated RTM injects thermoset resin into closed molds, halving labor content versus hand layup while maintaining aerospace-grade void content below two percent. Airbus A320 family rate increases depend on RTM panel supply from Premium Aerotec's Augsburg plant.
- Adhesive Bonding:Film and paste adhesives join pre-cured cores to facings, remaining dominant for repairs and low-rate production where autoclave investment cannot be justified. EPA NESHAP regulations on solvent emissions are forcing water-based formulation shifts at Kansas and Washington State facilities.
- Sandwich Construction:Generic term encompassing any core-plus-facing assembly, with performance varying dramatically by core density and facing modulus selection. This catch-all category captures legacy manufacturing still prevalent in general aviation.
- Mechanical Fastening:Rivets and screws supplement bonding in high-load transfer zones or repair scenarios, adding weight but enabling field disassembly. Military drone manufacturers in Turkey and Israel favor this approach for rapid battlefield repair.
Adhesive bonding anchors the volume base while resin transfer molding is climbing the fastest as Airbus and Boeing push for rate-capable automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Washington State and Toulouse, where Boeing and Airbus procurement teams dictate specification terms, while Asian fabricators absorb margin compression from feedstock import dependencies and currency volatility.
United States
FAA Part 25 certification requirements and Boeing 737 MAX production rate recovery drive honeycomb panel demand. The EPA's NESHAP regulations on adhesive solvent emissions force Kansas and Washington State facilities into capital-intensive thermal oxidizer investments. Wichita's Spirit AeroSystems cluster concentrates co-curing operations for wing-to-body fairings.
Germany
Airbus A320 family rate increases and Premium Aerotec's Augsburg RTM automation expansion anchor procurement volumes. ECHA REACH restrictions on hexavalent chromium surface treatments extend European supplier qualification timelines by 18-24 months. Bavaria's aerospace corridor integrates composite finishing with automotive-scale thermoplastic processing.
Japan
Toray's carbon fiber precursor supply and METI industrial policy support advanced composites manufacturing. The country's national aerospace regulator maintains alignment with FAA bilateral certification agreements. Nagoya's Chubu region hosts co-curing operations serving both commercial aviation and defense programs.
China
COMAC C919 production ramp and MIIT dual carbon goals accelerate domestic honeycomb panel substitution for imported structures. GB standards for aircraft materials are converging toward FAA and EASA technical equivalence. Tianjin's aerospace industrial zone concentrates bonding operations for Airbus A320 family final assembly.
Israel
Military drone programs specifying honeycomb sandwich structures for payload bays operate outside FAA commercial certification frameworks. The country's national defense procurement authority accelerates material substitution cycles for classified applications. Tel Aviv's defense technology corridor integrates composite fabrication with unmanned systems development.
Honeycomb Panel for Aircraft Market Competitive Landscape
Integrated core-to-panel suppliers and specialized core manufacturers split the market along certification ownership lines. Consolidation favors vertically integrated channels capable of delivering FAA 8110-3 design-approved finished panels. Three archetypes dominate: captive fiber-and-resin producers controlling upstream costs, regional finishing specialists with CNC contouring equipment, and automotive-scale thermoplastic entrants. Competitive moves concentrate on M&A for core capacity and strategic partnerships for autoclave operator training pipelines.
Among North American fabricators, Hexcel Corporation and Plascore occupy positions at opposite ends of the product spectrum. Hexcel exemplifies the captive fiber archetype with in-house carbon fiber and resin production. Plascore represents the specialized core manufacturer model with aluminum and aramid honeycomb focus. Toray Advanced Composites anchors the trans-Pacific supply chain with Japanese manufacturing scale extended through North American finishing operations.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Advanced Composites |
| Plascore |
| Rel Core |
| Euro-Composites |
| The Gill Corporation |
| Oerlikon Metco |
| Argosy International |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
Single-source carbon fiber precursor dependency between Japan and North American panel fabricators determines both the premium spread for qualified aerospace materials and the geographic clustering of co-curing operations. Boeing and Airbus procurement teams exploit this concentration to enforce long-term offtake contracts with inflation-indexed pricing, while tier-1 suppliers absorb margin compression from yen-denominated feedstock volatility.
Pricing Analysis
Configured-to-order pricing for FAA 8110-3 design-approved floor panels commands multiples of three to five times standard uncertified core sheet pricing. Three-tier pricing structure across premium, standard, and economy levels separates co-cured primary structure panels from adhesive-bonded secondary assemblies and commodity aluminum cargo flooring. Cost compression in the standard tier is intensifying because automotive-scale thermoplastic entrants from Lanxess's Antwerp facility are pulling unit costs below aerospace thermoset equivalents. Commercial aircraft OEMs exhibit the least price sensitivity due to decade-long supply commitments, while maintenance providers face acute margin pressure from fourteen-month PMA certification timelines.
Supply Chain Analysis
Tariff exposure between Japanese carbon fiber precursor producers and North American panel fabricators dominates supply chain risk assessment for qualified aerospace honeycomb. Raw material sourcing draws from Toray's Nagoya precursor facilities, Hexcel's Salt Lake City resin operations, and Kaiser Aluminum's Spokane foil smelter. Distribution runs through vertically integrated tier-1 suppliers with in-house CNC contouring equipment rather than specialized core-only manufacturers. Single-source vulnerability concentrates in aramid fiber supply for Nomex honeycomb, where DuPont's Richmond, Virginia facility anchors global qualified production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across certification tiers and manufacturing process generations creates niche entry points for specialists. Urban air mobility developers and military drone programs are bypassing FAA commercial frameworks, opening demand pockets outside incumbent supplier relationships.
For Market Incumbents: Pre-empt thermoplastic substitution by retrofitting existing autoclaves for polyetherketoneketone processing at facilities in Washington State and Bavaria. Secure captive Nomex core capacity through strategic partnerships with DuPont's Richmond aramid fiber operations to block entrant access to qualified cabin interior supply. Certification investment in FAA PMA pathways for aging narrowbody fleets defends aftermarket revenue against distributor consolidation. For New Entrants and Emerging Players: Establish a beachhead in unmanned aerial systems payload bay structures for Israeli and Turkish defense programs operating outside FAA Part 25 constraints. Target thermoplastic honeycomb production for eVTOL airframes in California and Germany, where automotive-scale manufacturing eliminates aircraft-grade certification overhead. Go-to-market angle emphasizes rapid-turnaround panel contouring without autoclave curing timelines. For Investors and Strategic Acquirers: Regional finishing specialists with CNC contouring equipment and EPA-compliant thermal oxidizer installations represent the most defensible acquisition target archetype. Long-term viability hinges on positioning for sustainability-linked procurement criteria from Boeing's supplier lifecycle carbon assessment programs. Signal to watch is consolidation of maintenance organization vendor lists around module-level suppliers capable of delivering finished installation kits.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Retrofit for Thermoplastic Processing | Enables PEKK panel production for wing-to-body fairings at Spirit AeroSystems' Kinston facility. |
| Captive Nomex Core Capacity Acquisition | Secures qualified aramid fiber supply from DuPont's Richmond operations for cabin interior dominance. |
| EPA NESHAP Compliance Hub Consolidation | Concentrates finishing operations in Kansas and Washington State to meet adhesive solvent emission limits. |
| Urban Air Mobility Volume Contracts | Opens automotive-scale production for eVTOL developers in California and Germany without certification overhead. |
| PMA Certification Pipeline Investment | Accelerates aftermarket panel approvals for aging 767-300ER and A330-300 cargo conversion demand. |
Research Methodology
Initial hypotheses were tested against primary input from tier-1 supplier procurement managers, FAA certification engineers, and MRO technical directors and refined through secondary validation against SEC 10-K filings, EASA DOA framework documentation, and customs trade data. Aerospace OEM program managers and autoclave operations technicians provided operational context on co-curing cycle compression. Bottom-up volume modeling triangulated against top-down procurement spend analysis from Boeing and Airbus supplier disclosure.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, application criticality, end-user procurement sophistication, and manufacturing technology intensity. CAGRs were derived from production rate trajectories for the 737 MAX and A320 family programs, cross-referenced against resin transfer molding automation deployment timelines at Premium Aerotec's Augsburg plant.
Sensitivities concentrate around FAA Part 25 amendment timing, carbon fiber precursor tariff exposure, and thermoplastic substitution acceleration in non-structural applications. Forecasts reflect assumptions on Boeing production rate recovery and Airbus A321XLR composite structure adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market