
 Stealth Coating Market | 2026-2036
Stealth Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Stealth Coating Market Analysis
The performance gap between premium radar absorbing systems and commodity visual camouflage is expanding as mission profiles demand multi-spectral survivability. BAE Systems leverages its integrated defense electronics heritage to anchor high-value electromagnetic absorption contracts across UK and Australian naval programs. Lockheed Martin Corporation dominates next-generation aerospace applications through captive R&D pipelines tied to classified airframe development. PPG Industries, Inc. competes in the commercial-military crossover space, sustaining coating chemistry advantages that bridge infrared suppression and corrosion protection.
Stealth coatings are engineered material systems that manipulate electromagnetic, acoustic, or thermal signatures through controlled impedance matching, layered dielectric compositions, and frequency-selective surface architectures, primarily serving to reduce detectability of military platforms across radar, infrared, and sonar domains. Radar absorbing materials command the largest value pool due to legacy fighter and bomber fleet modernization cycles, while infrared coatings represent the fastest-expanding segment driven by heat-seeking missile countermeasure requirements. Hybrid solutions integrating electromagnetic absorption with infrared reflective technology are capturing margin concentration as defense contractors demand consolidated signature management rather than discrete coating stacks.
The US Department of Defense dictates material qualification pathways through MIL-STD-461 and MIL-STD-810 frameworks, while the EU Green Deal and REACH chemical restrictions are forcing reformulation of legacy solvent-based coating systems across European supply chains. Stakeholders must monitor evolving spectrum allocation rules from the FCC and cross-border technology transfer controls, as these will determine which coating chemistries achieve platform integration and which face market access barriers.
Market Dynamics
Defense procurement reforms under the US Department of Defense are compressing qualification timelines for radar absorbing materials while simultaneously tightening electromagnetic spectrum warfare performance thresholds. This regulatory acceleration is forcing coating suppliers to front-load R&D expenditure against shorter contract award cycles.
Growth Catalysts
- Electromagnetic spectrum warfare doctrines:NATO member states are mandating multi-spectral signature management across next-generation combat aircraft programs. Pentagon-funded development pipelines prioritize platforms with integrated radar and infrared suppression.
- Heat-seeking missile proliferation:Infrared coatings are capturing procurement priority as theater missile defense requirements expand. Naval and rotary-wing platforms across Indo-Pacific operating environments drive specification updates.
- REACH chemical restrictions:The EU Green Deal is accelerating solvent-based coating reformulation. European defense contractors must qualify aqueous and low-VOC alternatives to maintain platform integration access.
Market Restraints
- Rare earth magnet supply concentration:Ferrite and carbonyl iron feedstocks for radar absorbing layers concentrate in Chinese processing facilities. Western coating manufacturers face input cost volatility and dual-use export control friction.
- MIL-STD-461 qualification timelines:Electromagnetic interference testing protocols extend material validation to 18-24 months. Smaller suppliers lack capital reserves to sustain pre-revenue development phases.
- Visual camouflage substitution:Commodity multispectral paints satisfy lower-threat mission profiles at one-tenth the unit cost. Budget-constrained operators defer premium absorbing system upgrades.
Strategic Opportunities
- Unmanned platform proliferation:UAV swarming tactics require disposable signature management at unit cost parity with manned aircraft. Coating formulations optimized for additive manufacturing deposition are capturing DARPA attention.
- Hybrid electromagnetic-infrared integration:Consolidated signature management stacks displace discrete coating layers. Suppliers mastering dielectric-magnetic composite architectures command margin concentration.
- Australian naval modernization:The AUKUS submarine program generates demand for acoustic and radar absorbing hull treatments. Local content requirements incentivize joint venture formation with established US and UK coating houses.
Industry Challenges
- Computational materials engineering talent scarcity:Finite element modeling for frequency-selective surface design requires physicist-chemist hybrid profiles. Defense contractors and commercial aerospace compete for identical PhD pipelines.
- Legacy platform retrofit integration:Fifth-generation absorbing materials impose weight and thickness penalties incompatible with aging airframe structural margins. Engineering teams must balance performance gain against airworthiness recertification burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stealth Coating Market |
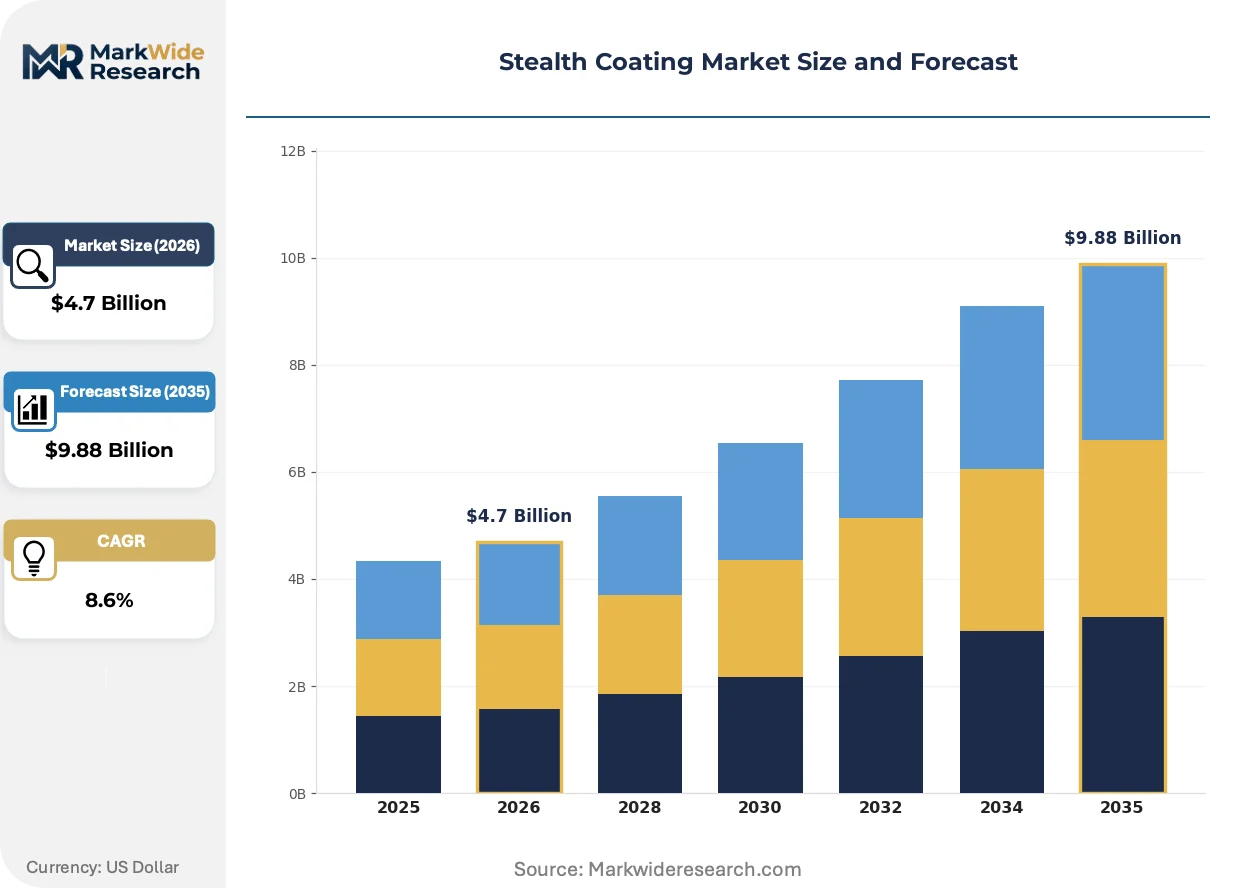
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Coatings, Radar Absorbing Materials, Sound Dampening Coatings, Visual Stealth Coatings Application: Aerospace, Military Vehicles, Naval Defense, Commercial Aviation Technology: Electromagnetic Absorption, Acoustic Coating, Infrared Reflective Technology, Hybrid Solutions End User: Defense Contractors, Government Agencies, OEMs, Research Institutions |
| Companies Covered | PPG Industries, Inc., AkzoNobel N.V., BAE Systems, Lockheed Martin Corporation, BASF SE, Axalta Coating Systems, The Sherwin-Williams Company, Northrop Grumman Corporation, Hentzen Coatings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stealth Coating Market Emerging Trajectories
Metamaterial architectures and additive manufacturing processes are compressing the traditional trade-off between broadband absorption and mechanical durability. These advances enable functionally graded coatings that adapt signature properties across platform surface geometry.
Metamaterial-based radar absorbing structures manipulate electromagnetic waves through subwavelength resonator arrays rather than bulk dielectric loss. Naval aviation programs in the United States and United Kingdom are piloting these surfaces for shipboard aircraft engine inlets. The technology is expanding into conformal antenna integration, merging signature reduction with communication aperture functionality.
REACH and the EU F-Gas Regulation are banning perfluorinated compounds historically used in corrosion-resistant primer systems. European coating formulators are accelerating ceramic-polymer hybrid development to satisfy both chemical compliance and salt-fog durability requirements. German and French naval procurement offices now specify reformulated systems for surface combatant superstructures.
Platform primes are unbundling coating application from airframe manufacture, creating dedicated signature management subcontractors. This channel shift concentrates technical risk with specialized suppliers while allowing OEMs to optimize final assembly throughput. The pattern is most visible in US Air Force next-generation bomber and fighter sustainment contracts, where depot-level reapplication cycles generate recurring revenue pools distinct from original equipment supply.
Stealth Coating Market Segmentation
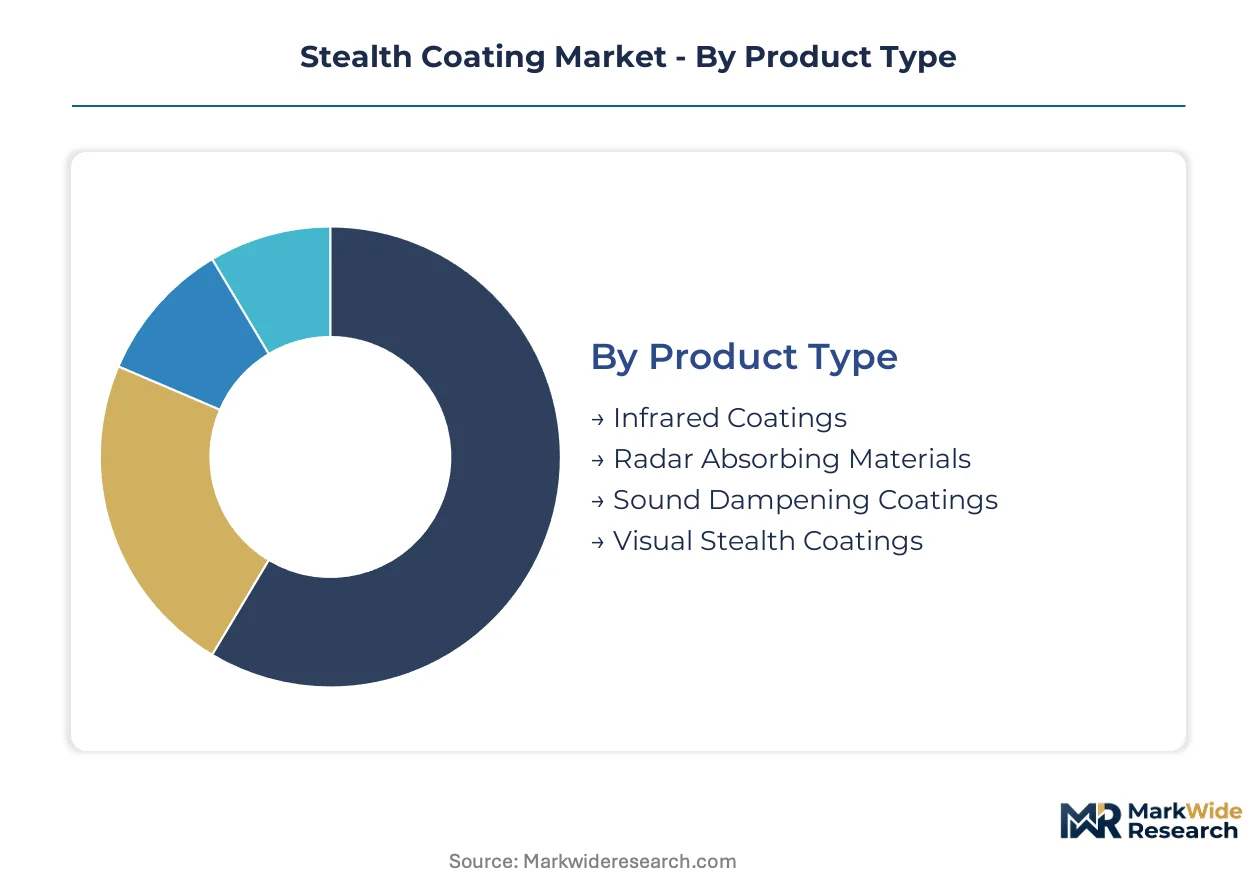
Stealth coating procurement splits sharply between mission-critical defense platforms and commercial aviation requirements. Segment boundaries blur as multi-spectral signature management consolidates formerly discrete material categories into integrated stack architectures.
Product Type:
Customization intensity varies from commodity visual treatments to engineered electromagnetic systems requiring platform-specific impedance matching protocols.
- Radar Absorbing Materials:Ferrite and carbonyl iron composites with controlled dielectric loss tangents dominate fifth-generation fighter programs. Pentagon-funded next-generation combat aircraft sustain procurement concentration in the United States, though qualification timelines under MIL-STD-461 compress supplier margins.
- Infrared Coatings:Ceramic-polymer hybrids manipulate thermal emissivity to defeat heat-seeking missile seekers. Indo-Pacific naval and rotary-wing platforms drive specification urgency as theater missile defense requirements expand across NATO member states.
- Sound Dampening Coatings:Viscoelastic polymers with embedded particulate fillers attenuate acoustic signatures for submarine hull applications.
- Visual Stealth Coatings:Pigment-engineered systems matching spectral reflectance to operating environments satisfy lower-threat mission profiles at reduced unit cost.
Leading the category by volume: Radar Absorbing Materials. Expanding most quickly: Infrared Coatings.
Application:
Platform operating environments dictate coating stack complexity, with naval applications demanding simultaneous acoustic and electromagnetic suppression.
- Aerospace:Conformal radar absorbing structures integrate with engine inlet geometries and leading edges. US Air Force next-generation bomber and fighter programs anchor demand, with depot-level reapplication cycles generating recurring revenue distinct from original equipment supply.
- Naval Defense:Hull-applied acoustic tiles and radar absorbing superstructure treatments address multi-domain detectability. AUKUS submarine program requirements concentrate procurement across Australian, UK, and US naval modernization pipelines.
- Military Vehicles:Ground platform coatings prioritize infrared suppression against man-portable anti-tank guided munitions.
- Commercial Aviation:Reduced-signature treatments for business and regional jets address corrosion protection crossover with marginal signature reduction benefits.
Highest specification intensity: Aerospace. Steepest expansion trajectory: Naval Defense.
Technology:
Technology selection pivots on frequency band targeting, with broadband architectures commanding premium positioning over narrowband solutions.
- Hybrid Solutions:Consolidated electromagnetic-infrared stacks displace discrete coating layers through dielectric-magnetic composite architectures. Margin concentration accrues to suppliers mastering impedance matching across multiple spectrum domains simultaneously.
- Electromagnetic Absorption:Layered dielectric compositions with frequency-selective surface architectures manipulate radar cross-section through controlled wave interference.
- Infrared Reflective Technology:Low-emissivity surface treatments reduce thermal contrast against background environments.
- Acoustic Coating:Elastomeric hull treatments attenuate sonar return through impedance mismatch with surrounding water.
Driving margin expansion: Hybrid Solutions. Maturest technology base: Electromagnetic Absorption.
End User:
Contracting authority determines qualification burden, with direct government procurement imposing stricter material validation than commercial channels.
- Defense Contractors:Platform primes unbundle coating application from airframe manufacture, concentrating technical risk with specialized signature management subcontractors. US Air Force sustainment contracts exemplify this channel shift.
- Government Agencies:Direct procurement through defense ministries and research laboratories funds pre-competitive technology development.
- OEMs:Original equipment manufacturers integrate coatings during initial platform assembly, with specification authority varying by contract structure.
- Research Institutions:DARPA and national laboratory funding pilots metamaterial architectures and additive manufacturing deposition methods.
Capturing procurement volume: Defense Contractors. Fastest qualification pathway: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington DC anchors stealth coating procurement through Pentagon-funded next-generation combat aircraft programs, with demand concentrating around defense contractor clusters in Virginia and Maryland corridors.
United States
Defense procurement reforms under the US Department of Defense compress qualification timelines for radar absorbing materials while tightening electromagnetic spectrum warfare thresholds. MIL-STD-461 and MIL-STD-810 frameworks dictate material validation pathways. The Virginia-Maryland aerospace corridor sustains coating application subcontractor concentration for US Air Force next-generation bomber sustainment contracts.
United Kingdom
Naval aviation programs pilot metamaterial-based radar absorbing structures for shipboard aircraft engine inlets. BAE Systems leverages integrated defense electronics heritage to anchor electromagnetic absorption contracts. The Portsmouth naval base cluster drives specification urgency for acoustic and radar absorbing hull treatments under AUKUS submarine program requirements.
Germany
Naval procurement offices specify reformulated ceramic-polymer hybrid systems for surface combatant superstructures to satisfy EU Green Deal chemical compliance. REACH and the EU F-Gas Regulation ban perfluorinated compounds in legacy primer systems. The Kiel shipbuilding corridor concentrates aqueous and low-VOC alternative qualification activity.
Australia
The AUKUS submarine program generates demand for acoustic and radar absorbing hull treatments with local content requirements incentivizing joint venture formation. Heat-seeking missile countermeasure specifications expand across Indo-Pacific naval and rotary-wing platforms. The Osborne naval shipyard in South Australia anchors industrial participation mandates.
France
European defense contractors qualify aqueous coating alternatives to maintain platform integration access under REACH chemical restrictions. Ceramic-polymer hybrid development accelerates to satisfy salt-fog durability requirements. The Toulouse aerospace cluster sustains infrared coating research for thermal emissivity manipulation against heat-seeking threats.
Stealth Coating Market Vendor Landscape
Premium-margin players sit above commodity-margin players across qualification burden and spectrum coverage breadth. The vendor base concentrates around defense-electronics integrators, specialty chemical formulators, and aerospace platform primes with captive coating pipelines. Three archetypes dominate: integrated defense contractors with classified R&D access, commercial coating houses bridging military-commercial chemistry, and dedicated signature management subcontractors. Competitive moves center on unbundling coating application from airframe manufacture and forming AUKUS-aligned joint ventures for Australian naval content requirements.
Within the integrated defense contractor tier, BAE Systems and Lockheed Martin Corporation exemplify players leveraging captive electromagnetic absorption development pipelines tied to classified programs. Among specialty chemical formulators with commercial-military crossover positioning, PPG Industries, Inc. occupies a position bridging infrared suppression and corrosion protection chemistry. These three anchors represent distinct competitive vectors: platform prime integration, defense-electronics heritage, and coating chemistry scale.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| AkzoNobel N.V. |
| BAE Systems |
| Lockheed Martin Corporation |
| BASF SE |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Northrop Grumman Corporation |
| Hentzen Coatings, Inc. |
| Others |
Supply Flow & Price Mechanics
US Department of Defense procurement reforms compressing qualification timelines for radar absorbing materials are forcing coating suppliers to front-load R&D expenditure against shorter contract award cycles, compressing margins across the supplier base while concentrating pricing power with qualified incumbents.
Pricing Analysis
Outcome-based pricing anchored to electromagnetic spectrum warfare performance thresholds dominates premium tiers, with defense contractors paying for verified radar cross-section reduction rather than material volume. Three-tier pricing structure across MIL-STD-461 qualified, commercial-military crossover, and commodity visual camouflage levels separates segments by certification burden and spectrum coverage breadth. Cost compression in unqualified aqueous alternatives is intensifying because REACH chemical restrictions force European reformulation without guaranteed platform integration. Budget-constrained NATO member states exhibit highest price sensitivity, while Pentagon-funded next-generation combat aircraft programs demonstrate lowest sensitivity due to mission-critical specification requirements.
Supply Chain Analysis
Direct-to-defense-contractor channels handle hyperscale procurement for US Air Force next-generation bomber and fighter programs, with platform primes unbundling coating application to specialized signature management subcontractors. Rare earth magnet processing concentrates in China, with ferrite and carbonyl iron feedstocks drawing from Chinese facilities that expose Western coating manufacturers to dual-use export control friction. Viscoelastic polymer resins and ceramic-polymer hybrid precursors rest on petrochemical supply chains concentrated in Germany and the United States. Single-source vulnerability in Chinese rare earth processing creates structural supply risk that qualified suppliers mitigate through strategic stockpiling and alternative feedstock qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metamaterial architectures are displacing legacy layered dielectric compositions across naval aviation and next-generation combat aircraft programs, compressing the traditional trade-off between broadband absorption and mechanical durability.
For Market Incumbents: Extend electromagnetic spectrum warfare performance validation capabilities to capture DARPA-funded additive manufacturing deposition programs for UAV swarming applications. Deepen captive R&D pipelines for hybrid electromagnetic-infrared integration before qualification timelines compress further under US Department of Defense procurement reforms. Lockheed Martin Corporation and BAE Systems demonstrate defensive positioning through classified airframe development access that emerging entrants cannot replicate. For New Entrants and Emerging Players: Begin with Australian naval modernization under AUKUS submarine program local content requirements, where joint venture formation with established US and UK coating houses satisfies industrial participation mandates. Target aqueous and low-VOC alternative qualification for European defense contractors facing REACH chemical restrictions, as this segment offers penetrable access without MIL-STD-461 timeline burdens. Go-to-market positioning should emphasize additive manufacturing deposition expertise for disposable UAV signature management. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated signature management subcontractors given platform prime unbundling trends concentrating technical risk and recurring revenue pools. Long-term viability over a multi-year window favors suppliers mastering dielectric-magnetic composite architectures for consolidated signature management stacks. Acquisition target archetype: mid-cap coating formulators with aqueous chemistry capabilities and existing defense contractor relationships. Signal to watch: DARPA program awards for metamaterial-based radar absorbing structures piloting at US naval aviation programs.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | AUKUS local content requirements in Australia incentivize partnership with established US and UK coating houses. |
| Additive Manufacturing Deposition | UAV swarming tactics under DARPA attention require coating formulations optimized for non-traditional application methods. |
| Aqueous Chemistry Qualification | REACH and EU F-Gas Regulation bans on perfluorinated compounds force ceramic-polymer hybrid development for European naval procurement. |
| Hybrid Stack Integration | Consolidated electromagnetic-infrared architectures displace discrete coating layers and capture margin concentration. |
| Depot-Level Sustainment Contracts | US Air Force next-generation bomber reapplication cycles generate recurring revenue distinct from original equipment supply. |
Methodological Framework
Defense procurement databases, electromagnetic spectrum warfare doctrine publications, and REACH regulatory filings formed the secondary backbone, supplemented by customs and trade data tracking ferrite and carbonyl iron feedstock flows. Primary interviews with platform prime procurement officers, signature management subcontractor technical directors, and DARPA program managers combined with secondary validation through MIL-STD-461 qualification records and EU Green Deal implementation reports. Bottom-up coating formulation cost modeling and top-down defense budget allocation analysis provided triangulation across the analysis window.
Historical trendline analysis of radar absorbing material procurement cycles anchored the analytical framework, with segmentation dimensions spanning product type, application platform, technology architecture, and end-user contracting authority. CAGRs were derived through regression analysis of defense procurement outlays and platform modernization schedules, incorporating inputs from electromagnetic spectrum warfare doctrine evolution and chemical regulatory phase-out timelines. Frequency-selective surface adoption rates and additive manufacturing deposition pilot program progress served as industry-specific forecast inputs across the modeling period.
Underlying measurement precision varies by segment; radar absorbing materials carry tighter precision given established Pentagon-funded program visibility, while metamaterial architectures exhibit wider uncertainty given pilot program status. Forecasts reflect assumptions regarding AUKUS submarine program schedule adherence, REACH enforcement consistency, and rare earth supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market