
 Japan Electrically Powered Hydraulic Steering Market | 2026-2036
Japan Electrically Powered Hydraulic Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electrically Powered Hydraulic Steering Market Foresight
JIS D 1021 certification for steering system safety is reorganizing supplier eligibility across Japan's automotive tier structure. JTEKT Corporation leverages its integrated manufacturing footprint in Kashihara to dominate electromechanical steering module production. NSK Ltd anchors bearing and precision component supply for hydraulic actuation subsystems. ZF Friedrichshafen AG competes through sensor-based steering calibration technology tailored to Japanese OEM specifications.
Electrically powered hydraulic steering combines an electric motor-driven hydraulic pump with rack-and-pinion or recirculating-ball gearsets to deliver variable assist force based on vehicle speed and driver input. The system operates at hydraulic pressures typically ranging from 70 to 140 bar while drawing electrical power only on demand, eliminating continuous engine-belt parasitic losses. Active steering and variable steering configurations command premium positioning within product type segmentation as Japanese OEMs prioritize lane-keeping precision and autonomous-ready architectures. Passenger vehicle applications absorb the dominant volume share, though commercial vehicle demand for integrated steering systems is expanding fastest as bus and truck fleets retrofit for driver-assist compliance.
METI vehicle energy efficiency regulations and JIS safety standards jointly dictate steering system efficiency thresholds and electromagnetic compatibility requirements for Japanese market access. PMDA and MLIT coordination on autonomous vehicle testing protocols further shapes sensor-based steering technology roadmaps. Stakeholders must monitor how METI's evolving carbon-neutral vehicle standards recalibrate hydraulic-electric hybrid architectures against full electromechanical alternatives.
Market Dynamics
METI's tightening fuel-efficiency mandates are compressing the transition timeline from conventional hydraulic to electrically powered hydraulic architectures, forcing tier-one suppliers to requalify entire module portfolios under revised JIS D 1021 safety protocols.
Growth Catalysts
- Commercial vehicle electrification:Bus and truck fleets across Osaka and Nagoya industrial zones are retrofitting steering systems to meet autonomous-ready compliance standards ahead of MLIT-mandated driver-assist rollouts.
- JIS D 1021 recertification:The reorganized safety framework is disqualifying legacy hydraulic suppliers and consolidating procurement authority among certified electromechanical module producers.
- Dual-motor pump architectures:Variable displacement electric pumps drawing power on demand are eliminating continuous engine-belt parasitic losses that plagued first-generation hydraulic systems.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent-motor designs are compressing margin stability for pump manufacturers.
- Kashihara supply concentration:Electromechanical steering module production clusters heavily around a single Nara Prefecture manufacturing corridor, exposing buyers to localized disruption risk.
- Full electromechanical substitution:Rack-assist electric steering systems are capturing share in compact passenger vehicles where hydraulic-electric hybrid architectures once dominated.
Strategic Opportunities
- Kyushu commercial vehicle corridor:Fukuoka and Kitakyushu logistics hubs remain underpenetrated for integrated steering retrofits relative to Kanto saturation levels.
- Sensor-steering convergence:Lane-keeping precision requirements are creating white space for torque sensor and angle sensor integration within hydraulic-electric hybrid modules.
- METI carbon-neutral vehicle standards:The evolving framework is expected to recalibrate efficiency thresholds in ways that favor hydraulic-electric architectures over pure electromechanical alternatives in heavy commercial applications.
Industry Challenges
- Electromechanical-hydraulic integration engineering:Japanese OEMs report 18-24 month qualification timelines for reconciling electric motor control logic with legacy hydraulic valve bodies.
- JIS electromagnetic compatibility testing:Revised EMC protocols are extending certification cycles and requiring specialized anechoic chamber investments that mid-tier suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electrically Powered Hydraulic Steering Market |
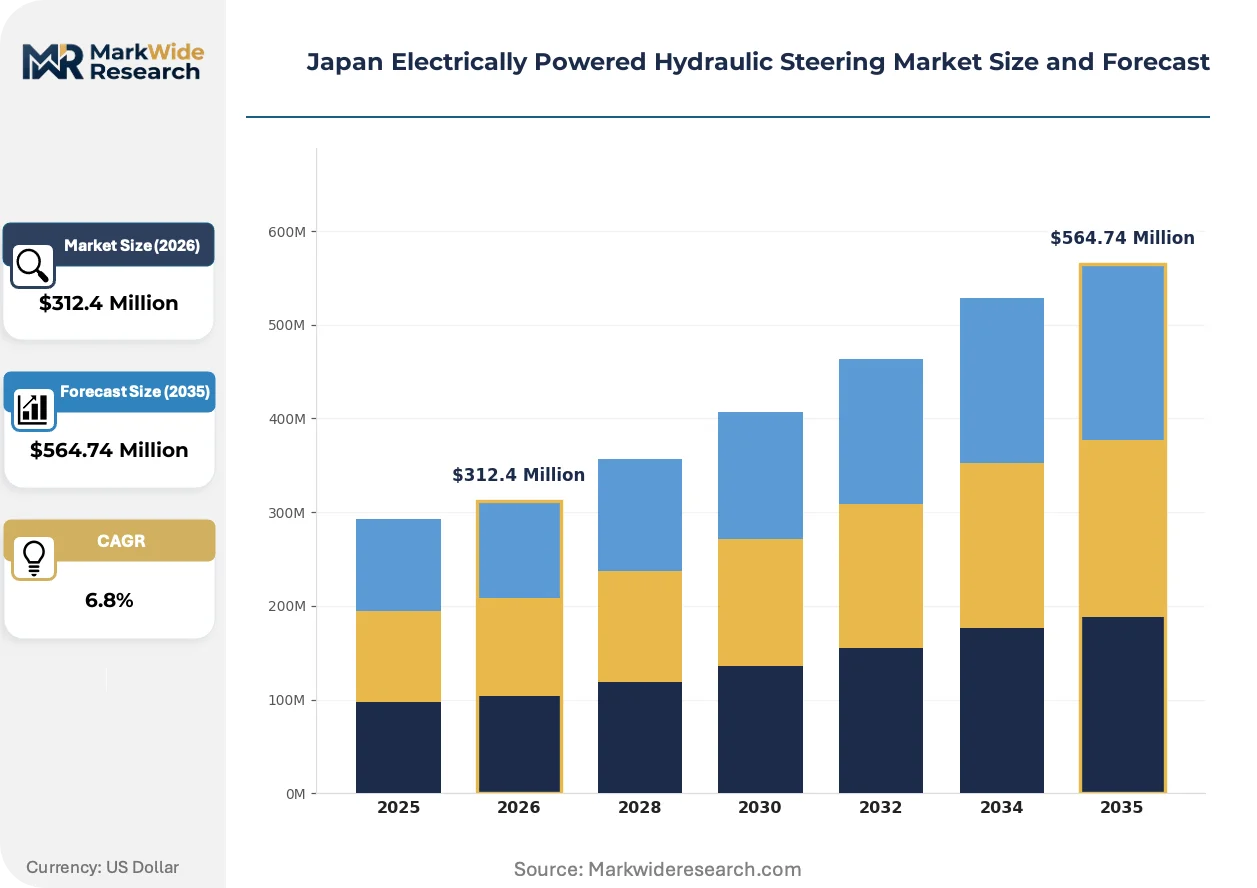
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Steering, Active Steering, Variable Steering, Integrated Steering End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electromechanical, Hydraulic Actuation, Sensor-Based, Control Algorithms Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Specialty Vehicles |
| Companies Covered | JTEKT Corporation, NSK Ltd, Nexteer Automotive Group Ltd, ZF Friedrichshafen AG, Robert Bosch GmbH, Showa Group, Hitachi Astemo Ltd, KYB Corporation, Nidec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electrically Powered Hydraulic Steering Market Shifts & Advancements
Steering system architectures are fragmenting along efficiency-performance tradeoffs as Japanese OEMs bifurcate procurement between autonomous-ready precision modules and cost-optimized legacy replacements.
Modular electric pump units with integrated motor-inverter assemblies are decomposing the traditional separation between hydraulic power generation and electronic control. Tier-one suppliers in Aichi Prefecture are adopting these consolidated subsystems at accelerated pace for 2027 platform launches. The technology is decomposing established tier structures by allowing electronics specialists to capture value previously held by hydraulic component manufacturers.
METI's vehicle energy efficiency regulations are mandating real-world fuel consumption testing that exposes steering system parasitic losses in ways laboratory protocols previously masked. OEM procurement teams are now specifying maximum standby power draw thresholds in supplier contracts. Heavy commercial vehicle platforms face the steepest redesign pressure as their higher hydraulic flow rates amplify efficiency penalties under the new testing regime.
Fleet procurement managers at Tokyo and Yokohama logistics operators are consolidating steering system sourcing through vehicle-as-a-service leasing structures rather than discrete component purchases. This channel shift is transferring lifecycle cost accountability from end-users to OEM captive finance arms. The restructuring is most visible in bus fleet renewals where municipal operators demand guaranteed availability clauses that bundle steering maintenance into per-kilometer service fees.
Japan Electrically Powered Hydraulic Steering Market Segmentation
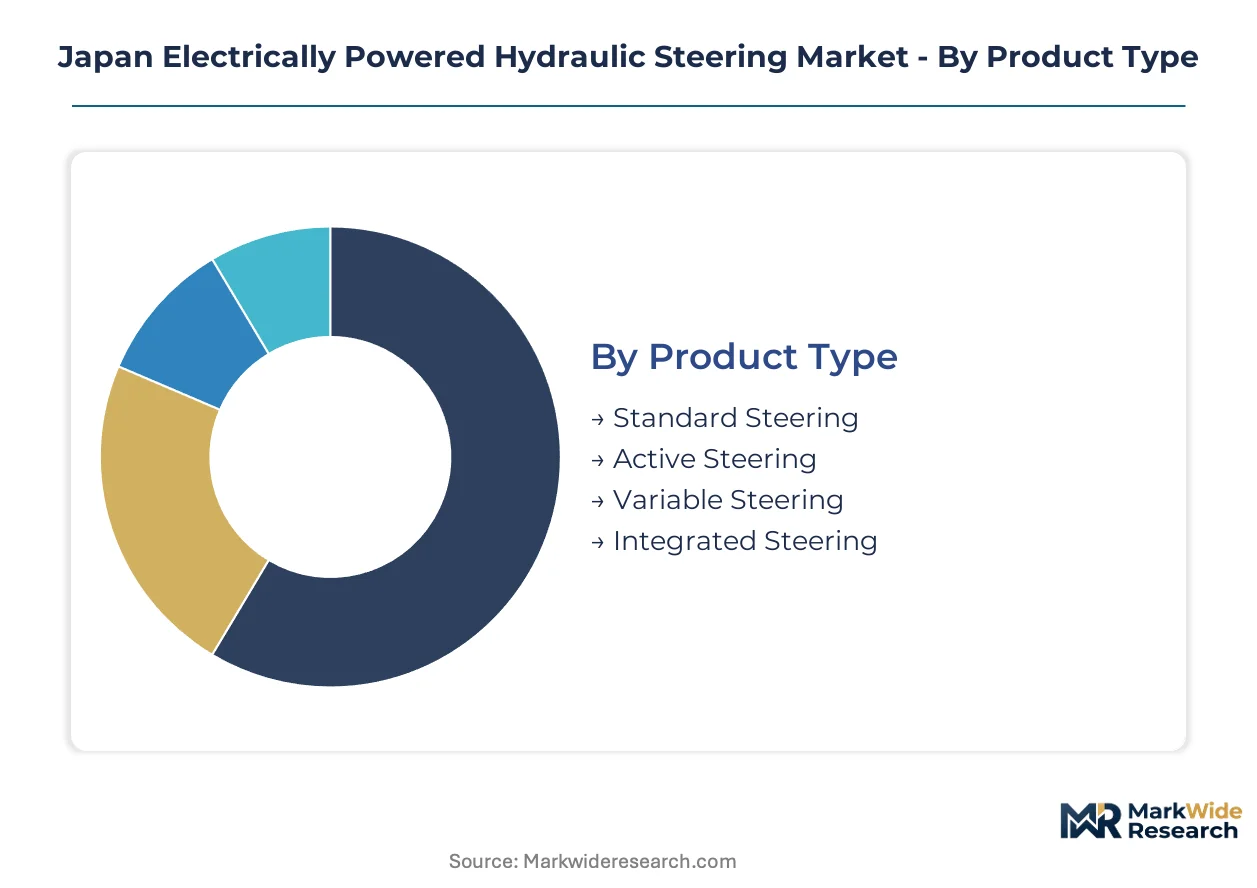
Japanese OEM procurement strategies fragment steering system demand across four intersecting dimensions. Product architecture choices determine fuel-efficiency compliance margins, while technology selection separates autonomous-ready platforms from legacy replacements.
Product Type:
Full electromechanical steering systems are displacing hydraulic-electric hybrids fastest in compact passenger vehicles, forcing suppliers to defend their positioning across each architecture tier.
- Standard Steering:Conventional rack-and-pinion or recirculating-ball configurations with fixed assist curves dominate replacement demand in aging vehicle fleets across rural prefectures. Cost-sensitive procurement at independent repair networks in Hokkaido and Tohoku sustains this category despite efficiency disadvantages.
- Active Steering:Variable ratio systems that modulate steering response based on vehicle speed and yaw rate command premium positioning in luxury sedan platforms from Tokyo-based OEMs. Kanto corridor assembly plants specify these modules for lane-keeping precision requirements ahead of MLIT-mandated driver-assist rollouts.
- Variable Steering:Speed-sensitive assist systems adjust hydraulic pressure through electronically controlled valves, bridging cost and performance tiers for mid-market passenger vehicles.
- Integrated Steering:Combined motor-pump-inverter assemblies consolidate previously separate subsystems, attracting commercial vehicle retrofits in Osaka and Nagoya logistics hubs.
Standard steering retains volume leadership; integrated steering holds the steepest expansion curve.
End User:
Procurement authority concentrates differently across the Japanese automotive tier structure depending on platform complexity and certification requirements.
- OEMs:Vehicle manufacturers in the Kanto industrial corridor wield direct sourcing power for electromechanical steering modules on new platforms. Their engineering teams specify JIS D 1021 compliance thresholds and EMC testing protocols that disqualify uncertified suppliers.
- Tier-1 Suppliers:Integrated module producers like JTEKT Corporation and NSK Ltd capture value through subsystem consolidation, supplying complete steering columns to multiple OEMs from Kashihara manufacturing clusters.
- Aftermarket Providers:Independent distributors serve fleet maintenance operations and collision repair networks, particularly in Kyushu commercial vehicle corridors where retrofit demand outpaces OEM coverage.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source steering systems through specification rather than design, relying on tier-1 technical integration.
OEMs dominate new platform procurement; aftermarket providers are gaining share fastest in commercial retrofit channels.
Technology:
Control sophistication determines which suppliers qualify for autonomous-ready platform business versus commodity replacement markets.
- Electromechanical:Motor-driven rack or column assist systems eliminate hydraulic circuits entirely, capturing compact vehicle segments where efficiency metrics outweigh load-bearing requirements. METI fuel-efficiency testing protocols favor these architectures in passenger applications.
- Hydraulic Actuation:Traditional pump-and-valve systems with electric motor-driven pumps retain dominance in heavy commercial vehicles where steering loads exceed electromechanical torque limits. Nara Prefecture suppliers anchor production of these high-pressure subsystems.
- Sensor-Based:Torque and angle sensing modules enable closed-loop control for lane-keeping and parking assist functions, representing the critical integration point for autonomous vehicle architectures.
- Control Algorithms:Embedded software for variable assist mapping and diagnostic protocols determines electromagnetic compatibility compliance under revised JIS standards.
Hydraulic actuation retains installed base dominance; sensor-based technology is climbing the fastest toward platform-critical status.
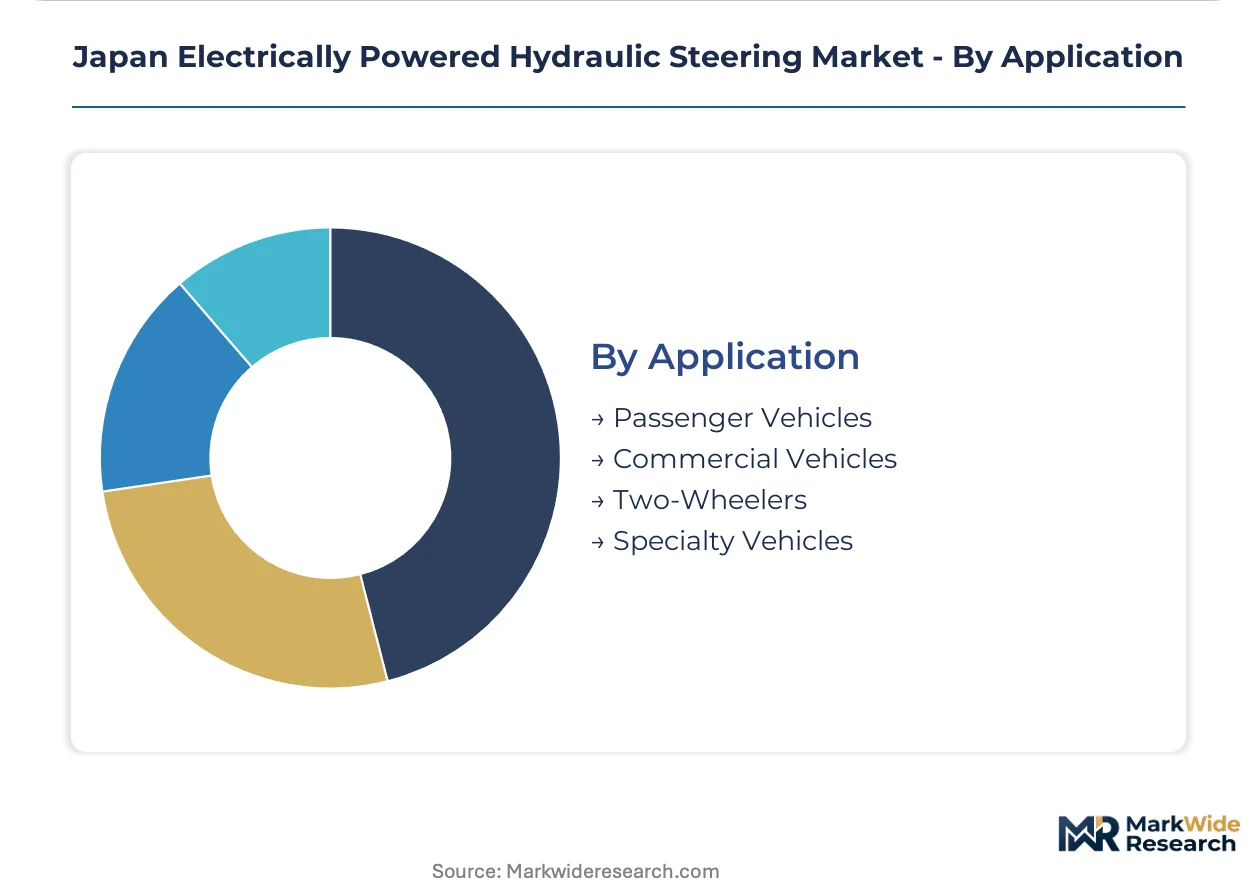
Application:
Vehicle weight class and duty cycle dictate the economic boundary between hydraulic-electric hybrid and full electromechanical architectures.
- Passenger Vehicles:Sedans, hatchbacks, and SUVs across the Tokyo-Yokohama metropolitan corridor absorb the dominant volume share, with electromechanical systems displacing hydraulic-electric hybrids in segments below two tons gross vehicle weight.
- Commercial Vehicles:Buses and trucks face the steepest redesign pressure under METI efficiency mandates, with dual-motor pump architectures eliminating parasitic losses in urban delivery fleets across Osaka and Nagoya industrial zones.
- Two-Wheelers:Motorcycles and scooters represent a marginal addressable market for electrically powered hydraulic steering due to weight and packaging constraints favoring purely mechanical or electromechanical alternatives.
- Specialty Vehicles:Construction equipment, agricultural machinery, and municipal service vehicles require customized high-torque hydraulic systems with limited standardization potential.
Passenger vehicles retain volume leadership; commercial vehicles hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers in Japan's logistics corridors drive steering system demand through vehicle-as-a-service leasing structures. Their sourcing decisions concentrate in industrial manufacturing clusters where METI efficiency mandates and JIS safety recertification reshape supplier eligibility.
Kanto/Tokyo
Passenger vehicle OEMs in the Tokyo-Yokohama metropolitan corridor absorb the dominant volume share of electromechanical steering modules. METI vehicle energy standards force platform redesigns that favor sensor-based architectures for lane-keeping precision. Kashihara manufacturing clusters in adjacent Nara Prefecture anchor integrated module production for Kanto assembly plants.
Kansai/Osaka
Commercial vehicle retrofits in Osaka and Nagoya logistics hubs represent the fastest-expanding demand segment for dual-motor pump architectures. MLIT-mandated driver-assist rollouts compress fleet upgrade timelines for urban delivery operators. Bus fleet renewals through municipal vehicle-as-a-service contracts bundle steering maintenance into per-kilometer service fees.
Chubu/Nagoya
Toyota-dominated supply chains in Aichi Prefecture accelerate adoption of modular electric pump units with integrated motor-inverter assemblies. Tier-one suppliers target 2027 platform launches with consolidated subsystems that decompose traditional hydraulic-electronic boundaries. JIS D 1021 recertification disqualifies legacy suppliers from new platform procurement.
Kyushu
Fukuoka and Kitakyushu logistics corridors remain underpenetrated for integrated steering retrofits relative to Kanto saturation levels. Commercial fleet operators face delayed compliance timelines but accelerating METI pressure for autonomous-ready architectures. Aftermarket providers gain share fastest in this corridor where OEM coverage gaps persist.
Hokkaido and Tohoku
Rural prefectures sustain replacement demand for standard steering configurations through cost-sensitive independent repair networks. Aging vehicle fleets and limited autonomous vehicle deployment delay electromechanical displacement. JIS safety recertification penetrates slowly here, preserving legacy hydraulic supplier participation longer than in metropolitan corridors.
Japan Electrically Powered Hydraulic Steering Market Competitive Landscape
Player mix skews toward integrated module producers with captive manufacturing footprints and bearing specialists supplying precision components for hydraulic actuation. Market structure consolidates around tier-one subsystem suppliers capable of JIS D 1021 certification and electromagnetic compatibility testing. Two strategic archetypes dominate: consolidated electromechanical module manufacturers and precision component specialists. Competitive moves center on qualification timeline acceleration and sensor-steering convergence technology licensing.
Among Japan-based integrated manufacturers, JTEKT Corporation and NSK Ltd exemplify the tier-one consolidation archetype, with the former representing vertically integrated module production and the latter anchoring bearing supply for hydraulic subsystems. ZF Friedrichshafen AG occupies a position among foreign technology licensors competing through sensor-based calibration systems. These three companies illustrate how supplier eligibility reorganizes around certification capability and manufacturing footprint control.
| Leading Market Players |
|---|
| JTEKT Corporation |
| NSK Ltd |
| Nexteer Automotive Group Ltd |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Showa Group |
| Hitachi Astemo Ltd |
| KYB Corporation |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Kanto-based OEMs and Kashihara module producers lock in rare-earth magnet supply access while anchoring price visibility across multi-year procurement cycles. These agreements insulate tier-one suppliers from neodymium spot volatility while committing buyers to minimum volume thresholds that shape inventory positioning throughout the Nara manufacturing corridor.
Pricing Analysis
Cost-plus contracts with rare-earth price indexation dominate procurement between Japanese OEMs and electromechanical steering module suppliers. Three-tier pricing structure across JIS D 1021-certified premium, standard compliance, and legacy replacement tiers reflects certification investment differentials. Pricing pressure stems from full electromechanical substitution in compact passenger segments where hydraulic-electric hybrids face displacement. Aftermarket providers in rural prefectures exhibit highest price sensitivity, while Tokyo-based luxury OEMs prioritize lane-keeping precision over unit cost.
Supply Chain Analysis
Just-in-time inventory protocols prevail across Kanto assembly plants, though strategic stockpiling of rare-earth magnets and precision bearings buffers against Kashihara concentration risk. Supply draws from Japan for integrated modules, China for processed rare-earth alloys, and Germany for sensor calibration systems. Neodymium-dysprosium price volatility constitutes the dominant supply chain risk. Distribution runs through OEM captive logistics networks for new platforms and independent aftermarket channels for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's electrically powered hydraulic steering market sits in early-cycle expansion as commercial vehicle electrification accelerates fleet retrofit timelines under METI efficiency mandates. Penetration of integrated steering modules in bus and truck applications remains below saturation levels across major industrial corridors.
For Market Incumbents: Secure JIS D 1021 recertification ahead of 2027 platform launches to disqualify uncertified competitors from OEM procurement. Expand sensor-steering convergence R&D to defend against full electromechanical substitution in passenger segments. Backward integration into rare-earth magnet supply through offtake partnerships mitigates margin compression from neodymium price swings.
For New Entrants and Emerging Players: Lead with aftermarket coverage in Kyushu logistics corridors where OEM service networks remain sparse and municipal fleet operators demand rapid retrofit turnaround. Target integrated steering modules for commercial vehicle applications where hydraulic-electric architectures retain torque advantages over pure electromechanical alternatives. Partner with Fukuoka-based distributors to establish service presence ahead of MLIT-mandated compliance deadlines.
For Investors and Strategic Acquirers: Capital is best deployed toward tier-one electromechanical module producers with captive Kashihara manufacturing footprints and established JIS certification capabilities. Long-term viability hinges on positioning for heavy commercial vehicle platforms where efficiency regulations favor hydraulic-electric hybrid persistence. Watch METI carbon-neutral vehicle standard revisions as the critical inflection signal for technology roadmap recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS D 1021 Certification Investment | Establishes supplier eligibility for Tokyo-based OEM platform procurement ahead of regulatory deadlines. |
| Dual-Motor Pump Architecture Development | Eliminates parasitic losses that METI real-world testing protocols now expose and penalize. |
| Kyushu Distribution Partnership | Captures commercial retrofit demand in underpenetrated logistics corridors before OEM coverage expands. |
| Rare-Earth Supply Agreement | Secures magnet input price stability against dysprosium volatility compressing pump manufacturer margins. |
| Sensor-Steering Integration R&D | Positions modules for autonomous-ready lane-keeping requirements in MLIT-mandated driver-assist rollouts. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and METI regulatory officials converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against JIS standard documentation, vehicle production databases, and customs records tracking rare-earth alloy imports. Bottom-up volume modeling triangulated against top-down market sizing across product architecture and application segments.
Segmentation dimensions modeled include steering system architecture, vehicle weight class, technology sophistication tier, and regional production cluster penetration. CAGRs were derived through regression analysis of historical platform adoption curves and forward projection of regulatory compliance timelines. Forecast inputs incorporated METI efficiency mandate enforcement schedules and MLIT autonomous vehicle testing protocol evolution.
Forecasts assume regulatory continuity in METI vehicle energy standards and JIS D 1021 certification protocols; material policy shifts would require re-modeling of supplier qualification timelines and technology substitution curves. Revision becomes warranted when full electromechanical steering torque limits expand to capture heavy commercial vehicle applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Fluids Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Camless Engine Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Tuning Box Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Brazil Automotive Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Powertrain Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market