
 Europe Electro Hydraulic Power Steering Market | 2026-2036
Europe Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electro Hydraulic Power Steering Market Foresight
CE marking under the EU Machinery Directive is reorganizing competitive access across the Europe Electro Hydraulic Power Steering Market. ZF Friedrichshafen AG leverages its integrated manufacturing footprint in Germany to dominate rack-type system production. Robert Bosch GmbH sustains technology leadership through precision sensor integration for closed-loop architectures. JTEKT Corporation anchors its European position via specialized column-type supply contracts with German OEMs.
Electro hydraulic power steering combines hydraulic actuation with electric motor-driven pumps to deliver variable steering assistance while reducing parasitic engine load. Systems typically operate at hydraulic pressures between 70 and 140 bar with brushless DC motors rated 200–600 watts, enabling fuel efficiency gains over conventional hydraulic setups. Rack type configurations command the largest installed base across passenger vehicle applications, while digital control technology captures the fastest expansion as OEMs mandate CAN-bus integrated steering modules. Pinion type systems occupy a mature niche in compact vehicle segments where packaging constraints limit rack unit dimensions.
The EU F-Gas Regulation and REACH compliance through ECHA constrain refrigerant and lubricant chemistries used in manufacturing processes, directly affecting supplier qualification timelines. Germany's KBA enforces type-approval protocols that gate market entry for non-EU component producers. Stakeholders must monitor evolving EU AI Act provisions for autonomous steering algorithms and assess backward integration into electric motor production as hybrid architectures gain share.
Market Dynamics
EU F-Gas Regulation phase-down mandates are compressing refrigerant and lubricant options available to electro hydraulic power steering manufacturers, forcing reformulation of hydraulic fluids and retooling of pump sealing architectures across German production lines.
Growth Catalysts
- Light commercial vehicle fleet electrification:German logistics operators are retrofitting existing chassis with electro hydraulic systems to meet municipal low-emission zone requirements without full powertrain replacement.
- CE marking harmonization:Machinery Directive compliance is consolidating supplier qualification standards, reducing fragmentation in cross-border component sourcing across EU member states.
- Brushless DC motor cost curves:Magnet material processing improvements are lowering pump motor unit economics, accelerating displacement of engine-driven hydraulic pumps in compact vehicle segments.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependency on Chinese processing infrastructure creates input cost volatility for European motor assemblers.
- REACH substance restrictions:ECHA authorization requirements for specific hydraulic fluid additives are extending supplier requalification timelines by 18-24 months.
- Full electric steering substitution:Steer-by-wire architectures in premium battery electric vehicles are eliminating hydraulic intermediate stages entirely.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:OEMs are qualifying secondary supply bases in Central Europe to reduce single-country concentration risk.
- EU AI Act algorithmic steering provisions:Autonomous vehicle mandates will require certifiable steering control modules, creating retrofit demand for closed-loop sensor integration.
- CAN-bus integrated module standardization:Convergence of digital control protocols with hydraulic actuation is opening aftermarket diagnostic and calibration service revenue streams.
Industry Challenges
- Embedded software validation:ISO 26262 functional safety certification for steering control firmware requires specialized automotive safety engineer talent pools that remain scarce in Eastern European engineering markets.
- Legacy hydraulic system interoperability:OEMs maintaining mixed fleets face integration complexity when mating electro hydraulic units with existing chassis sensor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electro Hydraulic Power Steering Market |
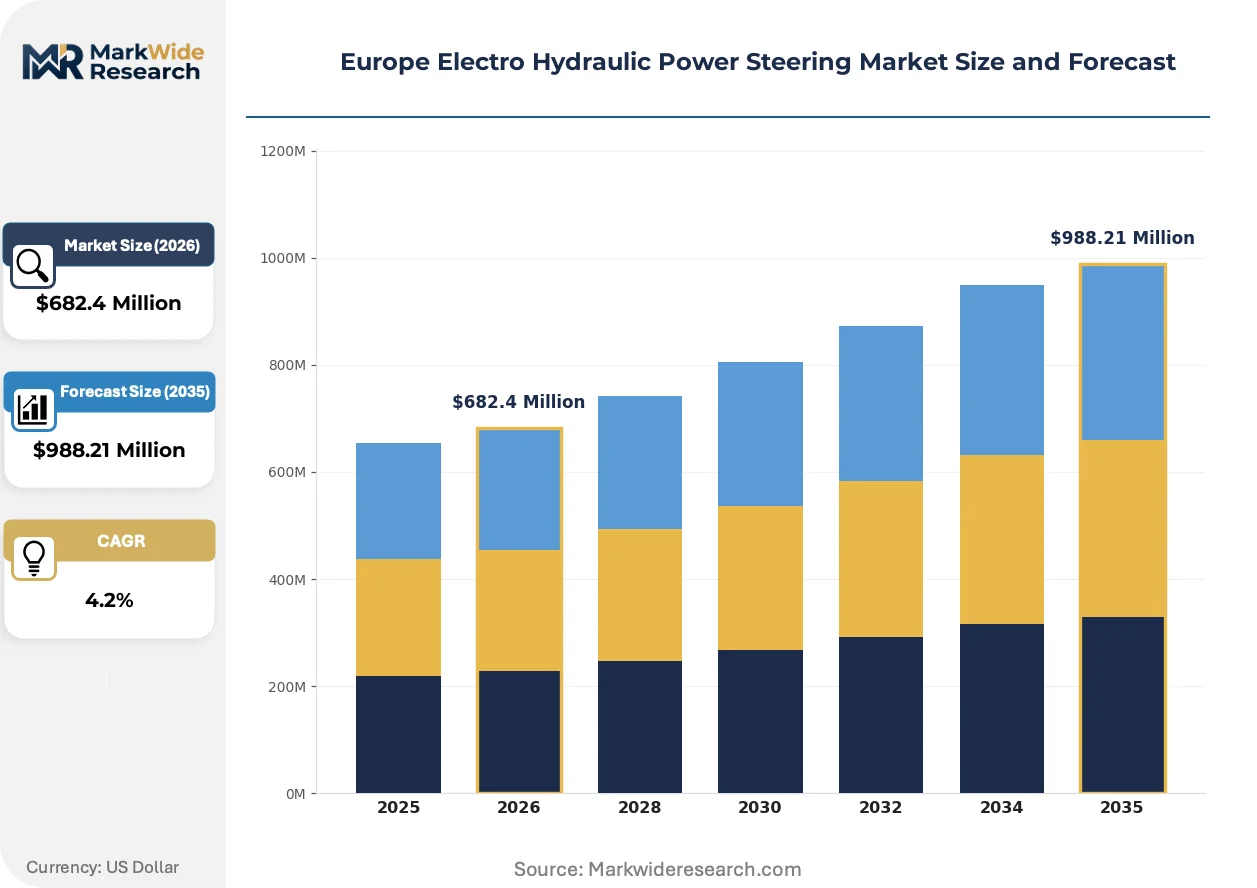
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $988.21 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Type, Rack Type, Pinion Type, Electric Rack Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Sports Cars End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Technology: Closed Loop, Open Loop, Hybrid System, Digital Control |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group, ZF Friedrichshafen AG, Robert Bosch GmbH, NSK Ltd, Denso Corporation, Mitsubishi Electric Corporation, Hitachi Automotive Systems, GKN PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electro Hydraulic Power Steering Market Shifts & Advancements
Digital control architectures are displacing analog hydraulic circuits across European passenger vehicle platforms, with real-time torque feedback algorithms now standard in rack-type system specifications. This shift is compressing development cycles and redefining supplier competency requirements.
Brushless DC pump motor technology is bifurcating the installed base. Permanent magnet synchronous designs deliver variable flow rates with 15-20% efficiency gains over brushed alternatives. German OEMs are adopting these units for mid-range platforms, while premium segments migrate toward full electric elimination of hydraulic stages. The technology is bifurcating supplier tiers into motor-integrated system houses versus pure hydraulic component vendors.
F-Gas Regulation amendments through 2024 are restricting hydrofluorocarbon use in manufacturing process cooling. Component producers must substitute alternative refrigerants in heat-treatment operations or absorb capital costs for closed-loop recovery systems. Smaller Italian and Spanish tier-two suppliers face disproportionate compliance burden relative to integrated German manufacturers with captive utility infrastructure.
Fleet procurement departments are consolidating steering system contracts under multi-year platform agreements rather than model-by-model sourcing. Large German leasing operators now specify electro hydraulic content as mandatory across light commercial vehicle tenders, compressing supplier negotiation cycles and favoring vertically integrated producers with volume scaling capacity. This concentration is most visible in Baden-Württemberg logistics hub procurement patterns.
Europe Electro Hydraulic Power Steering Market Segmentation
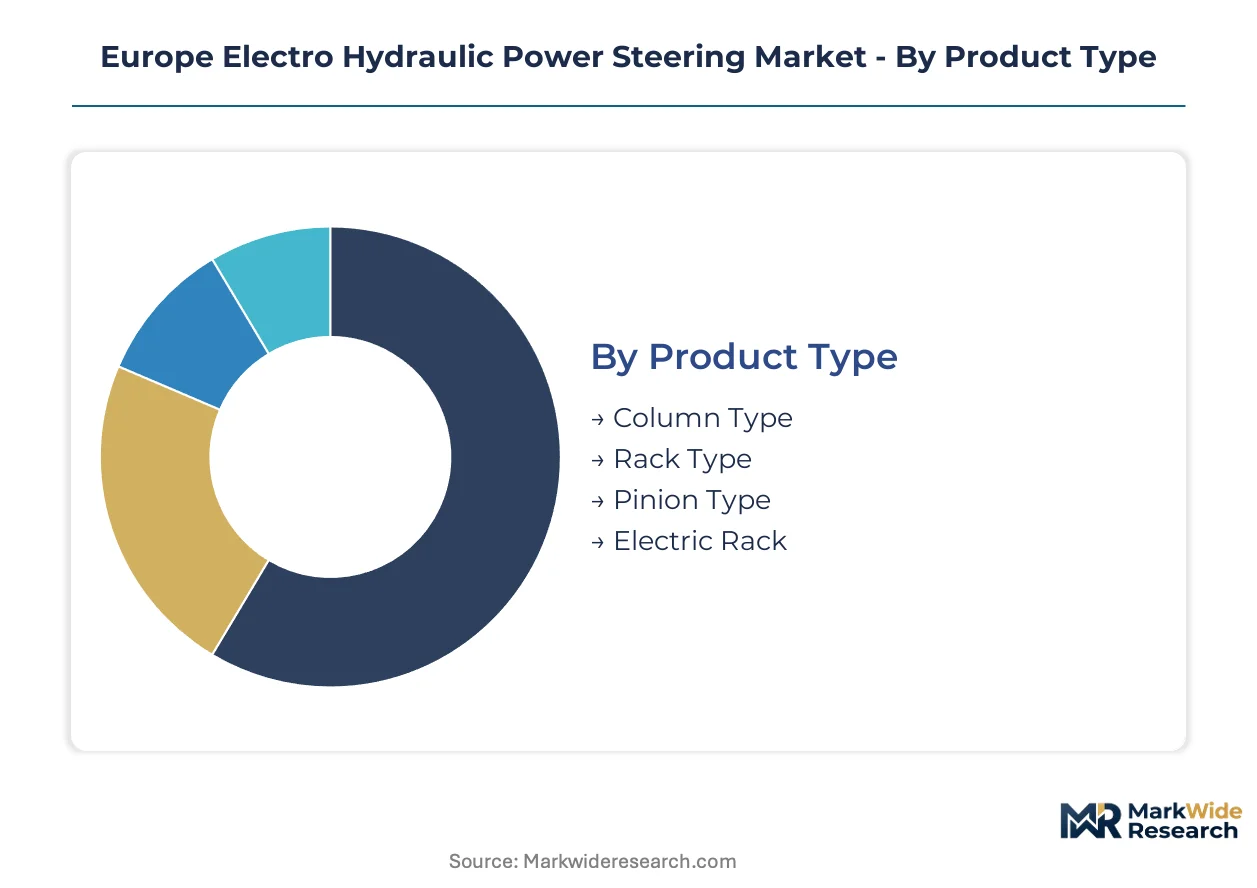
Segmentation in the Europe Electro Hydraulic Power Steering Market reveals how regulatory pressure and application requirements reshape supplier economics. CE marking under the EU Machinery Directive and KBA type-approval protocols create divergent compliance burdens across product architectures, forcing tier-one suppliers to specialize.
Product Type:
REACH substance restrictions and F-Gas Regulation phase-downs impose distinct material and sealing requirements on each hydraulic architecture, altering supplier qualification timelines.
- Rack Type:Integrates the hydraulic cylinder directly into the steering rack assembly, enabling precise torque vectoring across the axle line. German OEMs in Stuttgart and Wolfsburg specify these units for mid-range passenger platforms where packaging permits full rack integration. KBA enforcement of ISO 26262 functional safety for steering firmware extends validation cycles for rack-integrated control modules.
- Column Type:Mounts the assist mechanism on the steering column, preserving chassis space for compact vehicle architectures. JTEKT Corporation maintains specialized supply contracts with German OEMs for column-type systems where firewall intrusion limits rack unit dimensions. ECHA authorization requirements for hydraulic fluid additives disproportionately affect column-type producers sourcing from smaller Italian and Spanish tier-two suppliers.
- Pinion Type:Positions the hydraulic assist at the steering pinion, occupying a mature niche in compact segments. Packaging constraints in A-segment and B-segment vehicles sustain residual demand despite efficiency disadvantages.
- Electric Rack:Represents the transitional architecture toward full electric elimination of hydraulic stages. Premium battery electric vehicle platforms in Munich's automotive cluster are migrating production capacity toward these units.
Rack type handles the majority of throughput; electric rack is the fastest mover on share.
Application:
Cost tier differentiation separates mass-market specifications from precision-engineered performance segments, with hydraulic fluid formulation and sensor density driving unit economics.
- Passenger Vehicles:Constitutes the volume base across C-segment and D-segment platforms, where brushless DC pump motors at 200-400 watts displace engine-driven hydraulic pumps. Municipal low-emission zone requirements in German urban centers accelerate retrofit demand for existing fleets.
- Commercial Vehicles:Light commercial vehicle fleets across Baden-Württemberg logistics hubs mandate electro hydraulic content in multi-year platform tenders. German logistics operators retrofit existing chassis to meet emissions standards without full powertrain replacement.
- Luxury Cars:Premium segments are migrating toward steer-by-wire architectures that eliminate hydraulic intermediate stages entirely. Remaining electro hydraulic installations emphasize closed-loop sensor integration for autonomous steering preparation.
- Sports Cars:Prioritizes steering feel and road feedback over efficiency optimization. Analog hydraulic circuits persist in this segment where digital control architectures compromise driver engagement.
Passenger vehicles dominate installed base; commercial vehicles are expanding most quickly as fleet procurement consolidates.
End User:
Customer type determines contract structure, with OEM platform agreements compressing negotiation cycles relative to fragmented aftermarket channels.
- OEMs:German manufacturers in Stuttgart, Wolfsburg, and Munich consolidate steering system procurement under multi-year platform agreements. ZF Friedrichshafen AG leverages integrated manufacturing footprints to dominate direct supply relationships.
- Fleet Operators:Large German leasing operators now specify electro hydraulic content as mandatory across light commercial vehicle tenders. Volume scaling requirements favor vertically integrated producers with captive motor production.
- Aftermarket Providers:Service revenue concentrates on diagnostic and calibration for CAN-bus integrated modules. Technical complexity limits viable participants to specialists with ISO 26262 safety engineer credentials.
- Dealerships:Warranty service networks handle manufacturer-mandated recall and retrofit campaigns for F-Gas Regulation compliance.
OEMs command the majority of contract value; fleet operators are gaining procurement leverage fastest.
Technology:
Maturity curves separate established open-loop architectures from emerging digital control platforms requiring embedded software validation.
- Digital Control:Real-time torque feedback algorithms now standard in rack-type specifications compress development cycles. CAN-bus integration opens aftermarket diagnostic revenue streams for certified service providers.
- Closed Loop:Precision sensor integration enables variable assistance mapping based on vehicle speed and steering angle. Robert Bosch GmbH sustains technology leadership through specialized sensor supply for these architectures.
- Hybrid System:Combines electric motor-driven pumps with retained hydraulic actuation for transitional efficiency gains. Brushless DC permanent magnet synchronous designs deliver 15-20% efficiency improvements over brushed alternatives.
- Open Loop:Fixed displacement pumps without feedback sensors persist in cost-optimized compact vehicle segments. REACH substance restrictions for hydraulic fluid additives threaten long-term viability.
Digital control is climbing the fastest on technology share; open loop retains residual volume in price-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down mandates are compressing refrigerant options and reshaping supplier qualification timelines across European production corridors. Germany's KBA type-approval protocols gate market entry for component producers targeting automotive belt clusters.
Germany
Light commercial vehicle fleet operators in Baden-Württemberg logistics hubs mandate electro hydraulic content in multi-year platform tenders. KBA enforces ISO 26262 functional safety certification for steering control firmware. Stuttgart, Wolfsburg, and Munich anchor production gravity for rack-type and electric rack architectures serving mid-range passenger and premium battery electric platforms.
France
Passenger vehicle OEMs specify brushless DC pump motors at 200-400 watts for C-segment and D-segment platforms. ANSM and CNIL oversight intersects with CE marking under the EU Machinery Directive for cross-border component sourcing. The Île-de-France automotive cluster concentrates procurement consolidation under vertically integrated supply agreements.
Italy
Compact vehicle segments sustain residual demand for pinion-type systems where packaging constraints limit rack unit dimensions. ECHA authorization requirements for hydraulic fluid additives disproportionately affect tier-two suppliers lacking captive utility infrastructure. Lombardy-based component producers face reformulation costs for pump sealing architectures.
Spain
Aftermarket diagnostic and calibration services for CAN-bus integrated modules concentrate revenue among ISO 26262-certified specialists. REACH substance restrictions extend supplier requalification timelines by 18-24 months. Madrid and Barcelona logistics corridors channel retrofit demand for municipal low-emission zone compliance.
Poland
OEMs qualify secondary supply bases to reduce single-country concentration risk in Central European manufacturing expansion. CE marking harmonization consolidates cross-border component qualification standards. Warsaw and Kraków industrial zones attract motor-integrated system houses seeking proximity to German automotive belt demand.
Europe Electro Hydraulic Power Steering Market Competitive Landscape
Player mix skews toward integrated German manufacturing conglomerates with captive motor production and specialized Japanese column-type suppliers. Market structure concentrates around tier-one system houses with backward integration into electric motor production and tier-two hydraulic component vendors facing REACH compliance burdens. Two strategic archetypes dominate: vertically integrated producers with volume scaling capacity and sensor-integrated technology specialists. Competitive moves center on multi-year platform agreement consolidation and secondary supply base qualification in Central Europe.
Among Germany-based integrated manufacturers, ZF Friedrichshafen AG and Robert Bosch GmbH exemplify divergent positioning archetypes. ZF Friedrichshafen AG occupies a position representing rack-type system consolidation through integrated manufacturing footprints. Robert Bosch GmbH anchors the sensor-integrated tier, exemplifying precision component supply for closed-loop architectures. JTEKT Corporation sits within the specialized column-type segment, representing Japanese supply contract positioning with German OEMs.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| NSK Ltd |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Hitachi Automotive Systems |
| GKN PLC |
| Others |
Supply & Pricing Matrix
CE marking under the EU Machinery Directive gates supplier qualification timelines while simultaneously stratifying price tiers across the Europe Electro Hydraulic Power Steering Market, compressing margins for non-certified tier-two producers while amplifying pricing power for integrated German system houses with captive KBA type-approval protocols.
Pricing Analysis
Certification level (CE/KBA-grade) creates the primary spread across unit economics, with ISO 26262 functional safety validation commanding premium positioning for rack-type integrated modules. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and retrofit urgency. Cost compression in compact vehicle segments is intensifying because brushless DC motor cost curves are displacing legacy engine-driven pumps. Fleet operators consolidating multi-year platform tenders exhibit lowest price sensitivity, while Spanish and Italian tier-two suppliers face acute margin pressure from REACH requalification burdens.
Supply Chain Analysis
Germany anchors rack-type and electric rack production for Stuttgart, Wolfsburg, and Munich OEM clusters, while Poland and Czech Republic attract secondary motor-integrated system houses seeking proximity to demand. Neodymium and dysprosium magnet processing draws from Chinese infrastructure, creating input cost volatility for European motor assemblers. Single-source vulnerability concentrates in rare earth magnet supply channels. Distribution runs through tier-one system houses with backward integration into electric motor production, channeling components to OEM platform engineering teams and fleet procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across Baden-Württemberg logistics hubs is shifting buyer power toward volume-scaled operators, fragmenting supplier negotiation leverage and compressing contract cycles for non-integrated component vendors.
For Market Incumbents: Compound defensive positioning by securing multi-year platform agreements with German OEMs before secondary supply bases in Central Europe mature, while accelerating captive brushless DC motor production to offset rare earth magnet cost volatility from Chinese processing concentration.
For New Entrants and Emerging Players: CE marking fast-track qualification for column-type systems offers the most penetrable entry vector, targeting JTEKT-dominated supply relationships with German OEMs where firewall packaging constraints limit rack unit adoption. Aftermarket diagnostic services for CAN-bus integrated modules provide immediate revenue without full platform integration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-integrated closed-loop architectures as ISO 26262 certification requirements deepen engineering talent scarcity. Acquisition targets should prioritize tier-two hydraulic specialists with ECHA-compliant fluid formulations and existing KBA relationships. The signal to watch is F-Gas Regulation amendment timing affecting heat-treatment capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Qualification | Compresses supplier validation timelines for column-type system entry against entrenched Japanese competitors. |
| Backward Integration into Motor Production | Captures brushless DC pump margins and insulates against neodymium supply volatility from Chinese processors. |
| Secondary Supply Base Qualification | Reduces single-country concentration risk as Polish and Czech manufacturing zones attract OEM sourcing diversification. |
| CAN-Bus Module Standardization | Opens aftermarket diagnostic revenue streams for certified service providers with ISO 26262 safety credentials. |
| Hydraulic Fluid Reformulation | Addresses REACH substance restrictions that extend tier-two supplier requalification timelines by 18-24 months. |
Research Methodology
The analysis maps rack-type, column-type, pinion-type, and electric rack architectures, each validated through procurement directors at German OEMs, fleet operators in Baden-Württemberg logistics hubs, tier-one system house engineering leads, and aftermarket diagnostic specialists. Primary fieldwork combined with secondary validation from KBA type-approval databases, ECHA substance restriction filings, EU F-Gas Regulation amendment tracking, and vehicle production data from German automotive belt clusters. Bottom-up unit economics triangulated against top-down market sizing across component and system-level revenue streams.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit vehicle registration data, tier-one supplier SEC disclosures, and customs records for brushless DC motor trade flows. Segmentation dimensions modeled across product type, application, end user, and technology maturity, with propulsion architecture and regional production cluster as automotive-specific overlays. CAGRs derived from installed base evolution and replacement cycle analysis, incorporating fleet electrification retrofit demand and steer-by-wire substitution risk as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover REACH compliance timelines, F-Gas phase-down implementation pace, and rare earth magnet supply continuity, with deviation risk concentrated in regulatory amendment timing and Chinese export policy shifts. Recalibration cycles align with material shifts in EU AI Act autonomous steering provisions and KBA functional safety enforcement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Transmission Repair Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Automotive Power Modules Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Engine Starter Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Carburetor Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Tuning Box Market