
 Global Pulmonary Drugs Market | 2026-2036
Global Pulmonary Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulmonary Drugs Market Foresight
India is tilting toward contract manufacturing scale-up for active pharmaceutical ingredients used in respiratory formulations. AstraZeneca leverages its biologics pipeline to sustain leadership in severe asthma monoclonal antibodies. Boehringer Ingelheim anchors its position through inhaled combination therapies for chronic obstructive pulmonary disease. GlaxoSmithKline competes via deep primary care channel control across Europe and emerging Asian markets.
Pulmonary drugs comprise systemically or locally acting pharmaceutical agents formulated for delivery to the bronchial tree, alveolar tissue, or pulmonary vasculature, typically administered via pressurized metered-dose inhalers, dry powder devices, or nebulized solutions achieving particle sizes of one to five micrometers for optimal lung deposition. These agents modulate airway smooth muscle tone, inflammatory mediator release, mucociliary clearance, or vascular remodeling to treat obstructive, restrictive, or vascular lung diseases. Combination drugs dominate value capture by merging long-acting beta-agonists with inhaled corticosteroids in single-device platforms that improve adherence and command premium positioning. Dry powder inhalers represent the fastest-growing formulation segment as device engineering eliminates propellant dependencies and enables breath-actuated dosing with improved lung targeting.
The FDA, EMA, and Japan's PMDA enforce divergent bioequivalence standards for inhaled generics that shape generic substitution rates and market access timelines across jurisdictions. The EU F-Gas Regulation and FDA environmental assessments are forcing propellant transitions in pressurized inhalers toward lower-global-warming-potential alternatives, altering formulation chemistry and device redesign cycles. Stakeholders must monitor how these regulatory trajectories intersect with payer cost-containment pressures to determine portfolio prioritization between novel biologics and complex generic inhalation products.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough therapies are compressing development timelines and forcing incumbents to recalibrate portfolio bets between novel biologics and complex generic inhalation products.
Growth Catalysts
- Hospital Outpatient Expansion:Respiratory therapy programs in hospital outpatient clinics are deepening chronic disease management infrastructure and creating dedicated prescription channels for inhaled combination therapies.
- EMA Bioequience Harmonization:Converging standards for inhaled generics across European member states are reducing regulatory fragmentation and accelerating market access for complex generic developers.
- Dry Powder Engineering:Breath-actuated dosing technology is eliminating propellant dependencies while improving lung deposition precision and patient adherence metrics.
Market Restraints
- Hydrofluorocarbon Propellant Phase-Out:The EU F-Gas Regulation and FDA environmental assessments are forcing costly formulation chemistry overhauls and device redesign cycles for pressurized metered-dose inhalers.
- Divergent Bioequivalence Standards:The FDA, EMA, and Japan's PMDA maintain incompatible requirements for inhaled generics, fragmenting development strategies and delaying substitution rates.
- Active Pharmaceutical Ingredient Concentration:Contract manufacturing scale-up for respiratory APIs concentrates in India, creating single-source vulnerabilities and quality assurance complexity.
Strategic Opportunities
- Japan's PMDA Streamlining:Accelerated review pathways for severe asthma biologics are opening priority market access for monoclonal antibody developers with differentiated mechanisms.
- Biologics-Device Convergence:Integration of monoclonal antibodies with smart inhaler platforms is creating premium positioning opportunities in severe asthma and COPD maintenance.
- Primary Care Channel Control:Deep penetration of respiratory specialists in Germany's ambulatory care networks offers anchoring potential for combination therapy portfolios.
Industry Challenges
- Inhaler Device Engineering Talent:Shortage of aerosol scientists and pulmonary formulation chemists is constraining R&D throughput and extending candidate-to-clinic timelines.
- Legacy System Integration:Digital health connectivity requirements for next-generation inhalers are forcing compatibility architectures with hospital electronic health record systems.
- Particle Size Certification:Cascade impaction testing for one-to-five micrometer deposition standards requires specialized laboratory infrastructure and extended validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulmonary Drugs Market |
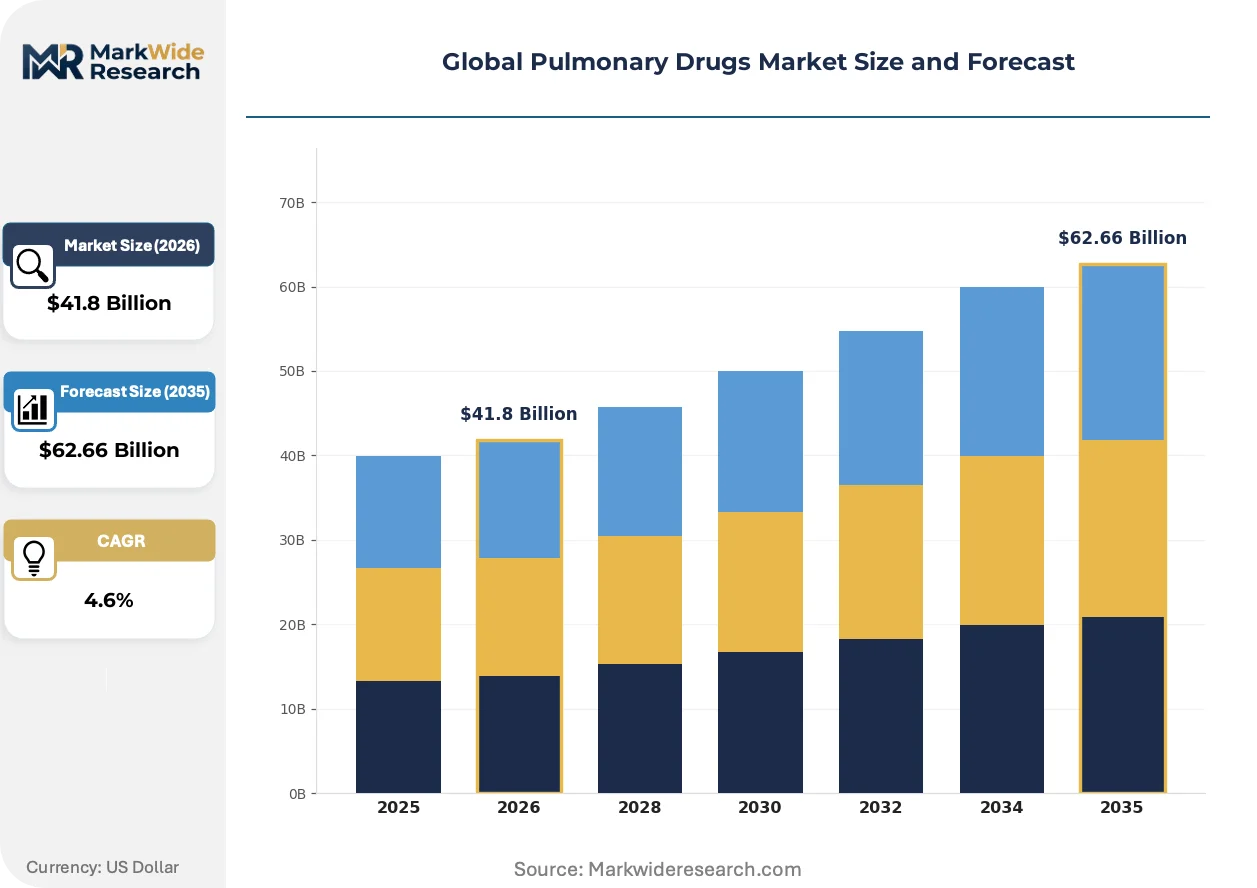
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $62.66 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Bronchodilators, Corticosteroids, Mucolytics, Leukotriene Modifiers, Combination Drugs Therapy Area: Asthma, Chronic Obstructive Disease, Pulmonary Fibrosis, Cystic Fibrosis, Pulmonary Hypertension End User: Pharmacies, Outpatient Clinics, Specialized Care Centers, Homecare Providers, Long-term Care Facilities Formulation: Inhalers, Nebulizers, Oral Tablets, Injectable Solutions, Dry Powder, Soft Mist |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Novartis, F. Hoffmann-La Roche Ltd., Sanofi, Merck & Co., Pfizer, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulmonary Drugs Market Shifts & Advancements
Digital inhaler connectivity and propellant chemistry transitions are simultaneously reshaping device engineering priorities and environmental compliance frameworks across formulation categories.
Smart inhaler platforms with embedded sensors and Bluetooth connectivity are virtualizing adherence monitoring and enabling real-time dose tracking. Hospital systems and payers in the United States are piloting these devices for high-cost biologic regimens. This virtualization is compressing the feedback loop between prescription and clinical intervention, shifting economic value from drug substance to data-enabled service layers.
The EU F-Gas Regulation is mandating transition to lower-global-warming-potential propellants for all pressurized metered-dose inhalers by specified phase-down schedules. Formulation chemists are redesigning suspension stability and valve sealing around hydrofluoroalkane alternatives with markedly different vapor pressure profiles. European manufacturers are absorbing capital intensity for device retooling while awaiting FDA alignment on environmental assessment requirements.
Specialty pharmacy channels are disintermediating traditional wholesale distribution for severe asthma biologics requiring cold-chain handling and patient onboarding support. Payers in Germany and Japan are consolidating reimbursement around these channels to capture outcomes data and manage prior authorization workflows. This concentration is most visible in monoclonal antibody categories where injection training and adverse event monitoring create service differentiation.
Global Pulmonary Drugs Market Segmentation
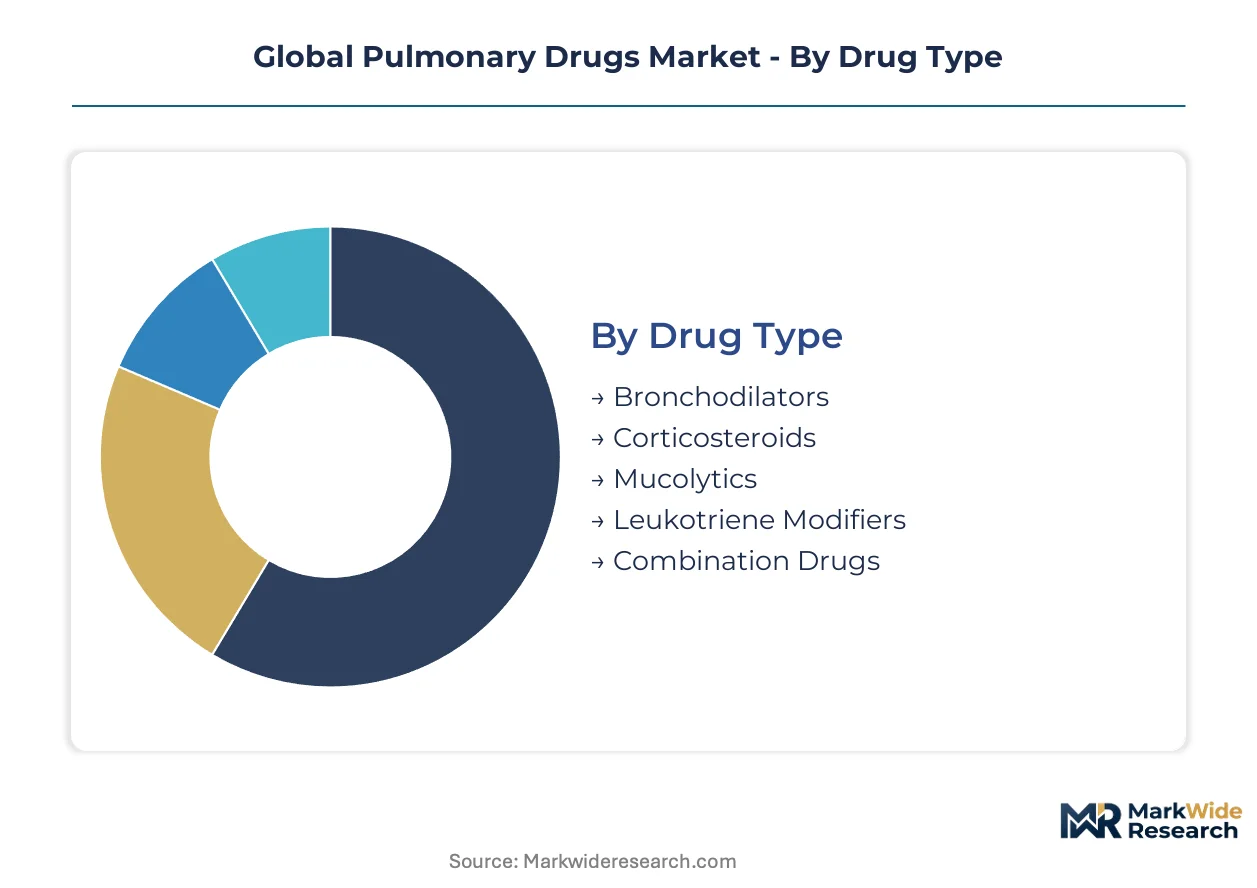
Pulmonary drug segmentation reveals divergent margin structures across formulation technologies and therapy intensities. Prescription channel dynamics and device engineering requirements create distinct competitive arenas within each category.
Drug Type:
Cycle times vary sharply — bronchodilators refresh every 18-24 months with generic substitution, while biologic combination therapies sustain 8-10 year exclusivity windows.
- Combination Drugs:Fixed-dose combinations of long-acting beta-agonists with inhaled corticosteroids in single-device platforms command premium positioning through adherence improvements and patent-protected device mechanics. Demand concentrates in Germany and Japan where payer consolidation favors maintenance therapy simplification and hospital outpatient programs prioritize single-prescription regimens for severe asthma populations.
- Bronchodilators:Short-acting and long-acting beta-agonists serve as first-line symptomatic relief across all obstructive indications. Volume concentrates in United States retail pharmacies where rescue inhaler co-pays drive rapid generic substitution and formulary tier placement determines prescriber behavior.
- Corticosteroids:Inhaled anti-inflammatory agents form the backbone of chronic asthma and COPD maintenance protocols.
- Leukotriene Modifiers:Oral tablet formulations targeting inflammatory mediator pathways serve pediatric and adherence-challenged populations.
- Mucolytics:Agents reducing sputum viscosity address cystic fibrosis and bronchiectasis niches with specialized nebulized delivery requirements.
Combination Drugs dominate installed base value. Bronchodilators represent where volume expansion concentrates fastest.
Therapy Area:
Cost tier separation is pronounced — severe asthma biologics exceed $30,000 annual therapy cost while maintenance COPD inhalers cluster under $5,000.
- Chronic Obstructive Disease:Progressive airflow limitation requiring stepwise escalation from bronchodilator monotherapy through triple-combination maintenance. Patient volume concentrates in United States Medicare populations and Germany's statutory health insurance system where smoking-related disease burden drives the largest addressable prescription base.
- Asthma:Heterogeneous inflammatory condition spanning intermittent to severe persistent phenotypes with biologic eligibility thresholds. Severe asthma demand concentrates in Japan's PMDA-accelerated review pathway and United States specialty pharmacy channels where monoclonal antibody penetration is deepest.
- Pulmonary Fibrosis:Restrictive interstitial disease with limited therapeutic options and antifibrotic agent specialization.
- Cystic Fibrosis:Orphan disease category with mutation-specific modulator therapies and concentrated prescriber networks.
- Pulmonary Hypertension:Vascular remodeling indication requiring parenteral, inhaled, and oral prostacyclin pathway agents.
COPD anchors prescription volume. Severe asthma biologics concentrate margin expansion.
End User:
Customer type determines service intensity — hospital outpatient clinics require respiratory therapist staffing while homecare operates on nursing visit economics.
- Outpatient Clinics:Hospital-affiliated respiratory therapy programs with pulmonologist oversight and spirometry capabilities. United States health systems and Germany's ambulatory care networks are deepening chronic disease management infrastructure with dedicated prescription channels for inhaled combination therapies.
- Specialized Care Centers:Cystic fibrosis foundation-accredited programs and severe asthma referral centers managing complex biologic regimens. Japan's designated medical institutions and United States academic medical centers concentrate prescriber expertise for monoclonal antibody initiation.
- Pharmacies:Retail and mail-order dispensing for maintenance inhaler refills and rescue medication access.
- Homecare Providers:Nebulized therapy delivery and respiratory equipment services for post-acute transitions.
- Long-term Care Facilities:Skilled nursing protocols for COPD exacerbation prevention and inhaler administration assistance.
Outpatient Clinics dominate biologic therapy initiation. Pharmacies handle the greatest refill volume.
Formulation:
Supply concentration clusters around device engineering competencies — dry powder inhaler manufacturing requires precision milling capabilities distinct from pressurized metered-dose propellant handling.
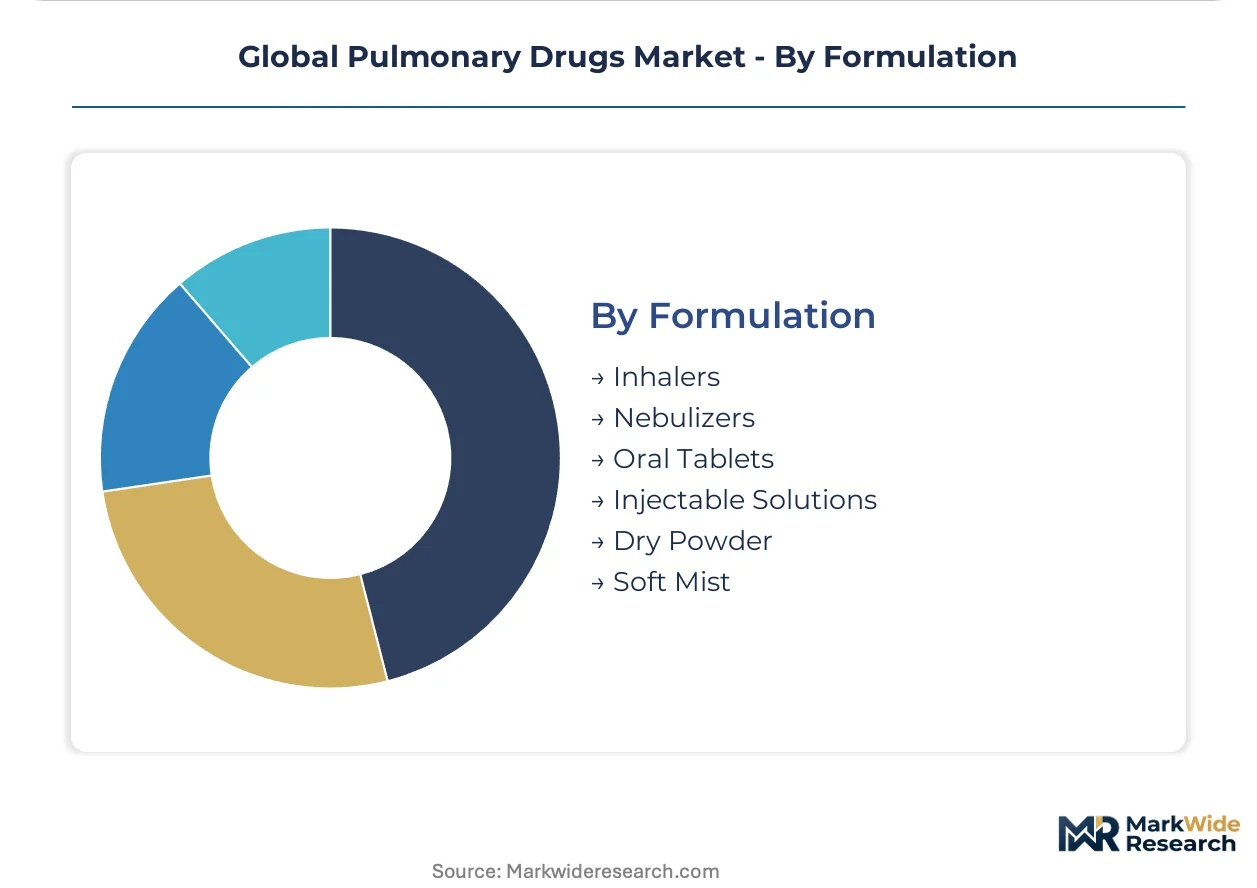
- Dry Powder:Breath-actuated devices eliminating propellant dependencies through engineered particle dispersion. European manufacturers are absorbing capital intensity for device retooling while the formulation segment climbs fastest on improved lung deposition precision and patient adherence metrics.
- Inhalers:Pressurized metered-dose devices with hydrofluorocarbon propellant transitions mandated by EU F-Gas Regulation. Formulation chemists in Germany and United States facilities are redesigning suspension stability around hydrofluoroalkane alternatives with markedly different vapor pressure profiles.
- Nebulizers:Compressor and mesh-based systems for acute care and pediatric administration.
- Soft Mist:Propellant-free liquid inhalation systems with slower velocity aerosol generation.
- Oral Tablets:Systemic delivery for leukotriene modifiers and phosphodiesterase inhibitors.
- Injectable Solutions:Subcutaneous and intravenous biologics for severe asthma and pulmonary hypertension.
Inhalers retain the largest installed base. Dry Powder is where formulation investment concentrates most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes specialty pharmacy biologics for severe asthma. Germany emphasizes ambulatory care integration for COPD maintenance. Japan accelerates monoclonal antibody access through streamlined regulatory pathways.
United States
Hospital outpatient clinics are deepening respiratory therapy infrastructure with dedicated prescription channels for inhaled combination therapies. The FDA's accelerated approval pathways for breakthrough therapies compress development timelines for novel biologics. Boston and San Francisco biotech clusters concentrate monoclonal antibody R&D for severe asthma phenotypes.
Germany
Statutory health insurance systems drive prescription volume for smoking-related COPD maintenance therapies. The EMA bioequivalence harmonization across member states reduces regulatory fragmentation for complex generic inhalation products. North Rhine-Westphalia anchors ambulatory care networks with deep pulmonologist penetration in combination therapy portfolios.
Japan
Severe asthma populations concentrate demand for monoclonal antibody eligibility thresholds. The PMDA streamlines accelerated review pathways for biologics with differentiated mechanisms of action. Tokyo and Osaka designated medical institutions concentrate prescriber expertise for biologic initiation and patient onboarding.
India
Contract manufacturing scale-up for respiratory active pharmaceutical ingredients is tilting toward export-oriented production. The CDSCO enforces evolving bioequivalence standards that shape generic substitution timelines for domestic and export markets. Gujarat and Maharashtra pharmaceutical clusters absorb capital intensity for API precision milling and device component fabrication.
United Kingdom
Primary care channel control determines formulary placement for maintenance inhaler regimens. The MHRA aligns with EMA environmental assessments on propellant transition timelines for pressurized metered-dose devices. London and Cambridge biotech corridors concentrate digital inhaler connectivity development with hospital electronic health record integration.
Global Pulmonary Drugs Market Competitive Landscape
Capability concentration sits with biologics developers commanding premium positioning; scale advantage sits with primary care channel controllers managing volume prescriptions. The market structures around three tiers: monoclonal antibody specialists, combination therapy incumbents, and complex generic challengers. Dominant competitive moves include biologics-device convergence for adherence monitoring and propellant chemistry transitions for environmental compliance.
Within the biologics-specialist tier, AstraZeneca and GlaxoSmithKline exemplify divergent strategic anchors. AstraZeneca occupies a position aligned with severe asthma monoclonal antibody development. GlaxoSmithKline represents primary care channel depth across European and emerging Asian markets. Boehringer Ingelheim sits within the combination therapy tier, anchoring inhaled maintenance portfolios for chronic obstructive pulmonary disease.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| F. Hoffmann-La Roche Ltd. |
| Sanofi |
| Merck & Co. |
| Pfizer |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Air freight corridors connecting Gujarat and Maharashtra to European formulation facilities carry active pharmaceutical ingredients whose transit cost volatility feeds directly into downstream price stratification across inhaler device tiers. The EU F-Gas Regulation's propellant transition mandates and India's CDSCO export compliance requirements create dual cost pressure nodes that manufacturers absorb through tiered pricing architectures separating premium biologic-device combinations from standard maintenance therapies.
Pricing Analysis
Long-term offtake agreements between hospital systems and biologic manufacturers dominate severe asthma therapy pricing, while spot purchasing governs rescue inhaler categories where formulary tier placement determines access. Three-tier pricing structure across premium, standard, and economy levels separates monoclonal antibody regimens with embedded sensor platforms from generic bronchodilators and institutional procurement volumes. Cost compression in pressurized metered-dose categories is intensifying because hydrofluoroalkane propellant reformulation demands capital retooling without commensurate reimbursement uplift. Retail pharmacy channels exhibit highest price sensitivity for maintenance combination therapies, while specialty pharmacy networks show lowest sensitivity for cold-chain biologics requiring patient onboarding services.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk planning for respiratory active pharmaceutical ingredient sourcing. API precision milling concentrates in Gujarat and Maharashtra, while device component fabrication clusters in Germany and the United States, creating geographic dispersion that logistics coordinators must synchronize against just-in-time manufacturing schedules. Formulation chemistry for dry powder inhalers draws from specialized excipient suppliers in Switzerland and Japan, with single-source vulnerability concentrated in lactose carrier processing capabilities. Distribution runs through hospital outpatient procurement systems for biologic therapies and wholesale pharmaceutical distributors for retail pharmacy maintenance refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pulmonary Drugs Market sits at an inflection where FDA breakthrough therapy designation pathways and EU F-Gas environmental mandates simultaneously compress development timelines and force capital reallocation toward compliant formulation platforms.
For Market Incumbents: Entrench position through backward integration into respiratory API manufacturing to offset India's contract manufacturing concentration risk, while accelerating smart inhaler platform development to capture adherence data value pools before generic substitution erodes combination therapy margins. The priority lever rests on pulmonologist channel control in Germany's ambulatory care networks where statutory health insurance consolidation favors maintenance therapy simplification. For New Entrants and Emerging Players: Complex generic dry powder inhalers with bioequivalence pathways through the EMA's harmonized standards represent the most penetrable entry point for mid-cap developers lacking biologics infrastructure. Japan's PMDA-accelerated review pathway for severe asthma monoclonals offers second white-space opportunity for differentiated mechanism biologics. Licensing agreements with established device engineering firms provide the most viable go-to-market angle given aerosol scientist talent scarcity. For Investors and Strategic Acquirers: Digital inhaler connectivity developers with hospital electronic health record integration capabilities present the highest-conviction acquisition archetype for capturing service-layer value migration. Long-term viability over the coming decade hinges on portfolio positioning between environmental compliance hardware and data-enabled adherence platforms. The signal to watch is FDA alignment with EU F-Gas propellant transition timelines, which would trigger synchronized capital deployment cycles across transatlantic manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Transition | EU F-Gas Regulation mandates hydrofluoroalkane reformulation for all pressurized metered-dose devices by specified phase-down schedules. |
| Biologics-Device Convergence | Smart inhaler platforms with embedded sensors enable real-time adherence monitoring for high-cost monoclonal antibody regimens. |
| API Manufacturing Scale-Up | India's CDSCO export compliance requirements shape generic substitution timelines for domestic and international markets. |
| Specialty Pharmacy Channel Development | Cold-chain handling and patient onboarding services create service differentiation for severe asthma biologics in United States and Germany. |
| Regulatory Approval Pathway Optimization | Japan's PMDA streamlines accelerated review for biologics with differentiated mechanisms of action in severe asthma phenotypes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases to establish baseline market sizing and competitive positioning. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, and Japan. Bottom-up prescription volume modeling triangulates against top-down expenditure estimates from statutory health insurance systems and Medicare claims data.
Forecast inputs include therapy line progression rates, dosage form adoption curves, administration route preferences by patient population, and regional regulatory cluster alignment on bioequivalence standards. Segmentation modeling spans drug type, therapy area, end user channel, and formulation technology across the projection horizon. CAGRs derive from fitted growth curves against historical prescription volume trajectories, adjusted for propellant transition capital cycles and biologics pipeline maturation timelines.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy stringency, environmental regulation enforcement pace, or respiratory disease epidemiology would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and generic substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Farm Animal Drugs Market