
 Over the Counter (OTC) Drugs Market | 2026-2036
Over the Counter (OTC) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Counter (OTC) Drugs Market Analysis
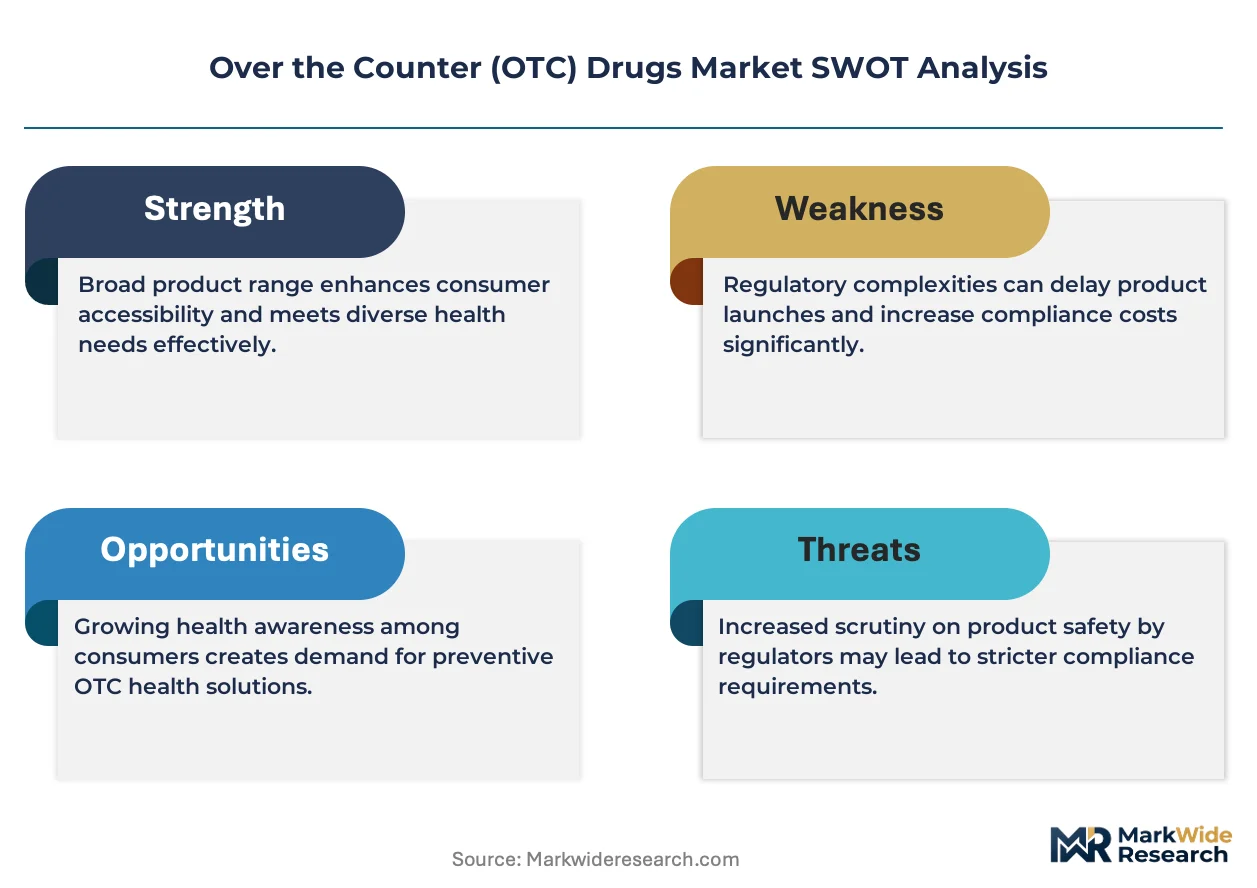
Younger self-directed consumers is collapsing the historical dominance of physician-mediated purchase decisions in cough, cold, and digestive categories. Haleon leverages its heritage brand portfolio to sustain shelf presence across retail pharmacy and supermarket channels. Bayer anchors its position through R&D intensity in analgesic formulations with differentiated delivery mechanisms.
Over the Counter drugs are non-prescription pharmaceutical preparations containing active ingredients at dosages deemed safe for unsupervised consumer use, manufactured through standardized tableting, liquid filling, or semi-solid compounding processes and regulated for stability, bioavailability, and label accuracy. Their primary commercial purpose is to deliver symptomatic relief for common, self-recognizable health conditions without clinical intervention. Analgesics and cold and flu medications occupy the largest revenue pools due to high purchase frequency and seasonal recurrence patterns, while digestive aids represent a structurally faster-growing segment as gut-health awareness expands among preventive-care-oriented buyers. The tablets and capsules formulation category dominates manufacturing scale, though liquids gain traction in pediatric and geriatric applications where swallowing difficulty limits solid-dose adoption.
The FDA's OTC monograph system governs active ingredient safety and efficacy determinations in the United States, while the EMA coordinates national competent authorities across EU member states for mutual-recognition procedures and CE-marked self-care products. These frameworks shape demand by determining which ingredients remain market-accessible without prescription conversion and by mandating label comprehension standards that filter product design. Stakeholders must monitor pending monograph reform implementation timelines and digital health integration requirements that could redefine self-selection criteria and channel eligibility for OTC status.
Market Dynamics
The FDA's OTC monograph reform is collapsing ingredient approval timelines and forcing manufacturers to accelerate reformulation cycles. This regulatory compression is simultaneously opening market access for new active ingredients while threatening legacy products with prescription conversion risks.
Growth Catalysts
- Self-medication among aging populations:Japan's METI has streamlined self-care product classifications, enabling faster market entry for geriatric-targeted formulations.
- Digital health integration:Mobile symptom-checker applications are qualifying consumers for OTC selection without pharmacist intermediation.
- Monograph reform acceleration:The FDA's revised review framework is expanding the eligible ingredient pool for pain-relief and sleep-aid categories.
Market Restraints
- Active ingredient supply concentration:Paracetamol and ibuprofen API production concentrates in China and India, exposing formulators to geopolitical supply disruptions.
- Label comprehension mandates:The EMA's readability requirements impose costly redesign cycles for multilingual European packaging.
- Generic substitution pressure:Retail pharmacy chains are displacing branded SKUs with private-label equivalents in analgesic and antacid segments.
Strategic Opportunities
- Preventive digestive health:Probiotic-OTC hybrids targeting Germany's gut-conscious consumer base remain underpenetrated relative to Nordic markets.
- Subscription direct-to-consumer channels:Amazon Pharmacy and CVS CarePass are capturing recurring revenue from chronic condition self-managers.
- Pediatric liquid formulation gaps:Swallowing-difficulty demographics in aging Japan and South Korea drive demand for novel delivery mechanisms.
Industry Challenges
- Regulatory affairs talent scarcity:Monograph reform complexity requires specialized FDA submission expertise that outpaces current workforce supply.
- Legacy ERP integration with track-and-trace:DSCSA compliance deadlines force costly upgrades to serialization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Counter (OTC) Drugs Market |
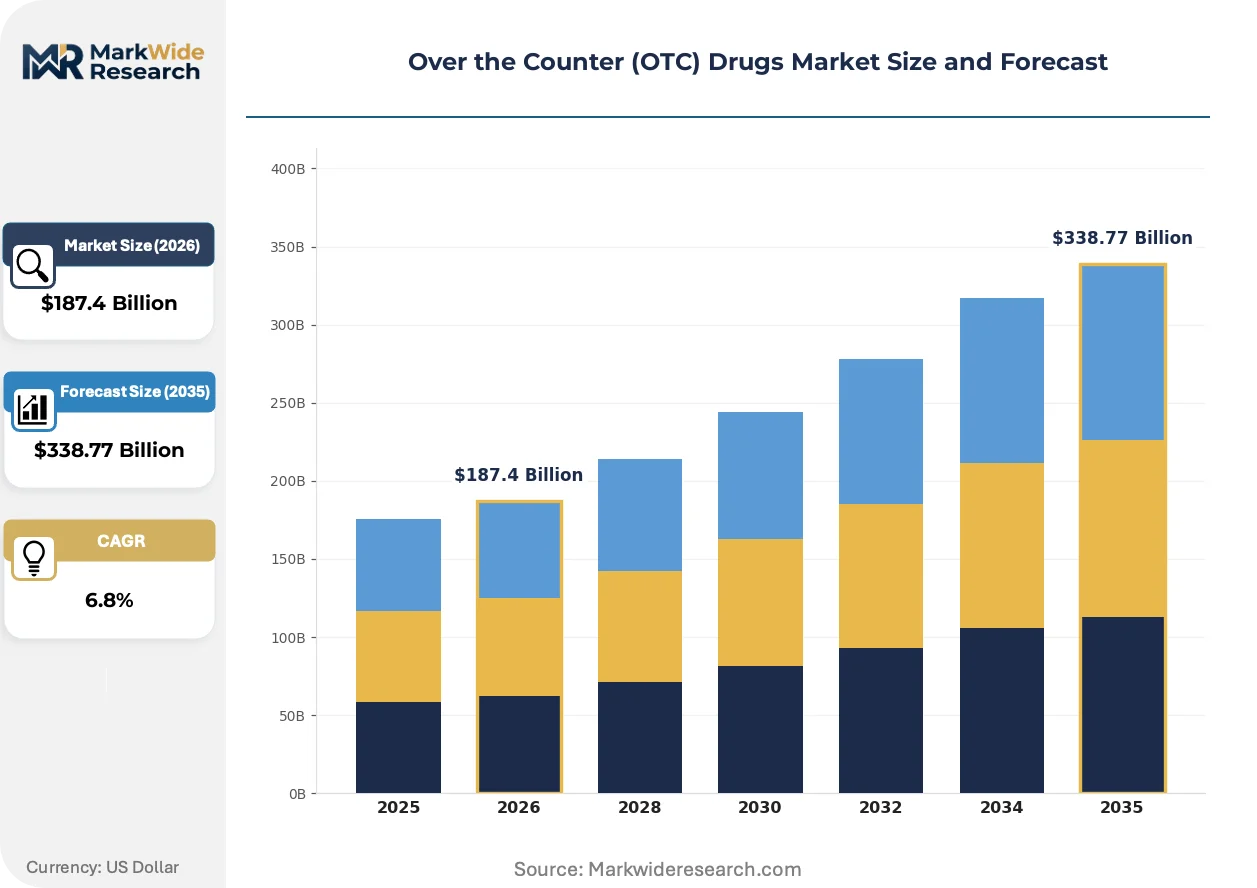
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cold & Flu Medications, Digestive Aids, Allergy Medicines End User: Retail Pharmacies, Supermarkets, Online Stores, Convenience Stores Formulation: Tablets, Capsules, Liquids, Ointments Sales Channel: Direct Sales, E-commerce, Wholesalers, Distributors |
| Companies Covered | Haleon, Kenvue, Bayer, Procter & Gamble Company, Reckitt, Sanofi, Pfizer, Johnson & Johnson Services Inc., Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Counter (OTC) Drugs Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how consumers access self-care products. Three distinct vectors are compressing traditional manufacturer-retailer relationships.
Extended-release tablet technologies are displacing immediate-release formats in analgesic and sleep-aid categories. Chronic pain self-managers in the United States and Germany are adopting once-daily dosing regimens that improve compliance. This shift is compressing SKU proliferation while rewarding R&D-intensive manufacturers with formulation patents.
The FDA's OTC monograph reform is eliminating the time-and-extent application requirement for certain sunscreen and skin-protectant ingredients. This procedural streamlining is accelerating market entry for zinc oxide and titanium dioxide alternatives. Dermatological OTC brands are responding by expanding mineral-based portfolios ahead of the 2025 implementation deadline.
Pharmacy benefit managers are unbundling OTC reimbursement from prescription formularies in employer-sponsored plans. United States-based employers now offer pre-tax health savings account integration for preventive OTC purchases. This behavioral shift concentrates volume in allergy, smoking cessation, and prenatal vitamin categories during open enrollment periods.
Over the Counter (OTC) Drugs Market Segmentation
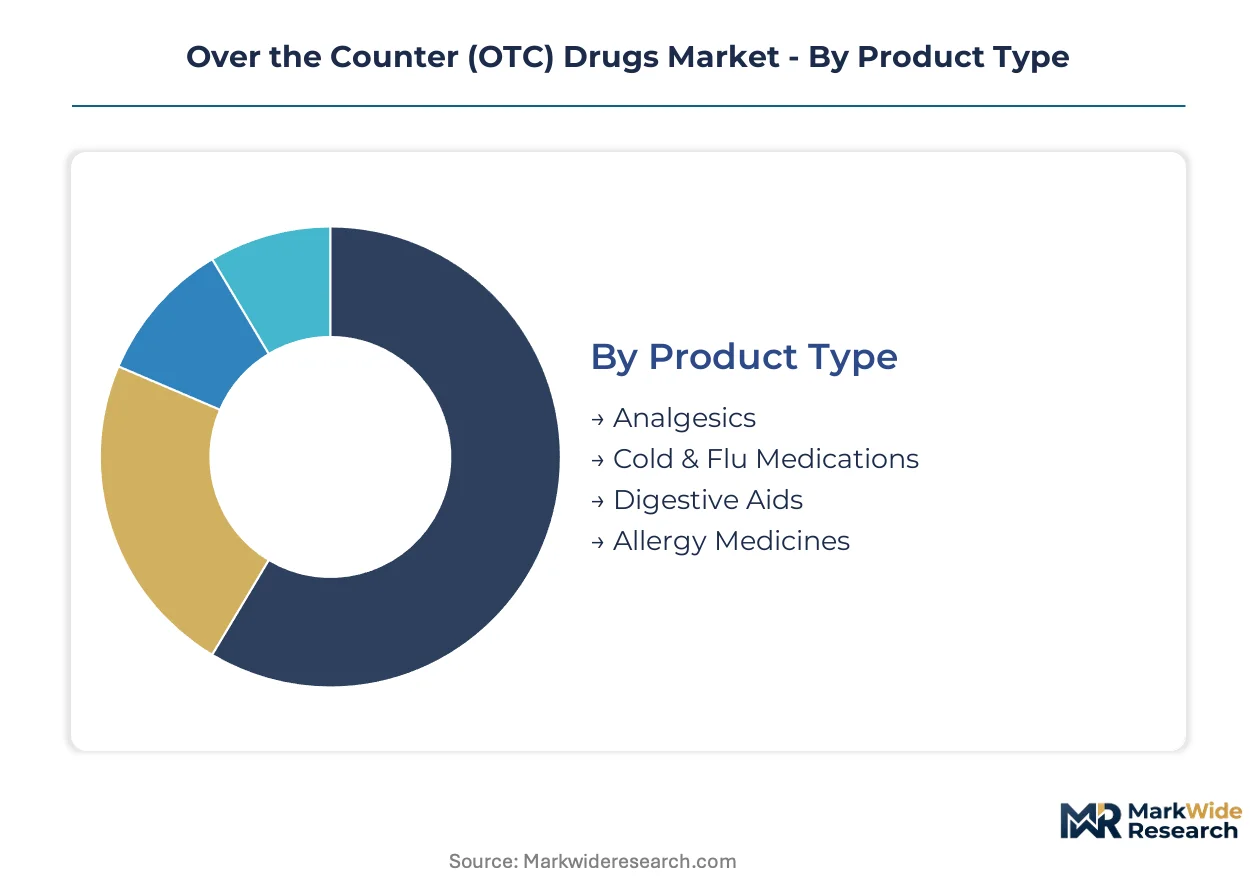
OTC drug manufacturers segment portfolios across therapeutic need, purchase setting, physical form, and route-to-market to align formulation investments with self-medication behaviors. Each dimension carries distinct margin profiles and regulatory compliance burdens that shape competitive positioning.
Product Type:
Private-label substitution pressure concentrates in mature categories with commoditized active ingredients, while differentiated formulations defend branded pricing in preventive segments.
- Analgesics:Formulations containing paracetamol, ibuprofen, or aspirin dominate purchase frequency and shelf space allocation. United States pharmacy benefit structures sustain higher per-capita consumption through HSA-eligible reimbursement, though generic substitution erodes branded margins in supermarket channels.
- Cold & Flu Medications:Seasonal demand spikes drive manufacturing capacity planning and inventory build cycles. German consumers demonstrate stronger preference for multi-symptom combination products than Japanese buyers, who favor single-ingredient precision targeting.
- Digestive Aids:Probiotic-enzyme hybrids attract preventive-care-oriented demographics seeking gut-health maintenance. Nordic markets lead adoption while German and French penetration remains underdeveloped relative to regional income levels.
- Allergy Medicines:Second-generation antihistamines with non-drowsy claims capture seasonal and perennial rhinitis self-treatment. Direct-to-consumer advertising restrictions in Canada and European Union member states limit brand awareness building versus United States market dynamics.
Analgesics anchors the volume base while digestive aids gains share at the steepest rate.
End User:
Channel cost structures determine which end-user segments absorb manufacturer trade spend versus passing price increases to consumers.
- Retail Pharmacies:Professional pharmacist counsel sustains higher price points for condition-appropriate selection. CVS and Walgreens in the United States, plus Boots in the United Kingdom, leverage loyalty programs to lock in recurring analgesic and allergy purchases.
- Supermarkets:Impulse placement and promotional stacking drive volume in cough-cold and digestive categories. German discounters Aldi and Lidl displace branded SKUs with private-label equivalents at 40-60% price discounts.
- Online Stores:Subscription mechanics capture chronic condition self-managers seeking automated replenishment. Amazon Pharmacy and CVS CarePass concentrate recurring revenue in prenatal vitamins and smoking cessation aids.
- Convenience Stores:Immediate-need fulfillment commands premium pricing for single-unit analgesic and digestive purchases. Urban density in Tokyo and Seoul sustains 24-hour accessibility that rural United States markets cannot replicate.
Retail pharmacies retains the largest transaction value per basket while online stores climbs fastest in recurring revenue capture.
Formulation:
Manufacturing complexity and stability requirements segment margins, with liquid and semi-solid forms carrying higher per-unit production costs than solid doses.
- Tablets:Standardized tableting processes enable scale economies and extended-release patent differentiation. Once-daily analgesic formulations improve compliance among chronic pain self-managers in Germany and the United States.
- Capsules:Gelatin and vegetarian shell options accommodate dietary restriction marketing claims. Enteric coatings protect acid-labile probiotics in digestive health applications targeting Japanese gut-conscious consumers.
- Liquids:Pediatric and geriatric applications dominate where swallowing difficulty limits solid-dose adoption. South Korean and Japanese aging demographics drive demand for novel delivery mechanisms in cough-cold categories.
- Ointments:Topical absorption formulations serve dermatological and musculoskeletal symptom relief. Zinc oxide and titanium dioxide mineral bases expand following FDA monograph reform streamlining.
Tablets commands the largest manufacturing scale while liquids expands most quickly in demographic-adaptive applications.
Sales Channel:
Channel control over consumer data and purchase timing determines which intermediaries capture value from manufacturer to end-user.
- Direct Sales:Manufacturer-controlled websites and telehealth integrations enable personalized regimen recommendations. United States DTC brands bypass retail margin stacking but absorb customer acquisition costs through digital advertising.
- E-commerce:Platform algorithms and review systems substitute for pharmacist counsel in product selection. Amazon's search dominance in the United States and Alibaba's Tmall in China concentrate online OTC discovery.
- Wholesalers:Inventory pooling and logistics networks serve independent pharmacy and small-format retail. McKesson and AmerisourceBergen in the United States, plus Phoenix and Alliance Healthcare in Europe, consolidate distribution scale.
- Distributors:Regional specialization addresses pharmacy chain and hospital outpatient formulary requirements. Japanese distributor consolidation under METI self-care streamlining reduces market entry friction for geriatric-targeted formulations.
Wholesalers handles the greatest physical volume while direct sales achieves the steepest expansion trajectory in margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports paracetamol and ibuprofen APIs to formulators in the United States and Germany, anchoring a trade corridor that supplies raw materials for finished OTC products consumed across North America and Western Europe.
United States
Pharmacy benefit structures and HSA-eligible reimbursement sustain the highest per-capita OTC consumption worldwide. The FDA's OTC monograph reform accelerates ingredient review timelines and expands eligible actives for pain-relief categories. New Jersey and Pennsylvania host concentrated manufacturing clusters where legacy formulators upgrade serialization infrastructure for DSCSA compliance.
Germany
Gut-health awareness among preventive-care-oriented buyers drives digestive aid adoption at rates exceeding other European markets. The EMA coordinates national competent authorities for mutual-recognition procedures that shape cross-border product access. The Rhine-Ruhr industrial corridor anchors formulation capacity for extended-release analgesic technologies serving chronic pain self-managers.
Japan
Aging demographics and swallowing-difficulty prevalence accelerate demand for novel liquid delivery mechanisms in cough-cold categories. METI has streamlined self-care product classifications, enabling faster market entry for geriatric-targeted formulations. The Kanto region around Tokyo concentrates distribution infrastructure that sustains 24-hour convenience store accessibility unmatched in rural markets elsewhere.
China
Domestic API production concentration for paracetamol and ibuprofen exposes global formulators to geopolitical supply disruption risks. The NMPA governs manufacturing standards and stability requirements for export-oriented producers. Zhejiang and Jiangsu provinces host the bulk of active ingredient synthesis capacity serving international pharmaceutical customers.
United Kingdom
Pharmacist counsel requirements sustain higher price points for condition-appropriate selection than supermarket channels permit. The MHRA operates post-Brexit regulatory frameworks that diverge from EMA coordination on certain monograph implementations. The Southeast England cluster around London maintains headquarters operations for several multinational OTC portfolio managers.
Over the Counter (OTC) Drugs Market Vendor Landscape
Listed leaders compete with private specialists across formulation patent portfolios and retail channel access. The vendor base concentrates among ten to fifteen entities with sufficient scale to absorb regulatory compliance costs and R&D intensity requirements. Three archetypes dominate: heritage brand portfolio managers, API-integrated formulators, and private-label contract manufacturers. M&A activity targets digestive health and dermatological specialists, while capacity expansion concentrates in extended-release solid-dose technologies.
Within the heritage brand tier, Haleon and Bayer occupy positions that exemplify divergent strategic emphases. Haleon leverages consumer-facing brand equity across retail pharmacy and supermarket channels to sustain shelf presence in mature categories. Bayer anchors its positioning through R&D intensity in analgesic formulations with differentiated delivery mechanisms. Kenvue represents the consumer health spin-off archetype, sitting within a structure that separates OTC portfolios from prescription pharmaceutical operations.
| Leading Market Players |
|---|
| Haleon |
| Kenvue |
| Bayer |
| Procter & Gamble Company |
| Reckitt |
| Sanofi |
| Pfizer |
| Johnson & Johnson Services Inc. |
| Perrigo Company |
| Others |
Supply Flow & Price Mechanics
FDA monograph reform gates both supplier qualification and price tier eligibility simultaneously, compressing legacy product margins while opening premium positioning for reformulation-ready manufacturers who can absorb accelerated compliance costs.
Pricing Analysis
Immediate-release formats trade at commodity parity while extended-release patents command 40-60% premiums in analgesic categories. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery mechanism sophistication and bioavailability claims. Price compression runs through immediate-release segments as German discounters displace branded SKUs with private-label equivalents. Supermarket channels exhibit highest price sensitivity; pharmacy benefit structures in the United States sustain lowest sensitivity through HSA-eligible reimbursement mechanics.
Supply Chain Analysis
Inventory cycles compress ahead of DSCSA compliance deadlines as manufacturers accelerate serialization infrastructure upgrades. Paracetamol and ibuprofen API production concentrates in China and India, exposing formulators to geopolitical disruption risks. Finished dose manufacturing draws from Zhejiang and Jiangsu synthesis clusters while distribution runs through McKesson and AmerisourceBergen networks in the United States and Phoenix plus Alliance Healthcare in Europe. Single-source API vulnerability represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through retail pharmacy chain consolidation and pharmacy benefit manager unbundling, shifting margin capture downstream from manufacturers to intermediaries.
For Market Incumbents: Fortify extended-release patent portfolios against generic substitution pressure in analgesic categories. Deepen backward integration into API supply through captive production or long-term offtake agreements with Indian and Chinese manufacturers to mitigate geopolitical exposure. Accelerate DSCSA-compliant serialization infrastructure ahead of enforcement deadlines to preserve wholesale channel access. For New Entrants and Emerging Players: Anchor in preventive digestive health segments where probiotic-enzyme hybrids remain underpenetrated in German and French markets relative to Nordic adoption rates. Target subscription direct-to-consumer channels through Amazon Pharmacy or CVS CarePass mechanics for chronic condition self-managers seeking automated replenishment. Lead with gut-health maintenance positioning rather than symptomatic relief claims. For Investors and Strategic Acquirers: FDA monograph reform reshapes the acquisition landscape by threatening legacy products with prescription conversion while rewarding reformulation-ready portfolios. Five-to-ten year viability favors targets with extended-release solid-dose capabilities and dermatological or digestive health specializations. Monitor FDA implementation timelines as the critical inflection signal for portfolio revaluation events.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Patent | Once-daily dosing regimens improve compliance among chronic pain self-managers in Germany and the United States. |
| Backward Integration into API Supply | Captive paracetamol production mitigates concentration risk from China and India sourcing dependencies. |
| DSCSA Serialization Compliance | Track-and-trace infrastructure upgrades preserve wholesale channel eligibility under FDA enforcement timelines. |
| Probiotic-Enzyme Hybrid Launch | Preventive gut-health positioning captures German consumers seeking maintenance over symptomatic relief. |
| Subscription DTC Channel Entry | Amazon Pharmacy and CVS CarePass mechanics lock in recurring revenue from chronic condition self-managers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regulatory affairs directors, pharmacy benefit managers, retail category buyers, and formulation R&D leads. Secondary validation drew from FDA monograph filings, EMA mutual-recognition procedure documentation, DSCSA implementation guidance, and pharmacy chain 10-K disclosures. Bottom-up volume builds triangulated against top-down macroeconomic anchors across the analysis window.
Across the projection horizon, the analytical framework modeled therapeutic category, dosage form, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate synthesis applied to base-year value estimates. Forecast inputs incorporated monograph reform implementation timelines, aging demographic swallowing-difficulty prevalence curves, and HSA reimbursement eligibility expansion patterns.
Material uncertainties — regulatory enforcement delays, API supply disruptions, and private-label substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these exogenous factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Omeprazole and Antihistamine Market