
 Personal Auto Insurance Market | 2026-2036
Personal Auto Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Auto Insurance Market Insights
China's connected-vehicle data infrastructure build-out is rewriting how insurers price risk in real time. Progressive leverages telematics data from millions of active devices to sustain precision underwriting at scale. State Farm anchors its market presence through an exclusive agent network that controls local distribution across thousands of U.S. communities. GEICO competes on direct-to-consumer digital acquisition costs that dominate the online quote-comparison channel.
Personal auto insurance is a property-casualty contract that indemnifies individual vehicle owners against financial loss from collision, theft, liability, or bodily injury, with premiums calibrated through actuarial models incorporating driving behavior, vehicle safety ratings, and geographic loss history. Its primary commercial purpose is to transfer operating risk from private motorists to pooled capital reserves while satisfying compulsory financial responsibility laws. Liability coverage leads policy type segmentation due to mandatory minimums in most jurisdictions, while comprehensive coverage captures expanding margin pools as climate-related weather losses drive replacement cost inflation. Online platforms represent the fastest-growing distribution channel, displacing traditional agent relationships among younger customer segments who complete purchases without human intermediaries.
NHTSA vehicle safety ratings directly influence loss-cost projections that insurers embed into rate filings, while state insurance commissioners in the United States review premium adequacy through prior-approval or file-and-use regimes that constrain pricing flexibility. The EU AI Act imposes algorithmic transparency obligations on automated underwriting systems that European carriers must integrate before deploying machine-learning-based risk scoring. Stakeholders must monitor whether U.S. state regulators harmonize telematics consent standards or perpetuate a patchwork that fragments product deployment across jurisdictions.
Market Dynamics
Telematics-enabled usage-based pricing is compressing traditional actuarial models as real-time driving data supplants historical loss tables for risk segmentation.
Growth Catalysts
- EU AI Act compliance mandates:European carriers must deploy algorithmic transparency frameworks for automated underwriting, accelerating investment in explainable machine-learning systems.
- Gig-economy vehicle operators:Ride-hailing and delivery drivers in the United States seek hybrid personal-commercial coverage endorsements that blend private auto contracts with commercial-for-hire protections.
- Connected-vehicle data infrastructure:China's real-time telemetry networks enable dynamic premium adjustments based on actual driving behavior rather than proxy variables.
Market Restraints
- State regulatory fragmentation:Prior-approval and file-and-use regimes across U.S. jurisdictions create inconsistent telematics consent standards that delay product launches.
- Climate-related loss cost inflation:Severe weather frequency drives comprehensive coverage replacement costs upward, pressuring reserve adequacy.
- Legacy agent distribution lock-in:Exclusive agency networks control local market access in thousands of U.S. communities, raising customer acquisition costs for direct-to-consumer entrants.
Strategic Opportunities
- Usage-based insurance penetration in Germany:Telematics-enabled pricing remains underdeveloped relative to vehicle density, creating white space for behavioral risk models.
- Digital-native distribution channels:Online quote-comparison platforms capture younger customer segments who complete purchases without human intermediaries.
- Vehicle safety rating integration:NHTSA crash-test data feeds directly into dynamic rate filings, enabling premium discounts for advanced driver-assistance systems.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals capable of integrating telematics streams with traditional reserving methods slows product development cycles.
- Legacy policy administration systems:Core platforms lack API architectures for real-time data ingestion, forcing expensive middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Auto Insurance Market |
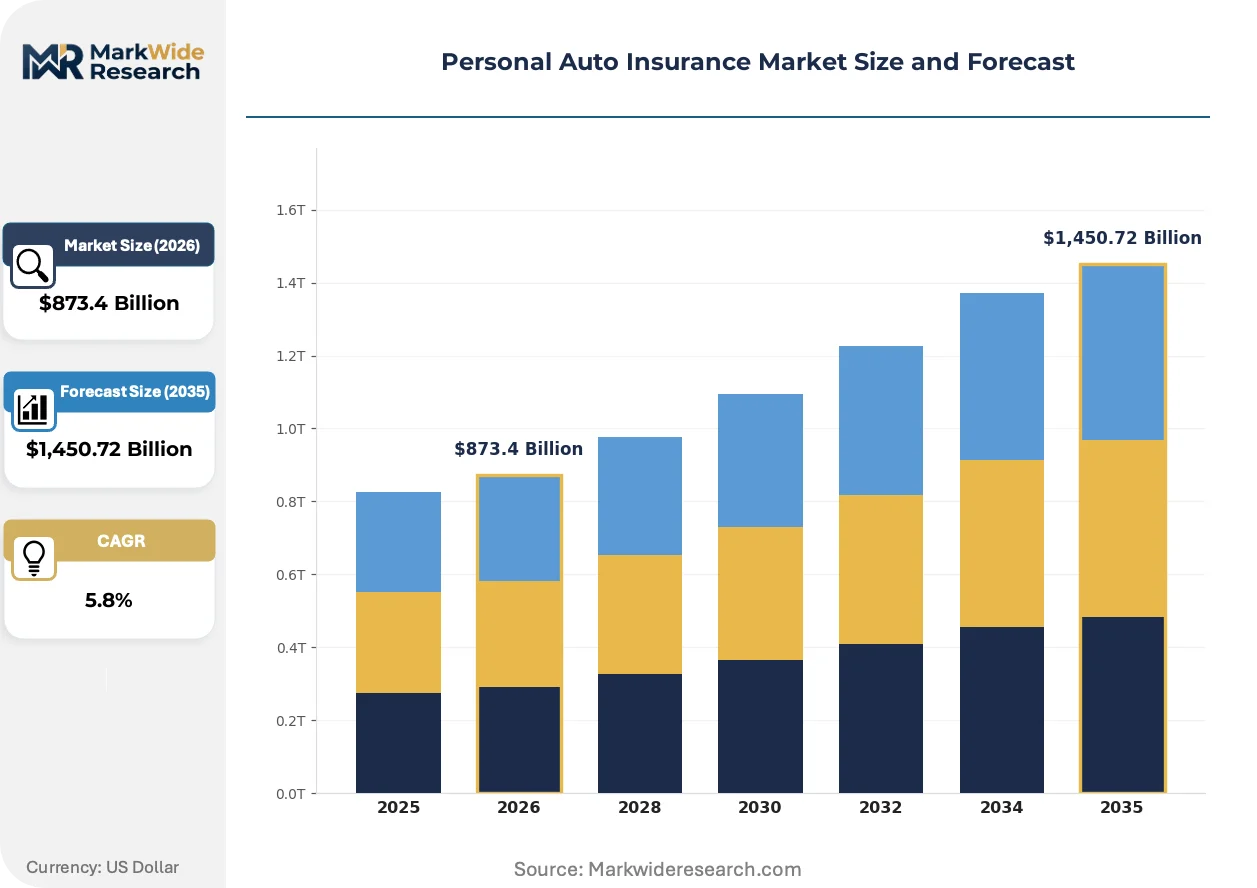
| Market Size in 2026 | $873.4 Billion |
| Market Size in 2035 | $1,450.72 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Liability, Collision, Comprehensive, Personal Injury Protection, Uninsured Motorist Distribution Channel: Direct Sales, Agents & Brokers, Online Platforms, Bancassurance, Call Centers Customer Type: Individual Drivers, Young Drivers, Senior Drivers, High-Net-Worth Individuals, First-Time Buyers Coverage Add-Ons: Roadside Assistance, Rental Car Reimbursement, Glass Coverage, Accident Forgiveness, Gap Insurance |
| Companies Covered | State Farm, Progressive, GEICO, Allstate, USAA, Farmers Insurance, Liberty Mutual, Travelers, American Family Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Auto Insurance Market Trends and Innovations
Real-time data streams and algorithmic decision-making are displacing static annual policy cycles with continuous risk monitoring and dynamic pricing adjustments.
Embedded telematics hardware is hybridizing traditional personal auto contracts with pay-per-mile structures. Younger policyholders in the United States adopt smartphone-based driving score apps that translate behavior into immediate premium adjustments. This convergence is compressing the gap between risk exposure and price paid, eroding the cross-subsidy pools that historically balanced safe and risky drivers.
REACH chemical safety standards and the EU AI Act impose dual compliance burdens on European carriers deploying predictive underwriting models. Insurers must document algorithmic decision pathways while ensuring training data excludes prohibited bias variables. Mid-sized carriers in France and Germany face particular strain as they retrofit legacy scoring engines to meet transparency mandates before deployment deadlines.
Digital self-service purchasing is displacing agent-mediated transactions among demographics under age forty. Younger buyers complete binding coverage through mobile-optimized comparison platforms that bypass traditional quote-to-bind workflows. This channel shift is most pronounced in the United Kingdom and United States, where regulatory sandbox frameworks have enabled direct insurer-consumer digital contracting without intermediary licensing requirements.
Personal Auto Insurance Market Segmentation
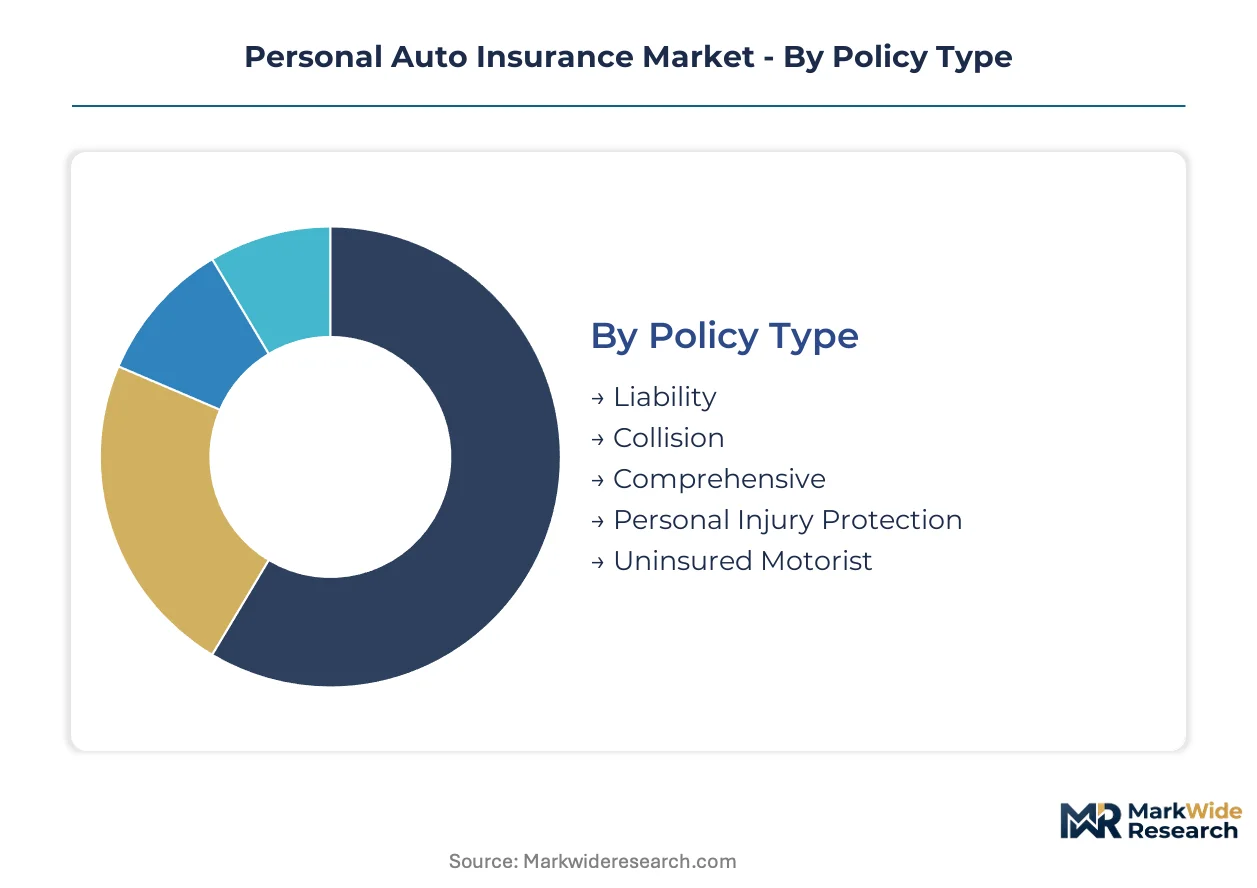
Personal auto insurance segmentation determines pricing precision, distribution investment, and reserve allocation. Insurers calibrate product design around policy type mandates, channel economics, and customer lifetime value profiles. Each segment carries distinct loss-cost characteristics and servicing intensity requirements.
Policy Type:
After-sales service intensity varies sharply across policy types, with claims frequency and severity driving support infrastructure requirements.
- Liability:Statutorily mandated coverage indemnifies third-party bodily injury and property damage. Demand concentrates among cost-conscious drivers in jurisdictions with stringent financial responsibility laws, where minimum coverage thresholds constrain premium flexibility.
- Comprehensive:Physical damage protection against theft, vandalism, and weather-related losses commands higher premium multiples. Climate loss inflation in hail-prone U.S. states and flood zones is compressing underwriting margins and accelerating rate filing activity.
- Collision:First-party vehicle repair coverage tied to accident frequency. Repair cost inflation for advanced driver-assistance system sensors is elevating severity trends.
- Personal Injury Protection:No-fault medical expense and lost-wage benefits required in specific U.S. states. Regulatory variation creates product standardization challenges across state lines.
- Uninsured Motorist:Protection against at-fault drivers lacking coverage. Penetration rates correlate inversely with state enforcement rigor of compulsory insurance laws.
By volume, Liability leads. By growth pace, Comprehensive is expanding most quickly.
Distribution Channel:
Customer acquisition economics stratify sharply across channels, with digital-native entrants disrupting legacy cost structures.
- Direct Sales:Insurer-employed sales forces bypass intermediary commissions. GEICO and Progressive deploy this model to dominate price-comparison search rankings.
- Agents & Brokers:Independent and exclusive intermediaries control local market access. State Farm's exclusive agent network maintains defensible share in thousands of U.S. communities through relationship-based persistency.
- Online Platforms:Mobile-optimized quote comparison enables self-service binding. Younger demographics in the United Kingdom and United States complete purchases without human intermediaries.
- Bancassurance:Bank-branch distribution leverages existing customer relationships. European carriers partner with retail banking networks to reduce acquisition costs.
- Call Centers:Voice-assisted sales support complex coverage consultations. Senior driver segments prefer assisted enrollment for policy explanation.
By premium volume, Agents & Brokers retains dominance. By share gain velocity, Online Platforms is climbing the fastest.
Customer Type:
Risk heterogeneity across life-stage and wealth profiles demands granular pricing segmentation and targeted product bundling.
- Individual Drivers:Standard risk pool encompassing prime-age motorists with clean loss histories. Telematics penetration is highest in this segment as insurers compete on behavioral pricing.
- Young Drivers:Elevated loss-cost demographics facing affordability constraints. Usage-based insurance adoption is concentrated here as smartphone scoring apps enable immediate premium relief for safe behavior.
- Senior Drivers:Mature motorists with declining mileage but age-related severity risk. Mature driver discount programs and defensive driving course incentives retain this profitable cohort.
- High-Net-Worth Individuals:Affluent households requiring excess liability limits and scheduled vehicle coverage. White-glove claims service and concierge repair coordination justify premium pricing.
- First-Time Buyers:New vehicle owners navigating coverage selection without prior carrier relationships. Digital education tools and simplified product structures reduce friction in this acquisition funnel.
By policy count, Individual Drivers leads. By margin expansion, High-Net-Worth Individuals is gaining share fastest.
Coverage Add-Ons:
Ancillary coverage penetration drives policyholder lifetime value and differentiates commoditized base products.
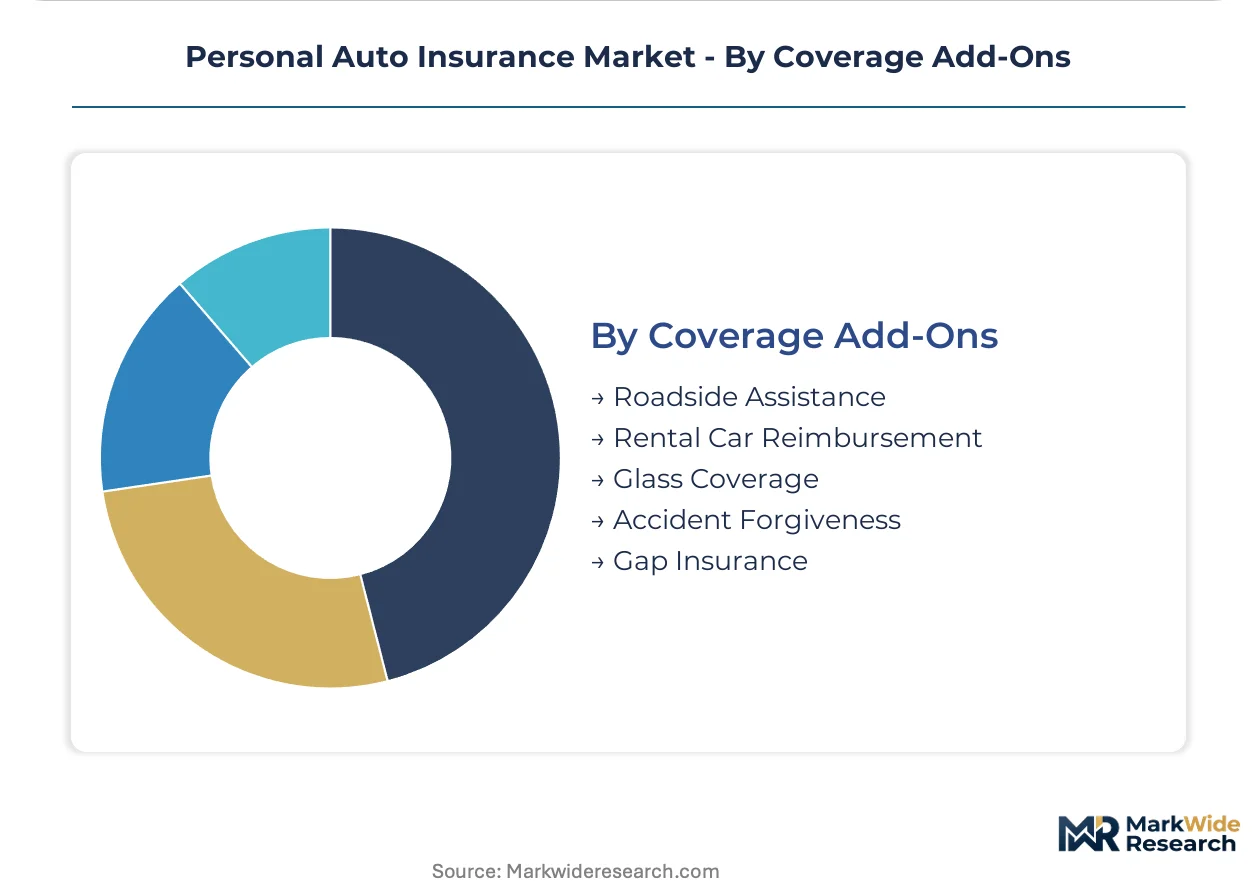
- Roadside Assistance:Emergency towing and mechanical breakdown services. Bundling penetration is highest among rural drivers with limited repair network access.
- Rental Car Reimbursement:Temporary transportation coverage during repair periods. Take-up rates correlate with vehicle dependency for employment commuting.
- Glass Coverage:Windshield repair and replacement with reduced or zero deductibles. Chip repair claims frequency is elevating loss costs in gravel-road geographies.
- Accident Forgiveness:First-at-fault accident surcharge protection. Young driver segments prize this feature for premium stability.
- Gap Insurance:New vehicle loan balance coverage against total loss depreciation. Dealer-finance penetration drives distribution concentration.
By attachment rate, Roadside Assistance leads. By growth trajectory, Accident Forgiveness is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier capital reserves concentrate most heavily in the United States, where premium volume and regulatory complexity generate the deepest risk-pooling infrastructure. State-level rate filing regimes and compulsory insurance mandates shape how insurers deploy telematics and direct-to-consumer platforms across jurisdictions.
United States
Gig-economy vehicle operators in California, Texas, and Florida drive demand for hybrid personal-commercial endorsements. State insurance commissioners in prior-approval jurisdictions review telematics-enabled rate filings before market deployment. The Southeast corridor from Atlanta to Miami anchors commercial-for-hire coverage expansion as ride-hailing density increases.
China
Connected-vehicle data infrastructure in the Yangtze River Delta and Pearl River Delta enables real-time risk pricing for private motorists. The Ministry of Industry and Information Technology governs telemetry data standards that insurers must integrate. Shenzhen-based technology clusters supply telematics hardware to domestic carriers seeking usage-based product differentiation.
Germany
Behavioral risk models remain underpenetrated relative to vehicle density, creating white space for telematics-enabled pricing. The EU AI Act imposes algorithmic transparency obligations on automated underwriting systems that German carriers must satisfy. Munich and Frankfurt insurance hubs host actuarial talent pools developing explainable machine-learning frameworks for dynamic premium adjustment.
United Kingdom
Digital-native distribution channels capture younger customer segments who complete purchases through mobile-optimized comparison platforms. Regulatory sandbox frameworks enable direct insurer-consumer digital contracting without intermediary licensing. London's fintech corridor supplies pricing engine technology to carriers competing on quote-to-bind speed.
India
First-time vehicle owners in Maharashtra, Gujarat, and Karnataka navigate coverage selection without prior carrier relationships. The Insurance Regulatory and Development Authority of India governs motor tariff structures while permitting telematics pilots in select urban markets. Bangalore's technology ecosystem supplies smartphone-based driving score applications to domestic insurers.
Personal Auto Insurance Market Competitive Landscape
Direct-to-consumer specialists and exclusive agency networks split the market along distribution channel lines. Consolidation pressure operates most intensely among mid-tier carriers lacking scale in either digital acquisition or captive agent relationships. Three archetypes dominate: telematics-enabled direct writers, exclusive agent network operators, and hybrid multichannel incumbents. Competitive moves center on strategic partnerships with connected-vehicle data providers and portfolio diversification into usage-based product structures.
Within the direct-to-consumer tier, GEICO and Progressive exemplify digital acquisition scale. State Farm anchors the exclusive agency archetype through relationship-based persistency in thousands of U.S. communities. These three carriers occupy positions that define competitive benchmarks for pricing precision, distribution economics, and customer lifetime value management across the industry.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| GEICO |
| Allstate |
| USAA |
| Farmers Insurance |
| Liberty Mutual |
| Travelers |
| American Family Insurance |
| Others |
Pricing and Supply Chain Analysis
The I-95 freight corridor's fuel surcharge volatility transmits directly into claims adjustment cost structures, concentrating pricing power among carriers with captive repair networks while forcing price differentiation between those with integrated logistics and intermediaries exposed to spot-rate variability.
Pricing Analysis
State insurance commissioner prior-approval regimes dictate the pricing tier structure across personal auto markets. Three-tier pricing separates premium telematics-enabled policies from standard traditional underwriting from economy minimum-coverage products. Price differentiation rests on driving behavior data granularity and geographic loss history precision. Pricing pressure stems from climate-driven comprehensive coverage loss cost inflation. Young drivers in usage-based insurance programs exhibit highest price sensitivity; high-net-worth individuals with scheduled vehicle coverage show lowest.
Supply Chain Analysis
Upstream telematics hardware feeds from semiconductor fabrication concentrated in Taiwan, South Korea, and China. Sensor arrays, GPS modules, and cellular chipsets constitute critical component dependencies. Single-source vulnerability in advanced driver-assistance system semiconductors creates supply chain risk. Distribution runs through OEM embedded installations, aftermarket device retail, and smartphone-based app deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal auto insurance is crossing into platform economics as connected-vehicle data interoperability between OEMs and carriers restructures value capture.
For Market Incumbents: Insulate core agency relationships from direct-to-consumer disintermediation by embedding telematics data sharing into exclusive agent workflows. Acquire predictive underwriting capabilities to counter algorithmic transparency mandates from the EU AI Act. Prioritize API architecture investments to reduce legacy system middleware drag. For New Entrants and Emerging Players: Establish a beachhead in Germany's underpenetrated usage-based insurance segment where behavioral risk models face limited incumbent saturation. Target gig-economy vehicle operators in California, Texas, and Florida seeking hybrid personal-commercial endorsements. Deploy smartphone-based driving score apps to bypass hardware-dependent customer acquisition costs. For Investors and Strategic Acquirers: The EU AI Act's algorithmic transparency mandates reshape the acquisition landscape toward carriers with explainable machine-learning frameworks already deployed. Long-term viability favors mid-sized carriers with demonstrated telematics integration depth over pure-play direct writers lacking data network effects. Watch for harmonization of U.S. state telematics consent standards as the inflection signal for scalable product deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | OEM telemetry sharing agreements with Ford and GM enable real-time risk pricing. |
| Algorithmic Transparency Compliance | Explainable machine-learning frameworks satisfy EU AI Act documentation requirements. |
| Agent Network Digitization | Mobile-optimized tools for State Farm's exclusive agents reduce quote-to-bind friction. |
| Usage-Based Product Launch | Pay-per-mile structures in Germany capture white-space behavioral pricing demand. |
| Climate Risk Reserving Enhancement | Hail and flood loss models for comprehensive coverage address Southeast U.S. severity trends. |
Research Methodology
A spread of perspectives from actuarial directors, state insurance commissioners, telematics platform engineers, and claims operations managers converged on the working assumptions underlying this analysis. Primary interviews with pricing strategy leads at direct-to-consumer carriers and exclusive agency network operators were cross-checked against secondary sources including NAIC rate filing databases, NHTSA vehicle safety datasets, and EU regulatory disclosure repositories. Bottom-up policy count modeling and top-down premium volume estimates were triangulated to constrain projection variance.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include policy type, distribution channel, customer life-stage, and connected-vehicle data integration depth. CAGRs were derived from loss-cost trend extrapolation and telematics penetration curve fitting. Vehicle miles traveled elasticity and regulatory filing approval timelines served as industry-specific forecast inputs.
Stress conditions across catastrophic weather frequency, semiconductor supply disruptions, and state regulatory harmonization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about gig-economy endorsement adoption curves and EU algorithmic transparency compliance deadlines. Cross-checking against NAIC aggregate financial statement benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market