
 Guaranteed Auto Protection (GAP) Insurance Market | 2026-2036
Guaranteed Auto Protection (GAP) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Guaranteed Auto Protection (GAP) Insurance Market Foresight
A capital-intensity divergence between legacy underwriters and digital entrants is rotating competitive dynamics in GAP insurance. Allstate leverages its captive agency network to sustain pricing power across direct and broker channels. Progressive differentiates through telematics-linked policy pricing, while Nationwide anchors its position via exclusive partnerships with credit unions and regional banks.
Guaranteed Auto Protection insurance covers the financial gap between a vehicle's actual cash value and the outstanding loan or lease balance following a total loss, typically triggered by collision, theft, or natural disaster. Policies activate when primary auto insurance settlements fall short of remaining debt obligations, protecting lenders and borrowers from residual liability. The distribution channel segment shows financial institutions capturing the dominant share through point-of-sale embedding at dealership finance offices, while online platforms represent the fastest-growing vector as direct-to-consumer quote engines reduce friction. Coverage level segmentation reveals loan balance policies as the mature volume base, with replacement cost riders emerging as the premium margin pool.
The US Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures for add-on insurance products, while state insurance commissioners regulate rate filings and producer licensing across jurisdictions. The National Association of Insurance Commissioners coordinates model laws that standardize GAP cancellation protocols and refund calculations. Stakeholders must monitor evolving state-level restrictions on dealer markup participation and the shift toward embedded finance platforms that disintermediate traditional broker networks.
Market Dynamics
The Consumer Financial Protection Bureau's enforcement of Truth in Lending Act disclosure requirements is restructuring how GAP insurance reaches borrowers, forcing distributors to abandon opaque markup practices in favor of transparent point-of-sale integration.
Growth Catalysts
- Subprime Auto Finance Expansion:Lenders targeting near-prime and subprime borrowers in the southeastern United States embed GAP coverage as a loss-mitigation tool, accelerating policy attachment rates at origination.
- Extended Loan Duration:Seventy-two and eighty-four month auto loans now dominate new vehicle purchases, extending the negative equity window where GAP protection delivers measurable value.
- CFPB Disclosure Standardization:Federal mandates for clear add-on product presentation reduce consumer confusion and lower post-sale cancellation rates.
Market Restraints
- Primary Insurer Bundling:Major auto carriers now package total-loss protection within comprehensive policies, creating direct substitution pressure on standalone GAP products.
- Dealer Markup Compression:State-level restrictions on dealer participation in insurance product pricing squeeze distribution margins and reduce incentive alignment.
- Residual Value Algorithmic Pricing:Used vehicle valuation platforms compress the information asymmetry that historically supported GAP premium pricing power.
Strategic Opportunities
- Embedded Finance Platforms:Fintech lenders integrating GAP coverage directly into digital loan origination workflows capture borrowers before dealership contact.
- Replacement Cost Riders:Policy upgrades covering new vehicle replacement rather than loan balance payoff command premium pricing from luxury and electric vehicle segments.
- Telematics-Linked Underwriting:Usage-based data streams from connected vehicles enable dynamic risk pricing and proactive loss prevention services.
Industry Challenges
- Legacy System Integration:Established underwriters face technical debt when connecting modern API-based distribution channels to mainframe policy administration platforms.
- Refund Calculation Standardization:The National Association of Insurance Commissioners' model laws create implementation variance across state jurisdictions, complicating multi-state operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guaranteed Auto Protection (GAP) Insurance Market |
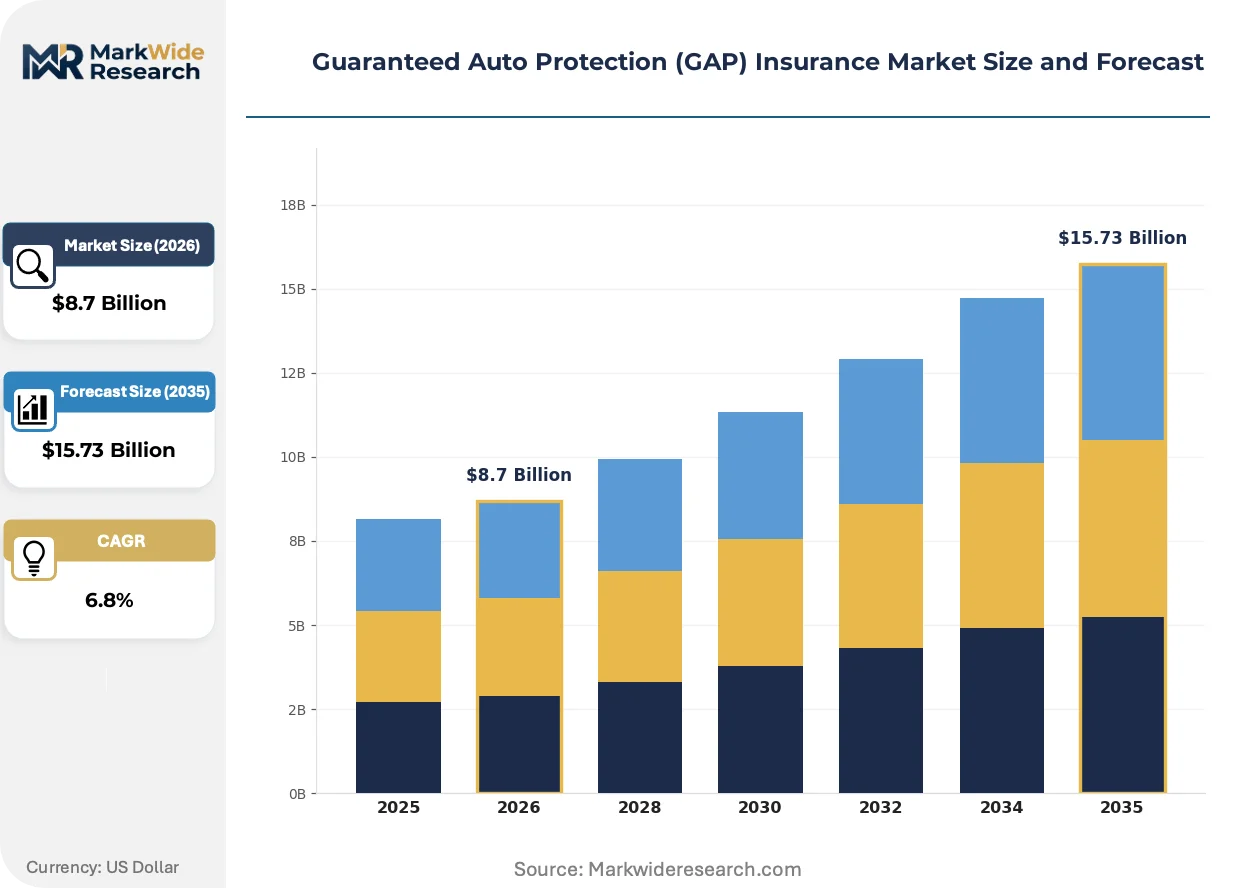
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Original Equipment Manufacturer, Standard, Limited Coverage Level: Loan Balance, Vehicle Value, Market Value, Replacement Cost Distribution Channel: Direct Sales, Insurance Brokers, Financial Institutions, Online Platforms Client Type: Individual Consumers, Automotive Dealerships, Fleet Operators, Rental Companies |
| Companies Covered | Allstate, Liberty Mutual, Erie, American Family, Farmers, Nationwide, Progressive, Travelers, Auto-Owners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guaranteed Auto Protection (GAP) Insurance Market Shifts & Advancements
Digital distribution infrastructure is fragmenting the traditional dealership-centric GAP insurance value chain, enabling direct-to-consumer alternatives and embedded finance integrations that bypass established broker networks entirely.
Application programming interfaces connecting loan origination systems with insurance policy administration platforms are decomposing the dealership finance office's historical monopoly over GAP distribution. Credit unions and digital auto lenders now embed coverage decisions into pre-approval workflows, compressing the time between loan acceptance and policy binding from days to seconds. This disintermediation is decomposing the markup-based revenue model that sustained captive agency networks for decades.
The Consumer Financial Protection Bureau's 2022 guidance on add-on product disclosures has triggered operational overhauls across point-of-sale distribution. Dealer groups now implement menu-based presentation systems that itemize GAP premiums separately from vehicle pricing, increasing transparency but compressing attachment rates in the near term. Independent agencies serving subprime lenders face the steepest compliance costs as they retrofit legacy quoting platforms.
Subscription and usage-based vehicle ownership models are altering the fundamental risk transfer calculus underlying traditional GAP products. Fleet management providers and mobility-as-a-service operators in California and Texas now demand coverage structures aligned with mileage-based depreciation rather than fixed loan amortization schedules. This shift forces underwriters to develop dynamic pricing engines that recalculate exposure as driving patterns evolve.
Guaranteed Auto Protection (GAP) Insurance Market Segmentation
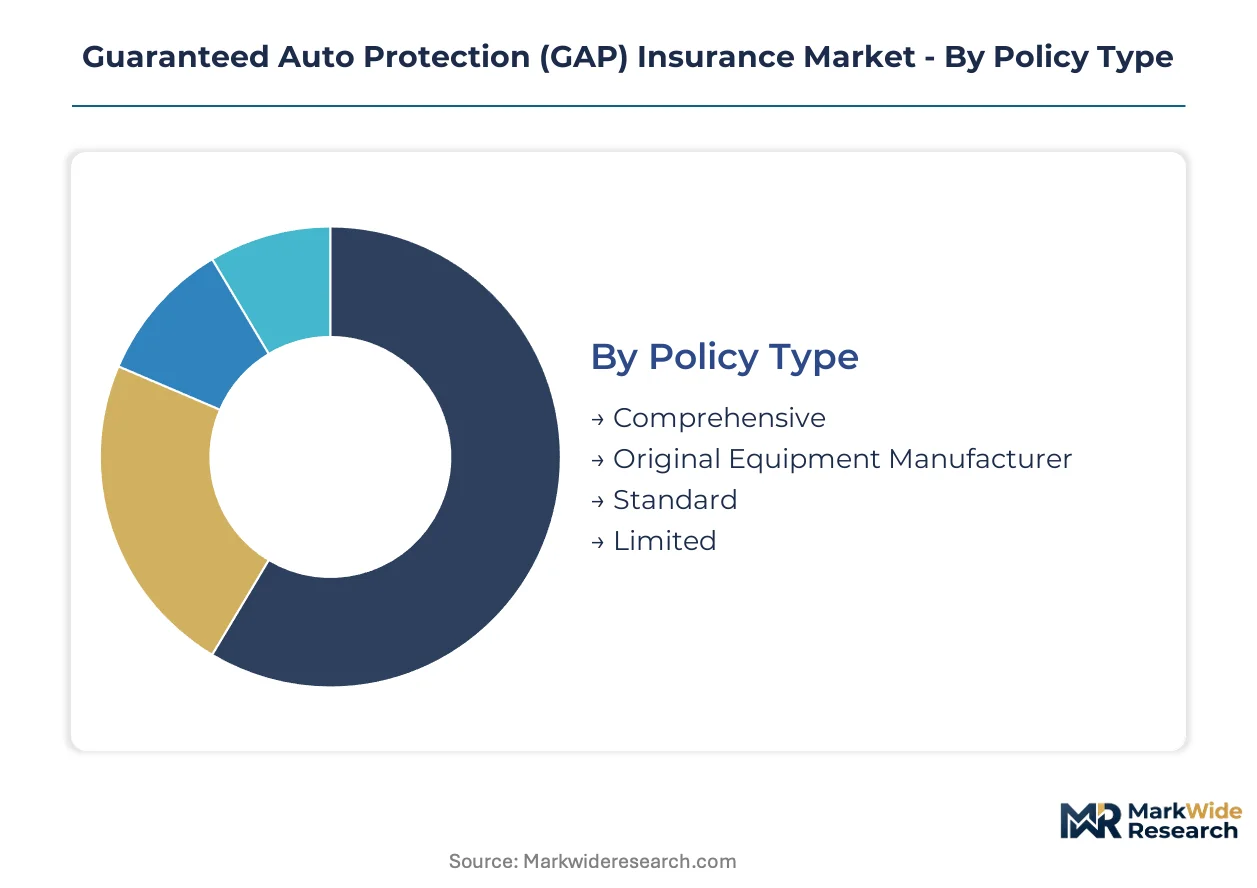
GAP insurance segmentation reveals how product design, distribution economics, and buyer risk profiles intersect. Coverage structures and channel strategies must align with borrower credit tiers and vehicle depreciation curves to sustain attachment rates.
Policy Type:
Geographic demand concentration varies sharply by policy sophistication, with export-oriented comprehensive products commanding premium positioning in cross-border auto finance while domestic-standard variants saturate subprime-heavy southeastern states.
- Comprehensive:Wraps collision, theft, and natural disaster triggers into unified coverage with no deductible gaps. Demand clusters in Texas and Florida where hurricane and flood exposure elevates total-loss frequency among financed vehicles.
- Original Equipment Manufacturer:Tied to captive finance arms of major automakers, embedding GAP at point of vehicle purchase with streamlined claims adjudication. Captive lenders in Michigan and Ohio leverage this integration to sustain above-market attachment rates.
- Standard:Baseline loan balance protection with fixed term matching original financing duration. Dominates credit union portfolios across the Carolinas and Georgia where conservative underwriting prevails.
- Limited:Restricted coverage windows and exclusion-heavy terms targeting deep subprime borrowers with elevated default risk. Concentrated among buy-here-pay-here dealers in Alabama and Mississippi.
Standard policies hold the largest share; momentum sits with OEM-integrated products.
Coverage Level:
Cost tier stratification separates commoditized loan-payoff products from premium replacement-cost riders that command margin expansion in luxury and electric vehicle segments.
- Loan Balance:Pays remaining principal obligation after primary insurance settlement, the foundational GAP structure. Volume concentrates in 72-84 month subprime originations where negative equity duration extends longest.
- Vehicle Value:Covers depreciation gap to stated value rather than loan balance, appealing to high-down-payment borrowers. Gains traction among credit union members in Virginia and Tennessee with conservative loan-to-value ratios.
- Market Value:Ties payout to real-time used vehicle pricing indices, reducing basis risk for underwriters. Emerging format in California where algorithmic valuation platforms compress pricing information asymmetry.
- Replacement Cost:Funds new vehicle acquisition rather than debt retirement, commanding premium pricing. Demand surges in Texas and Florida luxury markets where electric vehicle depreciation curves remain volatile.
Loan Balance coverage dominates volume; Replacement Cost gains share fastest in coastal premium markets.
Distribution Channel:
Volume concentration favors embedded finance routes while customer acquisition economics shift toward digital direct channels that bypass traditional broker commissions.
- Direct Sales:Carrier-owned agents and call centers quoting standalone policies post-purchase. Retains relevance in rural markets where dealership density remains low.
- Insurance Brokers:Independent producers shopping multiple carriers for refinance and lease-end conversions. Faces compression as embedded alternatives reduce borrower price sensitivity.
- Financial Institutions:Credit unions and regional banks embedding GAP at loan origination, capturing 100% attachment through menu-based presentation systems. Dominates southeastern states with high credit union penetration.
- Online Platforms:API-connected quote engines enabling pre-approval coverage decisions, climbing the fastest as fintech lenders disintermediate dealership finance offices.
Financial Institutions anchor current volume; Online Platforms represent the steepest expansion trajectory.
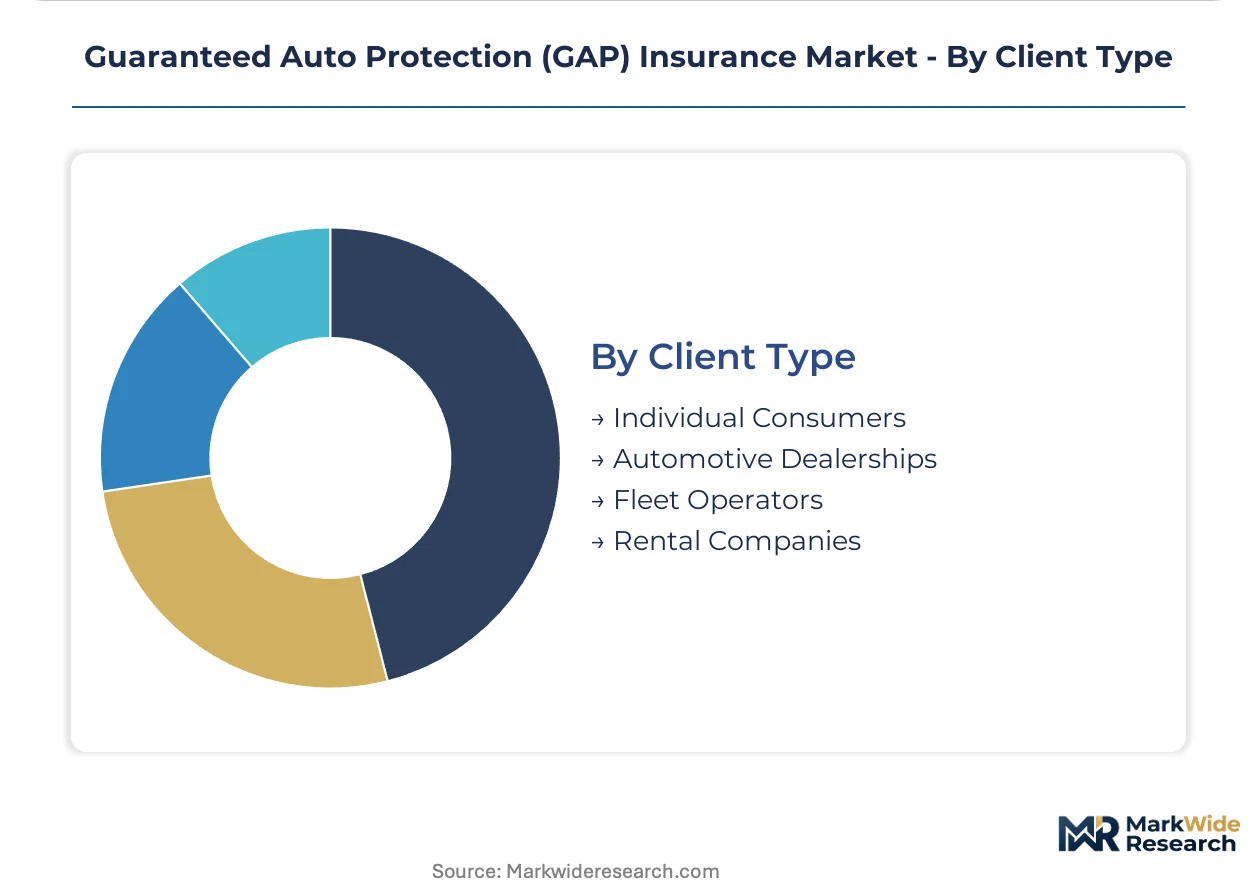
Client Type:
Customer risk profiles and policy utilization rates diverge sharply between individual borrowers with single-vehicle exposure and fleet operators managing portfolio-level depreciation risk.
- Individual Consumers:Retail borrowers financing personal vehicles, the historical core demand base. Concentrates in suburban markets across Georgia and North Carolina where extended loan terms elevate negative equity incidence.
- Automotive Dealerships:Franchise and independent dealers purchasing portfolio coverage or reinsuring self-administered programs. Volume correlates with new vehicle sales velocity in metropolitan Texas corridors.
- Fleet Operators:Commercial lessors and corporate vehicle pools requiring mileage-adjusted coverage structures. Emerging segment in California mobility-as-a-service markets where subscription ownership models proliferate.
- Rental Companies:Daily rental fleets managing residual value exposure on short-turnover vehicle inventories. Demand clusters in Florida tourism corridors with high fleet turnover rates.
Individual Consumers retain the largest share; Fleet Operators gain momentum as subscription models reshape vehicle ownership economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with subprime-heavy southeastern states showing elastic demand while coastal premium markets absorb replacement-cost riders with minimal friction. Regulatory disclosure mandates reshape distribution economics differently by jurisdiction.
United States
The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure standards that compress dealer markup participation. Extended loan terms among subprime borrowers in Georgia and North Carolina sustain negative equity windows where GAP protection retains value. Texas and Florida clusters concentrate replacement-cost demand amid luxury vehicle depreciation volatility.
Canada
Credit union penetration in Ontario and Quebec anchors embedded finance distribution with above-average attachment rates. Provincial insurance regulators coordinate rate filings through the Canadian Council of Insurance Regulators framework. British Columbia's public auto insurance system limits standalone GAP distribution to private supplemental channels.
Germany
KBA vehicle registration data informs residual value algorithms that compress pricing information asymmetry for underwriters. The EU Insurance Distribution Directive mandates standardized product disclosure across captive finance and independent broker channels. Bavaria's automotive manufacturing density supports OEM-integrated GAP programs through captive lender networks.
United Kingdom
Financial Conduct Authority oversight of add-on insurance products restricts point-of-sale bundling practices that historically sustained dealer margins. Extended personal contract purchase terms elevate negative equity incidence in suburban London markets. Midlands-based fleet operators pilot mileage-adjusted coverage structures for subscription ownership models.
Japan
METI coordination of fintech lending standards enables API-based GAP embedding in digital auto loan origination. Conservative loan-to-value ratios among regional bank borrowers limit standard policy penetration. Kansai manufacturing corridors concentrate OEM-integrated programs through captive finance subsidiaries.
Guaranteed Auto Protection (GAP) Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with legacy carriers leveraging captive agency density while digital entrants optimize quote-engine friction reduction. The market structures around three tiers: national carriers with multi-channel reach, regional specialists in credit union partnerships, and insurtech platforms disintermediating traditional distribution. Dominant competitive moves include embedded finance API integration and telematics-linked underwriting capability acquisition.
Among national carriers, Allstate, Progressive, and Nationwide occupy distinct positioning archetypes. Allstate represents the captive agency network model sustaining pricing power across direct and broker channels. Progressive exemplifies telematics-linked policy differentiation. Nationwide anchors its position through exclusive financial institution partnerships, particularly with credit unions and regional banks in high-penetration southeastern markets.
| Leading Market Players |
|---|
| Allstate |
| Liberty Mutual |
| Erie |
| American Family |
| Farmers |
| Nationwide |
| Progressive |
| Travelers |
| Auto-Owners |
| Others |
Supply & Pricing Matrix
Scale economies in captive finance operations concentrate underwriting capacity among national carriers with dealership network density, compressing price floors for standalone GAP products while elevating margin capture for embedded distribution through loan origination systems. This concentration simultaneously shapes supply chain configuration, as API-based policy administration platforms displace legacy mainframe integrations and redistribute value toward fintech-enabled credit unions and digital lenders.
Pricing Analysis
After-sales contract revenue from extended vehicle protection products drives lifetime value for dealership finance offices, embedding GAP premiums into 72-84 month loan structures as a high-margin attachment. Pricing stratifies across premium replacement-cost riders, standard loan-balance coverage, and economy limited-term policies differentiated by coverage window and exclusion density. Cost compression in the standard tier intensifies as primary auto insurers bundle total-loss protection into comprehensive policies, eroding standalone attachment rates. Subprime borrowers in southeastern states exhibit highest price sensitivity, while luxury electric vehicle purchasers in Texas and Florida absorb replacement-cost premiums with minimal friction.
Supply Chain Analysis
Dealer management system integration chokepoints underwrite distribution control, as F&I platform providers gate access to point-of-sale policy binding. Underwriting capacity concentrates in the United States, Canada, and Germany, with residual value algorithm development anchored in Michigan automotive clusters and KBA-linked German valuation platforms. Raw material dependencies include telematics hardware for usage-based pricing, API middleware for loan origination connectivity, and actuarial data feeds from vehicle registration databases. Single-source vulnerability in legacy policy administration systems threatens operational continuity as carriers migrate to cloud-native platforms. Distribution runs through captive finance subsidiaries, credit union embedded programs, and emerging direct-to-consumer quote engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
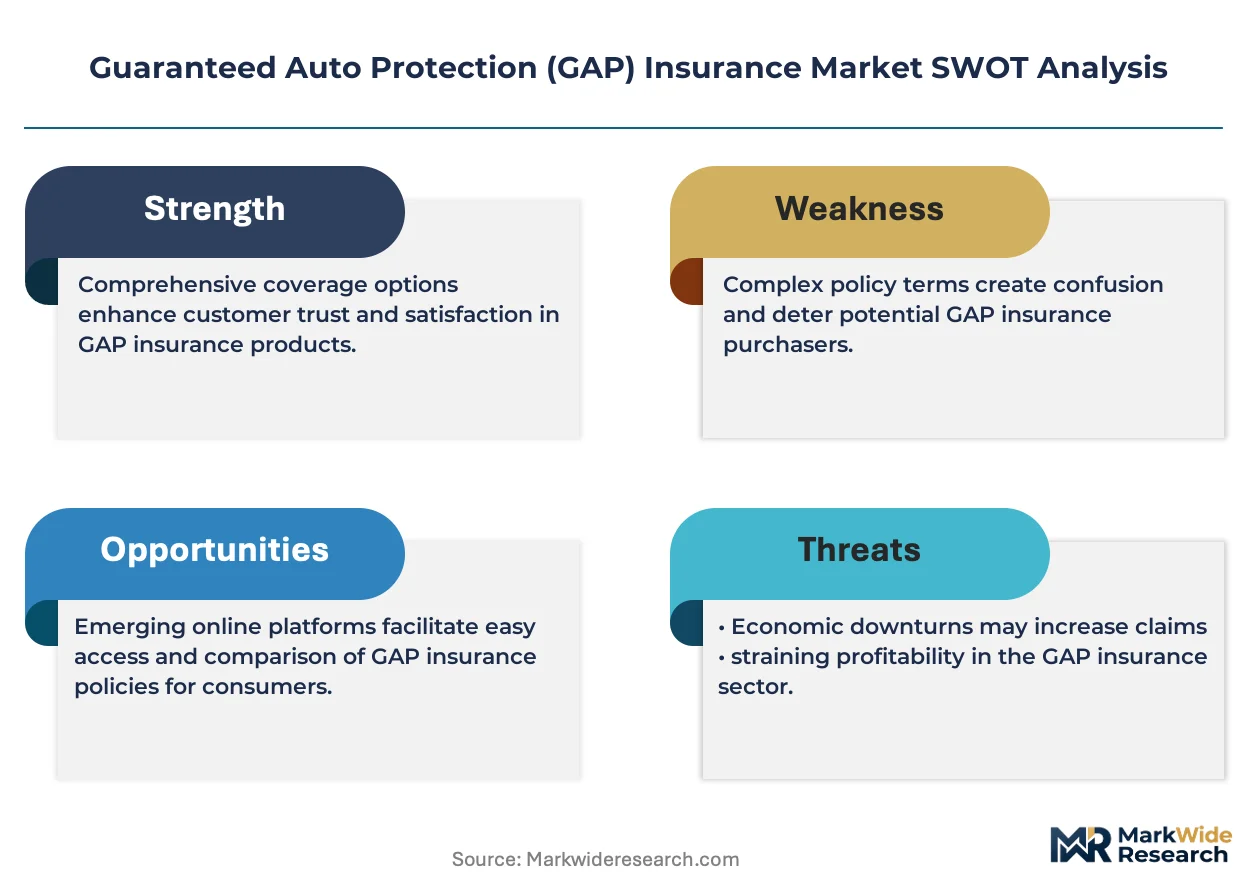
The GAP insurance market faces high-growth disruption from embedded finance platform proliferation, with the Consumer Financial Protection Bureau's disclosure mandates accelerating transparent point-of-sale integration and compressing opaque markup practices.
For Market Incumbents: Consolidate API infrastructure investments to defend against fintech disintermediation, prioritizing direct loan origination system connectivity that bypasses dealership finance office gatekeepers. Deepen backward integration into telematics data streams for dynamic risk pricing capability, offsetting substitution pressure from primary insurer bundled products. For New Entrants and Emerging Players: Differentiate on embedded finance workflow integration, targeting credit union and regional bank partnerships in high-penetration southeastern markets where legacy carrier relationships show friction. Penetrate fleet operator and mobility-as-a-service segments in California and Texas through mileage-adjusted coverage structures that incumbent actuarial platforms cannot easily replicate. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors insurtech platforms with proven API connectivity and captive finance carve-out opportunities. Long-term viability rests on embedded distribution infrastructure rather than standalone policy administration capability. Acquisition targets should demonstrate scalable loan origination integration and telematics underwriting readiness. The signal to watch is dealer management system provider consolidation, which would reshape point-of-sale access economics.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with Loan Origination Systems | Enables real-time GAP embedding at pre-approval, capturing borrowers before dealership contact. |
| Telematics-Linked Underwriting Development | Progressive's usage-based data streams enable dynamic risk pricing and proactive loss prevention. |
| Credit Union Partnership Expansion | Nationwide's exclusive relationships anchor volume in high-penetration southeastern states. |
| Replacement Cost Rider Product Launch | Premium pricing commands margin expansion in Texas and Florida luxury electric vehicle markets. |
| Embedded Finance Platform Acquisition | Fintech lender integrations disintermediate traditional dealership-centric distribution networks. |
Research Methodology
A standing panel of auto finance executives, dealership F&I managers, credit union lending officers, and insurance regulatory specialists provided ongoing calibration throughout the study period. Primary interviews with captive lender product development teams, independent agency principals, and state insurance commissioner staff were cross-validated against secondary sources including NAIC model law filings, CFPB enforcement action records, and vehicle registration database trends. Bottom-up policy volume estimates from distribution channel participants were triangulated with top-down market sizing derived from auto loan origination data and GAP attachment rate surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including policy type, coverage level, distribution channel, and client type alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves incorporating subprime auto finance expansion rates, extended loan term penetration, and embedded platform adoption trajectories. Forecast inputs included CFPB disclosure mandate implementation timelines and telematics device penetration in new vehicle sales.
Material uncertainties — regulatory restrictions on dealer markup participation, primary insurer bundling acceleration, and residual value algorithmic pricing compression — sit outside the modeled envelope. Forecasts reflect assumptions about embedded finance platform adoption curves and state-level insurance commissioner coordination on NAIC model law implementation. Practitioners should keep alternative scenarios live as Consumer Financial Protection Bureau enforcement priorities and fintech lending regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
US Motor Insurance Market