
 3D Surveillance Software Market | 2026-2036
3D Surveillance Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Surveillance Software Market Outlook
Enterprise security buyers is bifurcating between perimeter-defence incumbents and analytics-first adopters. Hexagon leverages its geospatial heritage to anchor defence and infrastructure contracts across NATO members. Surveill 3D competes on real-time volumetric rendering for urban command centres. Cambridge Pixel Ltd. specializes in radar-video fusion for maritime and border applications.
3D surveillance software constructs spatial depth models from multi-sensor inputs to enable volumetric threat detection and behavioural analytics in real time. The platform ingests LiDAR, stereo camera arrays, and millimetre-wave data to generate metrically accurate point clouds for automated object classification and tracking. Cloud-based software and edge computing deployments are capturing the fastest expansion as latency-sensitive sites adopt distributed processing architectures. AI-based analytics within the technology dimension commands premium pricing due to computational intensity and custom training requirements for specific facility geometries.
FCC spectrum allocations shape sensor interoperability in US deployments, while GDPR and the EU AI Act constrain biometric inference and automated decision thresholds across European installations. Health Canada's privacy frameworks influence procurement specifications for Canadian transportation hubs and federal facilities. Stakeholders must weigh regulatory fragmentation against the operational gains of cross-border standardisation in multi-national security networks.
Market Dynamics
Volumetric sensor fusion is compressing deployment timelines for critical infrastructure operators while GDPR and the EU AI Act impose algorithmic transparency mandates that reshape procurement specifications across NATO defence networks.
Growth Catalysts
- Critical infrastructure hardening:Power grid operators and transportation hubs are mandating depth-aware perimeter systems to replace planar camera networks. Germany's industrial automation clusters anchor European procurement volume.
- GDPR Article 35 compliance:Data protection impact assessments for biometric processing are accelerating privacy-preserving 3D analytics that anonymize subjects through skeletal abstraction rather than facial capture.
- Edge computing architectures:Latency-sensitive sites are distributing inference workloads to on-premise nodes, reducing backhaul costs for real-time volumetric rendering in urban command centres.
Market Restraints
- LiDAR sensor cost volatility:Solid-state emitter shortages and rare earth magnet dependencies in scanning assemblies create input price instability for hardware-software bundled deployments.
- Millimetre-wave spectrum licensing:FCC Part 15 constraints and national frequency allocation fragmentation limit cross-border interoperability for radar-video fusion systems in multi-national security networks.
- Point cloud storage economics:Metrically accurate spatial data generates petabyte-scale archives that strain enterprise IT budgets and complicate forensic retrieval workflows.
Strategic Opportunities
- Maritime perimeter gaps:Port authorities in Greece and Spain are underpenetrated for radar-video fusion despite EU Critical Entities Resilience Directive mandates for supply chain node protection.
- Neural radiance fields:Convergence of NeRF rendering with real-time volumetric capture enables photorealistic scene reconstruction from sparse sensor arrays, reducing hardware density requirements.
- Health Canada procurement frameworks:Federal facility specifications for transportation hubs are creating compliant product categories that domestic vendors can capture ahead of US competitors.
Industry Challenges
- Multi-sensor calibration expertise:Shortages of technicians capable of aligning LiDAR, stereo arrays, and millimetre-wave units within millimetric tolerance are extending deployment timelines.
- Legacy VMS integration:Incumbent video management software architectures lack native point cloud ingestion, forcing middleware development that fragments vendor support accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Surveillance Software Market |
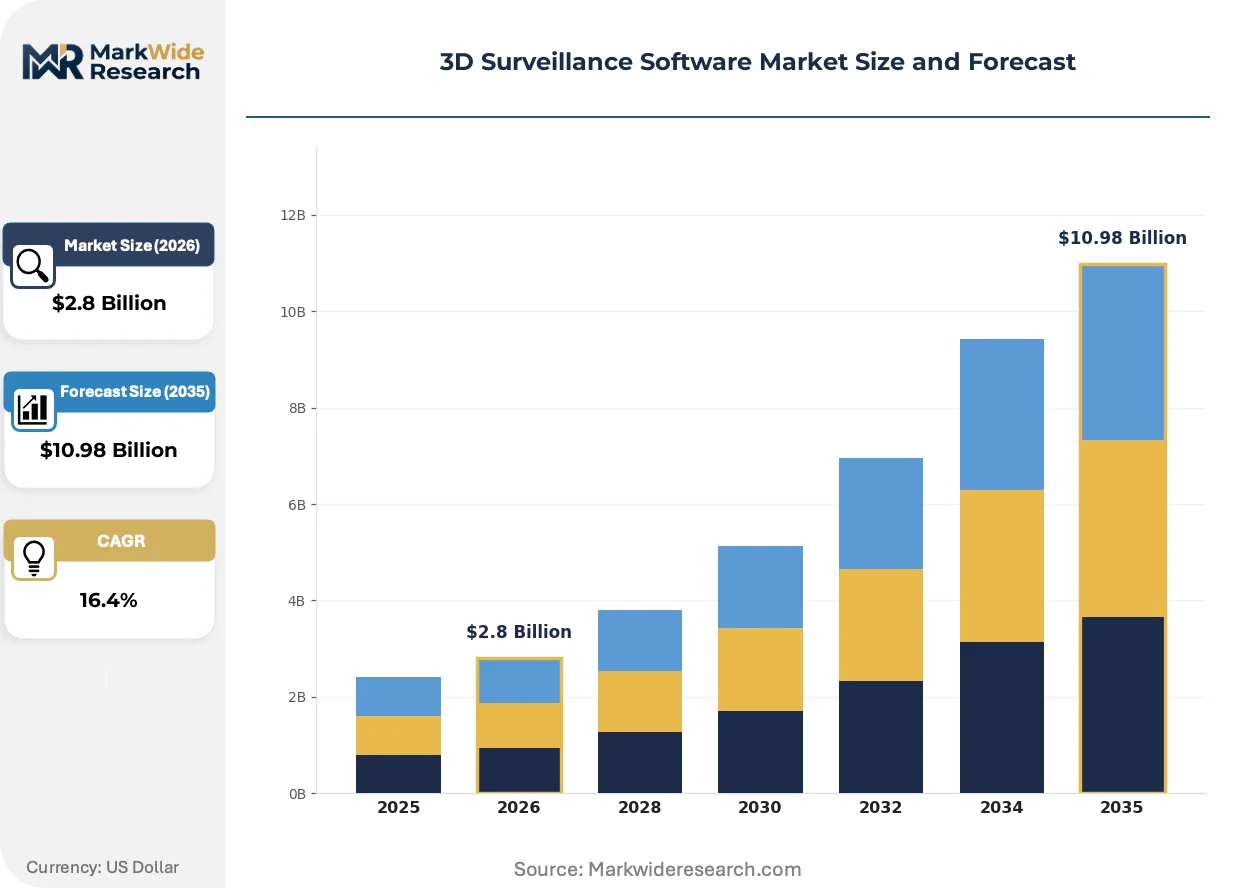
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solutions, Plugins, Cloud-Based Software Deployment: On-Premises, Cloud, Hybrid, Edge Computing End User: Government, Retail, Transportation, Industrial Technology: AI-Based, Machine Learning, Image Processing, IoT Integration |
| Companies Covered | Hexagon, Surveill 3D, Cambridge Pixel Ltd., Tacticware Resource Group LLC, Mirasys, Dallmeier electronic, Northern Digital Inc., Controp Precision Technologies Ltd, Senstar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Surveillance Software Market Strategic Shifts
Sensor hardware and inference algorithms are converging to enable standalone edge deployments that previously required rack-scale compute, while regulatory fragmentation is forcing modular compliance architectures.
Solid-state LiDAR is miniaturizing. Automotive-grade MEMS scanning modules originally developed for autonomous vehicles are migrating into security applications, enabling palm-sized volumetric sensors that mount on standard camera housings. Critical infrastructure operators in the Netherlands and Denmark are piloting these reduced-form-factor units for bridge and tunnel monitoring. The technology is miniaturizing deployment footprints and collapsing the distinction between perimeter camera upgrades and full 3D surveillance retrofits.
The EU AI Act's risk-based classification system entered force for high-risk biometric applications in February 2024. Systems performing real-time remote identification in publicly accessible spaces now require conformity assessment by notified bodies and algorithmic bias testing protocols. Defence and border security contractors serving European markets are restructuring product lines to segregate inference engines that trigger automated alerts from those supporting human-in-the-loop verification, with Germany's federal police procurement specifications now explicitly favouring the latter architecture.
Security-as-a-service models are displacing capital-heavy ownership structures. Municipal buyers and mid-sized commercial estates are subscribing to volumetric monitoring through managed detection providers that retain sensor hardware and algorithm ownership. The shift compresses customer switching costs and concentrates vendor-side balance sheet risk. France's smart city initiatives and Canadian municipal procurement frameworks are early adopters of this consumption pattern, with RFPs now specifying operational expenditure ceilings rather than upfront equipment budgets.
3D Surveillance Software Market Segmentation
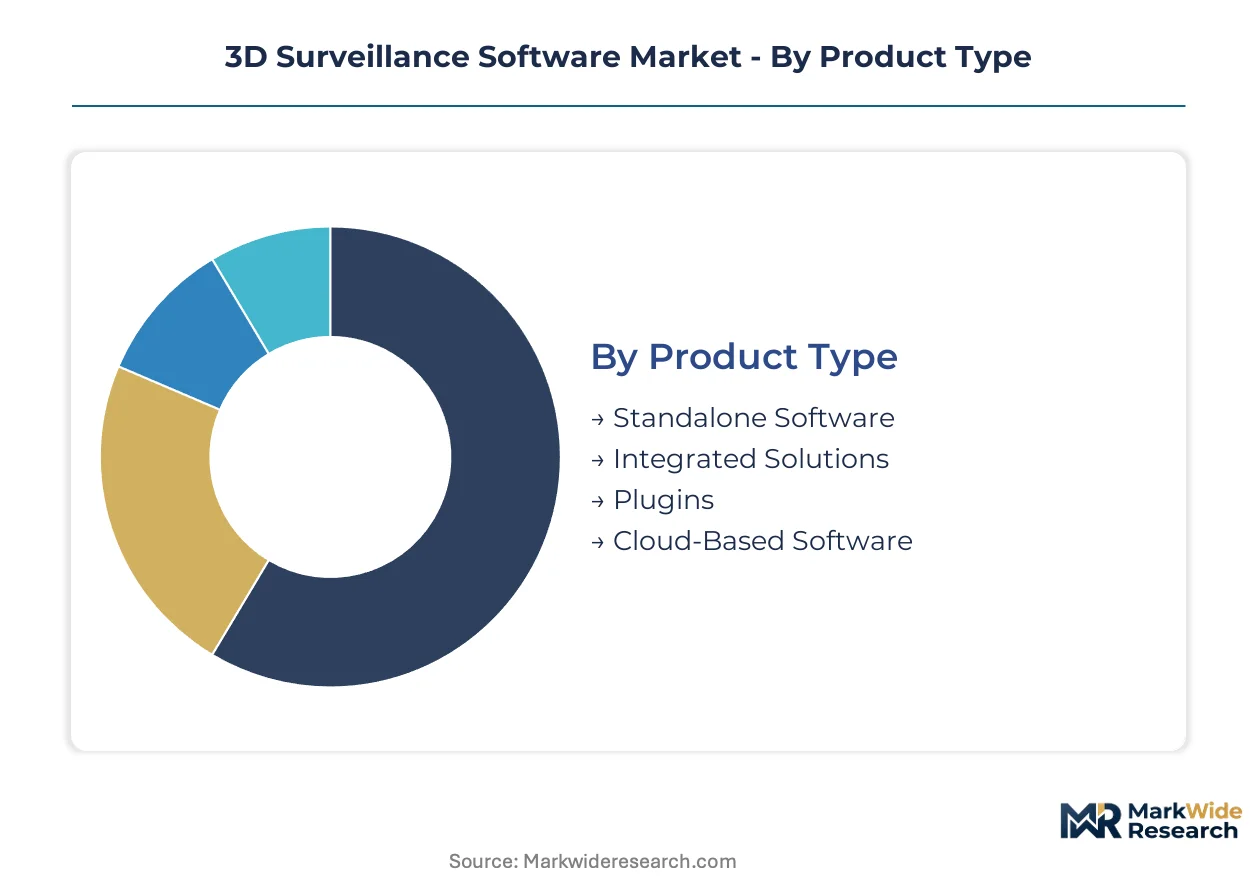
Segmentation in 3D surveillance software reveals how procurement specifications diverge across regulatory jurisdictions and operational risk profiles. Buyers select architectures based on data residency mandates, inference latency requirements, and integration complexity with legacy video management systems.
Product Type:
GDPR Article 35 data protection impact assessments and the EU AI Act's conformity requirements are bifurcating procurement between bundled hardware-software systems and modular software-only licenses that permit algorithmic transparency auditing.
- Standalone Software:Modular licenses deploy on customer-specified hardware, enabling algorithmic transparency documentation required by notified body assessments under EU AI Act high-risk system classifications. German federal police procurement now mandates this architecture for human-in-the-loop verification workflows.
- Integrated Solutions:Pre-validated sensor-software bundles compress deployment timelines for critical infrastructure operators facing compressed hardening deadlines. Netherlands bridge and tunnel monitoring pilots favor these configurations for reduced calibration complexity.
- Plugins:Middleware extensions retrofit point cloud ingestion into incumbent VMS architectures. France's smart city initiatives specify plugin compatibility to preserve existing municipal IT investments.
- Cloud-Based Software:Subscription models shift capital expenditure to operational budgets, aligning with Canadian municipal procurement frameworks that specify opex ceilings.
Established volume favors Integrated Solutions; emerging adoption favors Cloud-Based Software.
Deployment:
Latency tolerance thresholds and spectrum licensing constraints are reshaping where inference workloads execute across the compute continuum.
- On-Premises:Rack-scale deployments retain full data custody for defence and border security networks subject to national security classification protocols. NATO member specifications increasingly require air-gapped architectures for biometric processing.
- Cloud:Centralized processing serves forensic analytics and archival retrieval where real-time latency is non-critical. Health Canada's privacy frameworks constrain cloud eligibility for federal transportation hub deployments.
- Hybrid:Tiered architectures distribute real-time alerting to edge nodes while streaming aggregated metadata to cloud analytics. Spain's port authorities pilot this model under EU Critical Entities Resilience Directive compliance timelines.
- Edge Computing:Palm-sized MEMS LiDAR units with onboard inference collapse deployment footprints for latency-sensitive perimeter detection. Denmark's industrial automation clusters anchor European edge procurement volume.
Procurement concentration sits with On-Premises for defence networks; steepest expansion trajectory belongs to Edge Computing for civil infrastructure.
End User:
Threat models and compliance obligations vary sharply across facility types, driving divergent specifications for volumetric fidelity and retention architectures.
- Government:National security classifications mandate air-gapped deployments with algorithmic bias testing protocols. Germany's federal police specifications explicitly favor human-in-the-loop verification architectures.
- Retail:Loss prevention applications prioritize skeletal abstraction over facial capture to streamline GDPR compliance. French commercial estates are early adopters of security-as-a-service consumption models.
- Transportation:Maritime and aviation perimeter gaps require radar-video fusion for all-weather detection. Greek and Spanish port authorities remain underpenetrated despite EU directive mandates.
- Industrial:Power grid operators mandate depth-aware systems to replace planar camera networks, with Germany's automation clusters driving continental procurement volume.
Defence and critical infrastructure anchor current revenue; retail subscriptions are climbing the fastest.
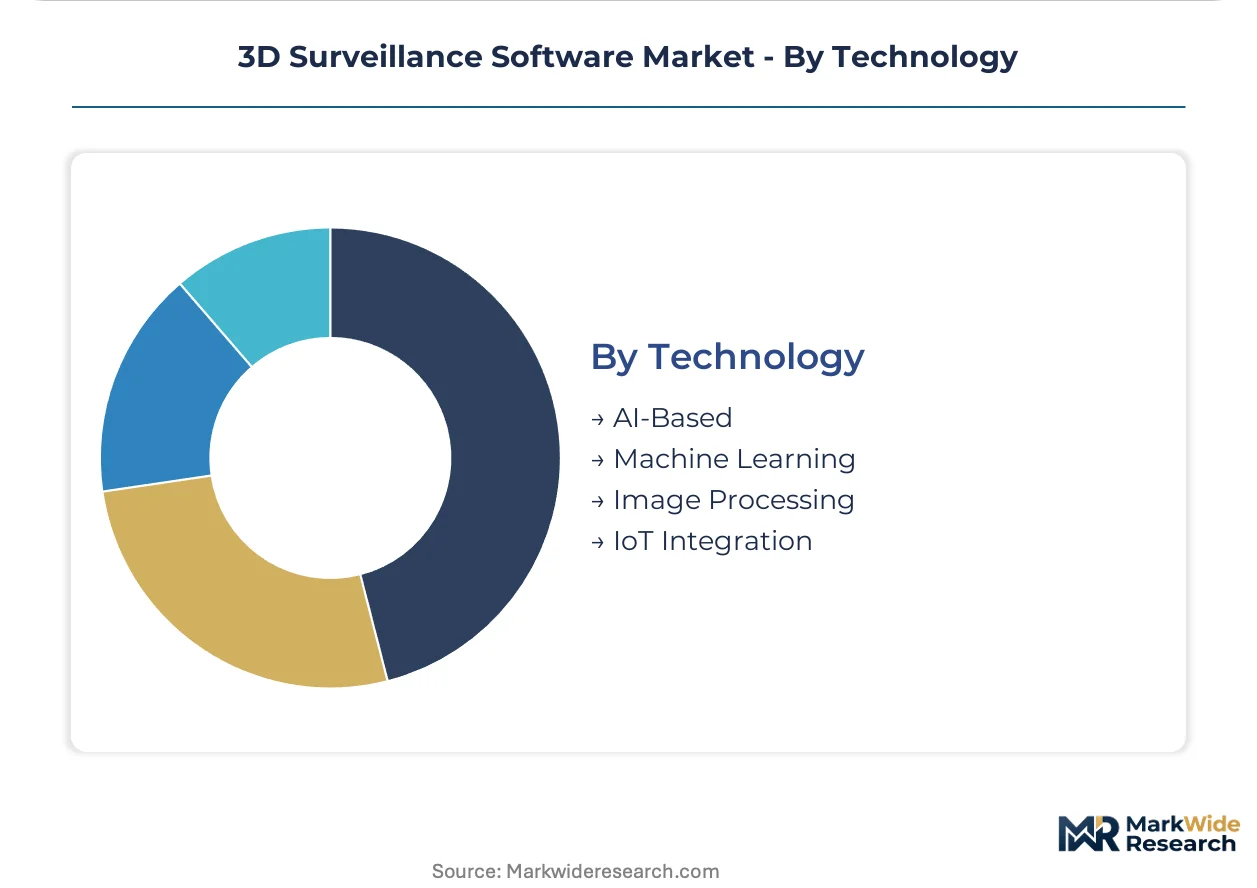
Technology:
Computational intensity and custom training requirements for facility-specific geometries are concentrating premium pricing in inference engine categories.
- AI-Based:Deep learning models for automated object classification command premium licensing due to training data acquisition costs and geometry-specific calibration. EU AI Act risk classifications now mandate conformity assessment for real-time remote identification applications.
- Machine Learning:Classical statistical methods support behavioral analytics with lower computational overhead and auditable decision boundaries. Preferred for GDPR Article 35 documentation requirements.
- Image Processing:Traditional computer vision pipelines integrate with legacy sensor arrays where neural network inference is computationally prohibitive.
- IoT Integration:Sensor fusion middleware harmonizes LiDAR, stereo arrays, and millimetre-wave units within millimetric calibration tolerance. Technician scarcity for multi-sensor alignment extends deployment timelines.
AI-Based analytics dominate premium contracts; Machine Learning gains share fastest in privacy-sensitive European deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters export edge-based surveillance architectures to Dutch critical infrastructure operators, establishing a trade-flow corridor that anchors European procurement volume for volumetric monitoring platforms.
Germany
Federal police specifications and industrial automation demand drive procurement concentration. The EU AI Act's high-risk system classifications mandate human-in-the-loop verification architectures for biometric processing. Bavaria's defence technology corridor anchors NATO-aligned contract awards for air-gapped deployments.
United States
Critical infrastructure hardening mandates and defence network modernisation accelerate depth-aware perimeter adoption. FCC Part 15 spectrum allocations constrain millimetre-wave sensor interoperability for cross-border security networks. Greater Boston's federal contractor cluster concentrates radar-video fusion development for maritime applications.
Netherlands
Bridge and tunnel monitoring pilots and smart port initiatives generate demand for miniaturised MEMS LiDAR units. GDPR Article 35 compliance requirements shape data protection impact assessments for biometric processing. The Randstad logistics corridor pilots palm-sized volumetric sensors for reduced-form-factor retrofits.
Canada
Transportation hub federal facility specifications and municipal procurement frameworks create compliant product categories. Health Canada privacy frameworks constrain cloud eligibility for biometric data processing. Ontario's Greater Toronto Area concentrates security-as-a-service subscription adoption under opex-ceiling RFP structures.
Spain
Port authority modernisation under EU Critical Entities Resilience Directive mandates drives radar-video fusion procurement. Algorithmic transparency requirements reshape defence contractor product lines for European market access. Barcelona's maritime logistics cluster pilots hybrid edge-cloud architectures for latency-tiered alerting.
3D Surveillance Software Market Competitive Environment
Listed leaders compete with private specialists across software licensing models, with bundled hardware-software systems commanding premium positioning against modular subscription offerings. Tiered competitive dynamics separate geospatial heritage incumbents from analytics-first challengers and radar-video fusion specialists. Three archetypes dominate: defence-anchored platform vendors, urban command centre real-time renderers, and maritime perimeter integrators. M&A activity concentrates on sensor fusion middleware capabilities, while strategic partnerships address multi-sensor calibration expertise scarcity.
Within the geospatial platform tier, Hexagon exemplifies defence and infrastructure contract anchoring across NATO procurement networks. Surveill 3D occupies a position among real-time volumetric rendering specialists targeting urban command centre deployments. Cambridge Pixel Ltd. represents radar-video fusion expertise for maritime and border security applications, reflecting the specialization-first competitive vector in European perimeter protection markets.
| Leading Market Players |
|---|
| Hexagon |
| Surveill 3D |
| Cambridge Pixel Ltd. |
| Tacticware Resource Group LLC |
| Mirasys |
| Dallmeier electronic |
| Northern Digital Inc. |
| Controp Precision Technologies Ltd |
| Senstar Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with solid-state LiDAR foundries lock in both supply access and price visibility for bundled hardware-software deployments, compressing margin volatility for critical infrastructure operators facing compressed hardening timelines under EU directive mandates.
Pricing Analysis
Next-generation MEMS-based volumetric sensors command a 40-60% premium over legacy mechanical scanning units, while prior-generation planar video analytics face price erosion from SaaS displacement. Three-tier pricing structure across premium AI-based inference engines, standard machine-learning pipelines, and economy image-processing tiers reflects certification grade and computational intensity. Pricing pressure stems from automotive-grade MEMS module commoditization feeding into security applications. Municipal buyers under opex-ceiling RFP structures exhibit highest price sensitivity; defence networks with national security classifications show lowest.
Supply Chain Analysis
Strategic stockpiling of rare earth magnets and indium phosphide emitters prevails over just-in-time preferences given solid-state LiDAR foundry concentration in Germany, Taiwan, and the United States. Supply chains draw from gallium arsenide wafer fabrication, precision MEMS foundry services, and specialized thermal management components. Single-source vulnerability concentrates in automotive-derived MEMS scanning module suppliers. Distribution runs through defence procurement networks and critical infrastructure operator direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by EU Critical Entities Resilience Directive enforcement timelines compressing procurement decisions across transportation and energy infrastructure.
For Market Incumbents: Fortify algorithmic transparency documentation capabilities to capture German federal police and NATO defence network contracts requiring notified body conformity assessment. Deepen backward integration into solid-state LiDAR foundry capacity to offset automotive sector demand competition for MEMS modules. Prioritize human-in-the-loop verification architectures as EU AI Act high-risk system classifications reshape product line requirements. For New Entrants and Emerging Players: Differentiate on privacy-preserving skeletal abstraction analytics that streamline GDPR Article 35 compliance for French retail and commercial estate buyers. Target Greek and Spanish port authority radar-video fusion gaps where EU directive mandates outpace incumbent penetration. Pursue security-as-a-service consumption models under Canadian municipal opex-ceiling procurement frameworks. For Investors and Strategic Acquirers: Capital is best deployed toward sensor fusion middleware specialists with multi-sensor calibration expertise, given technician scarcity extending deployment timelines. Long-term viability favors vendors with modular compliance architectures spanning GDPR, EU AI Act, and FCC spectrum allocation fragmentation. Watch for inflection when automotive MEMS LiDAR capacity expansion crosses into security application qualification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Middleware Acquisition | Addresses technician scarcity for LiDAR-stereo-radar calibration in NATO deployments. |
| Privacy-Preserving Analytics Development | Captures GDPR Article 35-compliant procurement from French municipal buyers. |
| MEMS LiDAR Foundry Partnership | Secures solid-state emitter supply against automotive sector demand competition. |
| Human-in-the-Loop Platform Launch | Aligns with German federal police specifications under EU AI Act risk classifications. |
| Security-as-a-Service Model Expansion | Matches Canadian municipal opex-ceiling RFP structures in Ontario transportation hubs. |
Study Parameters
Initial hypotheses were tested against primary input from critical infrastructure security directors, defence procurement officers, LiDAR sensor engineering leads, and municipal IT managers and refined through secondary validation across FCC spectrum allocation filings, EU AI Act implementing acts, Health Canada privacy framework updates, and customs data on solid-state emitter trade flows. Bottom-up deployment volume estimates triangulated with top-down addressable market sizing across the analysis window.
Variance decomposition across product type, deployment architecture, end-user facility classification, and inference technology intensity shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Model inputs incorporated EU directive compliance timeline acceleration, automotive MEMS module migration patterns, and municipal procurement framework shifts from capex to opex structures.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and automotive LiDAR capacity availability; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding GDPR Article 35 assessment completion rates and FCC Part 15 spectrum allocation stability. Revision becomes warranted when solid-state LiDAR foundry capacity utilization crosses automotive sector priority thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market