
 Asia Pacific Gas Detector Market | 2026-2036
Asia Pacific Gas Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Gas Detector Market Outlook
China's GB standards for hazardous gas monitoring is rebalancing the cost-of-entry calculus for foreign suppliers seeking manufacturing contracts. Industrial Scientific Corporation leverages its portable detector specialization to sustain premium positioning across Southeast Asian petrochemical sites. Riken Keiki Co., Ltd. anchors regional infrared sensor supply through captive Japanese fabrication capacity. Honeywell Analytics Inc. competes on integrated fixed-system architectures that dominate Chinese state-owned refinery tenders.
A gas detector is an instrument engineered to identify and quantify airborne concentrations of combustible, toxic, or oxygen-deficient gases through electrochemical reaction, infrared absorption, or catalytic bead oxidation, typically calibrated to trigger alarms at threshold limit values measured in parts per million. These devices serve as the primary life-safety layer in confined-space operations, continuous process monitoring, and leak detection protocols across heavy industry. Fixed detector installations command the largest installed base owing to permanent integration with distributed control systems, while portable units represent the fastest-expanding category as Asian contractors mobilize personal protective equipment fleets for temporary worksites. Electrochemical sensors retain mature dominance in carbon monoxide and hydrogen sulfide detection, though infrared technology captures margin-rich opportunities in methane quantification for LNG handling terminals.
China's MEE enforces ambient air quality disclosure rules that mandate real-time gas monitoring at designated industrial clusters, while Japan's METI certifies detector performance through JIS standards that constrain non-compliant imports. India's CEA electrical safety codes increasingly reference gas detection interlocks for transformer and switchgear rooms, broadening the addressable infrastructure base. Stakeholders must weigh the trade-off between sensor modularity and calibration infrastructure as multi-gas platforms gain preference over discrete single-gas units across Asian procurement specifications.
Market Dynamics
China's GB standards for hazardous gas monitoring are compressing the cost-of-entry calculus for foreign suppliers while elevating domestic certification requirements across industrial procurement chains.
Growth Catalysts
- Electrochemical sensor maturation:Carbon monoxide and hydrogen sulfide detection specifications now dominate refinery safety protocols across China's coastal processing corridors.
- India's CEA electrical safety codes:Gas detection interlocks for transformer rooms are broadening the addressable infrastructure base beyond traditional petrochemical applications.
- Australian mining safety mandates:Confined-space ventilation monitoring requirements are accelerating portable detector fleet deployments at Pilbara iron ore operations.
Market Restraints
- Japanese infrared sensor supply concentration:Captive fabrication capacity at domestic producers creates input bottlenecks for regional detector assembly.
- Calibration infrastructure gaps:Multi-gas platform complexity stretches service networks across Southeast Asian archipelago geographies.
- Import certification friction:Japan's METI JIS performance standards constrain non-compliant equipment entry into premium industrial segments.
Strategic Opportunities
- Vietnam's emerging LNG terminals:Methane quantification specifications for cryogenic handling create specification-grade demand for infrared sensing platforms.
- Cloud-connected monitoring convergence:Distributed control system integration with edge analytics is opening recurring-revenue service models.
- Indonesia's geothermal expansion:Hydrogen sulfide detection requirements at volcanic steam plants represent underpenetrated application terrain.
Industry Challenges
- Multi-gas calibration complexity:Cross-sensitivity management between electrochemical and infrared channels demands specialized field technician training.
- Legacy system integration:Retrofitting fixed detector networks into aging distributed control architectures at Chinese state-owned refineries extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Gas Detector Market |
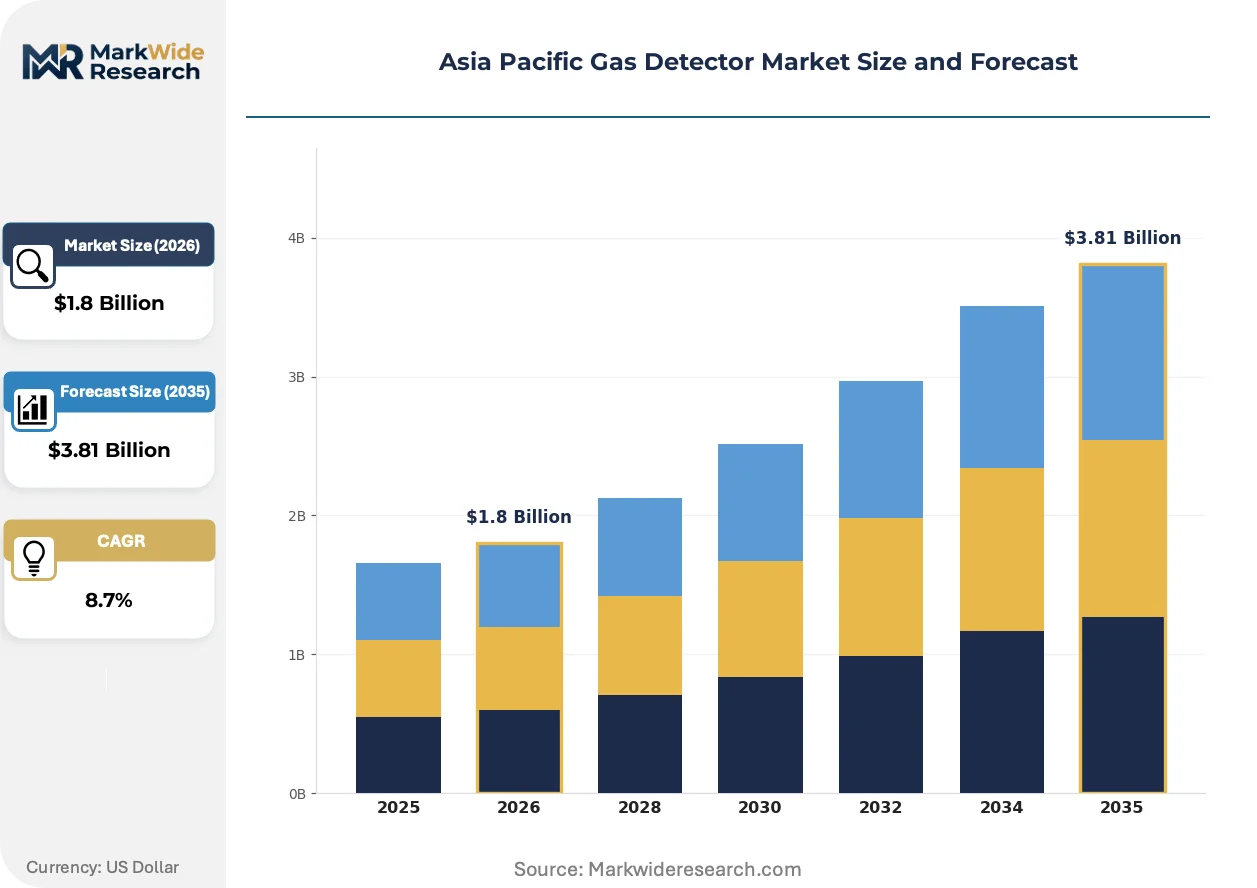
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Single-Gas Detectors Technology: Chemical Sensors, Infrared Sensors, Electrochemical Sensors, Ultrasonic Sensors End User: Manufacturing, Oil & Gas, Construction, Mining Application: Industrial Safety, Environmental Monitoring, Emergency Response, Occupational Health |
| Companies Covered | Industrial Scientific Corporation, Riken Keiki Co., Ltd., Honeywell Analytics Inc., Emerson Electric Co., Siemens AG, Drägerwerk AG & Co. KGaA, Teledyne Gas & Flame Detection, New Cosmos Electric, MSA Safety Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Gas Detector Market Strategic Shifts
Real-time ambient air quality disclosure mandates are compressing sensor refresh cycles while elevating data interoperability requirements across industrial monitoring architectures.
Photonic sensing platforms are integrating silicon photonics waveguide structures into compact methane detection modules. LNG terminal operators across Australia's Queensland Curtis Island complex are specifying these units for custody-transfer measurement applications. The technology is integrating optical pathlength miniaturization with thermal stability sufficient for tropical marine environments, compressing the form-factor advantage of traditional nondispersive infrared designs.
China's MEE enforcement of real-time industrial cluster monitoring is mandating open-data protocol compatibility for all new detector installations. Chemical processing corridors in Zhejiang and Jiangsu provinces must now publish airborne concentration feeds to provincial environmental platforms. Fixed-system architectures dominate procurement specifications as state-owned enterprises prioritize seamless regulatory reporting integration over portable unit flexibility.
Service unbundling is fragmenting traditional equipment-procurement relationships across Southeast Asian contractor fleets. Petrochemical maintenance contractors in Singapore and Malaysia are separating detector hardware acquisition from calibration and replacement sensor subscriptions. This pattern concentrates most visibly at temporary worksites where asset ownership economics favor operational expenditure models over capital deployment for personal protective equipment fleets.
Asia Pacific Gas Detector Market Segmentation
Equipment refresh cycles across Asia Pacific industrial corridors are compressing replacement timelines as regulatory disclosure mandates force sensor obsolescence. Procurement specifications now prioritize modularity and protocol compatibility over unit longevity, fragmenting traditional category boundaries.
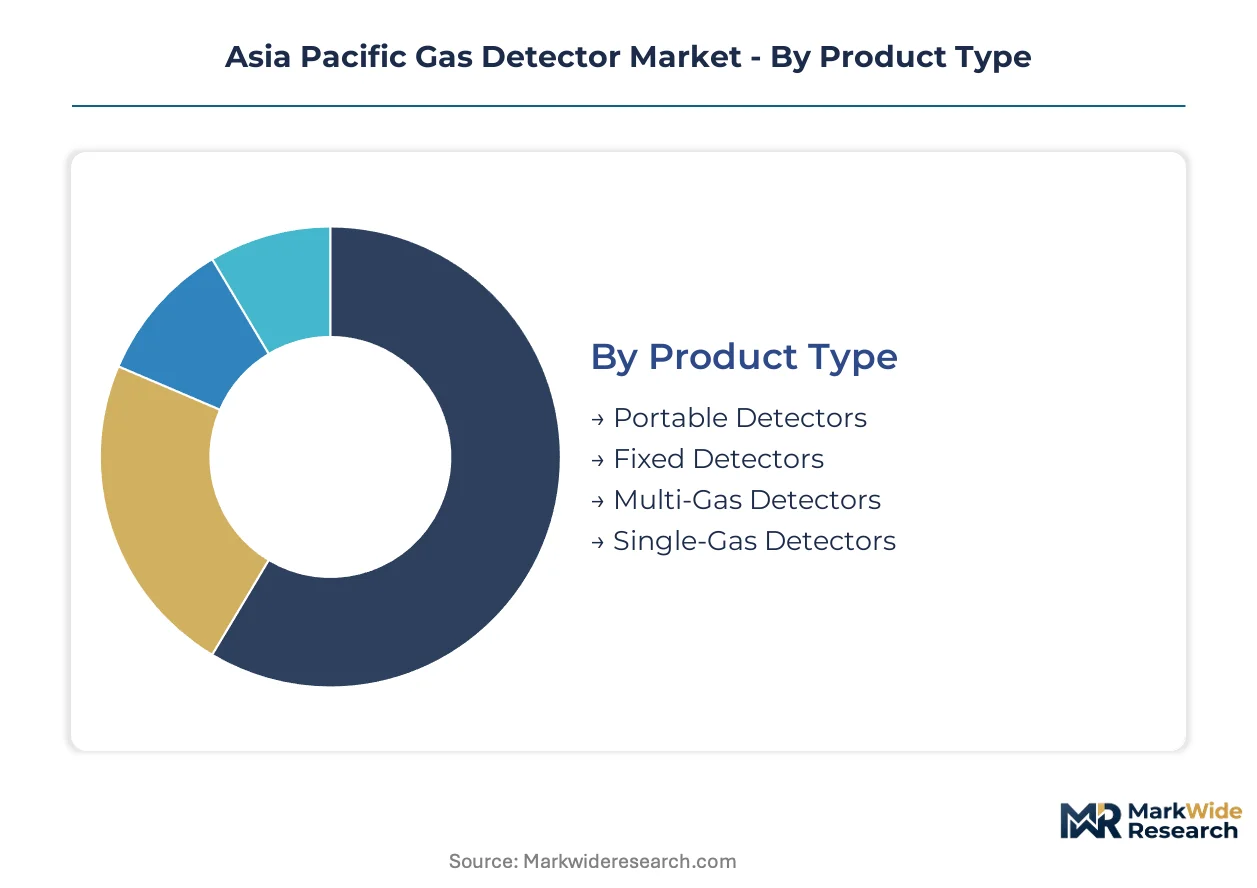
Product Type:
Upgrade dynamics vary sharply between permanently installed infrastructure and mobile protective fleets, with replacement economics driving divergent procurement patterns.
- Portable Detectors:Battery-powered units with wireless data transmission enable personal protective equipment deployment at temporary worksites. Australia's Pilbara mining contractors are expanding fleet sizes under confined-space ventilation mandates, while Southeast Asian petrochemical maintenance operators favor rental models over capital acquisition.
- Fixed Detectors:Hardwired installations integrate with distributed control systems for continuous perimeter monitoring. China's state-owned refineries in Zhejiang and Jiangsu provinces specify these for regulatory reporting compliance under MEE real-time disclosure rules.
- Multi-Gas Detectors:Modular platforms accommodate interchangeable electrochemical and infrared sensor cartridges. Procurement is shifting toward these units as calibration infrastructure matures across regional service networks.
- Single-Gas Detectors:Discrete units target specific hazard profiles at lower price points. Demand persists in cost-sensitive Indian transformer room applications under CEA electrical safety codes.
Volume placements concentrate in Fixed Detectors; the faster expansion belongs to Portable Detectors.
Technology:
Cost tiers separate mature electrochemical platforms from premium infrared specifications, with price-performance trade-offs determining adoption boundaries.
- Electrochemical Sensors:Catalytic reaction cells detect carbon monoxide and hydrogen sulfide through current measurement. These dominate refinery safety protocols across China's coastal processing corridors due to established calibration infrastructure and lower unit economics.
- Infrared Sensors:Non-dispersive absorption spectroscopy quantifies methane and hydrocarbon concentrations without oxygen dependence. LNG terminal operators at Australia's Queensland Curtis Island complex specify these for custody-transfer accuracy in cryogenic environments.
- Chemical Sensors:Metal oxide semiconductor films respond to reducing gases through resistance changes. These occupy economy-tier applications where precision requirements are less stringent.
- Ultrasonic Sensors:Acoustic leak detection identifies pressure differentials without direct gas contact. Deployment concentrates in high-value pipeline monitoring segments where fugitive emission prevention justifies premium positioning.
Revenue concentration sits with Electrochemical Sensors; margin expansion is climbing the fastest in Infrared Sensors.
End User:
Application intensity varies by sector hazard exposure, with regulatory enforcement depth determining procurement specification stringency.
- Oil & Gas:Exploration, production, refining, and LNG handling operations require continuous hydrocarbon monitoring. China's chemical processing belts and India's refining complexes drive specification-grade demand for integrated fixed-system architectures.
- Mining:Underground and open-pit extraction sites mandate confined-space gas detection. Australian iron ore operations in Western Australia deploy portable fleet expansions under ventilation monitoring requirements.
- Manufacturing:Chemical processing, electronics fabrication, and automotive plants require toxic gas surveillance. Procurement concentrates in China's industrial clusters where GB standards enforce hazardous gas monitoring compliance.
- Construction:Temporary worksites and infrastructure projects utilize rental-based portable detector deployment. Southeast Asian contractor fleets in Singapore and Malaysia are unbundling hardware acquisition from calibration subscriptions.
Installed base dominance rests with Oil & Gas; Mining is gaining share fastest on safety mandate acceleration.
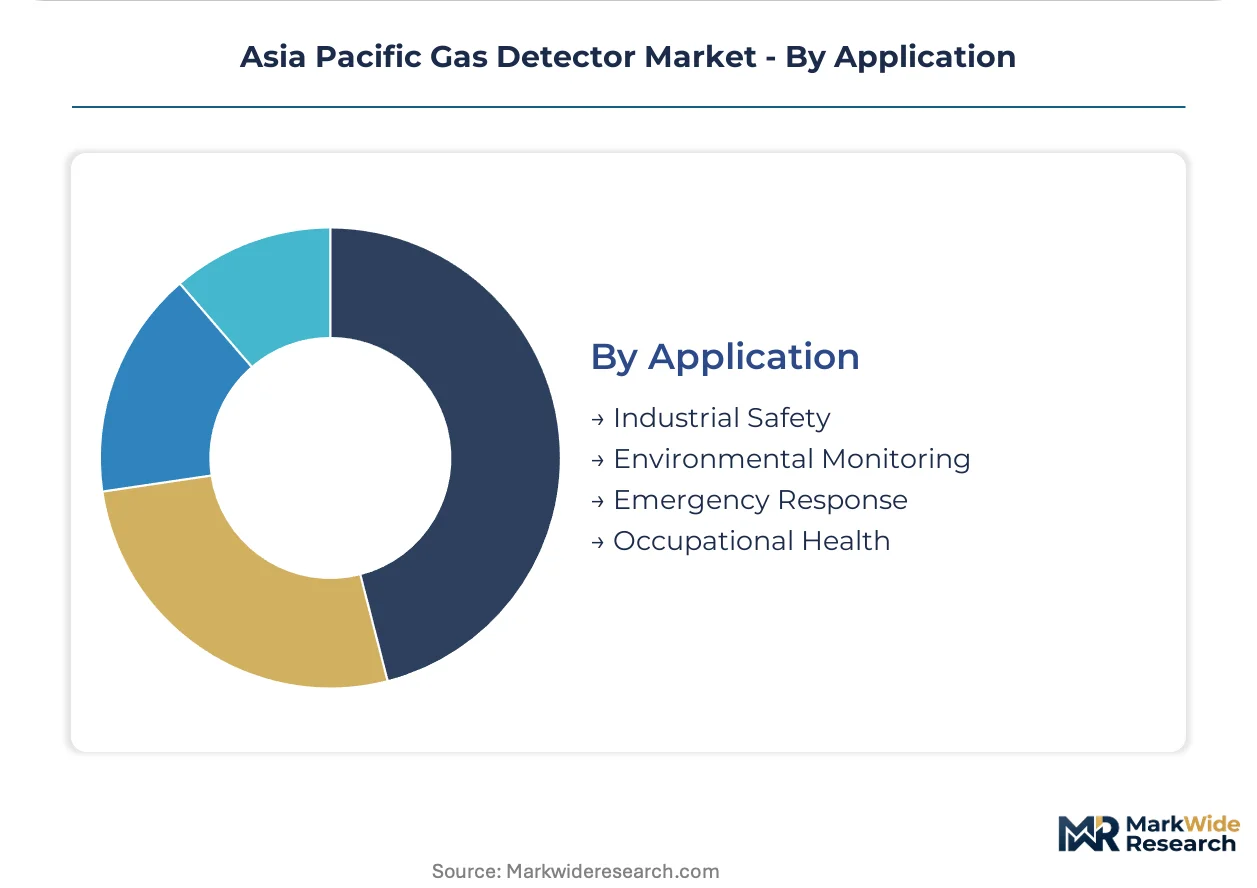
Application:
Customer type stratification separates compliance-driven institutional buyers from performance-oriented operational purchasers.
- Industrial Safety:Process hazard management and perimeter monitoring protect personnel and assets. Fixed detector networks at Chinese state-owned refineries prioritize seamless regulatory reporting integration.
- Environmental Monitoring:Ambient air quality surveillance and emission quantification support regulatory disclosure. China's MEE mandates real-time data publication from designated industrial clusters.
- Emergency Response:Rapid deployment capabilities for hazardous material incidents and disaster scenarios. Fire services and civil defense agencies specify ruggedized portable platforms.
- Occupational Health:Personal exposure assessment and workplace hygiene verification. Manufacturing facility managers in Japan deploy these under METI-certified JIS performance standards.
Procurement scale concentrates in Industrial Safety; Environmental Monitoring is expanding most quickly on disclosure mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's chemical processing corridors anchor regional demand concentration, with state-owned refineries in Zhejiang and Jiangsu provinces driving fixed-system procurement under MEE disclosure mandates. Special economic zones along coastal manufacturing belts compress deployment timelines through expedited regulatory approvals.
China
GB standards enforcement at hazardous industrial clusters accelerates fixed detector refresh cycles. MEE real-time ambient air quality disclosure rules mandate open-data protocol compatibility for new installations. Zhejiang and Jiangsu province refineries prioritize seamless regulatory reporting integration in procurement specifications.
Japan
Captive infrared sensor fabrication capacity sustains premium-tier supply positioning for regional detector assembly. METI JIS performance certification constrains non-compliant equipment entry into premium industrial segments. Kanto region electronics fabricators specify certified units under occupational health mandates.
India
CEA electrical safety code expansion into transformer and switchgear room applications broadens the addressable infrastructure base. Refining complexes along the western coast drive specification-grade demand for integrated fixed-system architectures. Gujarat and Maharashtra industrial corridors concentrate procurement activity.
Australia
Pilbara iron ore mining operations expand portable detector fleet deployments under confined-space ventilation monitoring requirements. Queensland Curtis Island LNG terminal operators specify infrared sensing platforms for custody-transfer measurement applications. Western Australian mining safety mandates accelerate personal protective equipment mobilization.
Vietnam
Emerging LNG terminal construction creates specification-grade demand for methane quantification capabilities. Cryogenic handling requirements at import facilities favor infrared sensing platform procurement. Southern coastal provinces concentrate infrastructure development activity.
Asia Pacific Gas Detector Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base separates into three strategic archetypes: integrated industrial automation conglomerates, sensor technology pure-plays, and safety equipment specialists. Consolidation pressure concentrates among mid-scale regional assemblers facing certification cost escalation. Dominant competitive moves include backward integration into captive sensor fabrication and geographic expansion through local certification partnerships.
Within the pure-play sensor tier, Riken Keiki Co., Ltd. and New Cosmos Electric exemplify Japanese specialists leveraging domestic fabrication infrastructure. Industrial Scientific Corporation occupies a position among portable detector specialists targeting Southeast Asian petrochemical maintenance markets. Honeywell Analytics Inc. and Emerson Electric Co. represent diversified conglomerates competing on integrated fixed-system architectures for Chinese state-owned refinery tenders.
| Leading Market Players |
|---|
| Industrial Scientific Corporation |
| Riken Keiki Co., Ltd. |
| Honeywell Analytics Inc. |
| Emerson Electric Co. |
| Siemens AG |
| Drägerwerk AG & Co. KGaA |
| Teledyne Gas & Flame Detection |
| New Cosmos Electric |
| MSA Safety Incorporated |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese sensor specialists anchor premium-tier supply through captive infrared fabrication capacity, compressing margin flexibility for foreign assemblers while elevating certification-driven pricing discipline across Asian procurement chains. This ownership structure concentrates pricing power upstream and fragments downstream bargaining leverage for detector integrators serving Chinese state-owned refineries.
Pricing Analysis
Lead-time premiums of 20-40% apply to certified units with sub-8-week delivery windows against standard 16-week cycles for non-certified inventory. Three-tier pricing structure across premium, standard, and economy levels separates METI JIS-certified Japanese units from GB-compliant Chinese alternatives and unbranded Southeast Asian imports. Cost compression in economy-tier portable detectors is intensifying because Indian transformer room contractors prioritize unit acquisition over calibration service bundling. Mining contractors in Australia's Pilbara region exhibit lowest price sensitivity, prioritating fleet reliability and sensor interchangeability over per-unit procurement economics.
Supply Chain Analysis
Infrared sensor supply rests on Japanese specialty chemical producers and domestic wafer fabrication facilities, with electrochemical cell production concentrated in South Korean and Chinese battery-grade chemical corridors. Key inputs span silicon photonics substrates, catalytic bead materials, and metal oxide semiconductor films. Single-source vulnerability concentrates in Japanese JIS-certified infrared emitter supply, where captive production serves domestic detector assemblers exclusively. Distribution runs through industrial safety distributors in Singapore and direct OEM relationships for Chinese refinery tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic sensing platforms are displacing traditional nondispersive infrared architectures across LNG terminal specifications, compressing refresh cycles and elevating protocol compatibility requirements. Incumbents and entrants must calibrate positioning against this technology-transition timeline.
For Market Incumbents: Deepen backward integration into electrochemical sensor fabrication to defend margin position against modular platform commoditization. Secure GB certification partnerships in Zhejiang and Jiangsu provinces to maintain access to Chinese state-owned refinery procurement channels. Invest in cloud-connected calibration infrastructure to capture recurring-revenue service models as Southeast Asian contractors unbundle hardware from operational expenditure contracts.
For New Entrants and Emerging Players: Direct-to-contractor digital rental platforms offer the most penetrable route for portable detector fleet penetration in Singapore and Malaysian petrochemical maintenance markets. Target Indonesia's geothermal expansion corridor for hydrogen sulfide detection specifications where established vendor presence remains thin. Lead with subscription-based calibration services to offset capital acquisition resistance among Southeast Asian construction contractors.
For Investors and Strategic Acquirers: Vietnamese LNG terminal commissioning schedules are the leading indicator that specification-grade infrared demand will accelerate through the projection horizon. Acquire mid-scale regional assemblers with existing METI JIS certification pathways rather than building compliance infrastructure de novo. Monitor MEE enforcement intensity at Zhejiang chemical clusters as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive electrochemical cell production secures margin control against Japanese infrared supply concentration. |
| Cloud-Connected Platform Launch | Edge analytics integration with distributed control systems opens recurring-revenue service models at Chinese refineries. |
| GB Certification Partnership | Local compliance pathways unlock state-owned enterprise procurement channels in Jiangsu and Zhejiang provinces. |
| Calibration Infrastructure Expansion | Regional service networks address multi-gas platform complexity gaps across Southeast Asian archipelago geographies. |
| Photonic Sensing Module Development | Silicon photonics waveguide structures capture custody-transfer specifications at Australian LNG terminals. |
Study Parameters
Trade databases, customs filings, and industrial safety equipment registration records formed the secondary backbone, supplemented by plant manager interviews at Chinese coastal refineries, procurement leads at Indian electrical infrastructure contractors, and aftermarket service heads at Australian mining operations. Primary fieldwork combined bottom-up unit deployment tracking with top-down market sizing validation across the analysis window. Triangulation across stakeholder inputs and secondary source reconciliation addressed data fragmentation inherent to regional distributor networks.
Historical trendline analysis of fixed versus portable detector deployment ratios informed the segmentation-level projection framework, with technology transition curves modeled across electrochemical, infrared, and emerging photonic sensing platforms. End-use intensity factors incorporated oil and gas refining capacity expansions, mining safety mandate enforcement depth, and CEA electrical code adoption timelines. CAGRs derived from volume-weighted average replacement cycle compression and specification-grade procurement mix shifts.
The model holds under steady MEE enforcement intensity and stable Japanese sensor supply capacity; deviation in GB standard revision timing or METI certification barrier elevation would shift demand concentration patterns. Forecasts reflect documented assumptions regarding regulatory disclosure mandate proliferation and technology substitution rates. A small set of named triggers—Vietnamese LNG terminal commissioning schedules, Indonesian geothermal project approvals, and Indian CEA code expansion into distribution infrastructure—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market