
 Safety Instrumentation Systems Market | 2026-2036
Safety Instrumentation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Instrumentation Systems Market Outlook
Software-defined safety logic is expanding as a recurring revenue layer, shifting vendor economics from hardware shipment toward continuous validation services. Honeywell International Inc. leverages its distributed control heritage to bundle safety subscriptions with process automation renewals. Emerson Electric Co. anchors its position through deep calibration and proof-testing service contracts tied to SIS lifecycle management. Yokogawa Electric Corporation differentiates by embedding cybersecurity monitoring within its safety system maintenance offerings.
Safety instrumentation systems comprise sensors, logic solvers, and final control elements engineered to SIL-rated reliability thresholds, typically achieving probability of failure on demand metrics between 10⁻¹ and 10⁻⁵ depending on safety integrity level classification. These architectures execute emergency shutdown, burner management, and fire-and-gas protection functions in hazardous process environments. Emergency shutdown systems occupy the largest installed base across hydrocarbon processing, while safety PLCs represent the fastest-expanding category as batch and discrete manufacturers replace hardwired relay logic with programmable fail-safe controllers. Quantum safety systems remain nascent but attract R&D allocation from majors seeking deterministic latency advantages in complex integrated operations.
IEC 61508 and IEC 61511 shape functional safety design standards, while ISA-84 governs process sector implementation in North American jurisdictions. The EPA's Risk Management Program and OSHA's Process Safety Management standard mandate systematic safety system verification, directly sustaining replacement demand. Manufacturers and end users must monitor convergence between functional safety and industrial cybersecurity standards, as IEC 62443 adoption begins conditioning market access for next-generation architectures.
Market Dynamics
Integrated safety architectures are compressing hardware replacement cycles as oil and gas operators consolidate distributed control and emergency shutdown layers into unified platforms, forcing legacy relay-based suppliers to pivot toward software-validated service models or exit.
Growth Catalysts
- IEC 61511 Compliance Mandates:Process industries in the United States Gulf Coast petrochemical corridor face intensified third-party certification audits, driving systematic replacement of pre-2003 safety instrumented systems.
- Burner Management Modernization:Refinery operators are retrofitting fired heater protection with SIL-rated programmable controllers to satisfy OSHA Process Safety Management enforcement priorities.
- Hydrogen Economy Infrastructure:Electrolyzer and ammonia synthesis projects in Germany and Saudi Arabia specify integrated fire-and-gas detection with safety PLC backbones from project conception.
Market Restraints
- Semiconductor Input Volatility:Safety PLC logic solver production depends on automotive-grade microcontrollers subject to allocation constraints from TSMC and Samsung foundry capacity.
- Specialized Engineering Concentration:Functional safety certification competence clusters in Norway, Germany, and Texas, creating talent access bottlenecks for projects elsewhere.
- Extended Proof-Testing Intervals:Advanced sensor diagnostics reduce mandatory shutdown frequency, compressing recurring service revenue for installed base maintenance providers.
Strategic Opportunities
- Indian Refinery Expansion:Reliance Industries and Indian Oil Corporation greenfield projects lack legacy hardwired safety infrastructure, enabling direct specification of integrated safety PLCs without migration complexity.
- Cyber-Physical Convergence:IEC 62443 certification for safety instrumented systems creates first-mover advantage for vendors bundling intrusion detection with functional safety validation.
- Modular Process Intensification:Pharmaceutical and specialty chemical manufacturers deploying skid-mounted production units specify pre-certified safety packages, shifting specification authority from EPCs to module fabricators.
Industry Challenges
- TUV Rheinland Exida Certification Backlogs:SIL verification timelines stretch to fourteen months for novel sensor architectures, delaying project commissioning and penalty clauses.
- Legacy System Archaeology:Brownfield installations lack as-built documentation for 1980s-era relay logic, forcing expensive reverse engineering before programmable migration.
- Cross-Domain Competency Requirements:Safety system engineers must now demonstrate IEC 62443 cybersecurity literacy alongside traditional IEC 61508 probabilistic calculation skills.
Report Scope
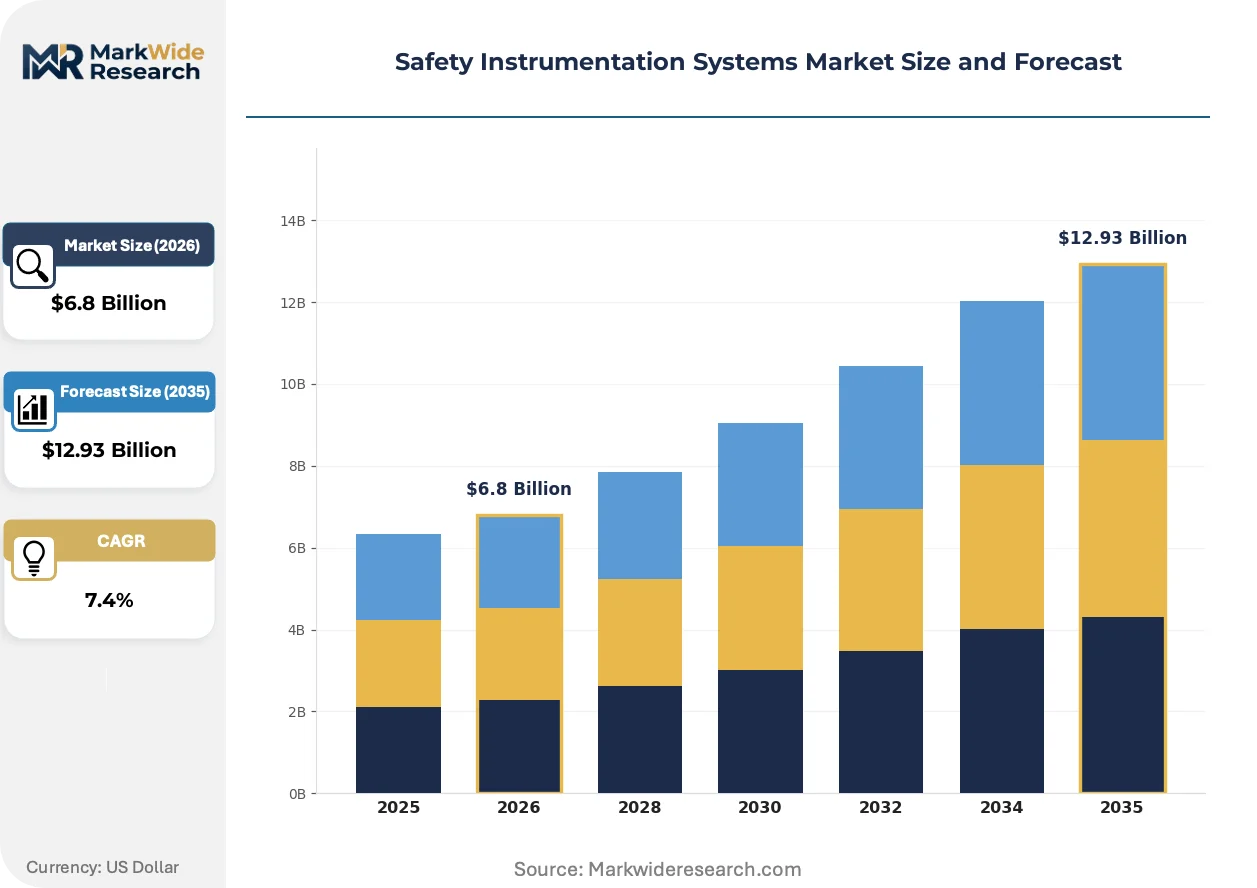
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Instrumentation Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Shutdown Systems, Fire & Gas Systems, Safety PLCs, Alarm Monitoring Systems End User: Oil & Gas, Chemical Processing, Power Generation, Manufacturing Technology: Industrial Ethernet, Fieldbus, Wireless Communication, Quantum Safety Systems Application: Process Safety, Industrial Automation, Environmental Monitoring, Machine Safety |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Rockwell Automation Inc., Siemens AG, Schneider Electric SE, Yokogawa Electric Corporation, HIMA Paul Hildebrandt GmbH, ABB Ltd., SIS-TECH Solutions LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Instrumentation Systems Market Strategic Shifts
Deterministic Ethernet protocols and embedded machine learning are redefining safety system architecture, compressing response latencies while expanding diagnostic coverage beyond traditional hardware redundancy approaches.
WirelessHART safety instrumented functions are integrating SIL 2-capable sensor networks into emergency shutdown architectures, enabling retrofit of tank farm and pipeline monitoring without explosive-area cabling costs. Offshore platform operators in the North Sea and Brazil pre-salt basins are piloting these configurations to reduce topside weight and installation man-hours. The technology is integrating proof-test automation that triggers sensor stimulus verification during production without process interruption.
REACH restrictions on per- and polyfluoroalkyl substances are forcing sensor manufacturers to reformulate sealing materials and cable insulation compounds used in safety instrumented systems deployed across European chemical processing. The regulation's industrial consequence is a twelve-to-eighteen-month qualification cycle for alternative fluoropolymer replacements in high-temperature applications. German BASF and Bayer site operators are most affected, accelerating sourcing audits to lock in compliant material streams before 2026 enforcement deadlines.
After-sales service unbundling is fragmenting traditional lifecycle contracts as end-users disaggregate hardware warranty, software maintenance, and TÜV re-certification into separate procurement events. EPC firms in the Middle East are driving this pattern, insisting on multi-vendor safety architecture support to avoid single-source dependency. Saudi Aramco and ADNOC project specifications now mandate open protocol interoperability, preventing proprietary lock-in through exclusive service agreements.
Safety Instrumentation Systems Market Segmentation
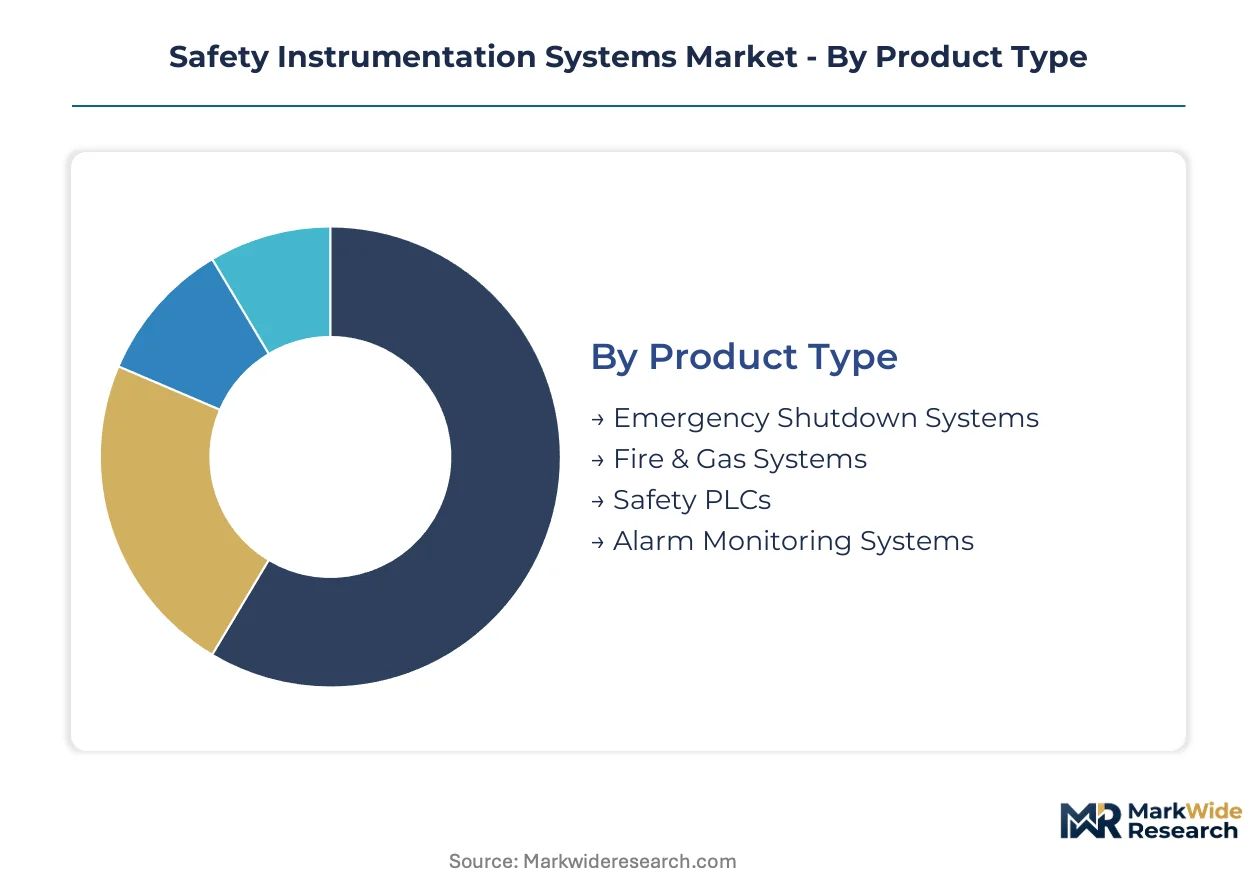
Safety instrumentation systems fragment across four distinct classification axes, each reflecting different procurement priorities and technical specifications. Product type segmentation reveals the hardware-software boundary where vendor economics shift most dramatically. End-user and application dimensions expose divergent compliance burdens and replacement cycles across hazardous industries.
Product Type:
The customization-to-standardization spectrum spans from fully engineered emergency shutdown architectures to commoditized alarm monitoring platforms with pre-validated logic libraries.
- Emergency Shutdown Systems:These architectures integrate sensors, logic solvers, and final control elements achieving SIL 3 reliability thresholds for process isolation. Hydrocarbon processing operators on the United States Gulf Coast concentrate procurement here, driven by EPA Risk Management Program audit intensification and OSHA Process Safety Management enforcement.
- Safety PLCs:Programmable fail-safe controllers replace hardwired relay logic with certified software-validated architectures. Batch and discrete manufacturers in Germany and India specify these for burner management retrofit projects, attracted by reduced wiring complexity and remote diagnostic capabilities.
- Fire & Gas Systems:Detection networks for combustible and toxic gas monitoring with integrated suppression activation.
- Alarm Monitoring Systems:Operator interface platforms consolidating safety alerts from distributed field devices.
Most installed capacity flows through Emergency Shutdown Systems. Expansion is steepest in Safety PLCs.
End User:
Volume concentration tilts toward capital-intensive process industries with mature regulatory frameworks, while margin opportunity clusters in emerging hydrogen infrastructure with first-mover specification windows.
- Oil & Gas:Upstream, midstream, and downstream operators deploy the most extensive safety instrumented function portfolios, from wellhead emergency shutdown to refinery fire-and-gas protection. Saudi Aramco and ADNOC project specifications now mandate open protocol interoperability, preventing proprietary lock-in through exclusive service agreements.
- Chemical Processing:Specialty chemical and petrochemical manufacturers face REACH restrictions on per- and polyfluoroalkyl substances in sensor sealing materials. German BASF and Bayer site operators accelerate sourcing audits to lock in compliant material streams before enforcement deadlines.
- Power Generation:Coal, gas, and nuclear facilities with turbine protection and boiler safety requirements.
- Manufacturing:Discrete and batch production with machinery safeguarding and robot cell interlocking.
Revenue gravity centers on Oil & Gas. Chemical Processing is gaining share fastest.
Technology:
Latency requirements and diagnostic coverage define the architectural choice between deterministic wired protocols and emerging wireless configurations.
- Industrial Ethernet:Deterministic protocols such as PROFINET and EtherNet/IP compress response latencies below ten milliseconds for integrated safety-DCS architectures. Major process automation vendors leverage this backbone to bundle safety subscriptions with control system renewals.
- Wireless Communication:WirelessHART safety instrumented functions enable SIL 2-capable sensor networks without explosive-area cabling costs. Offshore platform operators in the North Sea and Brazil pre-salt basins pilot these configurations to reduce topside weight and installation man-hours.
- Fieldbus:Foundation Fieldbus and PROFIBUS PA legacy installations with established device description libraries.
- Quantum Safety Systems:Experimental architectures exploiting quantum key distribution for tamper-evident safety communication.
Fieldbus retains the largest installed base. Wireless Communication is climbing the fastest.
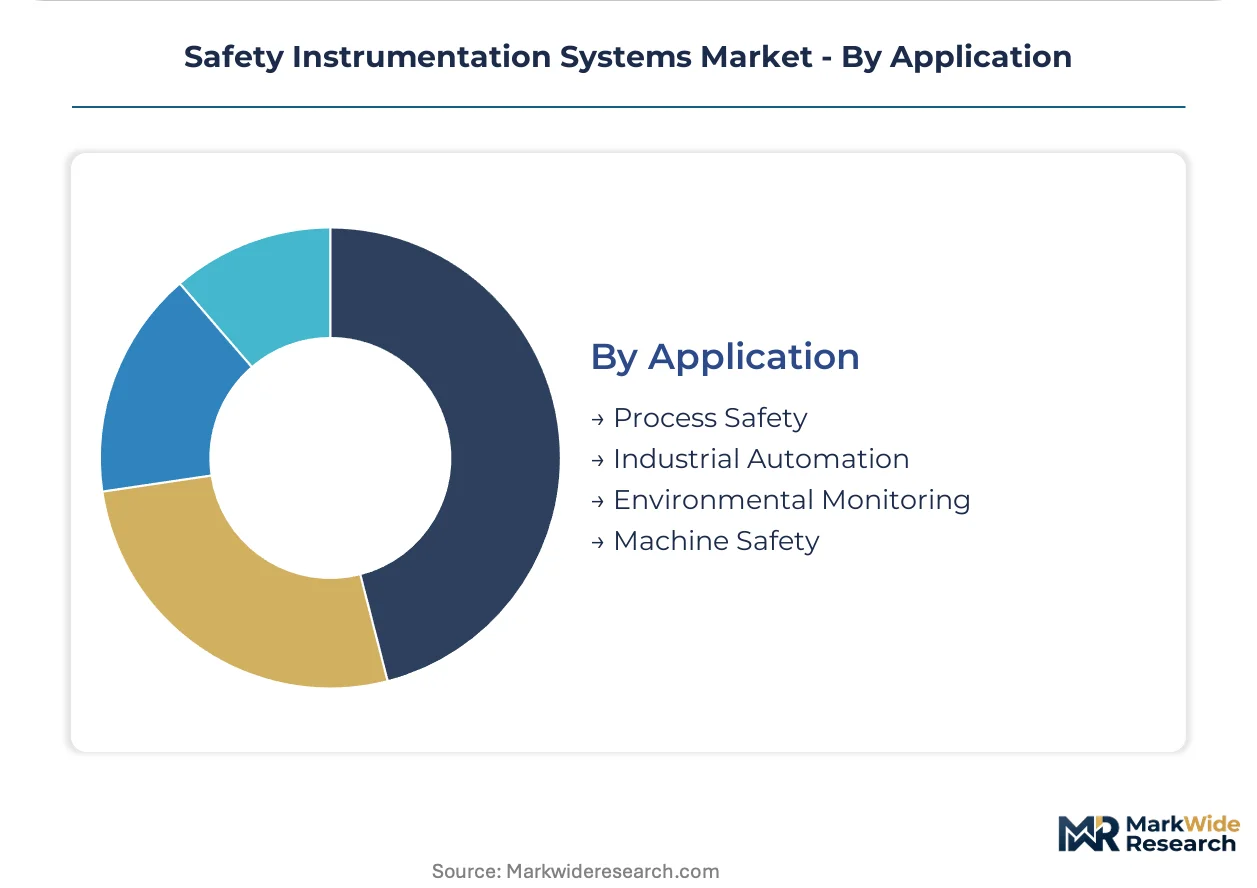
Application:
Functional scope ranges from catastrophic event prevention to occupational hazard reduction, with regulatory intensity scaling accordingly.
- Process Safety:Prevention of fires, explosions, and toxic releases through emergency shutdown and pressure protection. IEC 61511 compliance mandates in the United States Gulf Coast petrochemical corridor drive systematic replacement of pre-2003 safety instrumented systems.
- Industrial Automation:Integration of safety logic with motion control and batch sequencing. Pharmaceutical manufacturers deploying skid-mounted production units specify pre-certified safety packages, shifting specification authority from EPCs to module fabricators.
- Environmental Monitoring:Emission detection and containment verification for regulatory reporting.
- Machine Safety:Point-of-operation guarding and interlocking for industrial machinery.
Process Safety commands the dominant share. Industrial Automation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Gulf Coast operators outpace German chemical manufacturers in safety system replacement velocity, while Saudi Arabian greenfield projects bypass legacy migration entirely. National regulatory frameworks and industrial cluster concentration determine procurement patterns across major economies.
United States
EPA Risk Management Program audits and OSHA Process Safety Management enforcement drive systematic replacement of pre-2003 safety instrumented systems. The Gulf Coast petrochemical corridor concentrates demand in Texas and Louisiana refineries. Houston-area engineering procurement contractors specify integrated safety-DCS architectures for brownfield modernization projects.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force BASF and Bayer site operators to accelerate sourcing audits for compliant sensor sealing materials. ECHA enforcement deadlines approaching 2026 compress qualification cycles for alternative fluoropolymer replacements. The BASF Ludwigshafen complex and Bayer Leverkusen facilities anchor European chemical processing safety system demand.
Saudi Arabia
Saudi Aramco and SABIC greenfield projects specify integrated safety PLCs without legacy hardwired infrastructure migration complexity. SFDA-equivalent industrial safety mandates align with international IEC 61511 certification requirements. The Jubail Industrial City and Yanbu petrochemical complexes represent concentrated specification authority for EPC contractors.
India
Reliance Industries and Indian Oil Corporation refinery expansions enable direct integrated safety PLC specification without brownfield constraints. BIS standards adoption for process safety equipment accelerates domestic certification requirements. The Jamnagar refinery complex and Gujarat petrochemical corridor concentrate procurement for mega-project engineering firms.
Brazil
ANVISA-aligned industrial safety regulations and Petrobras pre-salt development sustain offshore platform safety system demand. WirelessHART pilot configurations reduce topside weight for floating production installations. The Santos Basin pre-salt fields and Rio de Janeiro engineering cluster anchor South American procurement.
Safety Instrumentation Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors capturing premium-tier positions while regional system integrators serve mid-market retrofit demand. The vendor base organizes around three archetypes: diversified industrial conglomerates with process automation heritage, pure-play functional safety specialists, and engineering service firms with certification expertise. Consolidation pressure intensifies as oil and gas operators consolidate supplier relationships. Geographic expansion through local certification partnerships represents the dominant competitive maneuver.
Within the diversified industrial tier, Honeywell International Inc., Emerson Electric Co., and Yokogawa Electric Corporation exemplify vendors bundling safety subscriptions with control system renewals. Honeywell leverages distributed control heritage to anchor recurring revenue streams. Emerson secures position through deep calibration service contracts tied to lifecycle management. Yokogawa differentiates by embedding cybersecurity monitoring within maintenance offerings. These three represent contrasting geographic and strategic positioning within the same competitive space.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Siemens AG |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| HIMA Paul Hildebrandt GmbH |
| ABB Ltd. |
| SIS-TECH Solutions LP |
| Others |
Value Chain & Pricing Dynamics
Automotive-grade microcontroller allocation constraints from TSMC and Samsung foundries cascade through safety PLC logic solver production, compressing margins for mid-tier programmable controller suppliers while premium-tier vendors with captive semiconductor supply lines maintain pricing power through certified-lifecycle service bundling.
Pricing Analysis
Capacity additions in India and Saudi Arabia are reshaping price floors for integrated safety-DCS architectures as greenfield projects bypass legacy migration costs. Pricing stratifies across SIL 4-certified premium tiers, SIL 2-3 standard tiers, and economy relay-replacement tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the standard tier is intensifying because EPCs in the Middle East disaggregate hardware warranty from software maintenance. Batch manufacturers in Germany show highest price sensitivity; oil and gas majors in the United States Gulf Coast exhibit lowest sensitivity due to regulatory penalty exposure.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and Saudi Arabia's In-Kingdom Total Value Add program are reshaping sourcing patterns for sensor and final control element procurement. Manufacturing concentrates in Germany, the United States, and Japan for precision instrumentation; China dominates cable and enclosure fabrication. Production draws from fluoropolymer sealing compounds, sapphire pressure sensor substrates, and hermetic relay contacts. Single-source vulnerability runs through automotive-grade microcontroller supply from Taiwanese foundries. Distribution runs through engineering procurement contractors in Houston, Ludwigshafen, and Jubail Industrial City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 61511 compliance mandates across process industries create a stable compounding growth engine, with regulatory audit intensification sustaining replacement cycles regardless of hydrocarbon price volatility.
For Market Incumbents: Deepen vertical integration into automotive-grade semiconductor supply through foundry partnerships or captive wafer allocation agreements to insulate against TSMC allocation constraints. Expand TÜV Rheinland and Exida certification capacity in Texas and Germany to capture fourteen-month verification backlogs as a service revenue layer. Defend against modular skid fabricators shifting specification authority away from traditional EPC channels by embedding pre-certified safety packages directly into OEM supply agreements. For New Entrants and Emerging Players: Launch via direct module fabricator relationships in pharmaceutical and specialty chemical skid-mounted production units, bypassing entrenched EPC procurement gatekeepers. Target WirelessHART safety instrumented function retrofits in Brazil's pre-salt offshore platforms and North Sea installations, where topside weight reduction commands premium pricing. White-space concentration sits with hydrogen economy infrastructure in Germany and Saudi Arabia, where electrolyzer projects specify integrated fire-and-gas detection from project conception without legacy hardwired constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety certification competence clusters in Norway, Germany, and Texas create talent access bottlenecks for projects elsewhere. The five-to-ten year viability frame favors vendors with IEC 62443 cybersecurity certification capabilities converging with traditional IEC 61508 probabilistic safety skills. Acquisition target archetype: mid-cap engineering service firms with TÜV/Exida certification authority and regional partnerships in India or Saudi Arabia. Signal to monitor: Saudi Aramco and ADNOC open-protocol interoperability mandates accelerating multi-vendor architecture adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive automotive-grade microcontroller allocation insulates against TSMC foundry constraints. |
| IEC 62443 Cybersecurity Certification | First-mover certification creates market access conditioning for next-generation safety architectures. |
| Modular Safety Package Pre-Certification | Pre-validated skid-mounted offerings shift specification authority from EPCs to module fabricators. |
| WirelessHART SIL 2 Sensor Network Deployment | Offshore platform weight reduction drives adoption in Brazil pre-salt and North Sea basins. |
| Regional Certification Partnership Expansion | Local TÜV/Exida authorization in India and Saudi Arabia accelerates project commissioning timelines. |
Study Parameters
Bottom-up safety instrumented function deployment modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with process safety engineers, EPC procurement managers, TÜV Rheinland certification auditors, and plant maintenance directors at BASF, Saudi Aramco, and Reliance Industries facilities combined with secondary validation from IEC 61511 audit databases, EPA Risk Management Program enforcement records, OSHA Process Safety Management inspection data, and SEC 10-K instrumentation segment disclosures.
Input-output matrices map sensor, logic solver, and final control element unit economics across product type, end-use industry, technology protocol, and application scope dimensions over the projection horizon. CAGRs derive from regression-adjusted replacement cycle analysis and greenfield project pipeline tracking. Industry-specific forecast inputs include semiconductor foundry allocation schedules and REACH fluoropolymer restriction compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended TÜV certification backlogs or automotive-grade microcontroller supply disruptions. Forecasts reflect documented assumptions regarding regulatory audit intensification persistence and hydrogen economy infrastructure buildout velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market