
 Homeland Security Surveillance Camera Market | 2026-2036
Homeland Security Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Homeland Security Surveillance Camera Market Outlook
Silicon carbide thermal substrates is shifting from niche military applications into mainstream homeland security camera housings, cutting heat-dissipation costs by half versus traditional aluminum enclosures. Hikvision leverages its vertically integrated sensor foundries to dominate fixed-position IP camera supply for government tenders across Asia. Lockheed Martin sustains premium positioning in PTZ and gimbal-stabilized platforms through captive aerospace-grade manufacturing. Thales Group anchors European demand with NATO-certified encryption modules embedded in border surveillance arrays.
Homeland security surveillance cameras are optoelectronic devices engineered for continuous monitoring of critical infrastructure, border zones, and public safety perimeters, typically operating across visible, near-infrared, and thermal spectral bands with ingress protection ratings of IP66 or higher and operational temperature spans from minus forty to plus sixty degrees Celsius. Their primary purpose is to deliver real-time situational awareness to security operators through video streams that support automated threat detection algorithms. IP camera architectures now lead procurement volumes as agencies retire coaxial analog networks, while thermal camera segments capture disproportionate margin pools in perimeter defense and maritime border applications. Smart technology layers including onboard AI inference engines represent the fastest-expanding capability set, though HD and 4K resolution tiers remain the baseline specification for indoor government and transportation end users.
The US Department of Homeland Security mandates FIPS 140-2 cryptographic validation for all federal camera deployments, while the EU AI Act imposes strict conformity assessments on biometric identification systems used in public spaces. China's GB standards for intelligent video surveillance dictate domestic data sovereignty and encryption protocols that foreign suppliers must satisfy through local partnerships. Stakeholders must weigh sovereign data-localization requirements against the cost of maintaining parallel product certifications across the American, European, and Chinese regulatory spheres.
Market Dynamics
AI-powered video analytics is compressing procurement cycles as federal agencies retire analog coaxial networks and mandate edge-computing inference engines in all new camera deployments.
Growth Catalysts
- FIPS 140-2 Cryptographic Validation:US federal procurement mandates drive replacement of legacy analog systems with encrypted IP architectures across ports and border crossings.
- Silicon Carbide Thermal Substrates:Advanced material adoption halves heat-dissipation costs in camera housings, enabling continuous operation in extreme temperature environments.
- Smart City Programs:Municipal infrastructure budgets in India and China accelerate fixed-position camera deployment for public safety and traffic management integration.
Market Restraints
- Sensor Foundry Concentration:Vertical integration by dominant Asian manufacturers limits supply alternatives for Western integrators seeking cost-competitive thermal imaging modules.
- EU AI Act Conformity Assessments:Strict biometric identification system requirements impose extended certification timelines and technical documentation burdens on European deployments.
- Aluminum Enclosure Cost Volatility:Legacy thermal management materials face input price swings that compress margins for mid-tier housing suppliers unable to pivot to silicon carbide.
Strategic Opportunities
- Maritime Perimeter Defense:Coastal surveillance applications in Southeast Asia remain underpenetrated for PTZ-stabilized platforms with integrated radar fusion.
- GB Standards Localization:China's data sovereignty and encryption protocols create partnership pathways for foreign suppliers establishing domestic manufacturing joint ventures.
- Edge-AI and Thermal Convergence:Onboard inference engines combined with uncooled microbolometer arrays open new specification tiers for battery-powered remote deployments.
Industry Challenges
- Multi-Domain Certification Complexity:Parallel FIPS 140-2, NATO encryption module, and GB standards validation requires dedicated compliance teams and extends product launch timelines.
- Legacy Analog Integration Friction:Hybrid network architectures demand specialized protocol gateways that increase system cost and maintenance overhead for federal infrastructure retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeland Security Surveillance Camera Market |
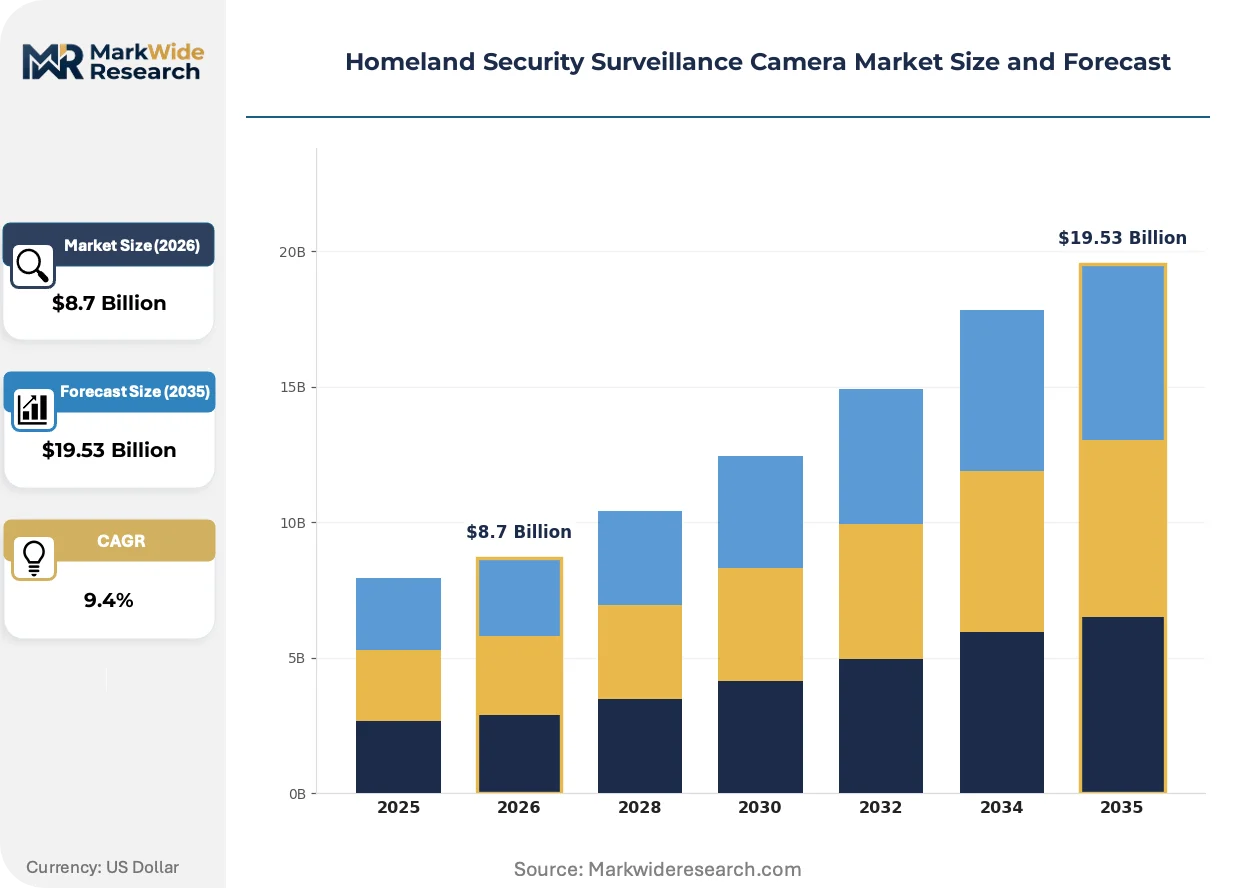
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Analog, IP, Thermal, PTZ Installation Type: Indoor, Outdoor, Wireless, Wired End User: Government, Military, Transportation, Education Technology: Infrared, HD, Smart, 4K |
| Companies Covered | Lockheed Martin, Hikvision, Thales Group, Honeywell International, Axis Communications, BAE Systems, Elbit Systems, Northrop Grumman, FLIR Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeland Security Surveillance Camera Market Strategic Shifts
Edge-computing inference engines are compressing the value chain by embedding threat detection algorithms directly into camera housings, eliminating centralized server dependencies for real-time analytics.
Silicon carbide thermal substrates is overtaking aluminum enclosures in next-generation camera housings by enabling passive cooling architectures that eliminate fan failure points. Maritime border agencies and desert-climate deployments are adopting these modules fastest, with procurement specifications now mandating minus-forty to plus-sixty-degree operational spans. This material transition is compressing supplier margins for legacy metal fabricators while rewarding compound semiconductor specialists.
The EU AI Act imposes strict conformity assessments on biometric identification systems deployed in public spaces, forcing manufacturers to segregate product lines between European and non-European feature sets. Border surveillance arrays must now demonstrate algorithmic transparency and human-in-the-loop override capabilities before CE marking approval. German and French integrators are responding by sourcing NATO-certified encryption modules from Thales Group to satisfy dual security and AI governance requirements.
Agency procurement departments are consolidating vendor relationships around full-system integrators capable of delivering camera hardware, analytics software, and maintenance services under unified contract vehicles. This bundling pattern displaces component suppliers who lack service capabilities, concentrating award decisions on firms with field engineering networks. The United States Department of Homeland Security exemplifies this shift through its emphasis on total cost of ownership evaluations rather than unit-price bidding.
Homeland Security Surveillance Camera Market Segmentation
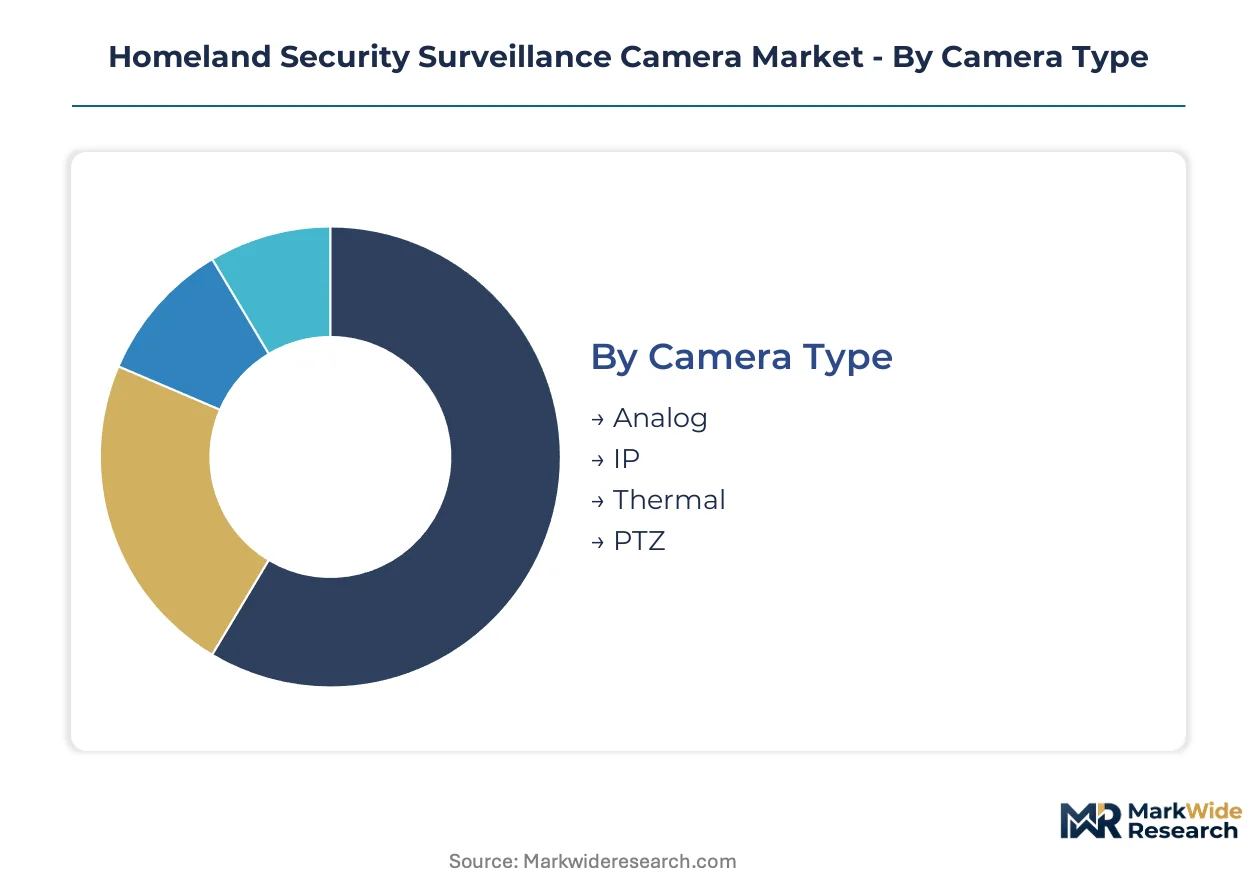
Homeland security procurement departments evaluate surveillance cameras across multiple technical and operational dimensions. Specification tiers diverge sharply between federal border installations and municipal smart city deployments.
Camera Type:
Budget authority and network infrastructure maturity separate buyers across this dimension.
- IP:Network-native architectures with Power-over-Ethernet connectivity and onboard encryption. US Customs and Border Protection mandates these for all new port installations under FIPS 140-2 compliance timelines.
- Thermal:Uncooled microbolometer arrays detecting long-wave infrared emissions. Maritime perimeter agencies in Southeast Asia specify these for coastal smuggling detection where visible-light cameras fail.
- Analog:Coaxial video output with limited resolution scalability. Legacy system maintenance contracts sustain residual demand at state-level correctional facilities.
- PTZ:Pan-tilt-zoom mechanisms with programmable patrol patterns. Gimbal-stabilized variants serve mobile border patrol units.
Volume sits with IP; growth tilts toward thermal.
Installation Type:
Physical deployment constraints and connectivity availability shape procurement specifications.
- Outdoor:IP66-rated housings with silicon carbide thermal substrates for passive cooling. Desert-climate border stations drive replacement cycles as legacy aluminum enclosures fail.
- Wired:Fiber-optic backhaul for bandwidth-intensive 4K streams. Federal critical infrastructure nodes require hardwired reliability over wireless alternatives.
- Indoor:Compact dome form factors for government facility lobbies and corridors. Transportation hubs in India deploy these for passenger flow analytics.
- Wireless:Cellular or mesh radio links for rapid deployment scenarios. Temporary checkpoints and disaster response favor battery-powered configurations.
Deployment scale favors wired outdoor; flexibility demands elevate wireless.
End User:
Threat models and oversight requirements create distinct purchasing behaviors.
- Government:Federal agencies with multi-year capital budgets and stringent certification requirements. The US Department of Homeland Security consolidates awards around full-system integrators.
- Transportation:Airport authorities and port operators integrating video with access control and baggage screening. Smart city programs in China accelerate fixed-position deployment.
- Military:Forward operating bases and perimeter defense with NATO encryption module requirements. Thales Group anchors European demand through certified supply.
- Education:Campus safety departments with limited technical staff favoring managed service contracts over capital purchases.
Contract value concentrates in government; deployment velocity peaks in transportation.
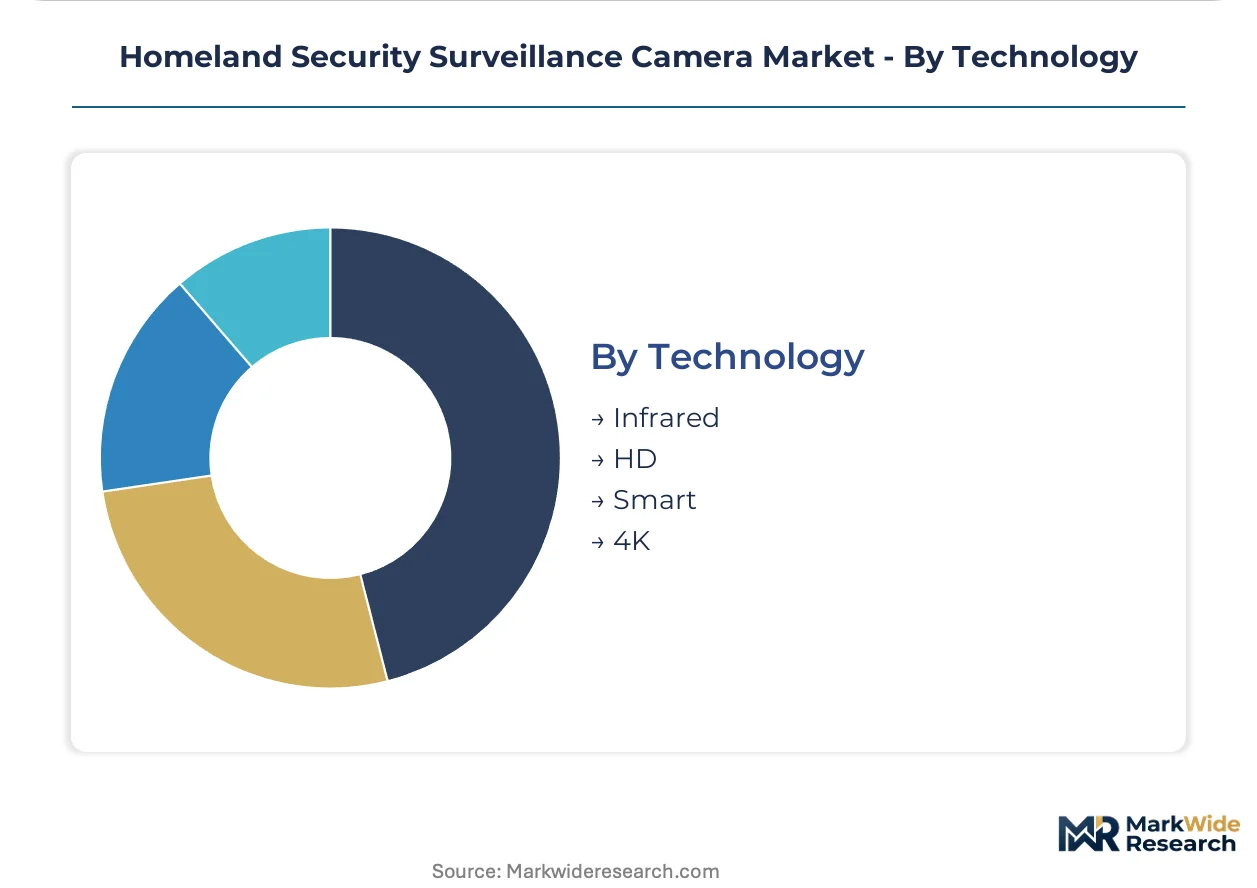
Technology:
Image quality thresholds and processing capabilities define competitive positioning.
- Smart:Edge-computing inference engines executing onboard threat detection. AI-powered video analytics compress procurement cycles as agencies retire centralized server architectures.
- 4K:Ultra-high-definition sensors for forensic identification at extended ranges. Border crossing identification lanes specify these for license plate and facial capture.
- HD:1080p resolution baseline for indoor government and transportation end users. Cost-sensitive municipal budgets standardize here.
- Infrared:Active near-IR illumination for zero-light environments. Perimeter arrays combine these with thermal for multi-spectral coverage.
Specification baselines cluster at HD; capability premiums accrue to smart.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for homeland security surveillance cameras concentrates in sovereign security budgets across three dominant national markets. Federal procurement specifications and smart city programs drive deployment velocity in the United States, China, and India.
United States
The US Customs and Border Protection operates over 8,000 cameras at land ports of entry alone. FIPS 140-2 cryptographic validation mandates from the Department of Homeland Security accelerate analog-to-IP replacement cycles. Arizona's Tucson and Texas's Rio Grande Valley anchor the densest camera concentrations along the southwest border corridor.
China
GB standards for intelligent video surveillance dictate domestic data sovereignty requirements that reshape foreign supplier access. MIIT certification protocols enforce encryption module localization for all government tenders. The Yangtze River Delta and Pearl River Delta host the principal manufacturing clusters for thermal imaging sensor foundries serving domestic security agencies.
India
Smart Cities Mission allocations fund municipal surveillance networks across 100 urban centers with integrated traffic and public safety analytics. The Ministry of Home Affairs mandates BIS certification for all critical infrastructure camera deployments. Maharashtra's Mumbai-Pune corridor and Karnataka's Bengaluru lead procurement volumes for transportation hub security upgrades.
Germany
Federal Police border surveillance programs specify NATO-certified encryption modules for Schengen perimeter arrays. The EU AI Act conformity assessment framework extends certification timelines for biometric identification systems. Bavaria's Munich and Baden-Württemberg's Stuttgart concentrate systems integrators serving federal and state security contracts.
United Kingdom
Home Office counter-terrorism grants fund networked camera deployments at transport nodes and crowded places. The Investigatory Powers Act oversight framework governs facial recognition deployment in public spaces. London's Metropolitan Police Service operates one of Europe's largest consolidated video management systems for urban surveillance coverage.
Homeland Security Surveillance Camera Market Competitive Environment
Strategic partnerships dominate the current landscape as component specialists align with systems integrators to meet bundled procurement requirements. The vendor structure organizes into three tiers: defense primes with captive aerospace manufacturing, Asian sensor foundries with vertical integration advantages, and European encryption module specialists. Archetypes include full-system integrators capturing consolidated federal contracts, thermal imaging component suppliers serving maritime perimeter agencies, and analytics software vendors embedding edge-AI inference engines. Geographic expansion and technology licensing represent the principal competitive vectors as firms navigate multi-domain certification complexity.
Among defense-anchored primes, Lockheed Martin and Northrop Grumman occupy positions exemplifying aerospace-grade manufacturing integration for PTZ and gimbal-stabilized platforms. Hikvision represents the foundry-integrated archetype with sensor manufacturing concentration serving government tenders across Asian markets. Thales Group anchors European demand through NATO-certified encryption supply, situating within the specialist tier for border surveillance array security modules.
| Leading Market Players |
|---|
| Lockheed Martin |
| Hikvision |
| Thales Group |
| Honeywell International |
| Axis Communications |
| BAE Systems |
| Elbit Systems |
| Northrop Grumman |
| FLIR Systems |
| Others |
Value Chain & Pricing Dynamics
Aluminum LME spot volatility cascades through camera housing fabrication costs, compressing margins for legacy metal fabricators while silicon carbide thermal substrate adopters capture pricing power in federal procurement tiers. Procurement officers at US Customs and Border Protection and India's Ministry of Home Affairs now mandate minus-forty to plus-sixty-degree operational spans, forcing tier-two suppliers toward material substitution or exit.
Pricing Analysis
Volume concentrates in HD-resolution IP cameras for municipal smart city budgets, while margin pools accrue to thermal imaging modules with onboard AI inference engines for maritime perimeter defense. Pricing stratifies across FIPS 140-2 certified architectures, NATO encryption module tiers, and uncooled microbolometer arrays. Cost compression in legacy aluminum enclosures intensifies because of raw material input swings. State-level correctional facilities in the United States exhibit highest price sensitivity; federal border agencies prioritize certification compliance over unit cost.
Supply Chain Analysis
Direct-to-government channels handle hyperscale federal procurement through consolidated full-system integrator contracts, displacing component-only vendors. Sensor foundry concentration rests in China, South Korea, and Taiwan for thermal imaging modules and edge-computing inference chips. Raw material dependencies draw from silicon carbide substrates, uncooled microbolometer arrays, and FIPS-validated encryption chipsets. Single-source vulnerability in thermal sensor foundries exposes Western integrators to supply allocation risk during sovereign security procurement surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homeland security surveillance cameras are undergoing a technology-transition phase as edge-computing inference engines displace centralized server architectures for real-time threat detection. Legacy analog coaxial networks face accelerated retirement timelines under federal procurement mandates.
For Market Incumbents: Acquire edge-AI software assets to bundle analytics capabilities with hardware offerings under unified Department of Homeland Security contract vehicles. Lockheed Martin and Northrop Grumman should deepen in-house production of gimbal-stabilized PTZ platforms to defend against Asian sensor foundry vertical integration. Certification investment in parallel FIPS 140-2, NATO, and GB standards validation extends product launch timelines but secures multi-domain award eligibility.
For New Entrants and Emerging Players: Cloud-based subscription analytics platforms offer rapid deployment routes for municipal smart city budgets lacking capital expenditure authority. Maritime perimeter defense in Southeast Asia presents the most penetrable geography, with coastal surveillance specifications still evolving for PTZ-radar fusion systems. Partner with established systems integrators for field engineering networks rather than building captive service infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal imaging component specialists with MIIT certification pathways in China's Yangtze River Delta manufacturing clusters. Long-term viability across the next decade hinges on sovereign data-localization compliance capabilities rather than pure technology performance. Watch for EU AI Act conformity assessment bottlenecks as an inflection indicator for European market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Inference Engine Integration | Onboard threat detection algorithms eliminate centralized server dependencies for US Customs and Border Protection deployments. |
| Silicon Carbide Thermal Substrate Adoption | Passive cooling architectures satisfy federal minus-forty to plus-sixty-degree procurement specifications without fan failure points. |
| Multi-Domain Certification Investment | Parallel FIPS 140-2, NATO, and GB standards validation opens consolidated federal contract vehicles across American, European, and Chinese procurement spheres. |
| Maritime Perimeter Defense Platform Development | PTZ-stabilized systems with integrated radar fusion address underpenetrated coastal surveillance demand in Southeast Asia. |
| Smart City Analytics Subscription Launch | Managed service contracts bypass municipal capital budget constraints in India's Smart Cities Mission allocations. |
Study Parameters
Independent corroboration across procurement officers at US Department of Homeland Security, systems integrators serving NATO border surveillance programs, and thermal imaging sensor foundry executives underwrites the qualitative findings in this study. Primary interviews with federal contract specialists, municipal smart city program directors, and maritime perimeter agency technical evaluators combined with secondary validation from FIPS 140-2 validation databases, MIIT certification registries, and EU AI Act conformity assessment documentation. Bottom-up deployment volume estimates and top-down sovereign security budget allocations were cross-referenced for triangulation.
Comparable-period anchoring to historical analog-to-IP replacement cycles and thermal imaging module adoption curves structured the forecast framework across the analysis window. Segmentation dimensions modeled include camera type, installation environment, end-user threat model, and resolution-technology tier alongside regulatory certification cluster as an industry-specific dimension. CAGRs were derived from deployment velocity differentials between federal capital budgets and municipal smart city program allocations, with silicon carbide thermal substrate penetration rates and edge-AI inference engine attach rates serving as key forecast inputs.
The model holds under steady sovereign security budget trajectories and stable raw material supply conditions; deviation in aluminum or silicon carbide pricing volatility, trade restriction imposition, or regulatory timeline acceleration would shift procurement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
AI CCTV Market