
 Rubber Foam Market | 2026-2036
Rubber Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Foam Market Analysis
Aftermarket refurbishment of automotive acoustic components is fragmenting across tiered supplier networks. Mitsui Chemicals leverages its polyolefin foam expertise to anchor Japanese OEM relationships. BASF competes through polyurethane chemistry leadership in European insulation grades. Recticel sustains margin pools via specialized closed-cell production for construction and marine applications.
Rubber foam comprises elastomeric cellular structures manufactured through continuous foaming, expansion, or batch processes with densities ranging from 25 to 250 kg/m³, serving primarily as thermal insulation, vibration damping, and sealing interfaces across industrial systems. Closed-cell foam dominates volume due to moisture resistance in HVAC and refrigeration, while composite foam captures premium positioning in aerospace and medical cushioning where multi-layer performance is required. Rebond foam occupies mature recycling-driven segments in carpet underlay and sports surfacing with compressed margin structures.
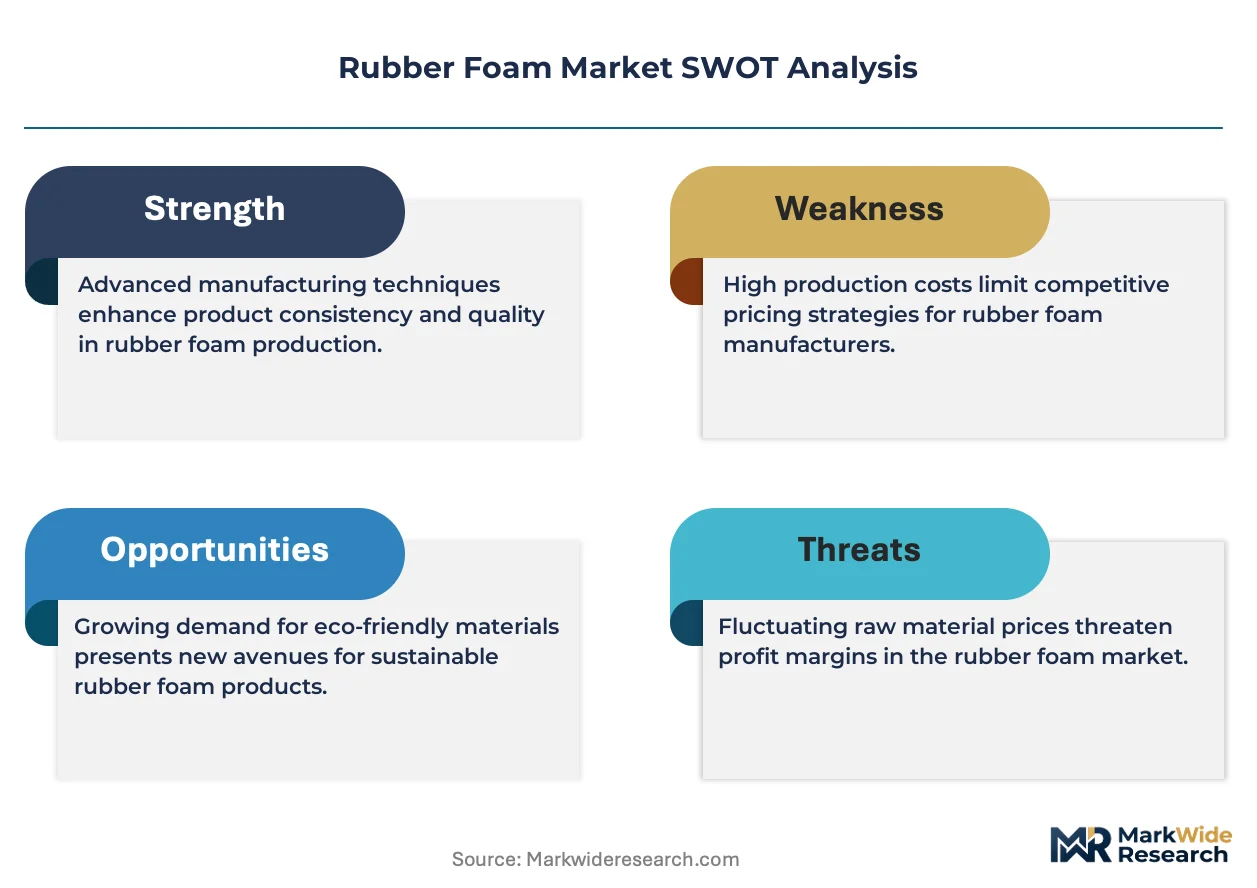
REACH restrictions on isocyanates and blowing agents constrain formulation flexibility for European producers, while China's GB standards and MEE enforcement tighten VOC emissions from foam curing operations. ISO 9001 and IATF 16949 certifications govern automotive supply qualification, creating tiered access barriers. Stakeholders must monitor regulatory divergence between EU F-Gas phase-down timelines and emerging economy enforcement capacity to align capacity investments with compliant chemistry transitions.
Market Dynamics
REACH isocyanate restrictions and China's MEE VOC enforcement are compressing formulation flexibility while automotive OEMs in Asia-Pacific accelerate closed-cell foam adoption for NVH reduction, creating divergent compliance investment requirements across supplier networks.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in China and India substitute dense rubber with cellular structures to meet fuel efficiency targets, driving closed-cell foam specification in door seals and underhood applications.
- F-Gas Regulation phase-down:Europe's hydrofluorocarbon restrictions accelerate blowing agent transitions toward water-blown and hydrocarbon systems, stimulating equipment replacement cycles in extrusion lines.
- Industrial corridor expansion:Construction activity in China's Yangtze River Delta and India's western belt concentrates demand for thermal insulation in HVAC infrastructure and cold chain logistics.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate price swings compress margin predictability for mid-scale foam converters dependent on spot market sourcing.
- Specialized equipment concentration:Continuous foaming line manufacturers cluster in Germany and Japan, creating 12-18 month delivery backlogs that constrain capacity expansion timing.
- Recycling infrastructure gaps:Cross-linked rubber foam lacks viable chemical depolymerization pathways, limiting circular economy claims and exposing producers to extended producer responsibility liabilities in France and Italy.
Strategic Opportunities
- Marine insulation retrofit:IMO 2020 sulfur regulations and subsequent energy efficiency mandates drive foam replacement in ship hull and pipe insulation across Baltic and Mediterranean fleets.
- Medical cushioning convergence:Antimicrobial additive integration with memory foam structures opens surgical positioning and patient support applications requiring biocompatibility certification.
- Direct-to-fabricator digital channels:Custom-cut foam configurators bypass traditional distributor markups in North American upholstery and packaging segments, capturing specification data for demand forecasting.
Industry Challenges
- Formulation chemist scarcity:Expertise in blowing agent transitions and catalyst balancing concentrates among aging technical workforces in European and Japanese headquarters, constraining regional R&D autonomy.
- IATF 16949 certification timelines:Automotive qualification cycles extend 18-24 months for new foam grades, delaying revenue recognition from approved supplier status despite technical validation completion.
- Legacy equipment retrofit complexity:Existing batch foaming installations require substantial control system upgrades to monitor real-time density and cell structure for quality consistency under tightened customer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Foam Market |
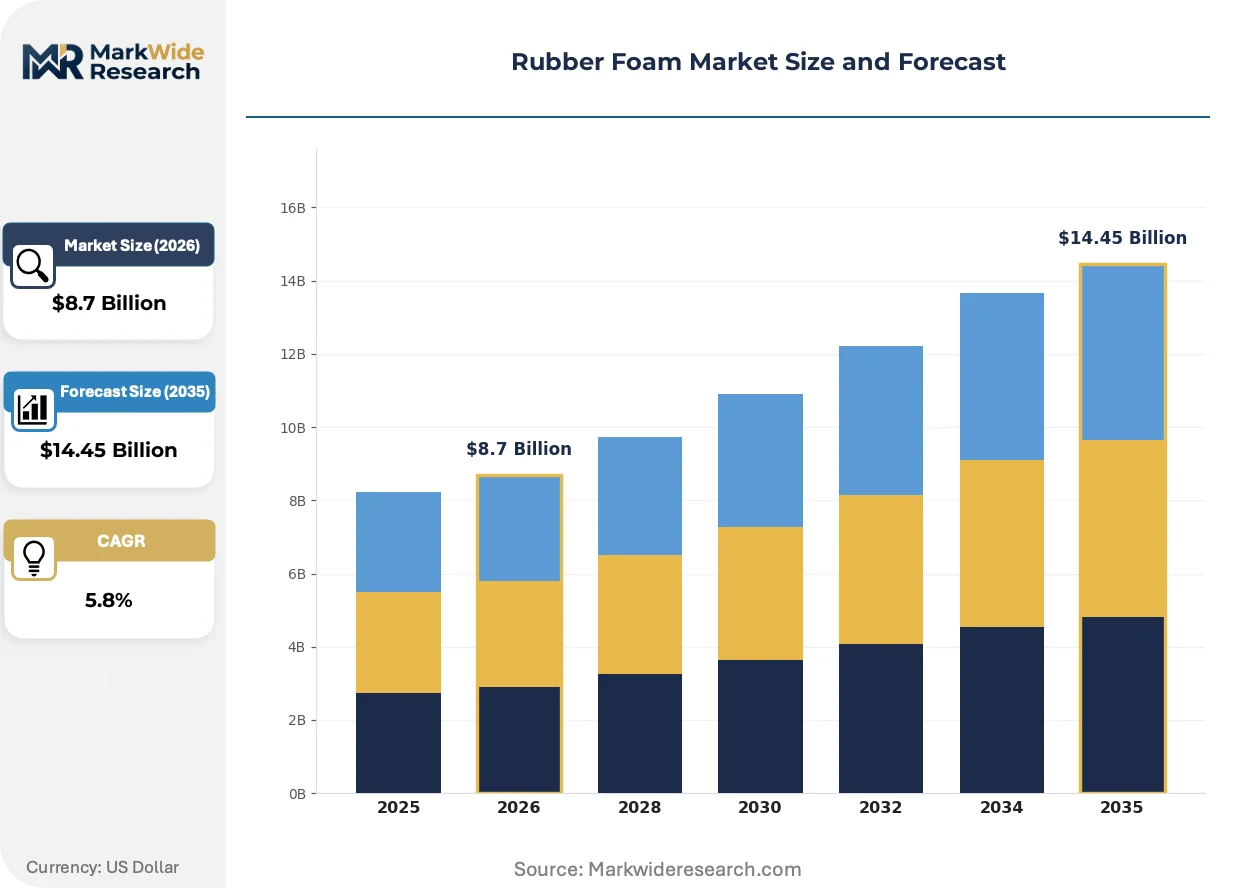
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-Cell Foam, Open-Cell Foam, Composite Foam, Rebond Foam End User: Automotive, Construction, Consumer Goods, Industrial Application: Soundproofing, Insulation, Packaging, Flooring Grade: Standard, High-Density, Low-Density, Specialty |
| Companies Covered | Recticel, Mitsui Chemicals, BASF, Dow, Tosoh, Covestro, Huntsman Corporation, Rogers Corporation, Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Foam Market Emerging Trajectories
Water-blown polyurethane systems and bio-based polyol feedstocks are reconfiguring competitive positioning in insulation grades, while digital quality monitoring compresses defect rates in continuous production environments.
Physical blowing agent replacement is collapsing the performance gap between hydrocarbon-expanded and legacy HFC-blown foams in low-temperature insulation applications. Cold chain operators in Germany and the Netherlands are qualifying these grades for refrigerated transport containers ahead of F-Gas prohibition timelines. The transition is collapsing premium pricing for specialty low-conductivity formulations as water-blown alternatives achieve equivalent lambda values.
China's GB standards evolution and MEE enforcement protocols are mandating enclosed curing ovens with thermal oxidizer integration for VOC capture. Foam producers in Shandong and Jiangsu provinces are consolidating batch operations into centralized industrial parks to share abatement infrastructure costs. The regulatory pressure is accelerating facility relocation toward compliant zones and disqualifying smaller extruders from automotive supply chains.
Specification authority is migrating from distributors to end-use engineering teams armed with simulation software for thermal and acoustic performance prediction. HVAC original equipment manufacturers in the United States and South Korea are issuing foam performance requirements directly to compounders, disintermediating traditional converter relationships. The pattern concentrates procurement leverage among technical buyers capable of validating cell structure and compression set data internally.
Rubber Foam Market Segmentation
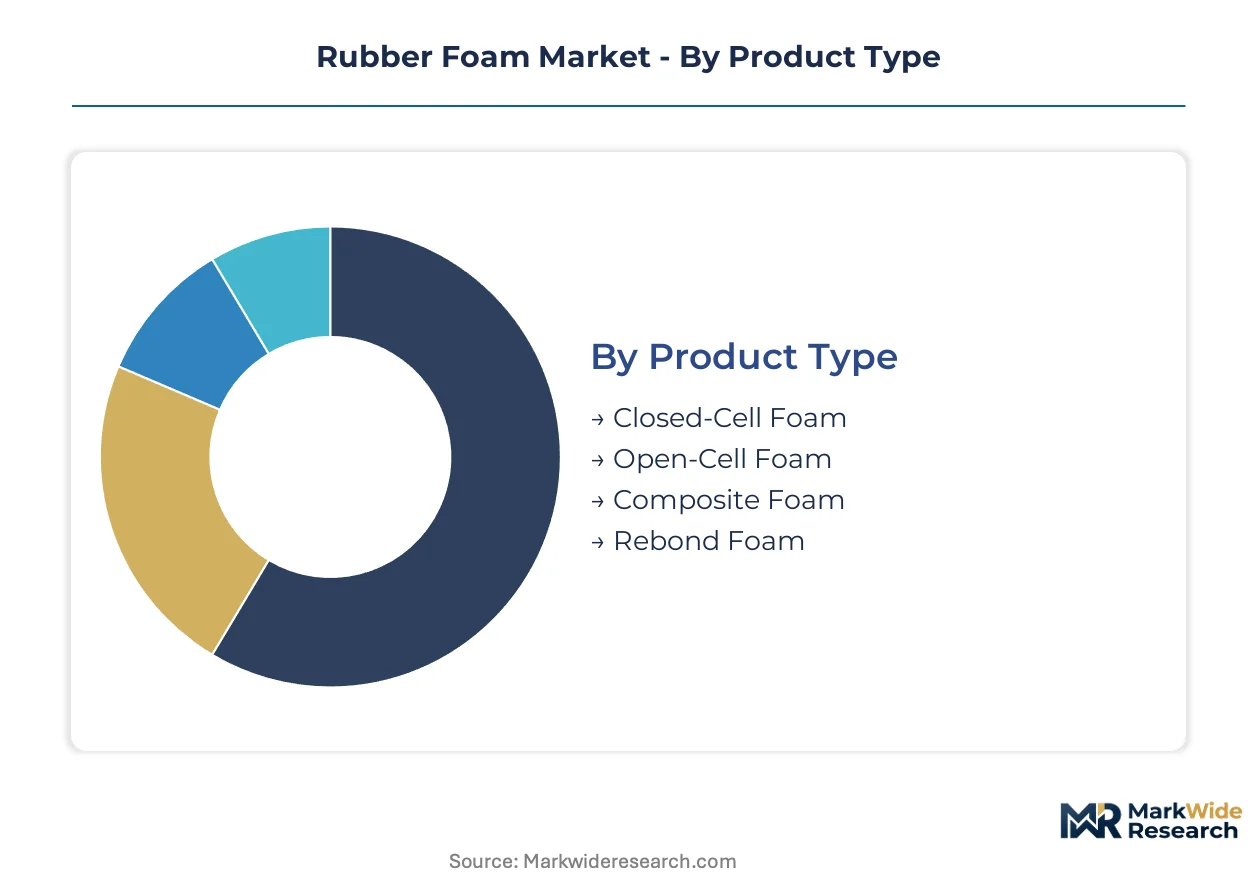
Rubber foam segmentation reflects divergent technical requirements across moisture resistance, load-bearing, and thermal performance specifications. Each dimension captures distinct margin structures and qualification barriers that reshape supplier competitive positioning.
Product Type:
Mature closed-cell technologies dominate volume throughput while emerging composite formulations capture premium positioning in performance-critical applications.
- Closed-Cell Foam:Elastomeric cellular structures with sealed cell walls deliver moisture resistance and compressive strength for HVAC and refrigeration systems. Demand concentrates in China's Yangtze River Delta industrial corridor where cold chain infrastructure expansion drives specification for thermal insulation grades. REACH F-Gas phase-down timelines accelerate blowing agent transitions toward water-blown systems in European production.
- Composite Foam:Multi-layer laminates combining rubber substrates with barrier films or reinforcement scrims achieve performance thresholds for aerospace seating and medical positioning equipment. German and South Korean OEMs are qualifying these grades for surgical support applications requiring biocompatibility certification under ISO 10993 protocols.
- Open-Cell Foam:Interconnected cellular structures optimize acoustic absorption and breathability in upholstery and filtration media.
- Rebond Foam:Recycled polyurethane scrap bonded under compression serves mature carpet underlay and sports surfacing segments with compressed margin structures.
Closed-cell foam handles the majority of throughput; composite foam is expanding most quickly on share.
End User:
Application intensity varies sharply across customer types, with automotive and construction commanding distinct specification authority and procurement leverage.
- Automotive:NVH reduction mandates and lightweighting targets drive closed-cell foam specification in door seals, underhood gaskets, and acoustic trim. IATF 16949 certification requirements create 18-24 month qualification cycles that delay revenue recognition for new compounders entering Japanese and German OEM supply chains.
- Construction:Thermal insulation demand concentrates in China's industrial corridor cities and India's western construction belt where HVAC infrastructure and cold chain logistics expansion accelerates specification for closed-cell grades. MEE VOC enforcement in Shandong and Jiangsu provinces is consolidating batch operations into centralized industrial parks.
- Consumer Goods:Mattress, furniture, and sporting equipment applications prioritize cost-positioned open-cell and rebond grades with limited technical differentiation.
- Industrial:Gasketing, sealing, and vibration isolation applications across machinery and process equipment favor standard-density formulations with broad chemical resistance.
Automotive commands premium pricing through qualification barriers; construction delivers volume scale through infrastructure cycle exposure.
Application:
Functional performance requirements segment the market across acoustic, thermal, protective, and surface applications with divergent density and cell structure specifications.
- Insulation:Low thermal conductivity grades serve refrigeration, HVAC ductwork, and pipe lagging with lambda value specifications tightening under F-Gas transition timelines. Cold chain operators in Germany and the Netherlands are qualifying hydrocarbon-expanded alternatives ahead of prohibition deadlines.
- Soundproofing:Open-cell and composite foam structures optimize acoustic absorption coefficients for automotive cabin trim, building partition systems, and industrial machinery enclosures. Specification authority is migrating from distributors to end-use engineering teams with simulation software for performance prediction.
- Packaging:Protective cushioning applications in electronics and precision equipment favor antistatic and custom-cut foam configurations.
- Flooring:Rebond and closed-cell underlayment grades serve residential, commercial, and sports surfacing with compression set and durability requirements.
Insulation captures the steepest expansion trajectory on energy efficiency regulation; soundproofing holds established automotive specification share.
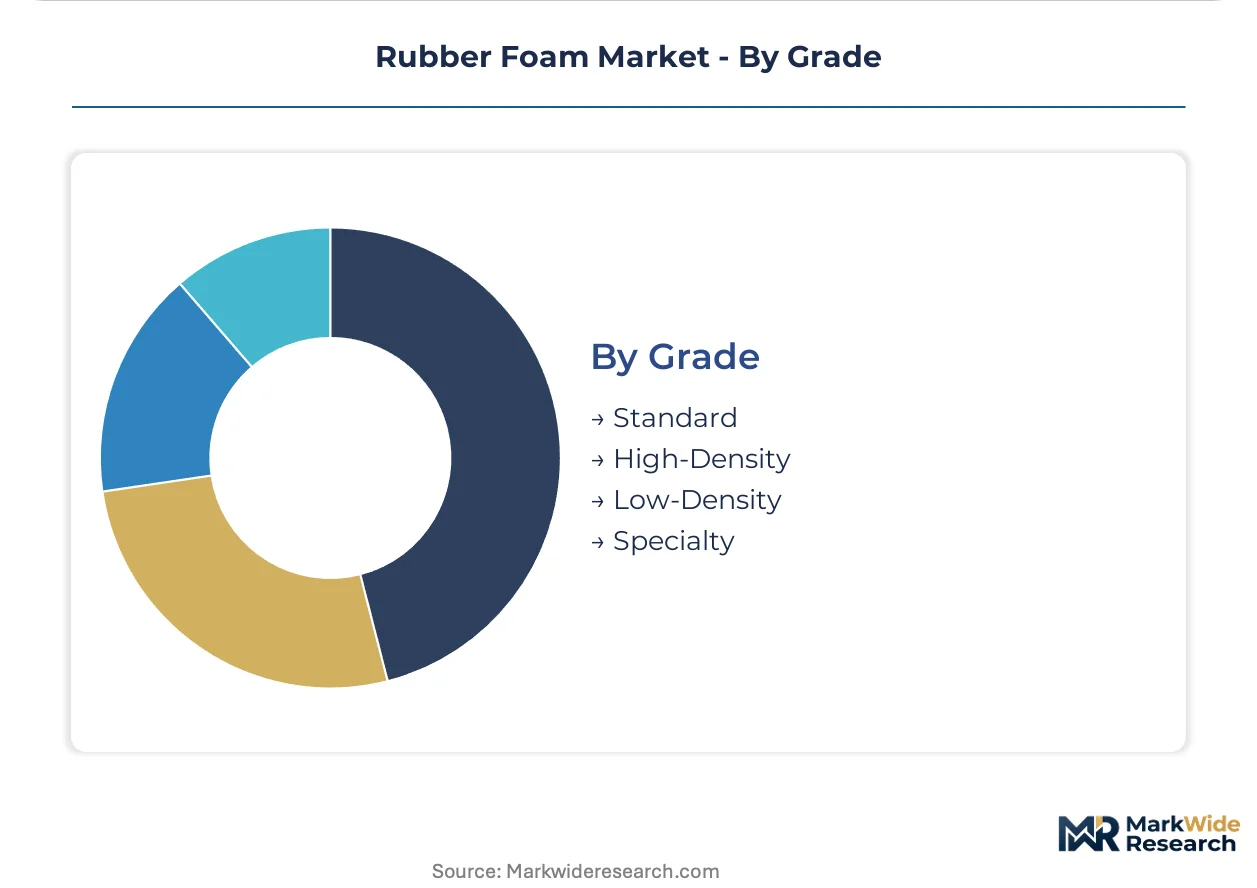
Grade:
Density and performance tiering separates commodity volume from certified premium positioning across end-use qualification requirements.
- Specialty:Custom-formulated grades with fire-retardant, antimicrobial, or low-smoke additives serve aerospace, medical, and marine applications requiring certification to IMO, FAA, or biocompatibility standards. Marine retrofit demand across Baltic and Mediterranean fleets is accelerating replacement of legacy insulation following IMO 2020 energy efficiency mandates.
- High-Density:Compressed cell structures above 150 kg/m³ deliver load-bearing performance for industrial gasketing and heavy-duty cushioning applications.
- Standard:Mid-density formulations serve broad construction and consumer goods applications with price-sensitive procurement patterns.
- Low-Density:Lightweight grades below 50 kg/m³ optimize material efficiency in packaging and disposable cushioning with limited durability requirements.
Standard grade moves the highest unit volumes; specialty grade is gaining share fastest on certification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's construction belt exhibit acute price sensitivity on standard-density grades, while German automotive OEMs absorb specialty foam premiums without volume elasticity. China's industrial corridor cities sit between these poles, trading margin for qualification access.
China
Cold chain logistics expansion across the Yangtze River Delta and Pearl River Delta drives closed-cell foam specification for refrigeration equipment and HVAC infrastructure. MEE enforcement of GB standards mandates thermal oxidizer integration in Shandong and Jiangsu curing operations, consolidating batch production into compliant industrial parks. Qingdao and Suzhou clusters host relocated extrusion capacity serving Japanese and German automotive supply chains.
Germany
F-Gas Regulation phase-down timelines accelerate water-blown and hydrocarbon system adoption in extrusion lines serving refrigeration OEMs. ECHA REACH restrictions on isocyanates constrain formulation flexibility, compressing margin pools for mid-scale converters dependent on legacy chemistry. The Ruhr industrial region and Bavarian manufacturing belt concentrate equipment replacement cycles as producers qualify low-conductivity alternatives ahead of prohibition deadlines.
United States
HVAC original equipment manufacturers in the Southeast and Midwest are issuing direct foam performance requirements to compounders, disintermediating traditional converter relationships. EPA oversight of blowing agent transitions aligns with state-level energy efficiency codes in California and New York. The Ohio River Valley and Texas industrial corridors concentrate demand forecasting through digital specification channels.
India
Construction activity in Maharashtra and Gujarat's western belt concentrates thermal insulation demand for commercial HVAC and cold chain infrastructure. BIS standards evolution and DGFT import protocols reshape material qualification for automotive NVH applications. The Delhi-Mumbai Industrial Corridor anchors capacity expansion timing as producers navigate 12-18 month equipment delivery backlogs from German and Japanese machinery suppliers.
Japan
Automotive OEMs in the Kanto and Kansai regions specify closed-cell foam for door seals and underhood gaskets under METI lightweighting mandates. JIS standards and IATF 16949 certification requirements create extended qualification cycles for new compounders. The Nagoya industrial cluster sustains polyolefin foam expertise through anchored supplier relationships with tiered network integration.
Rubber Foam Market Vendor Landscape
Capability concentration sits with European and Japanese headquarters housing aging formulation chemist expertise; scale advantage sits with Asia-Pacific producers leveraging corridor city demand density. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive polyol supply, specialized foam converters with IATF-certified automotive lines, and regional extruders serving construction price points. Dominant competitive moves include backward integration into blowing agent chemistry and geographic relocation toward MEE-compliant Chinese industrial parks.
Among Japanese chemical conglomerates, Mitsui Chemicals exemplifies the integrated tier with polyolefin foam expertise anchoring OEM relationships. BASF represents European chemistry leadership through polyurethane insulation grade positioning. Recticel occupies the specialized converter archetype, sustaining margin pools via closed-cell production for construction and marine applications. These three names illustrate how competitive positioning fragments across chemistry ownership, automotive qualification depth, and end-use specialization rather than converging on unified scale advantages.
| Leading Market Players |
|---|
| Recticel |
| Mitsui Chemicals |
| BASF |
| Dow |
| Tosoh |
| Covestro |
| Huntsman Corporation |
| Rogers Corporation |
| Armacell |
| Others |
Supply Flow & Price Mechanics
German and Japanese equipment manufacturers cluster continuous foaming line production, anchoring margin capture upstream while downstream foam converters absorb 12-18 month delivery backlogs and volatile polyol-isocyanate feedstock swings.
Pricing Analysis
Aftermarket refurbishment revenue for automotive acoustic components sustains lifetime value for IATF-certified compounders. Three-tier pricing structure across premium, standard, and economy levels separates specialty grades with IMO/FAA certification from construction-standard density tiers. Price differentiation hinges on REACH-compliant formulation complexity and automotive qualification depth. Pricing pressure stems from China's MEE enforcement consolidating batch operations into shared-abatement industrial parks. Construction buyers in India's western belt exhibit acute price sensitivity, while German automotive OEMs absorb specialty foam premiums without volume elasticity.
Supply Chain Analysis
Tariff exposure between China and key automotive export destinations dominates supply chain risk assessment for foam compounders serving Japanese and German OEM networks. Manufacturing concentration rests on China, Germany, and Japan for extrusion equipment and continuous foaming lines. Raw material dependencies draw from polyol feedstocks, isocyanate precursors, and hydrocarbon blowing agents. Single-source vulnerability concentrates in specialized catalyst suppliers and aging formulation chemist expertise. Distribution runs through tiered automotive supplier networks and direct-to-fabricator digital channels in North American upholstery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-blown system adoption and bio-based polyol penetration represent early-cycle expansion vectors, with F-Gas phase-down timelines accelerating chemistry transitions faster than equipment replacement cycles can absorb.
For Market Incumbents: Pre-empt margin compression in standard-density construction grades by securing captive polyol supply through backward integration or long-term offtake agreements with Middle Eastern feedstock suppliers. Anchor automotive relationships through IATF 16949 certification maintenance and real-time density monitoring upgrades that disqualify smaller extruders from OEM supply chains. For New Entrants and Emerging Players: Marine insulation retrofit across Baltic and Mediterranean fleets represents the most penetrable entry point, with IMO 2020 energy efficiency mandates driving foam replacement cycles independent of automotive qualification barriers. Medical cushioning convergence in surgical positioning equipment offers secondary white-space, requiring ISO 10993 biocompatibility investment. Direct-to-fabricator digital channels bypass traditional distributor markups and capture specification data for demand forecasting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized foam converters holding IATF-certified automotive lines but lacking REACH-compliant chemistry transitions. Long-term viability over a multi-year horizon favors compounders with water-blown system validation and MEE-compliant Chinese industrial park access. The signal to watch is qualification timeline compression for hydrocarbon-expanded alternatives in German cold chain applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Chemistry | Captures margin pools from hydrocarbon system transitions ahead of F-Gas prohibition deadlines in Germany and the Netherlands. |
| MEE-Compliant Facility Relocation | Qualifies batch operations for automotive supply chains by accessing shared thermal oxidizer infrastructure in Shandong and Jiangsu industrial parks. |
| Digital Quality Monitoring Deployment | Compresses defect rates in continuous production environments through real-time cell structure validation for HVAC OEM direct specification. |
| ISO 10993 Biocompatibility Certification | Opens surgical positioning and patient support applications for composite foam grades in German and South Korean medical device supply chains. |
| Marine Retrofit Partnership Program | Captures IMO 2020-driven insulation replacement cycles across Baltic and Mediterranean fleet operators with specialized closed-cell production. |
Methodological Framework
Desk research of customs and trade data, ECHA REACH substance registrations, and GB standards evolution preceded structured interviews with foam plant managers, automotive Tier 1 procurement leads, HVAC OEM specification engineers, and distribution channel partners across the analysis window. Primary fieldwork combined technical validation sessions with continuous foaming line operators and regulatory compliance reviews with MEE enforcement officials in Shandong province. Secondary sources included SEC 10-K filings from integrated chemical conglomerates, ACC and Cefic industry reports, and automotive production databases. Bottom-up segment sizing triangulated against top-down macro industrial output indices.
Assumptions held fixed include F-Gas phase-down enforcement timelines, MEE VOC abatement capacity expansion in Chinese industrial parks, and IATF 16949 certification duration benchmarks. Variables tested across the projection horizon encompassed polyol-isocyanate feedstock price elasticity, automotive lightweighting mandate stringency in China and India, and marine retrofit adoption rates post-IMO 2020. Segmentation modeling incorporated grade tier, end-use industry, application function, and regional production hub clustering. CAGR derivation weighted historical volume trajectories against equipment replacement cycle timing and regulatory compliance investment waves.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, automotive production volumes, or cold chain infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions on blowing agent transition pace and qualification timeline compression. Specific risks include REACH isocyanate restriction expansion, MEE enforcement capacity constraints, and formulation chemist expertise attrition. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Medical Rubber and Balloon Products Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Isoprene Rubber Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Global Cast Elastomers Market
Rubber
Europe Rubber Hose Market
Rubber
Reclaimed Rubber Market
Rubber
Rubber Block Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Industrial Rubber Products Market
Rubber
Global Tire Material Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Cellular Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Tire Reinforcement Materials Market