
 Global Chloroprene Rubber Market | 2026-2036
Global Chloroprene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chloroprene Rubber Market Foresight
REACH compliance is decoupling small compounders from European automotive supply chains. Denka Company Limited leverages captive acetylene feedstock to sustain margin stability across chloroprene monomer cycles. DuPont Performance Elastomers anchors North American specification control through ASTM-certified compound libraries. Shanxi Synthetic Rubber Group Co., Ltd. dominates domestic tender flows for mining conveyor belting in Shanxi Province.
Chloroprene rubber, also known as polychloroprene or Neoprene, is a synthetic elastomer produced through free-radical polymerization of 2-chloro-1,3-butadiene monomer, exhibiting resistance to ozone, weathering, and petroleum-derived fluids across a functional temperature range of approximately -40°C to 120°C. Its primary industrial purpose centers on dynamic sealing, vibration isolation, and protective barrier applications where petroleum resistance must coexist with mechanical flexibility. Solid-grade product types occupy the dominant volume position in mature automotive and industrial hose segments, while latex formulations represent the fastest-expanding category as dipped-glove manufacturers in Southeast Asia displace natural rubber for chemical-handling certifications. Emulsion polymerization leads manufacturing-method selection due to cost-scaled output, though suspension routes command premium positioning for crystallization-resistant grades specified in offshore marine cable jacketing.
The US EPA and OSHA jointly govern workplace exposure limits and environmental release thresholds for chloroprene monomer emissions near polymerization facilities, while China's MEE enforces escalating wastewater and air-quality standards that favor integrated producers with on-site recovery systems. Japan's METI coordinates industrial standards through JIS K 6380 classifications that define compound performance tiers for domestic procurement. Stakeholders must monitor regulatory divergence between jurisdictions where monomer-emission thresholds are tightening, as compliance-capital requirements will determine which polymerization assets remain economically viable through the forecast horizon.
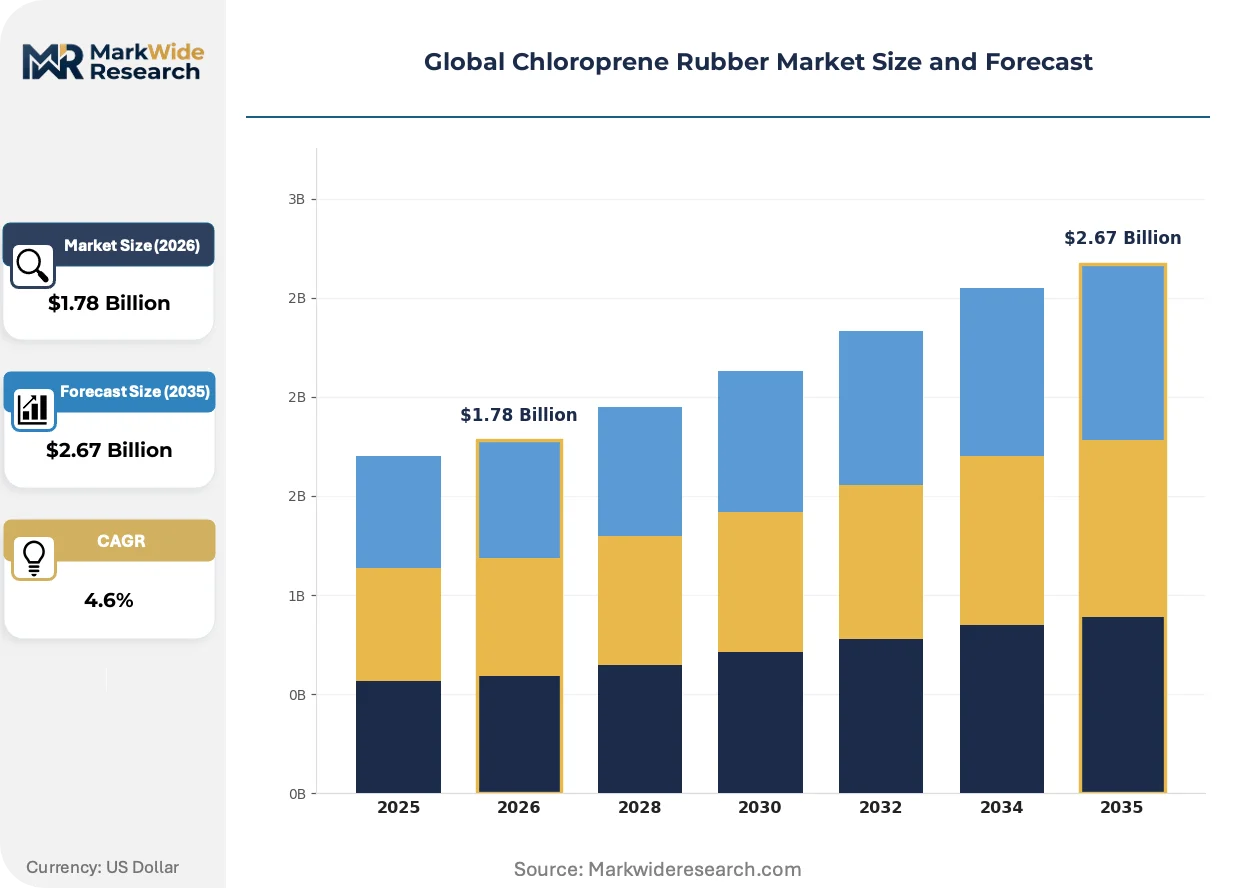
Market Dynamics
REACH compliance is decoupling small compounders from European automotive supply chains as integrated producers with captive acetylene feedstock capture margin stability across chloroprene monomer cycles. Specification engineers redirect toward polychloroprene formulations as EU F-Gas Regulation tightens compliance requirements for fluorinated alternatives.
Growth Catalysts
- EU F-Gas Regulation:Tightening compliance thresholds for fluorinated elastomers redirect specification engineers toward polychloroprene formulations in automotive sealing and HVAC applications.
- China's mining sector:Domestic tire and conveyor belt manufacturers scale captive consumption of solid-grade chloroprene rubber for Shanxi Province mining operations.
- Latex formulation demand:Dipped-glove manufacturers in Southeast Asia displace natural rubber for chemical-handling certifications requiring petroleum resistance.
Market Restraints
- Acetylene feedstock volatility:Chloroprene monomer production depends on acetylene derived from calcium carbide or petroleum cracking, exposing margins to energy price swings.
- Supply concentration in East Asia:Integrated polymerization assets with on-site recovery systems concentrate in China and Japan, limiting Western sourcing flexibility.
- Fluorosilicone substitution:Premium sealing applications above 150°C increasingly specify fluorosilicone elastomers despite higher unit costs.
Strategic Opportunities
- India's industrial safety mandate:BIS certification expansion for chemical-handling PPE creates white space for latex-grade chloroprene glove penetration.
- Offshore marine cable jacketing:Crystallization-resistant suspension polymerization grades command premium positioning in North Sea and Gulf of Mexico installations.
- Japan's METI JIS K 6380 alignment:Compound performance tier standardization enables specification harmonization across ASEAN procurement networks.
Industry Challenges
- Monomer emission compliance:US EPA and OSHA joint workplace exposure limits require capital-intensive scrubber retrofits at legacy polymerization facilities.
- Compound certification timelines:ASTM-certified compound library maintenance demands sustained R&D expenditure as OEMs compress qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chloroprene Rubber Market |
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Solid, Foam, Adhesive Application: Marine, Electrical Insulation, Industrial Hoses, Protective Gloves End User: Oilfield Equipment Manufacturers, Electronics Fabricators, Chemical Processing Plants, Construction Suppliers Manufacturing Method: Emulsion Polymerization, Suspension Polymerization, Solution Polymerization, Bulk Polymerization |
| Companies Covered | Showa Denko K.K., DuPont Performance Elastomers, Denka Company Limited, Asahi Kasei Chemicals Corporation, Resonac Holdings Corporation, ARLANXEO, Shanxi Synthetic Rubber Group Co., Ltd., Lanxess AG, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chloroprene Rubber Market Shifts & Advancements
Process automation and regulatory divergence are compressing qualification timelines while reshaping procurement patterns across automotive and industrial end-uses. Three developments dominate the current transformation cycle.
Continuous emulsion polymerization with inline viscosity monitoring is automating batch-to-batch consistency in solid-grade production. Tier-1 automotive suppliers in Germany and Japan adopt these systems to compress compound certification cycles from eighteen months to under nine. The technology is automating quality-assurance labor out of mid-volume compounders who lack capital for retrofit.
China's MEE escalates wastewater and air-quality standards that favor integrated producers with on-site chloroprene monomer recovery systems. Small batch compounders without captive feedstock face asset stranding as environmental compliance capital requirements rise. Shanxi Province mining belt manufacturers now specify suppliers with certified zero-liquid-discharge systems.
Specification engineers consolidate approved vendor lists to three or fewer compounders per region as OEMs reduce qualification overhead. Long-term supply agreements with volume commitments replace spot purchasing in North American automotive sealing procurement. The concentration is most visible in Detroit and Stuttgart where platform standardization drives rubber specification harmonization across vehicle lines.
Global Chloroprene Rubber Market Segmentation
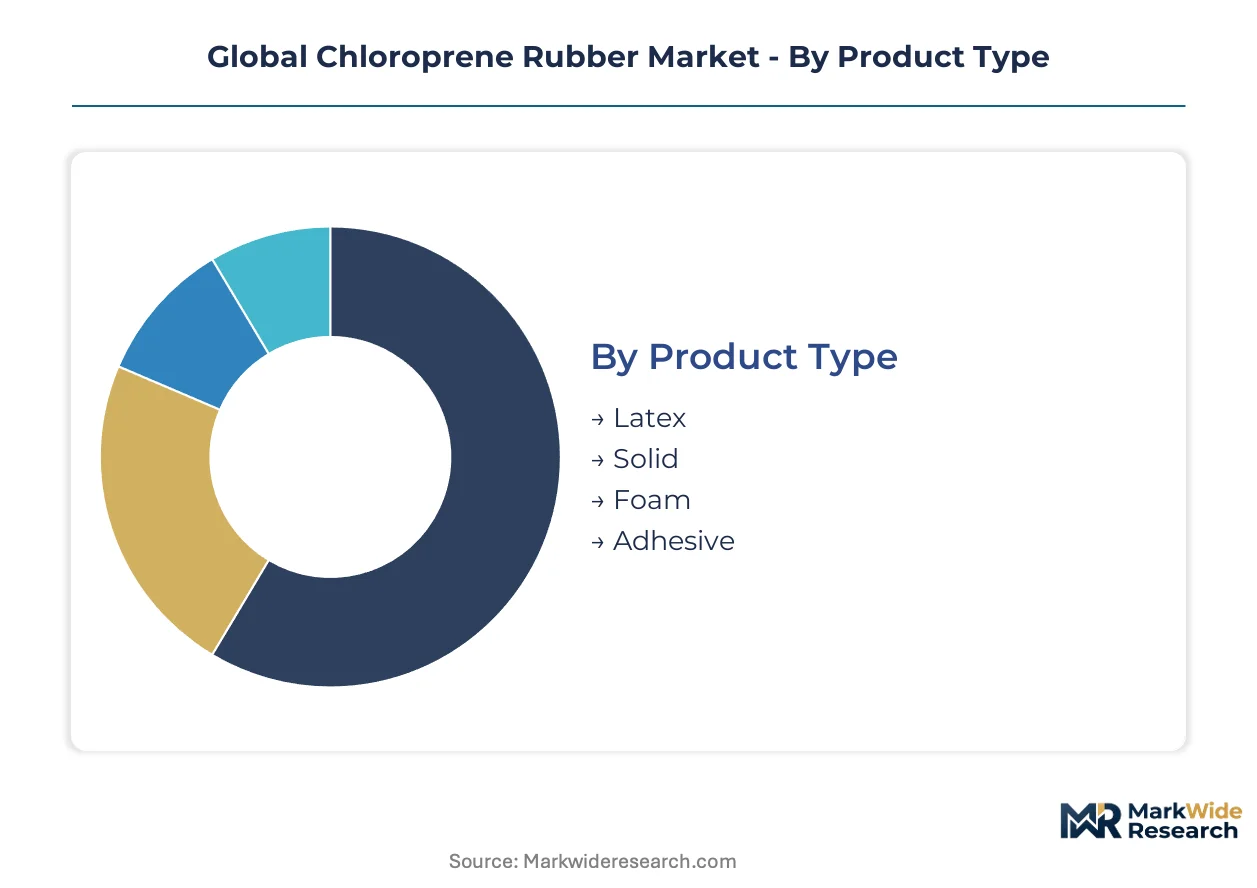
Chloroprene rubber segmentation reflects divergent margin structures between commodity solid grades and specialized latex formulations. Specification engineers select product types and manufacturing methods based on temperature resistance thresholds, chemical exposure profiles, and certification requirements.
Product Type:
Solid-grade formulations dominate volume shipments while latex commands premium pricing in certified protective equipment.
- Solid:Dense polymer blocks and sheets serve dynamic sealing and vibration isolation in automotive underhood applications. Shanxi Province mining belt manufacturers specify solid grades for conveyor systems requiring abrasion resistance across temperature swings from -40°C to 120°C.
- Latex:Aqueous dispersions enable dipped-glove manufacturing with controlled film thickness for chemical-handling certifications. Southeast Asian PPE fabricators displace natural rubber with chloroprene latex to meet petroleum resistance standards for industrial safety mandates.
- Foam:Cellular structures provide cushioning and thermal insulation in construction gaskets and marine seating applications.
- Adhesive:Solvent-based and waterborne contact cements bond dissimilar substrates in footwear and automotive trim assembly.
Today's leader: Solid. Tomorrow's challenger: Latex.
Application:
End-use selection tracks resistance requirements against ozone, petroleum fluids, and mechanical stress.
- Protective Gloves:Dipped chloroprene barriers protect against solvents, oils, and corrosive chemicals in chemical processing and laboratory environments. India's BIS certification expansion for chemical-handling PPE accelerates specification of latex-grade formulations in domestic manufacturing.
- Industrial Hoses:Reinforced tubes and covers convey petroleum products, hydraulic fluids, and chemical streams under pressure. Automotive OEMs specify chloroprene hose covers for underhood routing where heat and oil exposure degrade conventional elastomers.
- Marine:Wetsuits, drysuit seals, and deck equipment gaskets exploit weathering resistance in saltwater environments.
- Electrical Insulation:Cable jacketing and connector boots provide dielectric protection with flame retardancy for power distribution and telecommunications infrastructure.
Protective gloves claim the steepest expansion trajectory. Industrial hoses anchor revenue stability.
End User:
Procurement patterns diverge between specification-controlled OEM channels and price-sensitive industrial distributors.
- Chemical Processing Plants:Maintenance departments specify chloroprene gaskets, seals, and protective equipment for routine turnaround cycles and emergency response inventories.
- Oilfield Equipment Manufacturers:Downhole tools and surface processing equipment require elastomer seals resistant to hydrocarbon exposure and pressure cycling.
- Electronics Fabricators:Cleanroom glove specifications and static-dissipative matting employ latex and solid grades in semiconductor and display manufacturing.
- Construction Suppliers:Weatherstripping, expansion joint seals, and adhesive formulations serve commercial building envelope applications.
Chemical processing plants drive specification intensity. Oilfield equipment manufacturers concentrate volume purchasing.
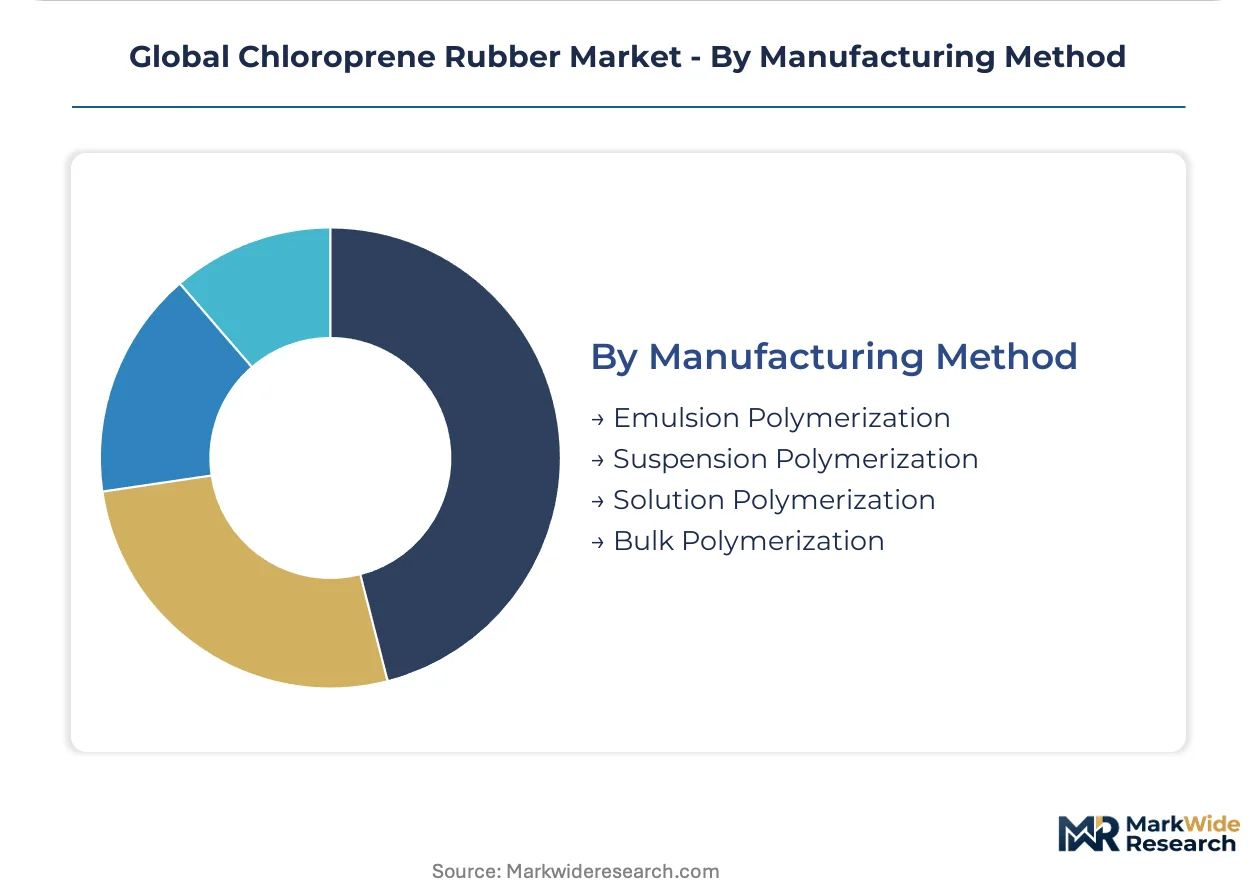
Manufacturing Method:
Process selection trades capital efficiency against crystallization resistance and batch consistency.
- Emulsion Polymerization:Water-based free-radical polymerization delivers cost-scaled output for general-purpose solid and latex grades. Continuous emulsion systems with inline viscosity monitoring compress batch-to-batch variation for Tier-1 automotive qualification cycles.
- Suspension Polymerization:Bead-form polymerization in aqueous media yields crystallization-resistant grades for low-temperature flexibility specifications. Offshore marine cable jacketing in North Sea and Gulf of Mexico installations commands premium positioning for suspension-grade material.
- Solution Polymerization:Organic solvent systems enable precise molecular weight control for specialty adhesive and coating applications.
- Bulk Polymerization:Mass polymerization without dispersing medium serves limited high-purity applications where residual emulsifiers compromise performance.
Emulsion polymerization commands volume dominance. Suspension polymerization captures margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymerization chemists and compound formulation engineers concentrate in East Asian industrial corridors, German automotive clusters, and US Gulf Coast chemical manufacturing zones. Talent density in these regions anchors chloroprene rubber production and specification control.
China
Shanxi Province mining belt manufacturers and domestic tire producers scale captive consumption of solid-grade material for conveyor systems and automotive underhood applications. China's MEE enforces escalating wastewater standards that favor integrated producers with on-site chloroprene monomer recovery systems. Yangtze River Delta polymerization facilities supply latex formulations to Southeast Asian dipped-glove fabricators.
Japan
Automotive OEMs in Toyota City and Yokohama specify chloroprene seals and hoses for domestic vehicle platforms requiring heat and petroleum resistance. METI coordinates industrial standards through JIS K 6380 classifications that define compound performance tiers for procurement networks. Kansai region chemical producers supply crystallization-resistant suspension polymerization grades for marine cable applications.
Germany
Tier-1 automotive suppliers in Stuttgart and Munich adopt continuous emulsion polymerization systems to compress compound certification cycles. EU F-Gas Regulation tightens compliance thresholds for fluorinated elastomers, redirecting specification engineers toward polychloroprene formulations in HVAC and sealing applications. REACH compliance requirements decouple small compounders from European automotive supply chains.
United States
Detroit-based OEMs consolidate approved vendor lists to three or fewer compounders per region as platform standardization drives rubber specification harmonization. US EPA and OSHA jointly govern workplace exposure limits for chloroprene monomer emissions near polymerization facilities. Gulf Coast chemical manufacturing zones host legacy polymerization assets requiring capital-intensive scrubber retrofits.
India
Dipped-glove manufacturers in Tamil Nadu and Maharashtra displace natural rubber with chloroprene latex to meet chemical-handling certifications for industrial safety mandates. BIS certification expansion for chemical-handling PPE creates specification pathways for latex-grade penetration. Western India industrial corridors concentrate compounding capacity for domestic mining and construction applications.
Global Chloroprene Rubber Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across chloroprene rubber manufacturing tiers. The vendor base separates into integrated polymerization operators with captive acetylene feedstock, regional compounders serving specification-controlled automotive channels, and latex dispersion specialists targeting protective equipment markets. Three archetypes dominate: East Asian integrated producers with backward feedstock control, European specification compounders with certified compound libraries, and emerging market volume suppliers with cost-scaled emulsion capacity. Competitive moves concentrate on environmental compliance capital deployment and long-term supply agreement consolidation with automotive OEMs.
Among Japanese integrated producers, Showa Denko K.K., Denka Company Limited, and Tosoh Corporation exemplify the archetype of acetylene-captive polymerization operators with margin stability across monomer price cycles. These companies occupy positions within supply chains where on-site recovery systems and environmental compliance infrastructure determine asset viability. DuPont Performance Elastomers represents North American specification control through compound library certification, while Shanxi Synthetic Rubber Group Co., Ltd. anchors domestic tender flows for Chinese mining belt applications.
| Leading Market Players |
|---|
| Showa Denko K.K. |
| DuPont Performance Elastomers |
| Denka Company Limited |
| Asahi Kasei Chemicals Corporation |
| Resonac Holdings Corporation |
| ARLANXEO |
| Shanxi Synthetic Rubber Group Co., Ltd. |
| Lanxess AG |
| Tosoh Corporation |
| Others |
Supply & Pricing Matrix
China's MEE wastewater discharge mandates gate qualified supply access and premium-tier pricing for chloroprene rubber producers with certified zero-liquid-discharge systems. Buyers without approved supplier status face procurement exclusion as environmental compliance capital requirements stratify the vendor base.
Pricing Analysis
Contracted compound supply with bundled certification services dominates automotive procurement, while spot transactional pricing persists in industrial distributor channels. Three-tier pricing structure across suspension-grade premium, emulsion-grade standard, and commodity solid-economy levels reflects crystallization resistance and batch consistency differentiation. Cost compression in standard-grade solid chloroprene intensifies as Shanxi Province mining belt manufacturers consolidate volume commitments to integrated producers. Tier-1 automotive OEMs exhibit lowest price sensitivity due to platform qualification lock-in, while construction suppliers and small batch compounders face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Container freight rate volatility from East Asian polymerization hubs to European automotive clusters compounds landed cost uncertainty for specification-grade material. Supply concentrates in China, Japan, and Germany, with integrated acetylene-captive assets in Shanxi Province and Kansai region anchoring global output. Production draws from calcium carbide and petroleum-derived acetylene feedstock, with chloroprene monomer recovery systems determining asset viability. Single-source vulnerability concentrates in suspension polymerization grades for offshore marine cable jacketing. Distribution runs through long-term supply agreements with volume commitments for automotive OEMs, supplemented by regional distributor networks for industrial maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-down schedules for fluorinated elastomers redirect specification engineers toward polychloroprene formulations in automotive sealing and HVAC applications.
For Market Incumbents: Extend certified compound library maintenance to compress automotive OEM qualification cycles from eighteen months to under nine. Denka Company Limited and Showa Denko K.K. should deepen backward integration into captive acetylene feedstock to sustain margin stability across monomer price cycles. Fluorosilicone substitution above 150°C represents the primary substitution threat requiring crystallization-resistant grade R&D investment. For New Entrants and Emerging Players: India's BIS-certified chemical-handling PPE manufacturers represent an underserved buyer archetype with specification pathways opening for latex-grade chloroprene glove penetration. Tamil Nadu and Maharashtra dipped-glove fabricators offer the most penetrable entry point. Target white-space expansion through BIS certification alignment and Southeast Asian distributor partnerships rather than direct automotive qualification. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with ASTM-certified libraries because automotive OEM vendor list consolidation to three or fewer suppliers per region creates scarcity value for qualified assets. Mid-cap European compounders facing REACH compliance decoupling from supply chains present acquisition targets. Monitor US EPA and OSHA joint enforcement actions on chloroprene monomer emission thresholds as the inflection signal for legacy asset stranding versus compliance-capital deployment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Denka Company Limited's captive supply anchors margin stability across chloroprene monomer cycles. |
| Continuous Emulsion Polymerization Retrofit | Tier-1 automotive suppliers in Stuttgart adopt inline viscosity monitoring to compress qualification timelines. |
| Zero-Liquid-Discharge System Certification | Shanxi Province mining belt manufacturers now specify suppliers with MEE-compliant wastewater recovery. |
| Long-Term Supply Agreement Consolidation | Detroit OEMs replace spot purchasing with volume commitments to reduce qualification overhead. |
| BIS Certification Pathway Investment | India's industrial safety mandate creates specification access for latex-grade chloroprene glove penetration. |
Research Methodology
Coverage spans East Asia, Europe, and North America, with primary inputs from each region's polymerization corridor and automotive manufacturing cluster. The research combines interviews with plant managers at integrated chloroprene producers, procurement leads at Tier-1 automotive suppliers, and technical R&D directors at compound formulation facilities with secondary validation. Secondary sources include customs and trade data, SEC 10-K filings from diversified chemical conglomerates, and JIS K 6380 classification documentation. Bottom-up volume modeling triangulates against top-down value estimates from automotive platform content analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, manufacturing method, application end-use, and regional production hub clustering. CAGRs derive from weighted average of historical trajectory and forward scenario analysis. Forecast inputs incorporate automotive platform standardization roadmaps and mining sector capital expenditure cycles for conveyor belt replacement.
Underlying measurement precision varies by segment; solid-grade automotive applications carry tighter precision than emerging latex-grade PPE categories due to established procurement data availability. Forecasts reflect assumptions on regulatory enforcement timing and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Industrial Rubber Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Global Cast Elastomers Market
Rubber
Rubber Sheets Market
Rubber
Europe Neoprene Market
Rubber
Liquid Polybutadiene Market
Rubber
Isoprene Rubber Market
Rubber
Oil Saver Rubber Market
Rubber
Plastomers Market
Rubber
Tire Chemicals Market
Rubber
Rubber Gloves Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Polyacrylate Rubber Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Performance Elastomers Market
Rubber
Global Elastomers Market