
 Digital Shore Durometer Market | 2026-2036
Digital Shore Durometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Shore Durometer Market Analysis
Buyer concentration is shifting as automotive tier-one suppliers consolidate testing budgets while medical device startups fragment demand across specialized laboratories. Mitutoyo Corporation leverages its Japan-based precision instrument heritage to dominate high-end digital durometer distribution. ZwickRoell Group competes through integrated materials testing platforms that bundle Shore hardness with tensile and flexural modules. Imada specializes in portable handheld units that occupy the mid-market manufacturing floor segment.
A digital Shore durometer measures elastomer and plastic hardness through electronic displacement sensors with resolutions reaching 0.1 Shore units, replacing mechanical dial indicators for repeatable quality control in polymer processing. Digital durometers lead product type revenue as laboratories retire analog units to meet ISO 17025 traceability mandates. Shore A scale instruments anchor the measurement scale category due to rubber and soft polymer dominance, though Shore D units are accelerating in engineering plastics applications. Quality control applications sustain the largest application share, while research and development segments attract premium pricing for data-logging and software-integrated models.
ASTM International governs Shore hardness test methods through ASTM D2240 in North America, while ISO 7619 and ISO 868 shape European and Asian calibration protocols through national metrology institutes. The U.S. FDA and EPA indirectly influence demand through medical device biocompatibility testing and tire rolling resistance regulations that require validated hardness documentation. Stakeholders must monitor evolving NIST-traceable calibration intervals and emerging IEC standards for wireless sensor interoperability to preserve instrument qualification pathways.
Market Dynamics
ASTM D2240 and ISO 7619 calibration mandates are forcing laboratories to retire analog durometers ahead of normal replacement cycles, compressing upgrade timelines and redistributing vendor relationships toward NIST-traceable service networks.
Growth Catalysts
- ISO 17025 Traceability Mandates:Accreditation bodies in Germany, Japan, and the United States now require documented calibration chains for polymer hardness testing, accelerating digital instrument procurement.
- Automotive Elastomer Verification:Tire manufacturers and sealing component suppliers deploy Shore A durometers for every-batch quality gates to satisfy OEM durability specifications.
- Engineering Plastics Expansion:Shore D scale adoption is accelerating as aerospace and electronics manufacturers validate high-durometer polymer structural components.
Market Restraints
- Sensor Component Concentration:Precision displacement transducers rely on Japanese and German component suppliers, exposing lead times to single-source vulnerabilities.
- Calibration Service Fragmentation:Third-party metrology providers in emerging markets lack NIST-traceable accreditation, forcing buyers to ship instruments overseas for recertification.
- Analog Unit Longevity:Mechanical dial durometers persist in cost-sensitive manufacturing floors where ISO compliance is not contractually enforced.
Strategic Opportunities
- Medical Device Biocompatibility Testing:FDA 21 CFR Part 820 quality system regulations mandate validated hardness documentation for implantable elastomer components.
- Wireless Sensor Integration:Bluetooth-enabled durometers paired with cloud-based SPC software are penetrating automotive tier-one supplier networks.
- India Manufacturing Uptake:BIS certification requirements for automotive components are driving first-time digital instrument adoption among domestic polymer processors.
Industry Challenges
- Metrology Technician Scarcity:Qualified personnel capable of interpreting Shore hardness correlation with tensile modulus remain concentrated in Germany, Japan, and the United States.
- Legacy System Integration:Digital durometers with proprietary data formats create friction when interfacing with existing LIMS and ERP platforms in multi-vendor testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Shore Durometer Market |
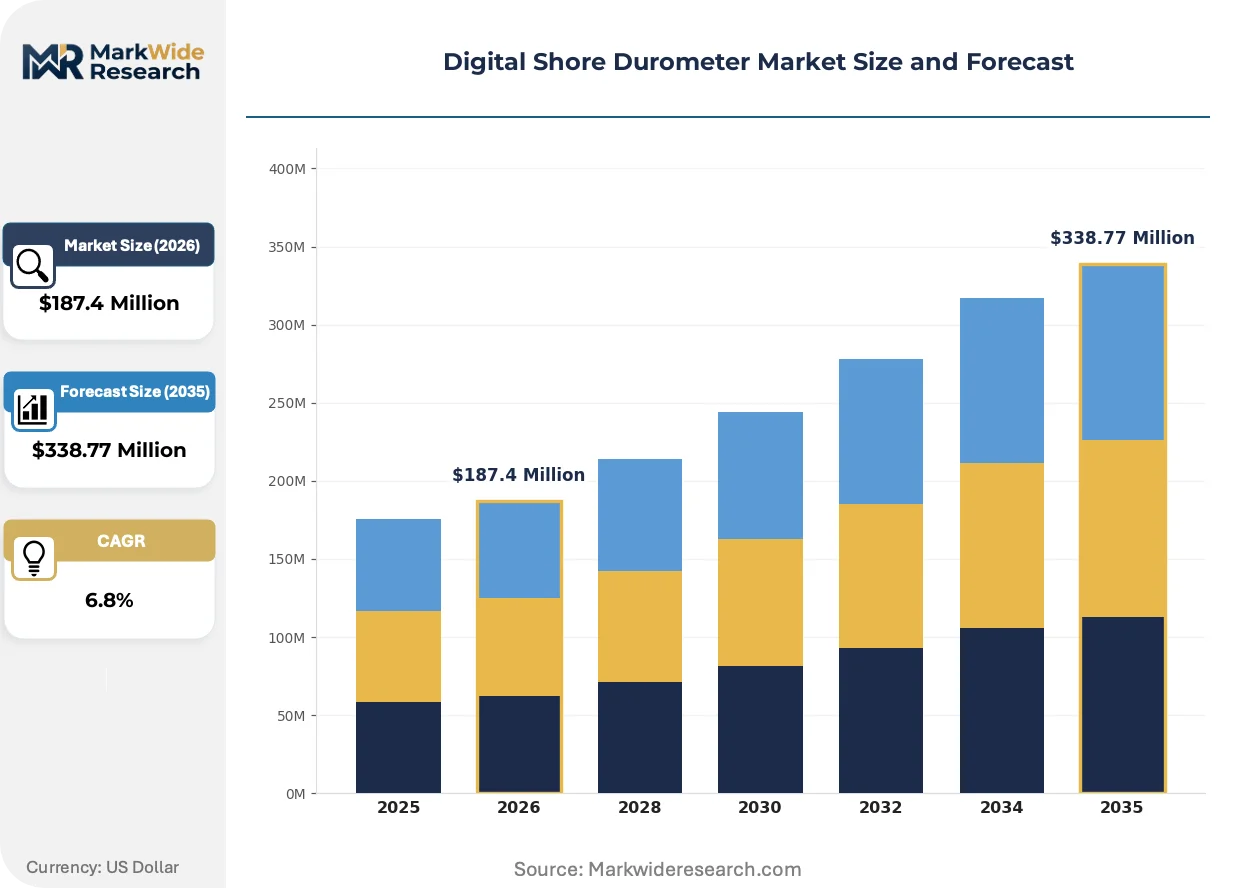
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Durometers, Digital Durometers, Shore A Durometers, Shore D Durometers Application: Material Testing, Quality Control, Research & Development, Manufacturing End User: Automotive Industry, Manufacturing Plants, Laboratory Testing, Educational Institutions Measurement Scale: Shore A Scale, Shore D Scale, Superficial Shore A, Superficial Shore D |
| Companies Covered | Mitutoyo Corporation, ZwickRoell Group, Shimadzu Corporation, Instron, Imada, Hildebrand, Insize, Shore Instruments & Mfg., Inc., PCE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Shore Durometer Market Emerging Trajectories
Electronic displacement sensing is electrifying instrument architectures while regulatory data-integrity requirements and buyer consolidation reshape competitive positioning around service bundling rather than hardware margins alone.
MEMS-based force sensors are electrifying portable durometer design by enabling sub-0.1 Shore unit resolution in battery-powered handheld units. Automotive quality engineers at tier-one sealing suppliers are adopting these instruments for at-line testing that previously required laboratory benchtop systems. The technology is electrifying vendor differentiation by collapsing the performance gap between manufacturing-floor and metrology-laboratory instruments.
EU MDR Annex I general safety and performance requirements now mandate traceable mechanical property documentation for polymer-based medical devices including hardness validation. Notified bodies in Germany and Ireland are rejecting submissions lacking ISO 17025-accredited test data. European medical device contract manufacturers are responding by mandating digital durometer procurement with embedded calibration certificates in their supplier qualification protocols.
Automotive OEMs are consolidating approved vendor lists for polymer testing equipment, shifting procurement authority from plant-level quality managers to centralized corporate metrology functions. Tier-one suppliers in Michigan, Stuttgart, and Aichi Prefecture now face mandated instrument standardization across multiple manufacturing sites. This concentration is most visible in tire manufacturing where Continental, Bridgestone, and Goodyear operations specify identical durometer models to ensure inter-plant data comparability.
Digital Shore Durometer Market Segmentation
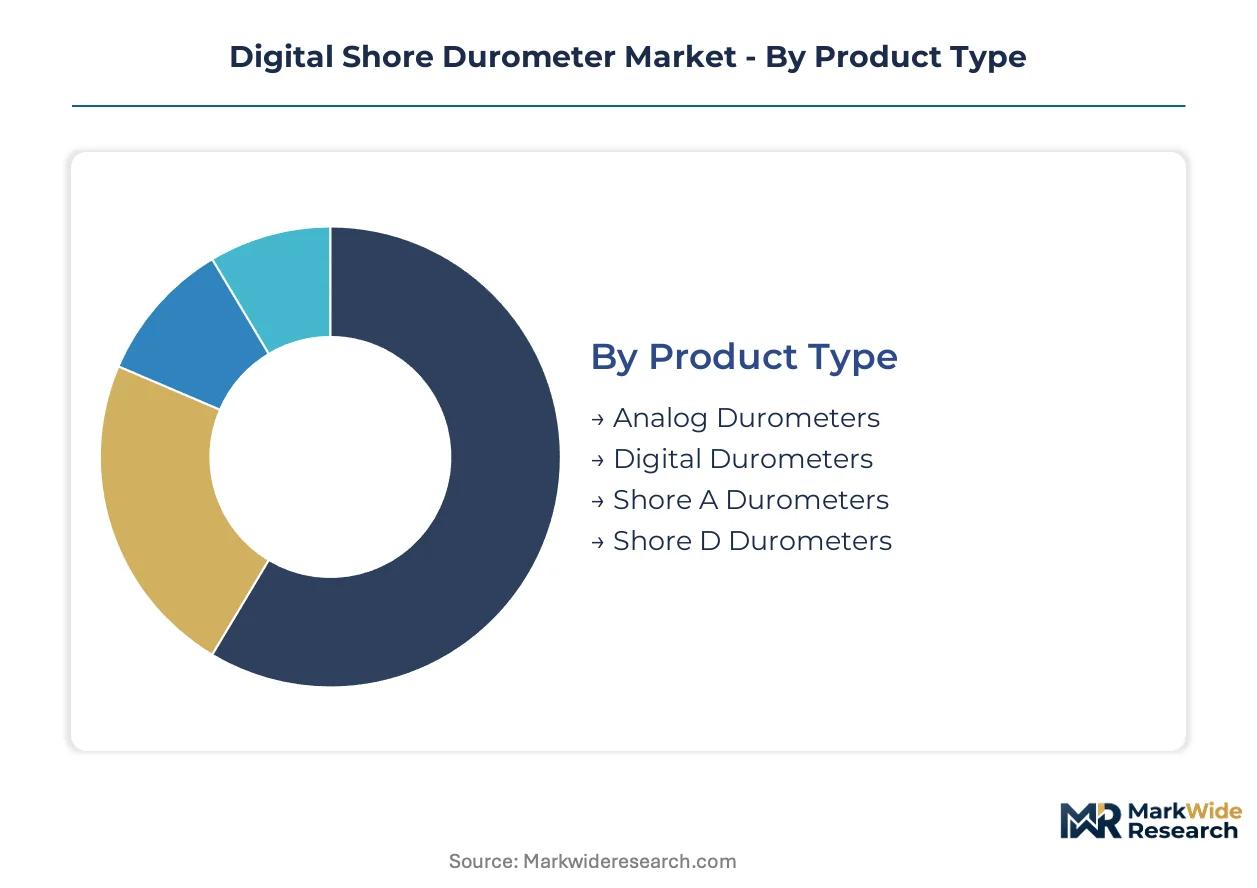
Digital Shore durometer segmentation reveals how instrument architecture, user environment, and measurement precision requirements fragment procurement patterns across polymer testing workflows. Buyers select configurations based on regulatory traceability mandates, floor durability needs, and data integration complexity rather than hardware specifications alone.
Product Type:
Standalone benchtop units serve laboratory accreditation requirements while embedded sensor modules integrate into automated production lines for real-time hardness monitoring.
- Digital Durometers:Electronic displacement sensors deliver 0.1 Shore unit resolution with NIST-traceable calibration certificates. Automotive tier-one suppliers in Germany and Japan are retiring analog fleets to satisfy ISO 17025 mandates from accreditation bodies. These instruments anchor laboratory procurement budgets despite premium positioning.
- Analog Durometers:Mechanical dial indicators persist on manufacturing floors where contract specifications omit digital documentation requirements. Cost-sensitive polymer processors in India and Southeast Asia continue fleet maintenance rather than upgrading.
- Shore A Durometers:Soft elastomer measurement dominates tire manufacturing and sealing component validation.
- Shore D Durometers:Engineering plastics testing accelerates in aerospace structural component programs.
Digital durometers lead volumes today; Shore D configurations are gaining share fastest.
Application:
Cost tier stratification separates high-frequency production floor testing from intermittent laboratory validation workflows.
- Quality Control:Every-batch hardness gates at tire plants and medical device molding operations require ruggedized handheld units with immediate pass-fail indicators. Automotive OEMs in Michigan and Stuttgart mandate standardized instrument models across supplier networks to ensure data comparability.
- Research & Development:Materials scientists demand software-integrated benchtop systems with statistical process control export capabilities. Premium pricing reflects data-logging depth and LIMS compatibility rather than sensor precision alone.
- Material Testing:Contract laboratories perform standardized Shore hardness as part of multi-property characterization suites.
- Manufacturing:At-line testing integrates durometers into automated inspection cells for continuous process monitoring.
Quality control commands the largest procurement volumes; R&D applications attract the steepest price premiums.
End User:
Customer type determines calibration service bundling requirements and training intensity.
- Automotive Industry:Tire manufacturers and sealing suppliers deploy Shore A instruments at every production gate to validate OEM durability specifications. Continental, Bridgestone, and Goodyear operations specify identical durometer models across plants to preserve inter-facility data integrity.
- Laboratory Testing:ISO 17025-accredited facilities require embedded calibration certificates and documented measurement uncertainty budgets. Notified bodies in Germany and Ireland reject medical device submissions lacking accredited hardness data.
- Manufacturing Plants:Polymer processors prioritize instrument durability over precision in non-contract-critical applications.
- Educational Institutions:Training programs purchase entry-level digital units for materials science curriculum.
Automotive procurement concentrates the largest instrument volumes; laboratory testing drives premium feature adoption.
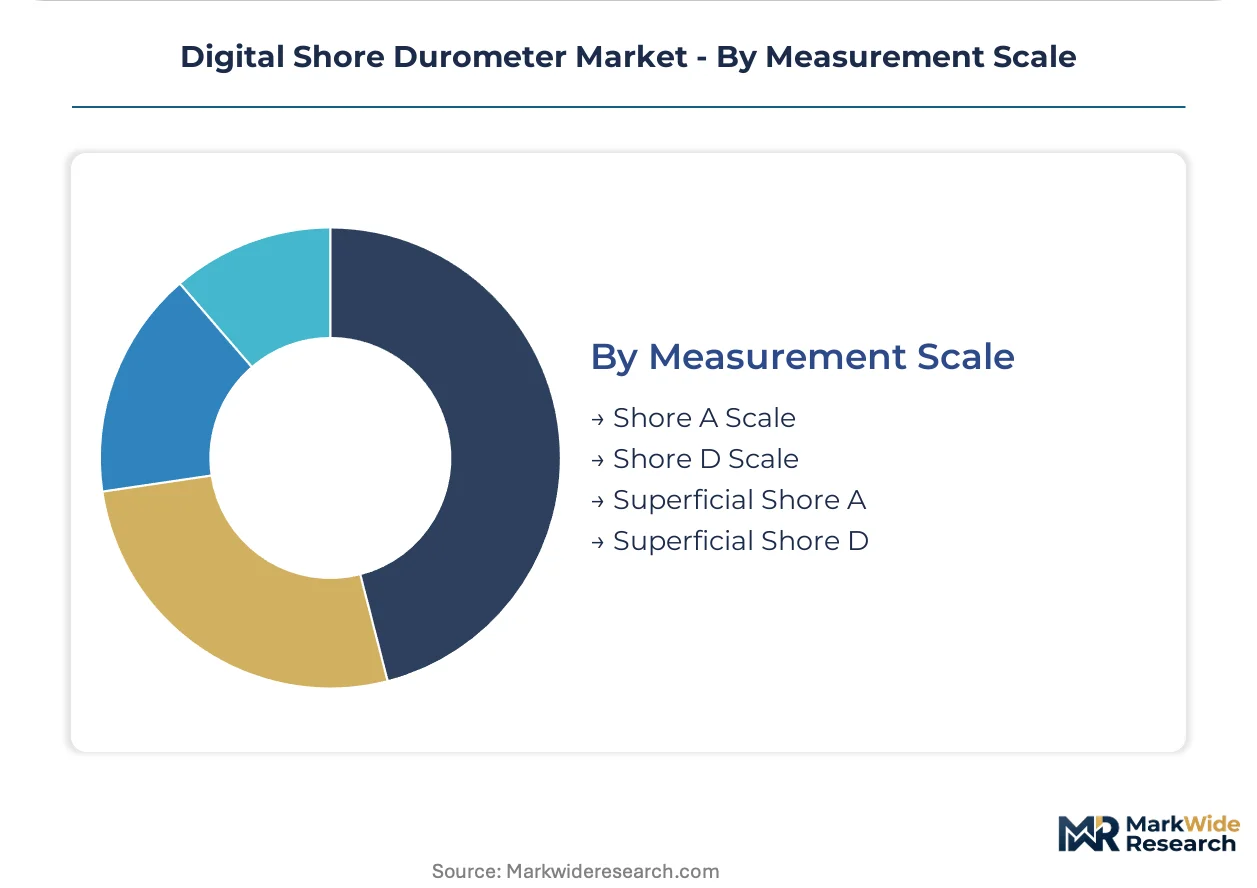
Measurement Scale:
Scale selection tracks polymer hardness range with Shore A dominating soft elastomers and Shore D penetrating structural plastics.
- Shore A Scale:Rubber compounds, thermoplastic elastomers, and soft polymers constitute the majority of industrial hardness testing. Tire rolling resistance regulations from the US EPA and durability specifications from German OEMs sustain demand concentration.
- Shore D Scale:High-durometer engineering plastics in aerospace and electronics applications require scale extension beyond Shore A limits. Japanese electronics manufacturers validate structural polymer components for portable device housings.
- Superficial Shore A:Thin specimen and coating applications prevent substrate influence on hardness readings.
- Superficial Shore D:Hard surface layers on soft substrates enable specialized composite characterization.
Shore A scale anchors current procurement; Shore D scale is climbing the fastest as engineering plastics displace metals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision metrology demand while Japan anchors high-resolution sensor supply chains for digital Shore durometers. The United States drives automotive tier-one procurement volumes. India and China represent emerging manufacturing uptake zones with divergent regulatory maturity.
Germany
Automotive OEMs in Stuttgart and Munich mandate standardized Shore hardness testing across sealing supplier networks. EU MDR Annex I requirements enforce ISO 17025-accredited documentation for polymer-based medical devices. Notified bodies in Berlin and Frankfurt reject device submissions lacking validated hardness data from digital instruments.
United States
Tire manufacturers in Michigan deploy Shore A durometers at every-batch quality gates for OEM durability specifications. EPA rolling resistance regulations and FDA 21 CFR Part 820 quality system rules require documented hardness validation. Automotive testing laboratories in Detroit concentrate instrument procurement authority under centralized corporate metrology functions.
Japan
Electronics manufacturers validate structural polymer components for portable device housings using Shore D scale instruments. METI industrial standards and JIS calibration protocols shape precision instrument specifications. Precision instrument clusters in Tokyo and Aichi Prefecture dominate high-end digital durometer distribution networks.
China
Domestic polymer processors accelerate first-time digital instrument adoption under tightening GB standards for automotive components. MIIT industrial upgrading programs and SAMR metrology directives pressure manufacturing floors toward electronic displacement sensors. Yangtze River Delta testing laboratories retire analog fleets to satisfy accreditation body mandates.
India
Domestic tire and sealing component manufacturers drive initial digital durometer procurement as BIS certification requirements tighten. CDSCO medical device regulations and automotive component quality mandates create dual compliance pressure. Polymer processing clusters in Maharashtra and Gujarat represent the fastest-growing instrument installation bases.
Digital Shore Durometer Market Vendor Landscape
Japanese producers anchor the high-precision tier; German specialists hold integrated materials testing platforms. The vendor base concentrates around precision instrument heritage firms and diversified testing equipment conglomerates. Three archetypes dominate: metrology heritage specialists, integrated platform bundlers, and portable handheld manufacturers. Competitive moves center on calibration service network expansion and wireless sensor interoperability development.
Within the metrology heritage tier, Mitutoyo Corporation and Shimadzu Corporation exemplify precision instrument lineage translated into Shore hardness measurement authority. ZwickRoell Group occupies a position among integrated platform providers that bundle hardness testing with tensile and flexural characterization. Imada represents the portable handheld segment focused on manufacturing floor durability rather than laboratory precision. These three anchors illustrate how competitive positioning fragments across user environment requirements rather than converging on uniform specifications.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| ZwickRoell Group |
| Shimadzu Corporation |
| Instron |
| Imada |
| Hildebrand |
| Insize |
| Shore Instruments & Mfg., Inc. |
| PCE Instruments |
| Others |
Supply Flow & Price Mechanics
Metrology technician scarcity in Germany, Japan, and the United States drives labor-cost differentials that separate premium-tier laboratory instruments from economy-grade manufacturing-floor units. Calibration service bundling requirements widen price spreads as NIST-traceable accreditation concentrates in mature metrology hubs.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for entry-level digital durometers while premium laboratory segments retain margin insulation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 17025-accredited units commanding substantial premiums over uncertified manufacturing-floor alternatives. Cost compression in the economy tier is intensifying because domestic Chinese producers expand displacement sensor assembly capacity. Automotive tier-one suppliers demonstrate lowest price sensitivity due to mandated instrument standardization, whereas Indian polymer processors exhibit highest sensitivity as first-time digital adopters.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Continental, Bridgestone, and Goodyear, while specialized metrology distributors serve fragmented laboratory procurement. Precision displacement transducers draw from Japanese and German component suppliers, creating single-source vulnerability for high-resolution sensor modules. Distribution runs through precision instrument clusters in Tokyo, Stuttgart, and Detroit that anchor calibration service networks. Tariff exposure on electronic sensor imports from Japan threatens lead time stability for North American instrument assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Shore Durometer Market functions as a regulatory compounder where EU MDR Annex I general safety and performance requirements enforce ISO 17025-accredited documentation, accelerating replacement cycles beyond normal hardware depreciation schedules.
For Market Incumbents: Lock in calibration service network density across automotive manufacturing corridors in Michigan, Stuttgart, and Aichi Prefecture to defend against emerging portable MEMS-based entrants. Deepen backward integration into displacement sensor production to reduce Japanese component dependency. Consolidate software-integrated benchtop offerings to capture R&D premium pricing before cloud-native competitors fragment the data-logging segment.
For New Entrants and Emerging Players: Capture India manufacturing floor demand by targeting BIS-certified automotive component suppliers with ruggedized handheld units priced below Mitutoyo and Imada entry points. Wireless sensor integration paired with cloud-based SPC software offers the most penetrable angle against legacy vendors with proprietary data formats. Focus initial deployment on Maharashtra and Gujarat polymer processing clusters where first-time digital adoption accelerates.
For Investors and Strategic Acquirers: Precision instrument conglomerates are the most active acquirer in this space, seeking calibration service capabilities to bundle with hardware margins. Long-term viability rests on regulatory tailwinds from medical device biocompatibility testing and tire rolling resistance documentation mandates. Watch for FDA 21 CFR Part 820 enforcement intensity as the inflection signal determining replacement cycle compression rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | NIST-traceable accreditation in Germany and Japan preserves instrument qualification pathways for medical device submissions. |
| MEMS Sensor Integration | Sub-0.1 Shore unit resolution in battery-powered handheld units collapses the laboratory-manufacturing floor performance gap. |
| Wireless Sensor Interoperability | Bluetooth-enabled durometers paired with cloud SPC software penetrate automotive tier-one supplier standardization mandates. |
| Backward Integration into Displacement Transducers | In-house sensor production reduces dependency on Japanese and German single-source component suppliers. |
| ISO 17025 Embedded Certification | Accredited calibration certificates embedded at manufacture satisfy EU MDR notified body rejection criteria for polymer-based devices. |
Methodological Framework
Bottom-up automotive and medical device end-use modeling reconciled against top-down precision instrument manufacturer tracking forms the analytical core. Primary interviews with quality control managers at tire plants, metrology laboratory accreditation officers, biomedical engineers at medical device contract manufacturers, and polymer processing plant engineers combined with secondary validation from FDA 510(k) filings, EPA rolling resistance regulation dockets, ISO 17025 accreditation body records, and customs trade data for displacement sensor imports. Triangulation between demand-side procurement patterns and supply-side production capacity ensures segment-level consistency.
Input-output matrices map Shore A and Shore D scale instrument flows across quality control, research and development, and material testing applications. Segmentation dimensions include product architecture, measurement scale, end-user industry, and regional regulatory maturity. CAGRs derive from instrument retirement cycle analysis correlated with accreditation mandate effective dates. Forecast inputs incorporate automotive OEM durability specification tightening and medical device biocompatibility testing expansion across the projection horizon.
Accreditation body enforcement variance, automotive OEM consolidation timing, and MEMS sensor cost curves are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Global Chiral Chromatography Column Market