
 Polybutadiene Rubber (PBR) Market | 2026-2036
Polybutadiene Rubber (PBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Polybutadiene Rubber (PBR) Market Analytics
Southeast Asian petrochemical complexes is realigning global PBR supply geography as new crackers come online in Thailand and Vietnam. China Petroleum & Chemical Corporation leverages its integrated refinery-polymer footprint to dominate domestic feedstock access. Kumho Petrochemical Co. Ltd. anchors specialty-grade output for premium tire compounds. JSR Corporation differentiates through advanced catalyst R&D for high-cis polymerization.
Polybutadiene rubber is a synthetic elastomer polymerized from 1,3-butadiene monomer, typically containing 90-98% cis-1,4 configuration in its high-grade form, with glass transition temperatures ranging from -90°C to -105°C depending on microstructure and catalyst system. Its primary commercial purpose centers on tire sidewalls and tread compounds where low rolling resistance and high abrasion resistance prove critical. High Cis product types command the dominant volume share due to superior elasticity and fatigue properties demanded by original equipment tire specifications. The Automotive end user segment channels the majority of value, though Industrial Products applications are gaining traction in conveyor belting and vibration-dampening components where oil resistance requirements intersect with cost-performance thresholds.
China's SAMR enforces GB standards governing rubber purity and additive limits, while REACH in Europe restricts certain catalyst residues and processing chemicals in imported PBR lots. The EPA in the United States monitors butadiene emissions from polymerization facilities under Clean Air Act provisions, elevating capital requirements for producers serving North American automotive contracts. Stakeholders must track evolving carbon-border adjustment mechanisms and catalyst technology transitions to preserve margin structures across regulated jurisdictions.
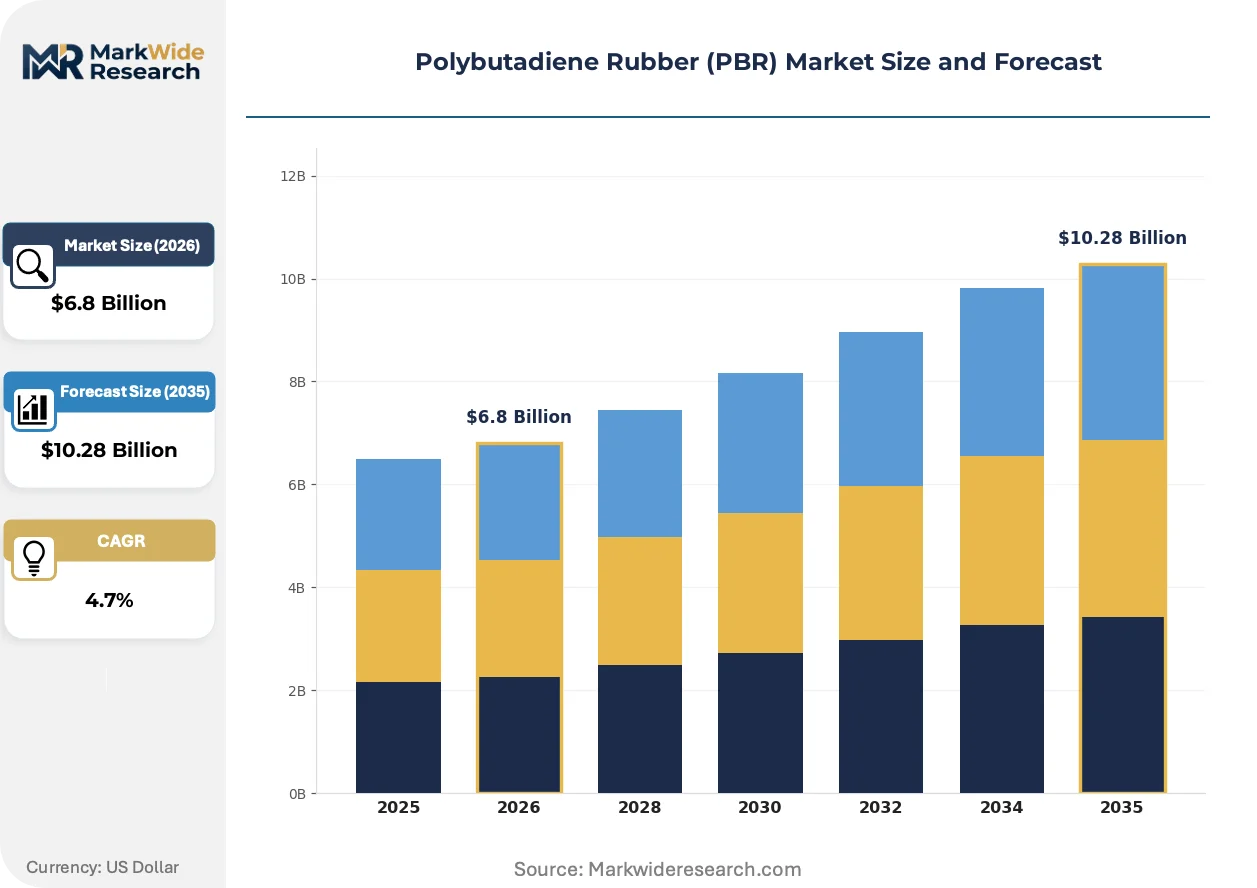
Market Dynamics
Tire manufacturers face mounting pressure to reformulate tread compounds as China's dual carbon goals and Europe's REACH restrictions tighten allowable catalyst residues and processing emissions across polymer supply chains.
Growth Catalysts
- Fuel-efficiency mandates:Automotive OEMs in Germany and Japan specify low-rolling-resistance tire compounds that demand high-cis PBR microstructures for elasticity retention under dynamic load.
- GB standard alignment:China's SAMR enforces purity thresholds that favor domestic producers with integrated refinery-polymer footprints capable of certifying additive limits.
- Specialty-grade differentiation:Premium tire compounders in South Korea procure advanced catalyst systems for fatigue-resistant sidewall formulations serving electric vehicle weight distribution requirements.
Market Restraints
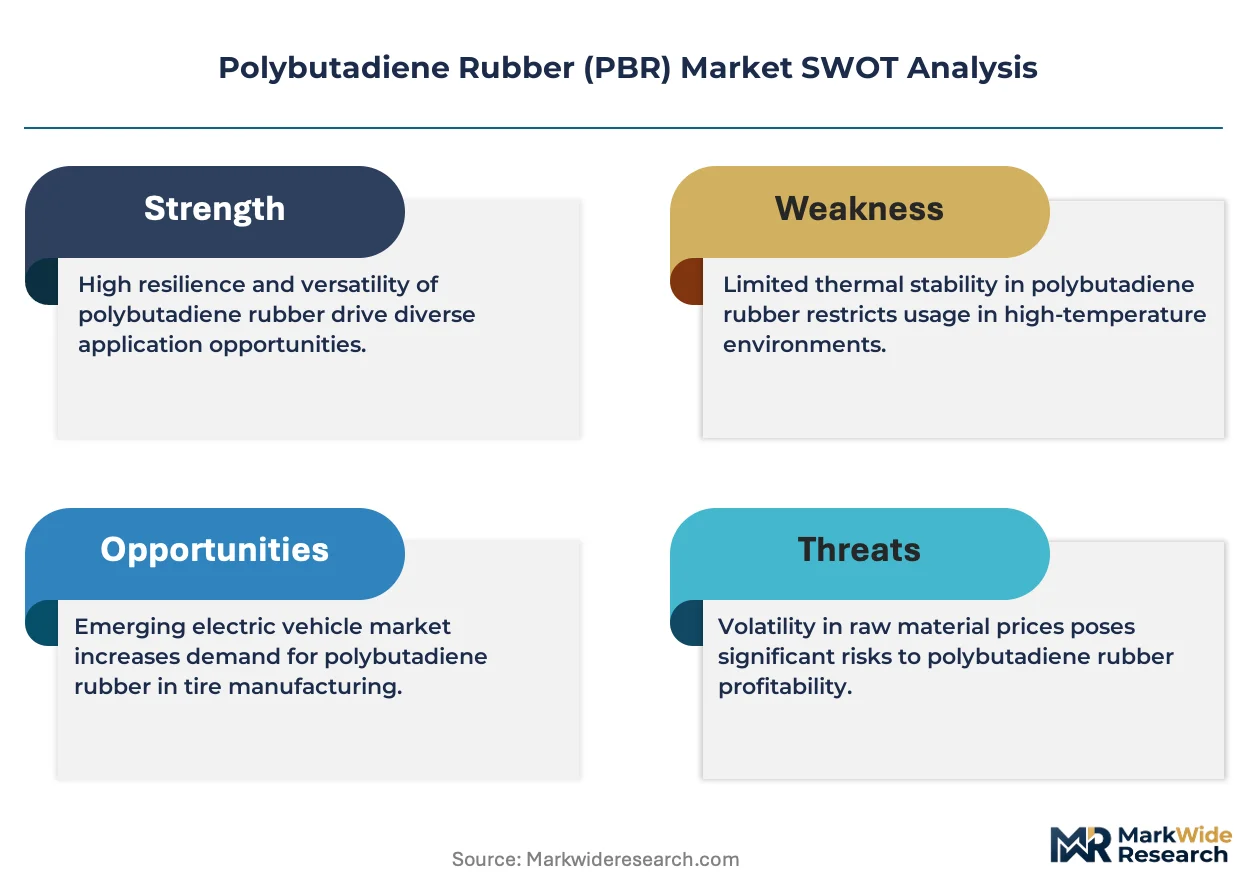
- Butadiene feedstock volatility:Naphtha cracker economics in Southeast Asia fluctuate with crude differentials, compressing margin predictability for non-integrated polymerizers.
- Supply concentration risk:East Asian manufacturing clusters around Shanghai and Ulsan channel over half of export-grade volume, exposing buyers to port congestion and regional logistics bottlenecks.
- Styrene-butadiene substitution:SBR compounds displace PBR in certain tread applications where wet-grip performance outweighs rolling-resistance optimization.
Strategic Opportunities
- Thailand cracker integration:New petrochemical complexes coming online in Map Ta Phut enable backward integration into butadiene monomer for regional polymerizers.
- Conveyor belting expansion:Industrial Products applications in mining and materials handling specify oil-resistant PBR compounds for vibration-dampening components.
- Carbon-border alignment:The EU's CBAM creates certification premiums for low-emission PBR lots that document catalyst residue and energy intensity through polymerization.
Industry Challenges
- Catalyst R&D talent scarcity:High-cis polymerization expertise concentrates among legacy Japanese and Korean research institutes, constraining new entrant process development.
- Clean Air Act capex burdens:EPA monitoring of butadiene emissions from polymerization facilities elevates scrubber and containment investments for North American contract qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybutadiene Rubber (PBR) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solution Polymer, Emulsion Polymer, High Cis, Low Cis Application: Tires, Footwear, Adhesives, Industrial Products End User: Automotive, Consumer Goods, Construction, Electronics Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | China Petroleum & Chemical Corporation, Zeon Corporation, LG Chem Ltd., UBE Corporation, LANXESS, ARLANXEO, Kumho Petrochemical Co. Ltd., Versalis S.p.A., JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybutadiene Rubber (PBR) Market Evolving Landscape
Polymerization technology and regulatory compliance frameworks are restructuring how PBR producers compete on catalyst efficiency, carbon intensity documentation, and specialty-grade certification.
Neodymium-based catalyst systems are absorbing development priority across high-cis polymerization lines. Tire compounders in Japan and South Korea specify these catalysts for superior stereospecificity and lower residual metal content. The technology is absorbing R&D budgets that previously targeted cobalt and nickel alternatives, compressing the viable catalyst menu for premium contract qualification.
REACH restrictions on certain processing chemicals and catalyst residues are reshaping import specifications for PBR lots entering European automotive supply chains. ECHA substance evaluations now cover specific neodymium and cobalt compounds used in polymerization initiators. German tire manufacturers are demanding full material passports documenting catalyst provenance and residual limits through polymerization.
Long-term offtake agreements are displacing spot-market procurement for tire-grade PBR volumes. Tier 1 automotive suppliers in China and South Korea now contract directly with integrated refinery-polymer operators for multi-year supply security. This concentration is most visible in the Yangtze River Delta manufacturing corridor, where Shanghai-based compounders lock in feedstock access ahead of cracker expansion cycles.
Polybutadiene Rubber (PBR) Market Segmentation
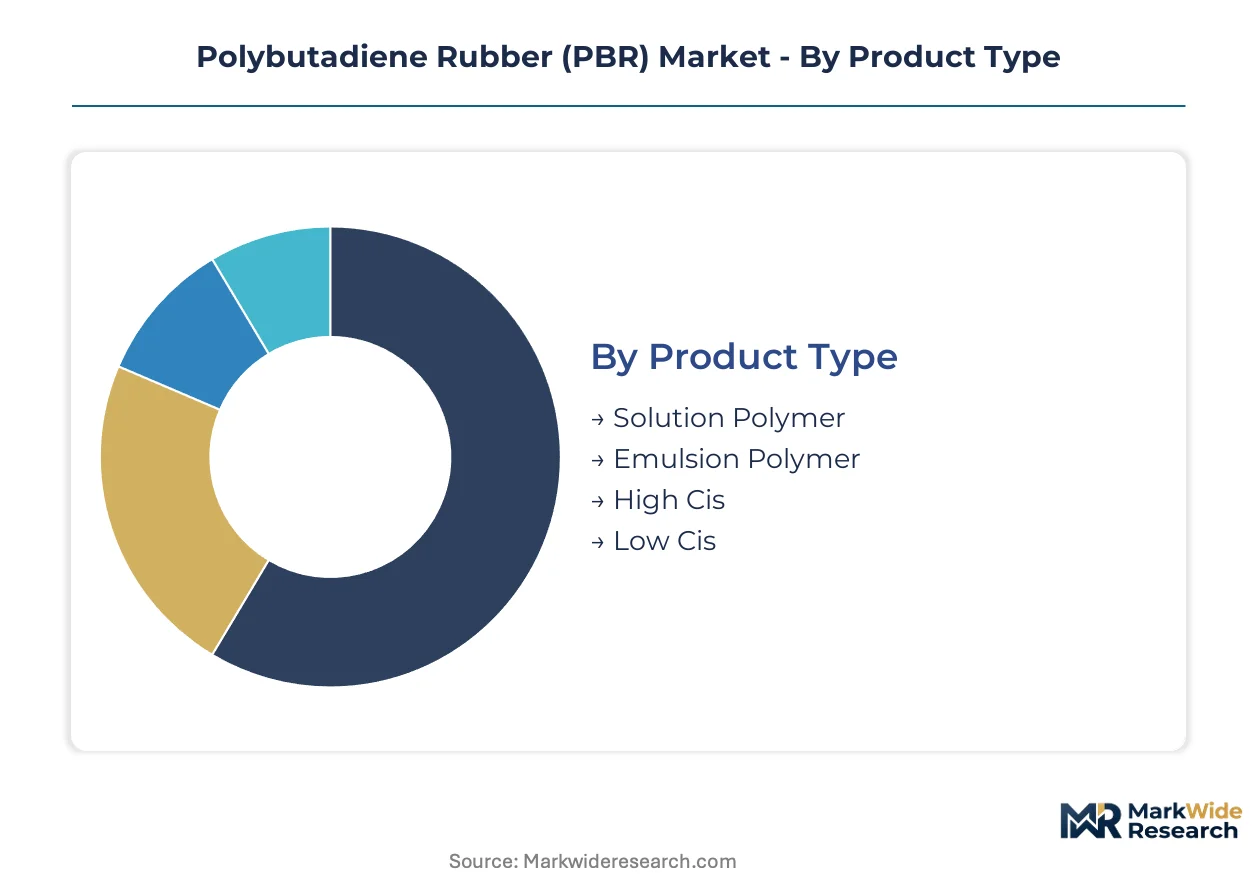
PBR formulation requirements diverge sharply across tire versus non-tire applications, with polymer microstructure specifications determining contract eligibility for automotive OEM supply chains. Catalyst systems and distribution economics create distinct margin profiles that reward specialization over commodity positioning.
Product Type:
Volume concentrates in standard high-cis grades, while premium tiers extract value from catalyst residue control and stereospecificity certification.
- High Cis:Contains 90-98% cis-1,4 configuration with glass transition temperatures between -90°C and -105°C, delivering superior elasticity and fatigue resistance. Tire compounders in Japan and South Korea specify this grade for electric vehicle sidewall formulations where weight distribution demands enhanced dynamic load performance. Mature deployment sits with High Cis. Newer deployment is concentrated in Low Cis.
- Solution Polymer:Manufactured via solution polymerization using neodymium, cobalt, or nickel catalyst systems, yielding narrower molecular weight distribution and cleaner microstructure than emulsion alternatives. German automotive suppliers now demand full material passports documenting catalyst provenance and residual metal limits for REACH compliance.
- Emulsion Polymer:Produced through aqueous emulsion systems with broader polydispersity, serving cost-sensitive applications where purity thresholds are less stringent.
- Low Cis:Features reduced cis-1,4 content for specialized compounding where processing characteristics outweigh elasticity optimization.
Neodymium catalyst lines are absorbing R&D investment that previously diversified across cobalt and nickel alternatives, narrowing the viable technology menu for premium contract qualification.
Application:
Tire manufacturing channels the dominant value flow, though industrial applications are climbing fastest as oil resistance specifications intersect with cost-performance thresholds.
- Tires:Sidewall and tread compounds consume the majority of high-cis volume, with original equipment specifications mandating low rolling resistance and high abrasion resistance. China's GB standards and dual carbon goals are tightening allowable additive limits and processing emissions across polymer supply chains serving domestic automotive production.
- Industrial Products:Conveyor belting and vibration-dampening components specify oil-resistant PBR compounds for mining and materials handling operations. Mining operators in Australia and Brazil are specifying fatigue-resistant formulations for heavy-duty conveying systems operating under continuous load cycles.
- Footwear:Soling compounds leverage PBR for abrasion resistance and flex crack resistance in athletic and industrial boot applications.
- Adhesives:Pressure-sensitive and contact adhesive formulations utilize PBR tack and cohesive strength for construction and assembly bonding.
Long-term offtake agreements are displacing spot-market procurement for tire-grade volumes, while industrial applications retain more fragmented purchasing patterns.
End User:
Automotive OEMs command pricing premiums through certified supply chains, with construction and electronics representing emerging specification development.
- Automotive:Tier 1 tire suppliers contract directly with integrated refinery-polymer operators for multi-year supply security. Shanghai-based compounders in the Yangtze River Delta manufacturing corridor are locking in feedstock access ahead of cracker expansion cycles to secure volume commitments.
- Construction:Waterproofing membranes, sealants, and expansion joint compounds specify PBR for weathering resistance and elasticity retention.
- Consumer Goods:Sporting equipment, footwear, and household products utilize PBR for durability and processing economics.
- Electronics:Emerging applications in cable insulation and component encapsulation are developing specification frameworks for dielectric performance.
Automotive qualification timelines stretch 18-24 months, while consumer goods and construction segments permit faster supplier switching.
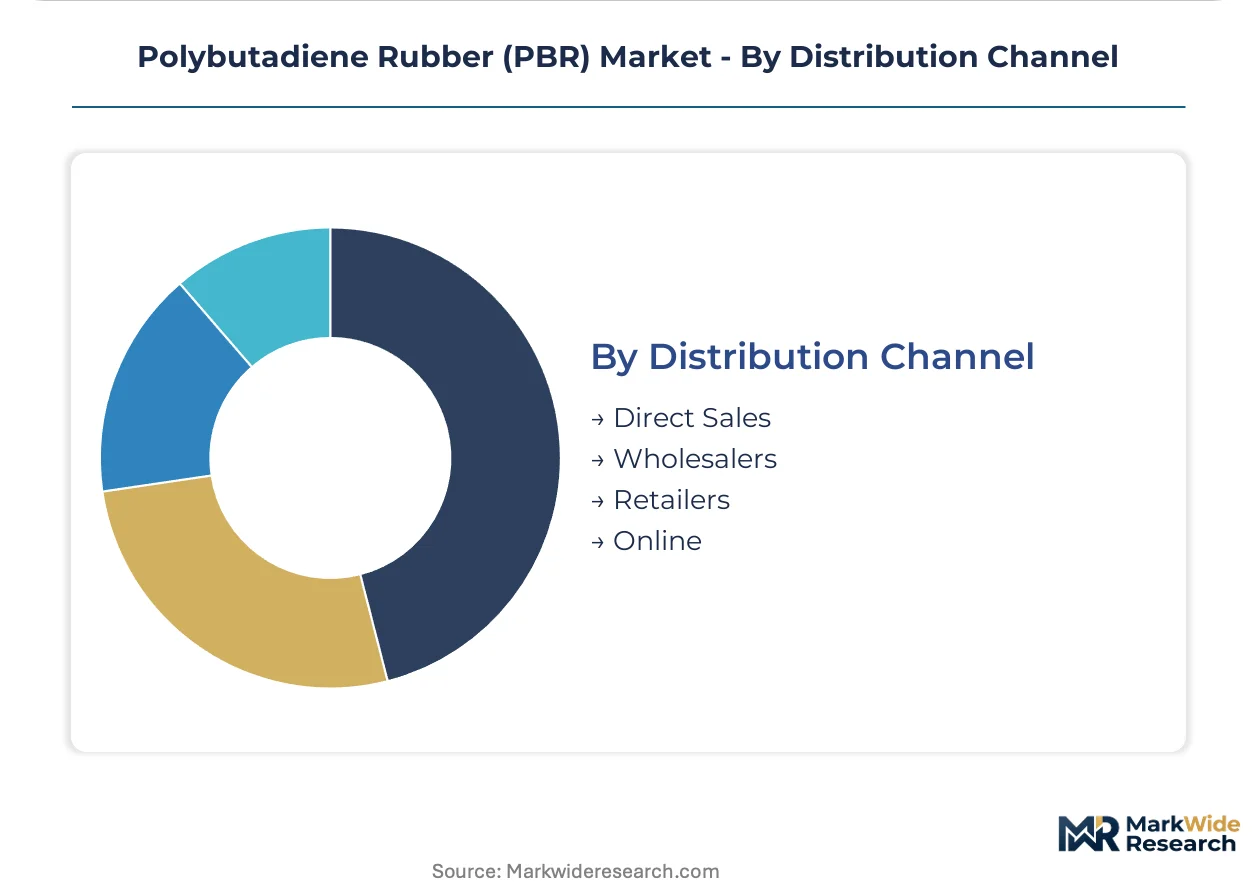
Distribution Channel:
Direct sales capture automotive and large industrial accounts, with intermediaries serving fragmented regional demand.
- Direct Sales:Integrated producers such as China Petroleum & Chemical Corporation and Kumho Petrochemical Co. Ltd. maintain direct relationships with tire compounders for volume commitments and technical service support.
- Wholesalers:Regional distributors stock standard grades for industrial processors and smaller compounders lacking direct refinery access.
- Retailers:Limited presence for small-volume specialty grades and aftermarket repair compounds.
- Online:Emerging for technical documentation and sample procurement, though bulk polymer transactions remain relationship-driven.
Direct sales infrastructure is concentrating among integrated producers with captive butadiene supply, while wholesaler networks face margin compression from feedstock volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butadiene feedstock availability in East Asian coastal zones anchors the geographic distribution of polybutadiene rubber production. China's integrated refinery-polymer complexes and South Korea's specialty-grade manufacturers concentrate capacity where naphtha crackers cluster. Regulatory frameworks in Germany and the United States impose emissions and residue standards that reshape trade flows for export-grade material.
China
Domestic tire production and electric vehicle expansion drive consumption of high-cis PBR grades. SAMR enforces GB standards governing rubber purity and additive limits that favor integrated producers with captive butadiene supply. The Yangtze River Delta manufacturing corridor around Shanghai channels the majority of compounder procurement through long-term offtake agreements.
South Korea
Premium tire specifications for automotive OEMs demand fatigue-resistant sidewall formulations with advanced catalyst systems. The national chemical regulator aligns with REACH-equivalent substance evaluations for polymerization initiators. The Ulsan petrochemical complex anchors specialty-grade output serving domestic compounders and export markets.
Germany
Automotive OEMs in Stuttgart and Munich specify low-rolling-resistance tire compounds requiring certified high-cis microstructures. ECHA substance evaluations cover neodymium and cobalt compounds used in polymerization, mandating full material passports. The Ruhr industrial region hosts compounders demanding documented catalyst provenance and residual metal limits.
United States
Clean Air Act provisions elevate capital requirements for polymerization facilities serving North American automotive contracts. EPA monitoring of butadiene emissions compresses margin structures for non-integrated producers. The Gulf Coast petrochemical corridor maintains feedstock access but faces scrubber and containment investments for contract qualification.
Japan
Neodymium-based catalyst R&D concentrates among legacy research institutes supporting stereospecificity improvements. METI frameworks guide chemical substance management for polymerization processes. The Chubu and Kansai industrial regions house tire compounders procuring advanced catalyst systems for dynamic load performance specifications.
Polybutadiene Rubber (PBR) Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and catalyst technology dimensions. The market structure concentrates among integrated petrochemical groups with captive butadiene supply and specialty polymerizers with advanced catalyst expertise. Three archetypes dominate: state-linked energy majors with refinery-polymer footprints, independent Korean and Japanese specialists in high-cis polymerization, and European diversified chemical groups with REACH-compliant certification systems. Capacity expansion and backward integration into butadiene monomer represent the primary competitive vectors.
Within the integrated energy-major tier, China Petroleum & Chemical Corporation exemplifies the state-linked archetype with refinery-polymer coordination. Kumho Petrochemical Co. Ltd. and JSR Corporation occupy positions among Asian specialists concentrating catalyst R&D and premium-grade certification. These three entities represent distinct strategic postures: feedstock security through vertical integration, specialty-grade differentiation through polymerization expertise, and advanced catalyst systems for stereospecificity control.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Zeon Corporation |
| LG Chem Ltd. |
| UBE Corporation |
| LANXESS |
| ARLANXEO |
| Kumho Petrochemical Co. Ltd. |
| Versalis S.p.A. |
| JSR Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers with integrated refinery-polymer footprints anchor supply discipline and pricing power in polybutadiene rubber, compressing margin volatility for non-integrated compounders while amplifying cost pass-through leverage during feedstock swings.
Pricing Analysis
Technical service bundling separates contract structures in polybutadiene rubber procurement. Long-term offtake agreements dominate automotive supply chains, incorporating catalyst certification support and material passport documentation as bundled value-adds. Three-tier pricing structure across premium, standard, and economy levels reflects catalyst residue thresholds and stereospecificity grades. Price differentiation hinges on neodymium catalyst certification and REACH-compliant documentation. Pricing pressure stems from styrene-butadiene substitution in wet-grip-optimized tread applications. Industrial compounders exhibit highest price sensitivity due to fragmented purchasing power, while automotive OEMs absorb premiums for certified supply security.
Supply Chain Analysis
Regional distribution centers in Shanghai, Ulsan, and Map Ta Phut channel export-grade volumes through hub-and-spoke patterns serving tire compounders. Manufacturing concentrates in China, South Korea, and Thailand where naphtha crackers cluster. Feedstock draws from butadiene monomer produced at integrated petrochemical complexes. Logistics chokepoints at East Asian port clusters expose buyers to congestion risk during cracker maintenance cycles. Distribution runs through direct sales for automotive tier 1s and wholesaler networks for fragmented industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polybutadiene rubber is transitioning from cobalt and nickel catalyst systems to neodymium-based polymerization, with legacy technology capacity facing stranded-asset risk as automotive OEMs mandate residue documentation.
For Market Incumbents: Extend catalyst R&D partnerships with Japanese research institutes to secure neodymium stereospecificity expertise before capability scarcity hardens. Lock in long-term offtake agreements with Yangtze River Delta compounders ahead of Thailand cracker expansions. Defend against styrene-butadiene substitution by certifying low-rolling-resistance grades for electric vehicle weight distribution requirements. Prioritize backward integration into butadiene monomer at Map Ta Phut and Ulsan complexes to preserve margin structures during naphtha volatility. For New Entrants and Emerging Players: Enter via conveyor belting and mining applications in Australia and Brazil where oil-resistant compound specifications outpace established supplier coverage. Target industrial products segments with shorter qualification timelines than automotive certification. Exploit fragmentation in vibration-dampening component procurement where direct refinery relationships remain underdeveloped. Build technical service capabilities around fatigue-resistant formulation support rather than competing on commodity spot pricing. For Investors and Strategic Acquirers: Distressed-cycle entries favor non-integrated polymerizers with stranded cobalt catalyst lines in Southeast Asia, where feedstock volatility has compressed valuations below replacement cost. Five-to-ten year viability hinges on successful catalyst technology transition and carbon-border adjustment mechanism compliance. Watch for EU CBAM implementation pace as inflection indicator for certified low-emission lot premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Monomer | Map Ta Phut cracker complexes enable captive feedstock supply for regional polymerizers. |
| Neodymium Catalyst Certification Program | German automotive OEMs now mandate REACH-compliant material passports documenting residue limits. |
| Long-term Supply Agreement | Shanghai-based compounders lock in volume commitments ahead of cracker expansion cycles. |
| Joint Venture for High-Cis R&D | Japanese research institutes concentrate stereospecificity expertise supporting premium grade development. |
| Green Manufacturing Transition | EU CBAM creates certification premiums for documented low-emission polymerization processes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving polymer plant managers, tire compounder procurement leads, catalyst R&D directors, and distribution channel partners. SEC 10-K disclosures, Cefic synthetic rubber reports, and SAMR GB standard documentation provided production and compliance benchmarks. Bottom-up volume modeling triangulated against top-down demand estimates from automotive production databases.
Segment-level granularity applied across product type tiers, application categories, end-user industries, and regional production hub clusters throughout the forecast period. CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific inputs incorporated electric vehicle penetration assumptions, REACH substance evaluation timelines, and naphtha cracker operating rate trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt catalyst technology transitions or carbon-border mechanism acceleration. Outputs reflect documented assumptions regarding feedstock integration economics and regulatory compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Tire Recycling Downstream Products Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Global Tire Material Market
Rubber
Rubber Block Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Silicone Rubber Market
Rubber
Rubber Sheets Market
Rubber
Liquid Polybutadiene Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Rubber Valve Stem Market
Rubber
Rubber Foam Market
Rubber
Rubber Gloves Market
Rubber
Europe Silicone Rubber Market
Rubber
Recycled Elastomers Market
Rubber
Flexible Rubber Sheets Market
Rubber
Rubber Bulb Seals Market