
 Reclaimed Rubber Market | 2026-2036
Reclaimed Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Reclaimed Rubber Market Intelligence
Subscription-based technical support for reclaim process optimization is repositioning supplier relationships from commodity transactions to performance partnerships. GRP Ltd. leverages its pyrolysis expertise to anchor high-value crumb rubber output for European tire makers. Tianyu (Shandong) Rubber & Plastic Products Co., Ltd. dominates reclaimed sheet rubber production through integrated devulcanization lines serving domestic automotive clients.
Reclaimed rubber comprises vulcanized scrap rubber that undergoes mechanical, thermal, or chemical devulcanization to restore plasticity, typically achieving 40-60% of original polymer chain length for recompounding into new products. Its primary purpose is substituting virgin synthetic or natural rubber in cost-sensitive, non-dynamic applications where tensile requirements remain moderate. Crumb rubber leads volume due to road construction absorption under federal and state infrastructure programs, while powdered rubber captures expanding margin pools in precision molding applications requiring consistent particle size distribution. Granulated rubber occupies a mature position in industrial matting and acoustic barriers where bulk fill economics prevail over performance specifications.
EPA landfill diversion rules and state-level scrap tire management programs in the US tighten feedstock availability, pushing reclaimers toward controlled collection networks. BIS certification requirements in India and REACH compliance obligations in Europe elevate quality barriers for export-oriented producers. Stakeholders must monitor devulcanization technology licensing costs against feedstock security to calibrate capacity commitments.
Market Dynamics
Devulcanization technology licensing costs and feedstock security tensions are forcing reclaimers to recalibrate capacity commitments against pyrolysis-to-reclaim upgrade cycles. Tire manufacturers in Asia are consolidating procurement of crumb rubber grades for cost-competitive tread compounds, compressing supplier margins while elevating quality certification requirements.
Growth Catalysts
- EPA landfill diversion mandates:US scrap tire management programs tighten feedstock availability, pushing reclaimers toward controlled collection networks and pyrolysis technology upgrades.
- EU REACH restrictions:Import constraints on virgin rubber accelerate European tire makers' absorption of BIS-certified reclaim grades from Indian suppliers.
- Crumb rubber:Federal and state infrastructure programs in road construction absorb volume leadership, creating stable demand baselines for reclaim processors.
Market Restraints
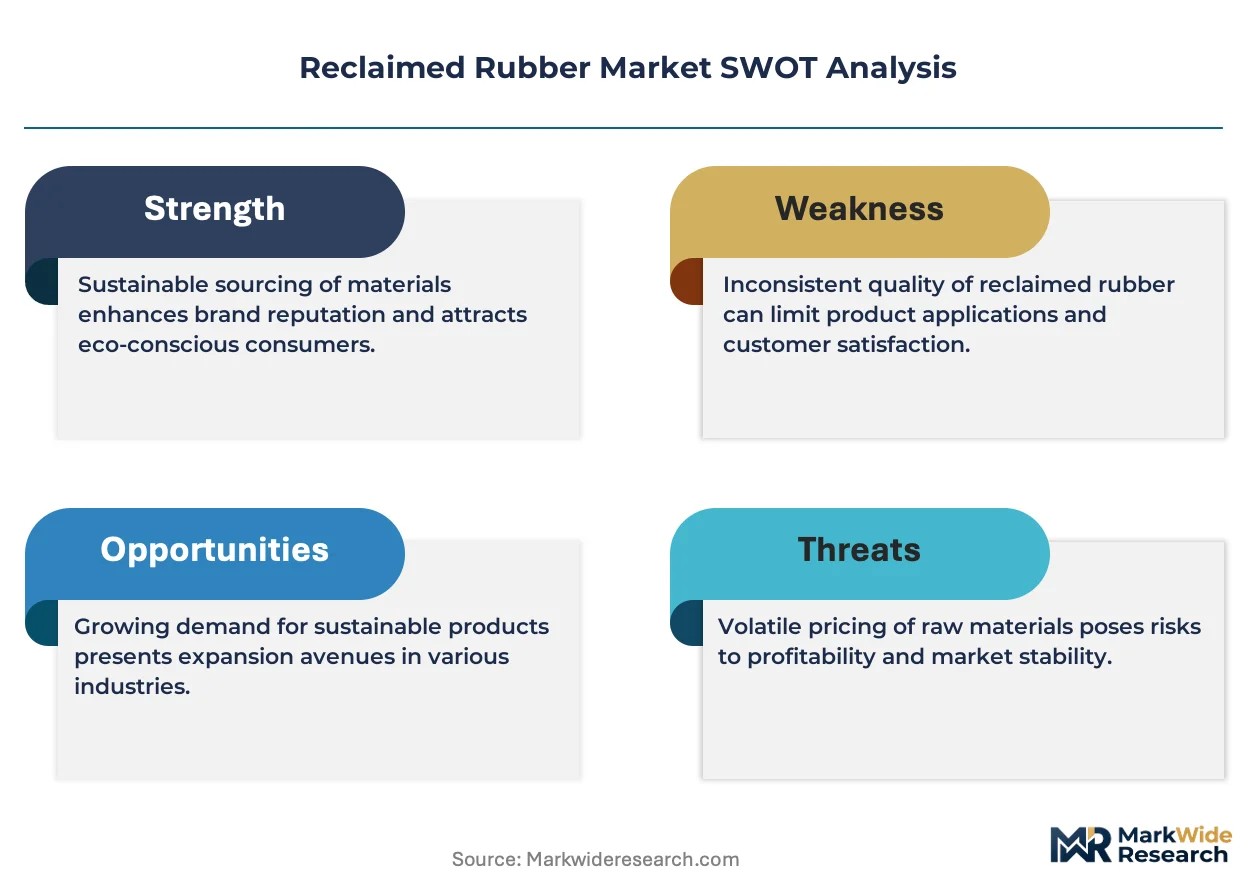
- Natural rubber price volatility:Feedstock cost swings compress reclaim rubber price advantages against virgin synthetic alternatives during commodity downcycles.
- Quality inconsistency:Mechanical devulcanization yields variable polymer chain restoration, limiting reclaimed rubber penetration in dynamic tire applications.
- BIS certification barriers:Indian quality standards create export friction for non-certified producers seeking placement in premium domestic tire supply chains.
Strategic Opportunities
- Precision molding applications:Powdered rubber with consistent particle size distribution captures expanding margin pools in automotive sealing components.
- Subscription-based technical support:Process optimization services reposition supplier relationships from commodity transactions toward performance partnerships.
- Acoustic barrier specifications:Granulated rubber bulk fill economics align with industrial matting demand in European construction markets.
Industry Challenges
- Devulcanization chemistry expertise:Thermal and chemical process optimization requires specialized polymer scientists, creating talent scarcity in emerging producer markets.
- Integrated line capex intensity:Continuous devulcanization systems demand substantial capital deployment, favoring scaled operators over batch processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reclaimed Rubber Market |
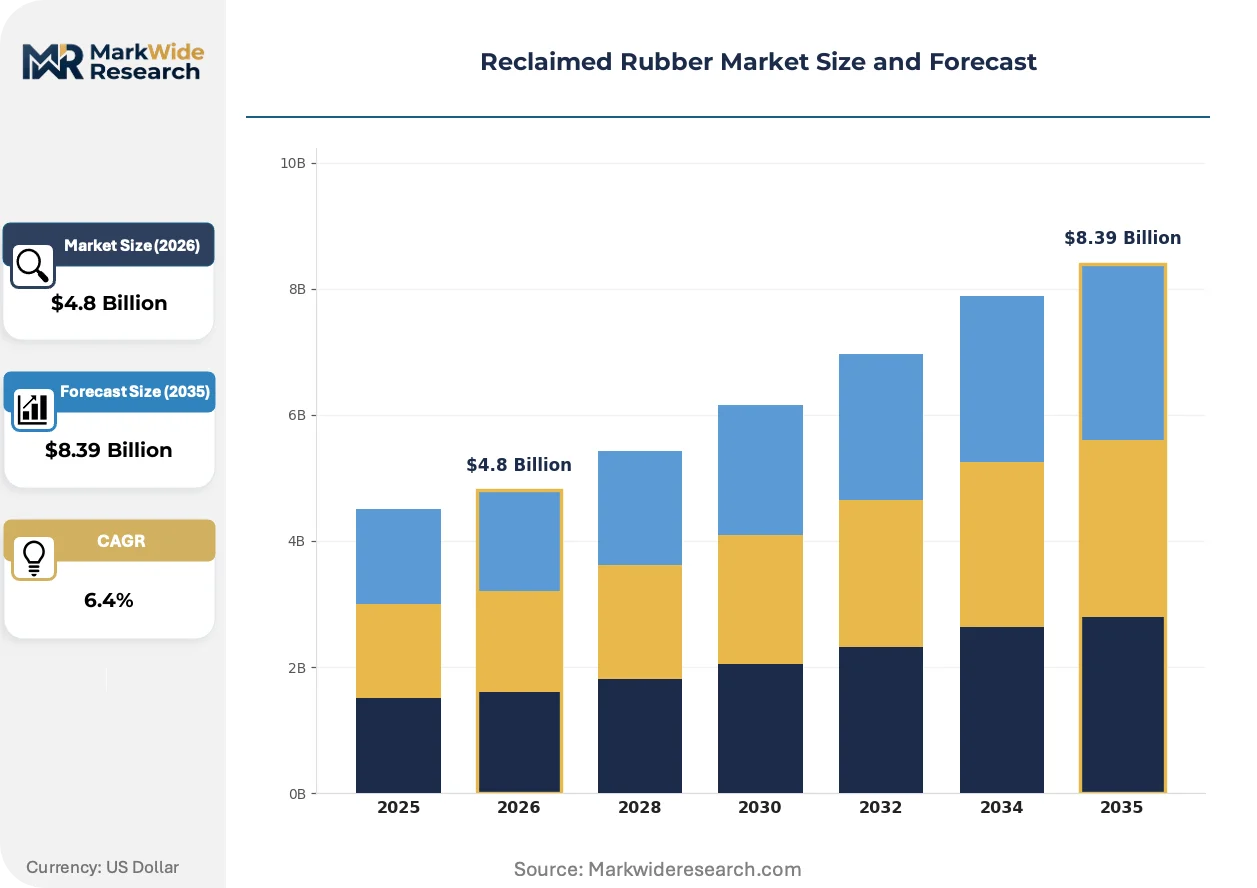
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crumb Rubber, Powdered Rubber, Granulated Rubber, Sheet Rubber End Use Industry: Automotive, Construction, Footwear, Industrial Products Form: Solid, Liquid, Composite, Foam Application: Road Construction, Tires, Molding, Coatings |
| Companies Covered | HUXAR, Balaji Rubber Industries Pvt. Ltd., GRP Ltd., Swani Rubber Industries, Fishfa Rubbers Ltd., J. Allcock & Sons Ltd., Tianyu (Shandong) Rubber & Plastic Products Co., Ltd., Minar Reclaimation Private Limited, Rolex Reclaim Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reclaimed Rubber Market Strategic Shifts & Innovations
Pyrolysis-to-reclaim technology upgrades are compressing production economics while regulatory compliance obligations reshape competitive positioning across feedstock procurement and quality certification. Three active shifts define the innovation landscape.
Continuous devulcanization reactor technology is consolidating process control advantages for reclaim rubber producers serving automotive tier-one suppliers. European tire manufacturers are adopting these systems at accelerated pace to meet REACH compliance timelines. The technology is consolidating batch processor market share by reducing energy intensity per ton and improving polymer chain length consistency.
EU REACH restrictions on virgin rubber imports are forcing reclaimers to upgrade quality certification infrastructure for export eligibility. Industrial consequence includes elevated laboratory investment and third-party testing partnerships. Powdered rubber segments serving precision molding applications are responding fastest, locking in multi-year supply agreements with certified Indian producers.
Buyer concentration among Asian tire manufacturers is compressing supplier negotiation leverage and elongating payment terms. Distributor networks serving smaller compounders are being displaced by direct mill relationships with volume commitments. This pattern is most visible in India, where domestic automotive clients are integrating backward into captive reclaim processing capacity.
Reclaimed Rubber Market Segmentation
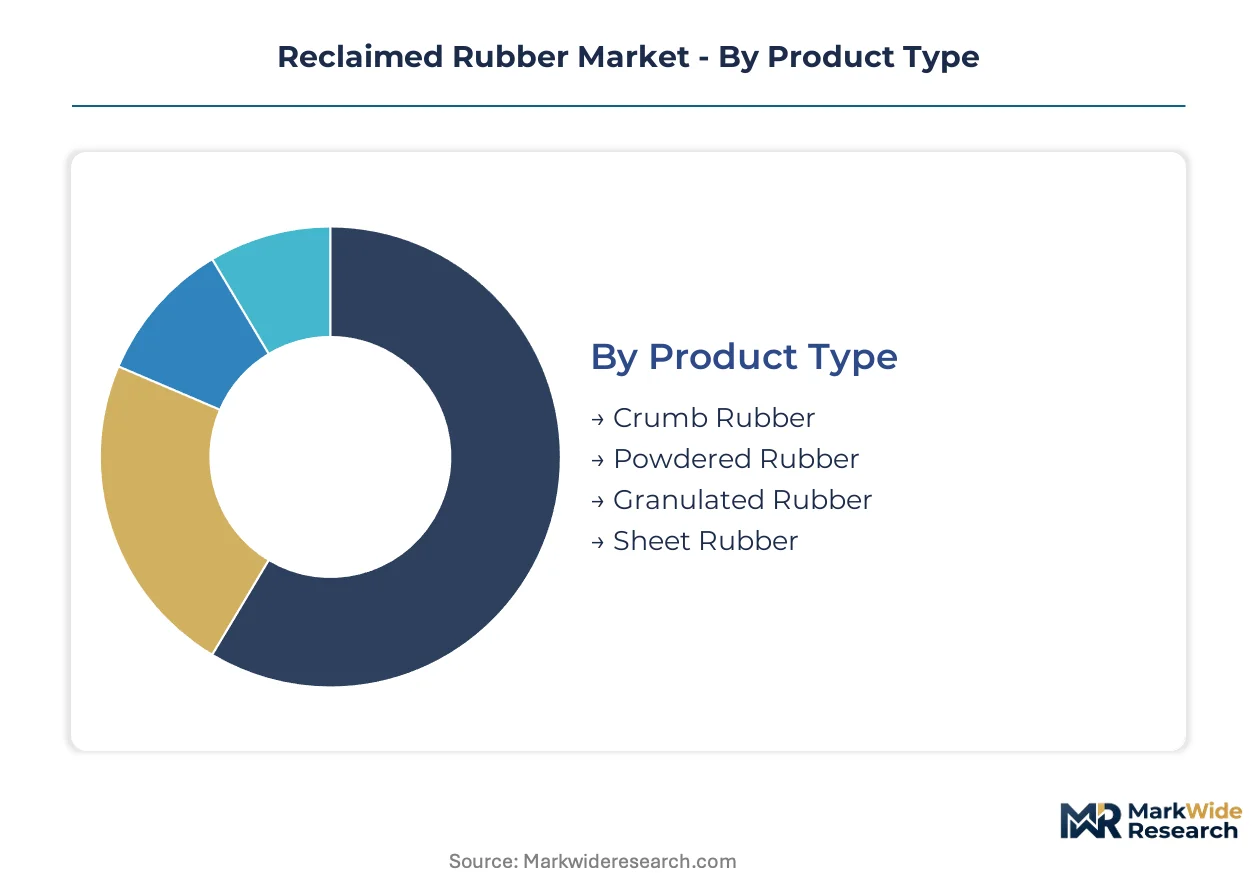
Reclaimed rubber producers navigate four distinct segmentation axes where buyer priorities diverge sharply. Product type determines processing technology investment, while end-use industry dictates certification requirements and margin capture potential.
Product Type:
Cost tier structures procurement decisions across tire manufacturers and compounders, with particle size precision commanding premium placement.
- Crumb Rubber:Ground vulcanized scrap with particle sizes ranging from 0.425mm to 4.75mm serves road construction absorption under federal and state infrastructure programs. US state-level procurement specifications favor this grade for asphalt modification, creating volume baselines that stabilize processor throughput.
- Powdered Rubber:Finely milled particles below 0.425mm achieve consistent particle size distribution critical for precision molding applications. Automotive sealing component manufacturers in Europe absorb expanding volumes as REACH compliance tightens virgin rubber substitution economics.
- Granulated Rubber:Coarse fragments between 4.75mm and 12.5mm fill industrial matting and acoustic barrier specifications where bulk economics prevail.
- Sheet Rubber:Devulcanized reclaimed material calendered into continuous sheets serves domestic automotive clients requiring consistent thickness tolerances for gasket production.
Crumb rubber leads on scale; powdered rubber leads on momentum.
End Use Industry:
Application maturity separates volume-driven commodity supply from performance-contracted technical partnerships.
- Automotive:Tier-one tire manufacturers and sealing component producers drive BIS-certified reclaim absorption in India, with direct mill relationships displacing distributor networks. REACH compliance timelines in Europe accelerate certified supplier qualification.
- Construction:Road construction specifications under federal and state programs absorb crumb rubber volume, while acoustic barrier applications in European markets leverage granulated rubber bulk fill economics.
- Footwear:Soling compounders utilize reclaimed sheet rubber for cost-sensitive non-dynamic applications where tensile requirements remain moderate.
- Industrial Products:Matting and gasket manufacturers source across all product types based on performance specifications and feedstock availability constraints.
Automotive commands margin premiums; construction provides volume stability.
Form:
Processing compatibility determines equipment retrofit requirements and compounder formulation flexibility.
- Solid:Standard calendered or extruded reclaim dominates tire and industrial applications requiring conventional mixing equipment compatibility.
- Liquid:Devulcanized rubber dispersed in processing oils enables spray-applied coatings and specialized adhesive formulations.
- Composite:Reclaim blended with virgin polymers or fillers targets intermediate performance tiers where cost optimization meets specification compliance.
- Foam:Expanded reclaim structures serve acoustic and cushioning applications with density specifications measured by end-use performance.
Solid form anchors throughput volumes; liquid form expands application boundaries.
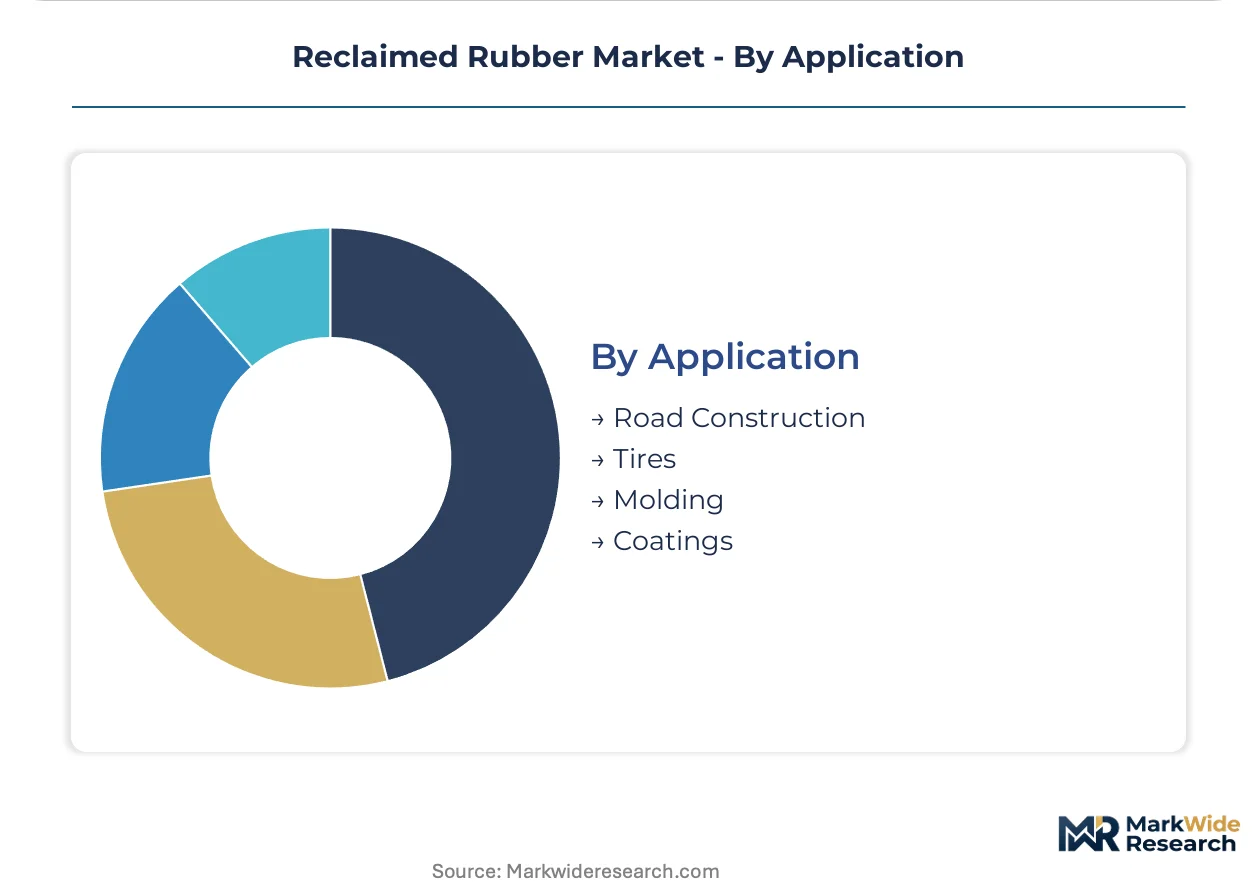
Application:
Specification intensity varies from prescriptive government standards to negotiated performance contracts.
- Road Construction:Federal and state infrastructure programs specify crumb rubber content percentages for asphalt modification, creating procurement baselines that absorb processor volume.
- Tires:Tread compound specifications demand consistent polymer chain length restoration, limiting reclaimed rubber penetration to non-dynamic components where quality certification unlocks placement.
- Molding:Precision automotive sealing components require powdered rubber with tight particle size distribution tolerances.
- Coatings:Liquid reclaim dispersions target industrial protective applications where spray application compatibility determines formulation acceptance.
Road construction absorbs volume leadership; molding captures expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as reclaimers migrate toward jurisdictions with lower compliance costs and abundant tire-derived feedstock. EPA landfill diversion mandates and EU REACH restrictions create divergent cost structures that reshape investment flows.
United States
State-level scrap tire management programs in California and Texas tighten feedstock availability, forcing reclaimers toward controlled collection networks. EPA enforcement of landfill diversion targets accelerates pyrolysis technology upgrades among processors serving road construction contractors. The Gulf Coast petrochemical corridor hosts expanding crumb rubber capacity for asphalt modification under federal infrastructure programs.
Germany
REACH compliance timelines for virgin rubber substitution drive automotive tier-one suppliers toward certified reclaim grades. The country's national chemical regulator enforces stringent quality documentation requirements that elevate laboratory investment thresholds. The Rhine-Ruhr industrial basin concentrates devulcanization capacity serving Continental and other domestic tire manufacturers.
India
BIS certification requirements unlock premium placement in domestic tire supply chains for compliant reclaim producers. The Bureau of Indian Standards mandates rigorous testing protocols that create export friction for uncertified competitors. Gujarat and Maharashtra host integrated devulcanization lines serving Maruti Suzuki and Tata Motors compounders directly.
China
Dual carbon goals and MIIT industrial efficiency standards pressure batch processors toward continuous reactor upgrades. The national standards administration tightens emissions controls on thermal devulcanization operations in Shandong Province. The Yangtze River Delta clusters precision molding-grade powdered rubber capacity for automotive sealing component exports.
Thailand
Natural rubber price volatility compresses reclaim substitution economics against virgin SMR grades in cost-sensitive applications. The country's industrial standards institute aligns quality protocols with ASEAN harmonization frameworks for cross-border tire trade. Eastern Economic Corridor zones attract pyrolysis-to-reclaim investments serving Japanese transplant automakers.
Reclaimed Rubber Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with certification-holding reclaimers commanding premium placement in automotive supply chains while commodity processors serve road construction volume. The market structure tilts toward regional concentration due to feedstock logistics constraints and devulcanization technology licensing costs. Three archetypes dominate: integrated tire-to-reclaim operators, independent pyrolysis specialists, and compounder-captive reclaim units. Competitive moves concentrate on backward integration into tire collection networks and continuous reactor technology licensing.
Among India-based reclaim specialists, GRP Ltd. and Balaji Rubber Industries Pvt. Ltd. exemplify the certification-driven archetype, while Tianyu (Shandong) Rubber & Plastic Products Co., Ltd. occupies a position within the integrated processing tier. Fishfa Rubbers Ltd. and Swani Rubber Industries represent regional scale operators competing on feedstock security rather than technology differentiation. These anchors illustrate how geographic clustering around tire manufacturing centers determines competitive positioning more than product innovation.
| Leading Market Players |
|---|
| HUXAR |
| Balaji Rubber Industries Pvt. Ltd. |
| GRP Ltd. |
| Swani Rubber Industries |
| Fishfa Rubbers Ltd. |
| J. Allcock & Sons Ltd. |
| Tianyu (Shandong) Rubber & Plastic Products Co., Ltd. |
| Minar Reclaimation Private Limited |
| Rolex Reclaim Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
EPA landfill diversion mandates gate qualified supply and premium-tier pricing access by forcing reclaimers toward controlled collection networks and pyrolysis technology upgrades. Tire manufacturers in Asia compress supplier margins while elevating quality certification requirements, creating tiered access economics that separate BIS-certified producers from commodity processors.
Pricing Analysis
Capacity additions in India are reshaping price floors as integrated devulcanization lines serving domestic automotive clients expand output. Three-tier pricing structure across BIS-certified premium, REACH-compliant standard, and uncertified economy levels separates qualified suppliers from commodity processors. Pricing pressure stems from buyer concentration among Asian tire manufacturers elongating payment terms. Road construction contractors show highest price sensitivity due to federal infrastructure program budget constraints, while automotive sealing component manufacturers absorb premium tiers for REACH compliance.
Supply Chain Analysis
BIS certification and REACH compliance gate supply chain access for export-oriented producers seeking placement in premium tire supply chains. Feedstock security concentrates in India, China, and Thailand where tire-derived scrap generation clusters around manufacturing centers. Raw material dependencies include vulcanized scrap rubber, devulcanization chemicals, and processing oils. Single-source vulnerability runs through controlled collection networks in US states with strict scrap tire management programs. Distribution runs through direct mill relationships displacing distributor networks among volume compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in precision molding applications where powdered rubber with consistent particle size distribution captures expanding premium pools. Devulcanization technology licensing costs and feedstock security tensions favor scaled operators with backward integration into tire collection networks.
For Market Incumbents: Extend certification infrastructure investments to lock in multi-year supply agreements with European automotive tier-one suppliers facing REACH compliance timelines. Deepen backward integration into controlled collection networks in US states with tightening EPA landfill diversion enforcement. Continuous reactor technology licensing creates defensive moats against batch processor competition in precision molding segments. For New Entrants and Emerging Players: Compounders serving acoustic barrier specifications in European construction markets represent an underserved buyer archetype with lower certification barriers and stable bulk fill demand. Target granulated rubber production for industrial matting applications where performance specifications remain moderate. Partner with regional tire collection cooperatives to secure feedstock without capital-intensive pyrolysis infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Indian reclaim specialists with BIS certification because fragmented domestic tire supply chains favor consolidated procurement relationships. Five-to-ten year viability hinges on devulcanization chemistry expertise scarcity in emerging producer markets. Watch for inflection in EU REACH enforcement intensity as signal for accelerated certified supplier qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Collection | Controlled feedstock networks in California and Texas secure supply against EPA diversion mandates. |
| Continuous Devulcanization Reactor Deployment | European tire manufacturers adopt these systems to meet REACH compliance timelines for virgin rubber substitution. |
| BIS Certification Investment | Indian quality standards unlock premium placement in Maruti Suzuki and Tata Motors supply chains. |
| Precision Molding Grade Powdered Rubber Expansion | Automotive sealing component manufacturers in Europe absorb volumes as REACH tightens substitution economics. |
| Subscription-Based Technical Support Launch | Process optimization services reposition supplier relationships from commodity transactions toward performance partnerships. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with tire manufacturer procurement leads, reclaim processor plant managers, automotive compounder technical directors, and devulcanization technology licensors combined with secondary validation against BIS certification registries, EPA landfill diversion reports, EU REACH substance restrictions, and customs trade data. Triangulation across stakeholder inputs and documentary sources calibrated segment-level volume estimates.
Historical trendline analysis of crumb rubber absorption in federal and state infrastructure programs, powdered rubber penetration in precision molding applications, and granulated rubber deployment in acoustic barriers informed projection frameworks. Segmentation dimensions modeled include product type, end-use industry, form, and application across the analysis window. CAGRs derived from elasticity analysis of natural rubber price volatility against reclaim substitution economics and regulatory compliance timeline impacts.
Underlying measurement precision varies by segment; BIS-certified reclaim grades and REACH-compliant powdered rubber carry tighter precision than commodity crumb rubber for road construction. Forecasts reflect assumptions about EPA enforcement intensity, EU REACH timeline adherence, and natural rubber price cycle positioning. A model refresh is warranted upon material change in devulcanization technology licensing cost structures or feedstock security policy shifts in major tire-producing jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Process Oil Market
Rubber
Global Cast Elastomers Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Rubber Extruder Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Wear Liners Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Rubber Ropes Market
Rubber
Tire Reinforcement Materials Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
FKM Elastomers Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Polybutadiene Elastomers Market
Rubber
Global Chloroprene Rubber Market
Rubber
Global Rubber Additives Market