
 End Load Cartoning Machine Market | 2026-2036
End Load Cartoning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
End Load Cartoning Machine Market Analysis
Asset-light leasing and equipment-as-a-service financing is fragmenting competitive access in the end load cartoning machine sector, enabling mid-sized pharmaceutical and food processors to deploy advanced automation without capital-intensive purchases. Syntegon Technology leverages its integrated control systems portfolio to anchor premium positioning across European and North American installations. Mpac Langen competes through specialized engineering for high-speed pharmaceutical cartoning, while Omori Machinery Co., Ltd. extends its geographic footprint with compact, modular designs tailored to Asian contract packaging operations.
An end load cartoning machine erects cartons from flat blanks and loads products through the open end, typically achieving speeds from 50 to 600 cartons per minute depending on mechanical configuration and product stability requirements; these machines serve primary and secondary packaging functions across regulated consumer goods industries. Automated systems dominate volume deployment in pharmaceutical and food and beverages end user segments, where line integration and serialization compliance command margin premiums. Semi-automated and robotic variants represent the fastest-expanding technology categories, driven by batch-size flexibility demands and labor cost pressures in personal care and household products manufacturing.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates compel pharmaceutical cartoning investments with integrated vision verification and reject systems. ISO packaging machinery safety standards and CE marking obligations further shape machine design, testing protocols, and market access timelines for suppliers serving regulated industries. Stakeholders must monitor evolving hybrid technology architectures and regional compliance divergence to align R&D roadmaps with buyer procurement criteria.
Market Dynamics
Pharmaceutical serialization mandates are compressing replacement cycles for end load cartoning equipment, forcing manufacturers to retire mechanical legacy systems before full depreciation and accelerating capital redeployment toward integrated vision-verification architectures.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace mandates for prescription pharmaceuticals require cartoning lines with embedded serialization modules, driving replacement demand across US contract packaging facilities.
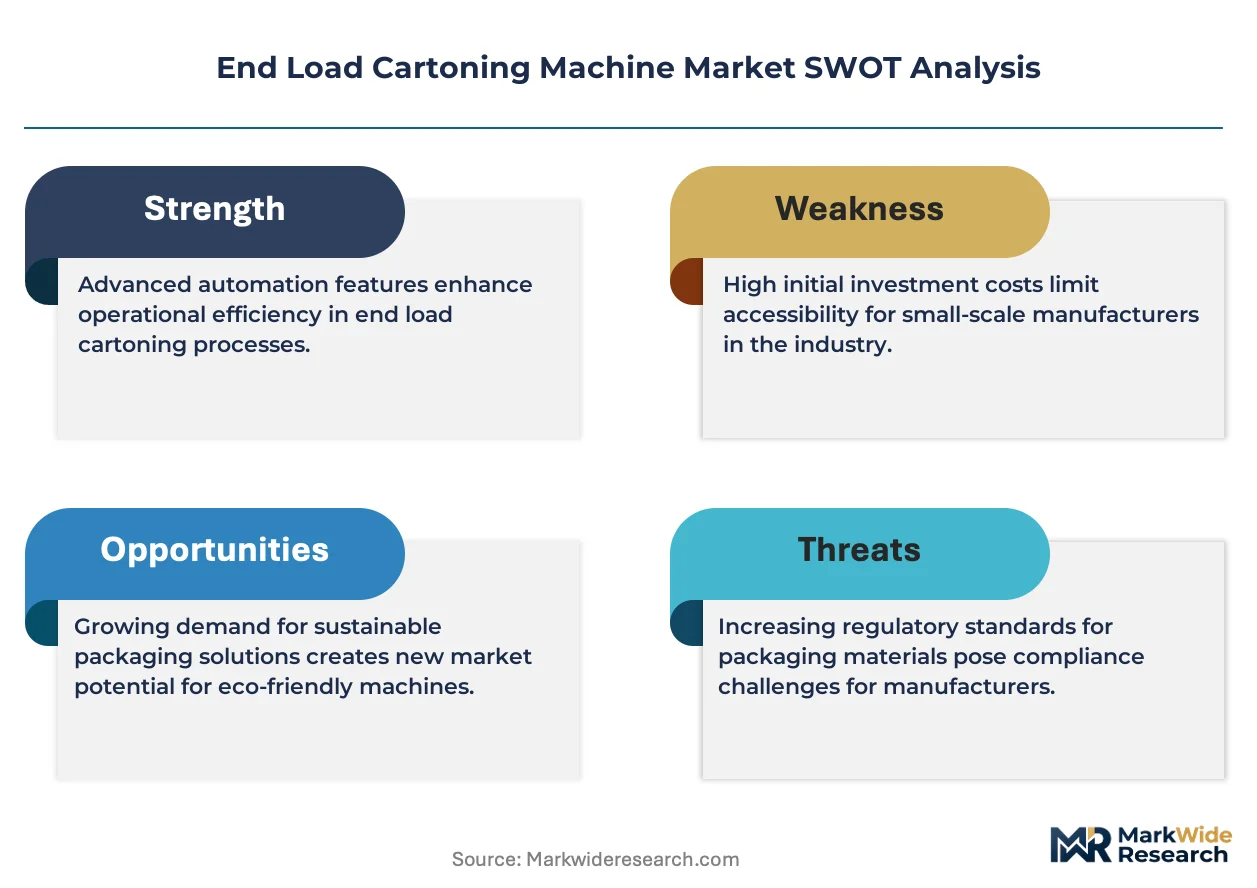
- Robotic loading integration:Collaborative robot arms handling unstable or fragile products expand addressable applications into personal care and nutraceutical segments previously excluded from high-speed automation.
- Contract packaging concentration:Third-party logistics providers in Germany and the Netherlands are consolidating pharmaceutical packaging services, creating pooled procurement leverage for multi-line automated cartoning installations.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for 316L pharmaceutical-grade steel and precision motion components compress OEM margins and destabilize project quoting cycles.
- European machine builder consolidation:Three specialized suppliers control premium pharmaceutical cartoning engineering capacity, creating bottleneck risk for validated system delivery timelines.
- Technical limitation in flexible format changeover:Mechanical cam-driven systems require 30-90 minute tooling swaps between carton sizes, constraining batch-size agility for multi-SKU manufacturers.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's phased serialization compliance timeline creates a 24-36 month equipment procurement window for domestic and multinational drug producers building capacity.
- Wet-wipe and single-serve food sachet cartoning:Hygiene and convenience formats in personal care and ready-to-eat segments represent greenfield automation demand outside traditional pharmaceutical concentration.
- CE marking and EU MDR convergence:Unified conformity assessment pathways reduce redundant testing costs for suppliers serving both medical device and pharmaceutical packaging buyers.
Industry Challenges
- Mechatronics technician scarcity:Servo tuning, vision system calibration, and robot programming skills are concentrated among aging European and Japanese specialist workforces, constraining field service expansion.
- IQ/OQ/PQ validation documentation burden:Pharmaceutical buyers require 12-18 month qualification protocols for new cartoning lines, extending revenue recognition cycles and working capital intensity for OEMs.
- Legacy SCADA integration complexity:Brownfield pharmaceutical facilities operate isolated control architectures from 1990s-2000s installations, complicating line-level data aggregation for Industry 4.0 upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Load Cartoning Machine Market |
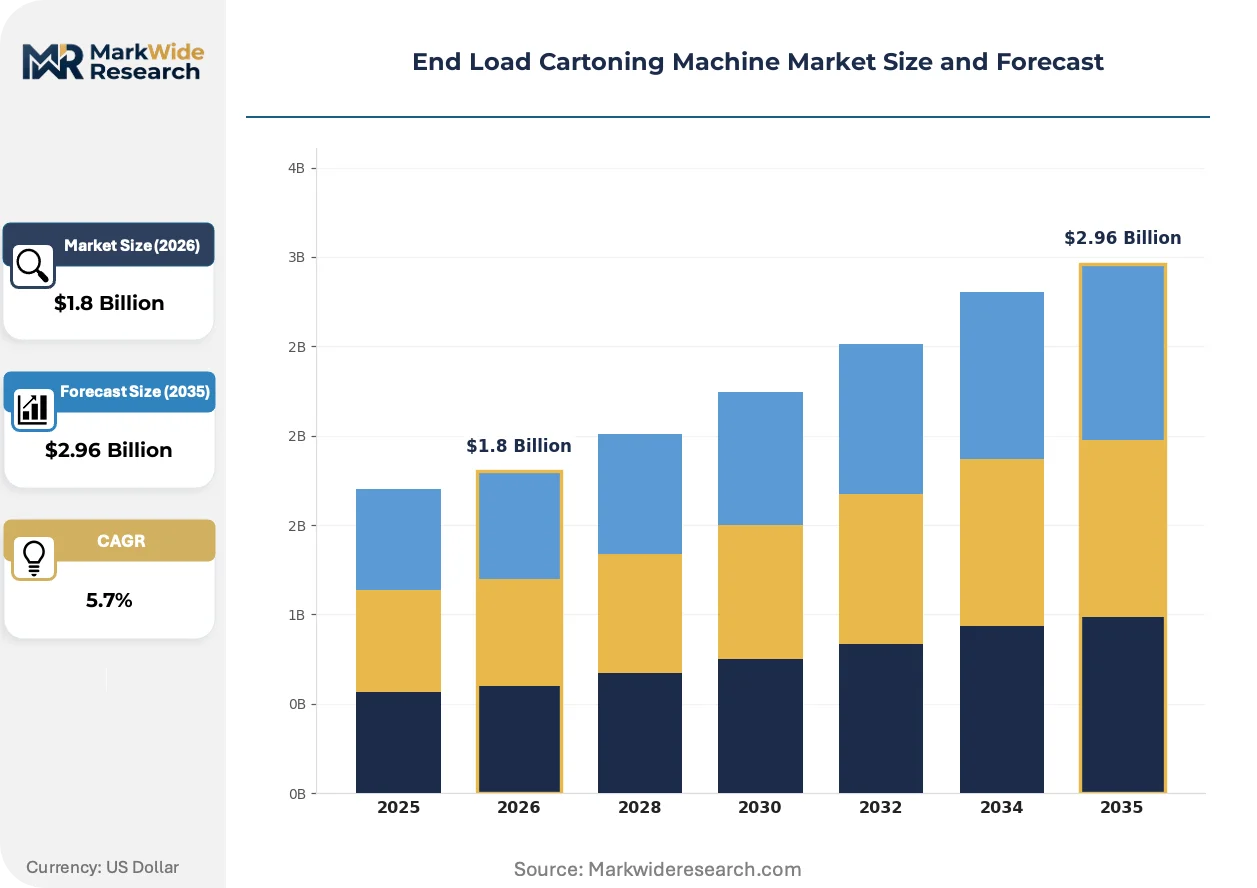
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Semi-Automated, Manual, Robotic End User: Pharmaceuticals, Food & Beverages, Personal Care, Household Products Application: Packaging, Bulk Handling, Production Lines, Quality Control Technology: Mechanical, Pneumatic, Electrical, Hybrid |
| Companies Covered | Mpac Langen, Omori Machinery Co., Ltd., Syntegon Technology, Econocorp Inc., Robert Bosch GmbH, IMA Group, ROVEMA GmbH, Cama Group, Marchesini Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Load Cartoning Machine Market Emerging Trajectories
Equipment architecture is pivoting from standalone mechanical systems toward modular, data-integrated platforms that synchronize with upstream filling and downstream case packing through standardized communication protocols.
Continuous motion cartoning technology is migrating from intermittent mechanical designs to servo-driven rotary systems that eliminate dwell time and enable 400-600 cartons per minute in pharmaceutical applications. Large molecule biologics manufacturers with temperature-sensitive vial products are adopting these platforms to minimize in-line exposure. The shift is compressing competitive differentiation around pure speed metrics and elevating gentle handling and traceability as purchasing criteria.
EU MDR traceability requirements are mandating unique device identification on medical device secondary packaging, compelling cartoning OEMs to pre-integrate thermal inkjet and laser marking modules with vision rejection systems. Machine builders must now validate entire print-verify-reject sequences as single qualified units rather than separate components. This regulatory bundling favors integrated control system suppliers over point-solution specialists in European medical device packaging procurement.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized North American pharmaceutical and nutraceutical processors. Monthly per-carton pricing with bundled maintenance and software updates reduces balance sheet impact and transfers obsolescence risk to OEMs. This financing innovation is most visible among private equity-backed contract packagers prioritizing EBITDA preservation over asset ownership.
End Load Cartoning Machine Market Segmentation
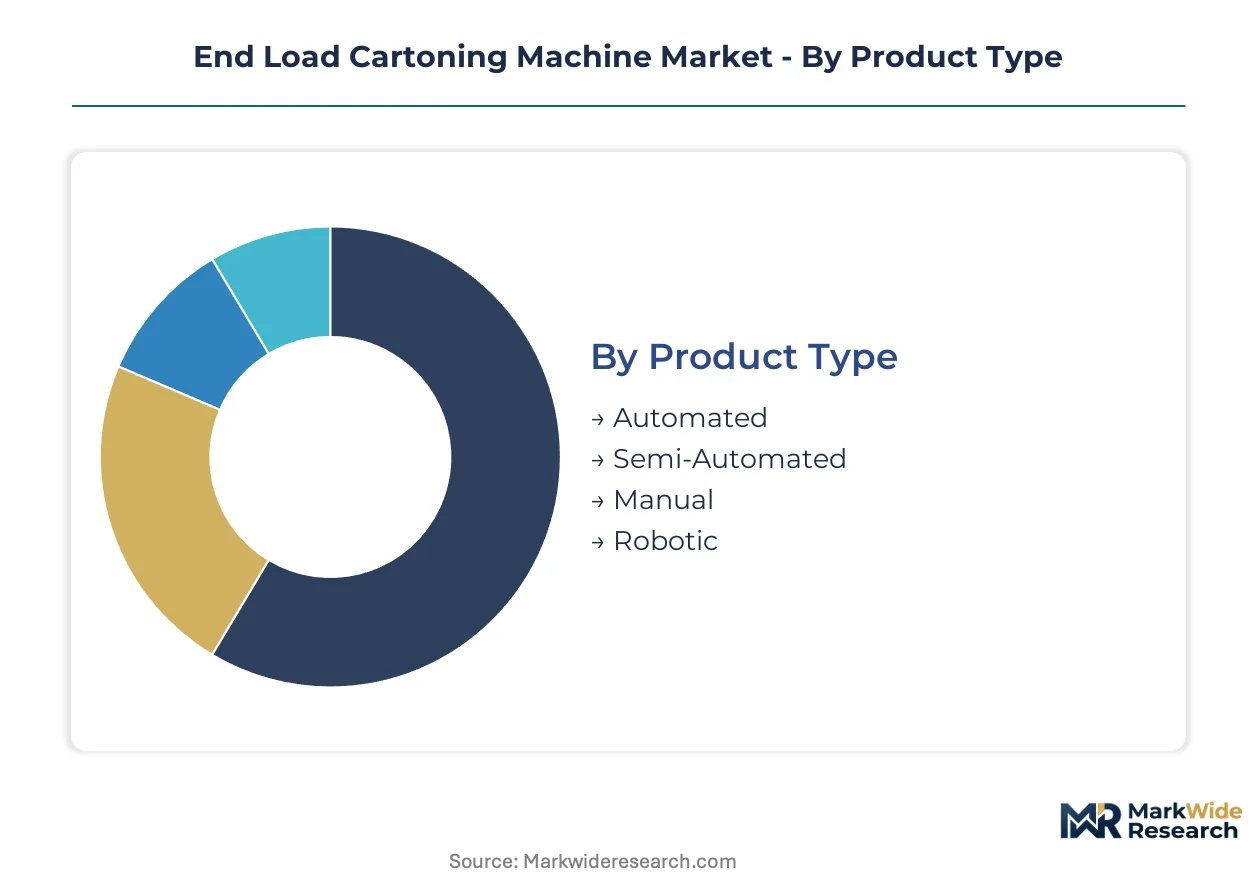
End load cartoning machine procurement varies sharply by operational scale and regulatory exposure. Pharmaceutical manufacturers prioritize validated automated systems with integrated serialization, while contract packagers in food and personal care balance throughput against batch flexibility demands.
Product Type:
Mature electromechanical platforms coexist with emerging robotic architectures as buyers weigh speed against format agility.
- Automated:Continuous motion servo systems achieve 400-600 cartons per minute with integrated vision verification and reject mechanisms. Demand concentrates in German and US pharmaceutical facilities facing FDA Drug Supply Chain Security Act and EU MDR serialization deadlines.
- Semi-Automated:Intermittent motion designs with manual loading stations serve mid-volume nutraceutical and personal care operations requiring 50-150 cartons per minute with frequent changeovers. Italian and Spanish contract packagers favor these for mixed-SKU production.
- Manual:Hand-fed carton erectors with pneumatic assist occupy artisan food and specialty cosmetic niches where labor costs remain below automation thresholds.
- Robotic:Collaborative arm configurations handle unstable vials, ampoules, and single-serve pouches previously excluded from high-speed lines. Japanese and South Korean biologics manufacturers drive adoption for gentle handling of temperature-sensitive products.
Automated systems handle the majority of throughput; robotic configurations are expanding most quickly on share.
End User:
Regulatory intensity separates premium equipment demand across customer verticals.
- Pharmaceuticals:Sterile vial, blister pack, and auto-injector cartoning requires 316L stainless steel construction, isolator integration, and IQ/OQ/PQ validation documentation. FDA and EMA serialization mandates compress replacement cycles to 7-10 years.
- Food & Beverages:Frozen meal, confectionery, and ready-to-eat cereal applications prioritize stainless steel washdown compatibility and quick-release tooling for allergen control. Dutch and Belgian dairy processors lead refresh investment.
- Personal Care:Wet-wipe canisters, cosmetic kits, and fragrance boxes demand gentle handling of irregular shapes. Brazilian and Mexican manufacturers balance automation against volatile local labor costs.
- Household Products:Detergent pods, cleaning wipes, and air freshener multipacks tolerate lower specification machinery with carbon steel frames and standard drives.
Pharmaceuticals commands the steepest pricing tier; food and beverages generates the largest installed base.
Application:
Functional deployment spans primary packaging through line integration layers.
- Packaging:Secondary carton formation, product insertion, and end-closure sealing constitute core machine function across all verticals.
- Bulk Handling:Accumulation buffers and lane dividers synchronize upstream filling variance with downstream case packing.
- Production Lines:Full line integration with upstream blister machines and downstream palletizers requires OPC-UA communication and centralized SCADA visibility.
- Quality Control:In-line checkweighing, vision inspection for leaflet presence, and serialization code verification add 15-25% to base machine cost.
Packaging absorbs the dominant capital share; quality control attachments climb fastest as regulatory bundling intensifies.
Technology:
Drive architecture determines precision, energy consumption, and maintenance burden.
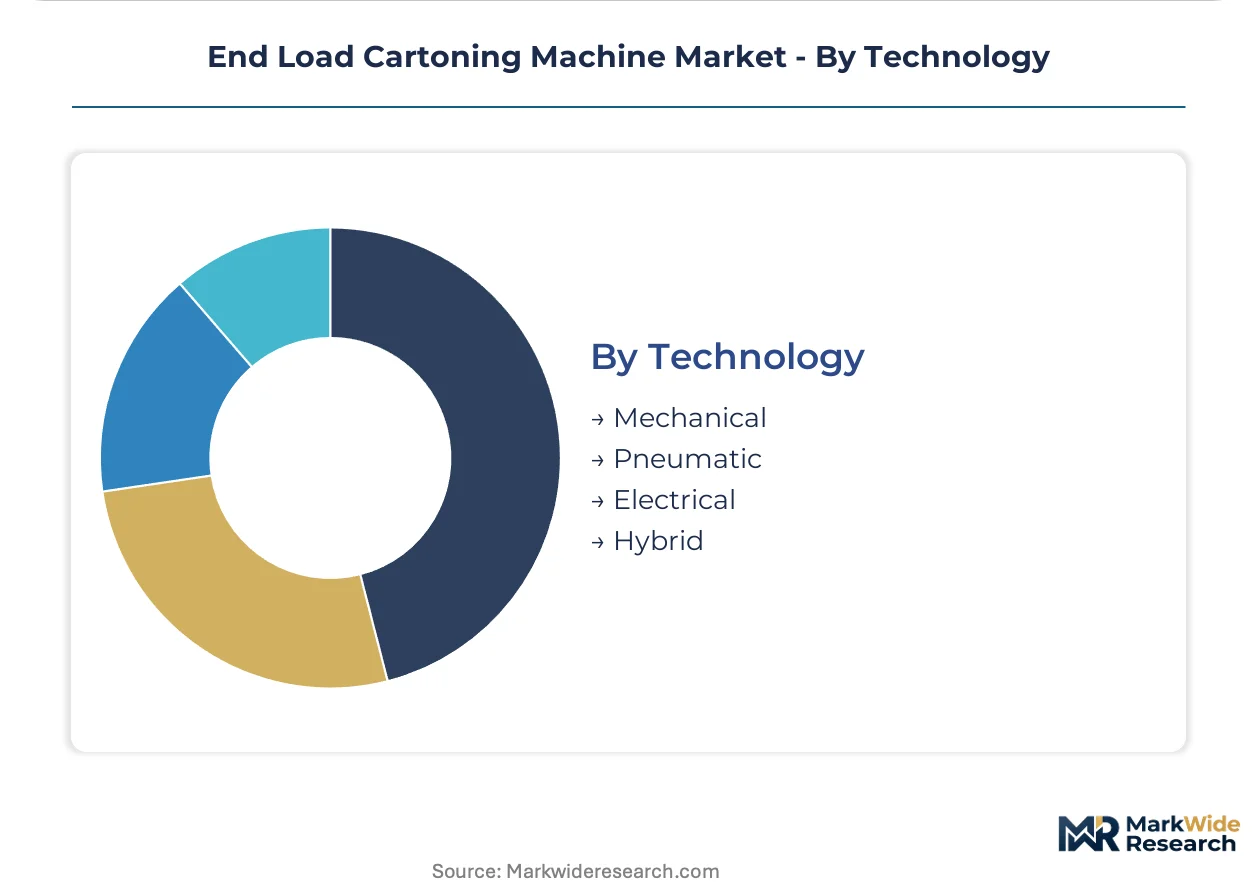
- Mechanical:Cam-driven intermittent motion systems with fixed kinematic profiles dominate legacy pharmaceutical installations. Long changeover times constrain multi-SKU flexibility.
- Pneumatic:Compressed air actuation for carton erection and product pusher mechanisms serves cost-sensitive food and household product lines. Energy efficiency disadvantages limit new adoption.
- Electrical:All-electric servo architectures with independent axis control enable recipe-driven format changeovers in under 10 minutes. German and Swiss OEMs anchor premium positioning.
- Hybrid:Combined servo-mechanical designs balance capital cost against motion precision for mid-tier pharmaceutical and nutraceutical processors.
Electrical platforms capture the bulk of new capacity investment; hybrid systems gain traction in emerging market upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented machinery builders in Germany and Switzerland supply validated cartoning systems to pharmaceutical manufacturers across North America and Asia, while import-dependent markets in India and Southeast Asia absorb second-hand European equipment alongside new Chinese and Japanese compact systems.
Germany
Domestic pharmaceutical serialization mandates under EU MDR compress equipment replacement cycles to seven years. CE marking convergence with medical device regulations reduces redundant testing costs for Baden-Württemberg machine builders. The Rhine-Main cluster around Frankfurt anchors high-speed continuous motion system development for sterile vial applications.
United States
FDA Drug Supply Chain Security Act deadlines drive contract packaging facilities toward integrated vision-verification architectures. Track-and-trace compliance requirements eliminate mechanical legacy systems before full depreciation. New Jersey and Pennsylvania pharmaceutical corridors concentrate multi-line automated cartoning procurement from European OEMs.
India
CDSCO phased serialization timelines create a procurement window for domestic drug producers building automated capacity. PLI scheme incentives for pharmaceutical manufacturing attract multinational packaging line investments. The Ahmedabad-Vadodara belt in Gujarat sees concentrated demand for semi-automated systems balancing throughput against batch flexibility.
Japan
PMDA biologics regulations elevate gentle handling requirements for temperature-sensitive large molecule products. METI industrial automation subsidies accelerate collaborative robot integration in cartoning lines. The Kansai region around Osaka hosts specialized engineering for compact modular designs serving Asian contract packaging operations.
China
NMPA pharmaceutical serialization mandates align with international traceability standards for export-oriented drug manufacturers. GB standards for packaging machinery safety shape domestic OEM design protocols. The Yangtze River Delta around Shanghai concentrates wet-wipe and single-serve food sachet cartoning demand from personal care processors.
End Load Cartoning Machine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying servo drives, vision modules, and robotic arms. The vendor base fragments across three capability layers: European premium engineering houses, Japanese precision automation firms, and emerging Chinese compact system builders. Strategic archetypes include integrated control system suppliers, pharmaceutical-validated specialists, and modular contract packaging enablers. Capacity expansion and technology licensing dominate competitive moves as OEMs transfer servo architecture IP to Asian manufacturing partners.
Among European engineering houses, Syntegon Technology and Mpac Langen exemplify divergent positioning archetypes. Syntegon anchors premium integrated control system deployment across German and North American pharmaceutical installations. Mpac Langen occupies the high-speed pharmaceutical specialization tier with validated engineering for sterile applications. Omori Machinery Co., Ltd. represents the Japanese precision automation model, extending geographic reach through compact modular architectures tailored to Asian contract packaging density requirements.
| Leading Market Players |
|---|
| Mpac Langen |
| Omori Machinery Co., Ltd. |
| Syntegon Technology |
| Econocorp Inc. |
| Robert Bosch GmbH |
| IMA Group |
| ROVEMA GmbH |
| Cama Group |
| Marchesini Group |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp freight corridor's container cost volatility shapes margin distribution across European machine builders while compressing pricing power for mid-tier servo motor suppliers serving pharmaceutical OEMs in Germany and the United States.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA-validated continuous motion systems commanding substantial premiums over semi-automated alternatives. Price differentiation hinges on CE marking tier and bundled IQ/OQ/PQ validation documentation depth. Cost compression in economy-tier pneumatic systems is intensifying because Chinese compact system builders are flooding Asian contract packaging markets. Contract packagers in India and Southeast Asia exhibit the highest price sensitivity, while German sterile pharmaceutical manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Export control restrictions on precision servo drives and motion control software limit technology transfer to Chinese manufacturing partners, constraining capacity expansion for mid-tier hybrid system builders. Component manufacturing concentrates in Germany, Japan, and Switzerland, with 316L pharmaceutical-grade stainless steel and precision ball screw assemblies feeding from specialized European and Japanese metalworkers. Single-source vulnerability around German-built validated control architectures threatens delivery timelines for multi-line pharmaceutical installations. Distribution runs through OEM-direct sales for large pharmaceutical accounts and specialized packaging machinery distributors serving regional contract packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting and predictive maintenance subscriptions are expanding faster than hardware shipments, transforming capital equipment vendors into recurring-revenue platforms anchored by uptime guarantees and software update streams.
For Market Incumbents: Insulate validated system margins by deepening captive supply of vision verification modules and serialization software stacks against emerging modular competitors from Japan and South Korea. Accelerate certification investment for EU MDR-aligned medical device packaging to preempt regulatory bundling advantages. Control channel access through exclusive service partnerships with major German and US pharmaceutical contract packagers. For New Entrants and Emerging Players: India's pharmaceutical manufacturing belt around Ahmedabad and Vadodara offers concentrated procurement demand with limited local validated engineering capacity, creating white-space for semi-automated system builders offering rapid commissioning timelines. Wet-wipe and single-serve food sachet applications in China's Yangtze River Delta present format-flexibility gaps underserved by incumbent pharmaceutical-specialized architectures. Pursue equipment-leasing partnerships with private equity-backed contract packagers prioritizing EBITDA preservation over asset ownership. For Investors and Strategic Acquirers: Vision system integrators with FDA-validated print-verify-reject sequences represent the most defensible acquisition targets as regulatory bundling elevates integrated control platforms over point-solution specialists. Long-term viability rests on software attach rates and service contract renewal velocity rather than hardware shipment cyclicality. Watch for CDSCO serialization enforcement acceleration in India as the inflection signal for emerging market capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | Captive supply of precision motion components insulates German OEMs against 316L steel cost volatility and Japanese component lead time extension. |
| Equipment-as-a-Service Platform Launch | Per-carton pricing with bundled maintenance transfers obsolescence risk and locks in recurring revenue from North American mid-tier pharmaceutical processors. |
| Vision System Validation Partnership | FDA-aligned print-verify-reject qualification as single units accelerates procurement decisions from serialization-mandated pharmaceutical buyers. |
| Modular Compact System Expansion | Format-flexible architectures tailored to Asian wet-wipe and food sachet contract packagers capture greenfield automation demand outside traditional pharmaceutical concentration. |
| Regional Service Hub Establishment | Local IQ/OQ/PQ documentation and field engineering presence in India compresses pharmaceutical buyer qualification timelines and working capital intensity. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA 483 observations, EMA manufacturing authorization records, SEC 10-K filings from disclosed packaging machinery suppliers, and customs trade data for pharmaceutical-grade steel and servo motor imports. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure surveys were triangulated to constrain volume estimates.
Scenario-bracketing around regulatory enforcement intensity and contract packaging consolidation pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, end-use vertical, drive architecture technology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle compression analysis and greenfield capacity addition tracking, with specific inputs from serialization mandate deadline phasing and METI industrial automation subsidy uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese compact system builders or accelerated EU MDR enforcement would shift outcomes beyond modeled ranges. Material shifts in FDA Drug Supply Chain Security Act deadline extensions or CDSCO serialization timeline revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Sealer Market
Cartons
Folding Cartons Market
Cartons
Mono Carton Market
Cartons
Mailers Market
Cartons
Carton Sealer Machine Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Folding Carton in Healthcare Market
Cartons
Europe Corrugated Box Market
Cartons
Round Corrugated Box Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Global Cartonboard Market
Cartons
Beverage Cartoners Market
Cartons
Tablet Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
Beverage Cartons Market