
 Global Leukapheresis Market | 2026-2036
Global Leukapheresis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Leukapheresis Market Foresight
The EU MDR is rebalancing procurement criteria toward traceable, single-use collection systems. Haemonetics Corporation dominates North American blood center automation with installed-base scale. Fresenius SE & Co. KGaA anchors European therapeutic apheresis through its hospital dialysis footprint. Miltenyi Biotec differentiates via magnetic cell separation integration downstream of leukapheresis collection.
Leukapheresis denotes the selective extracorporeal removal of white blood cells from whole blood, typically processing four to six blood volumes over two to four hours while returning erythrocytes, platelets, and plasma to the patient. The procedure serves as the critical first step in hematopoietic stem cell transplantation and autologous CAR-T manufacturing, where mononuclear cell yield and viability directly determine downstream therapeutic potency. Automated leukapheresis devices command the majority of installed value due to operator standardization and protocol reproducibility demands. Centrifugation technology leads procedure volume, though membrane separation is gaining share in research laboratories seeking gentler cell handling for immunotherapy preparation. End users at academic hospitals and transplant centers concentrate purchasing power, while blood banks face margin compression from commoditized disposable kit contracts.
The FDA enforces current Good Tissue Practice for cellular therapy starting materials, while the EMA's ATMP framework extends quality requirements to collection site qualification across member states. Japan's PMDA aligns with PIC/S standards for apheresis-derived cell products, creating a harmonized but stringent regulatory baseline. Stakeholders must monitor how evolving GMP annexes for starting materials reshape capital deployment between collection technology and site certification.
Market Dynamics
CAR-T therapy commercialization is concentrating leukapheresis demand at a small number of qualified collection sites, creating capacity bottlenecks that favor vendors with installed-base scale and regulatory documentation depth.
Growth Catalysts
- FDA current Good Tissue Practice:The enforcement of cGTP standards for cellular therapy starting materials mandates qualified collection sites, driving replacement of manual protocols with automated leukapheresis systems that generate compliant documentation trails.
- Academic medical centers:Transplant programs at major teaching hospitals are expanding apheresis unit throughput to serve both autologous stem cell and CAR-T patient pipelines, concentrating purchasing power among high-volume operators.
- Magnetic cell separation integration:Downstream immunotherapy manufacturing workflows now demand leukapheresis outputs compatible with closed-system magnetic selection, favoring collection technologies that preserve mononuclear cell viability for subsequent Miltenyi CliniMACS processing.
Market Restraints
- Single-use disposable costs:Centrifugation-based leukapheresis requires proprietary tubing sets and separation chambers that lock blood centers into long-term consumable contracts with limited third-party alternatives.
- Site qualification concentration:The EU MDR's tightened quality standards for ATMP starting materials restrict viable collection locations to a narrow pool of certified hospital apheresis units, particularly in Germany and France.
- Membrane separation throughput limits:Research-scale membrane filtration systems offer gentler cell handling but process blood volumes too slowly for clinical-scale CAR-T manufacturing, constraining their addressable market.
Strategic Opportunities
- Japan's PMDA alignment with PIC/S:Harmonized standards for apheresis-derived cell products create a regulatory pathway for Western equipment vendors to enter a market with aging transplant infrastructure and rising cell therapy investment.
- Point-of-care collection models:Mobile apheresis units deployed to satellite clinics could reduce patient travel burden for dispersed rural populations in Australia and Canada, opening new service revenue streams.
- Closed-system automation convergence:Integration of leukapheresis collection with downstream cell washing and cryopreservation in a single disposable set addresses contamination risks that currently require separate cleanroom processing.
Industry Challenges
- Apheresis nurse specialization:The two-to-four-hour procedure demands operators trained in extracorporeal circuit management and patient monitoring, with staffing shortages limiting expansion at qualified collection sites.
- EU MDR technical documentation:Manufacturers must retrospectively compile clinical evidence and risk management files for legacy devices, compressing timelines for product line refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Leukapheresis Market |
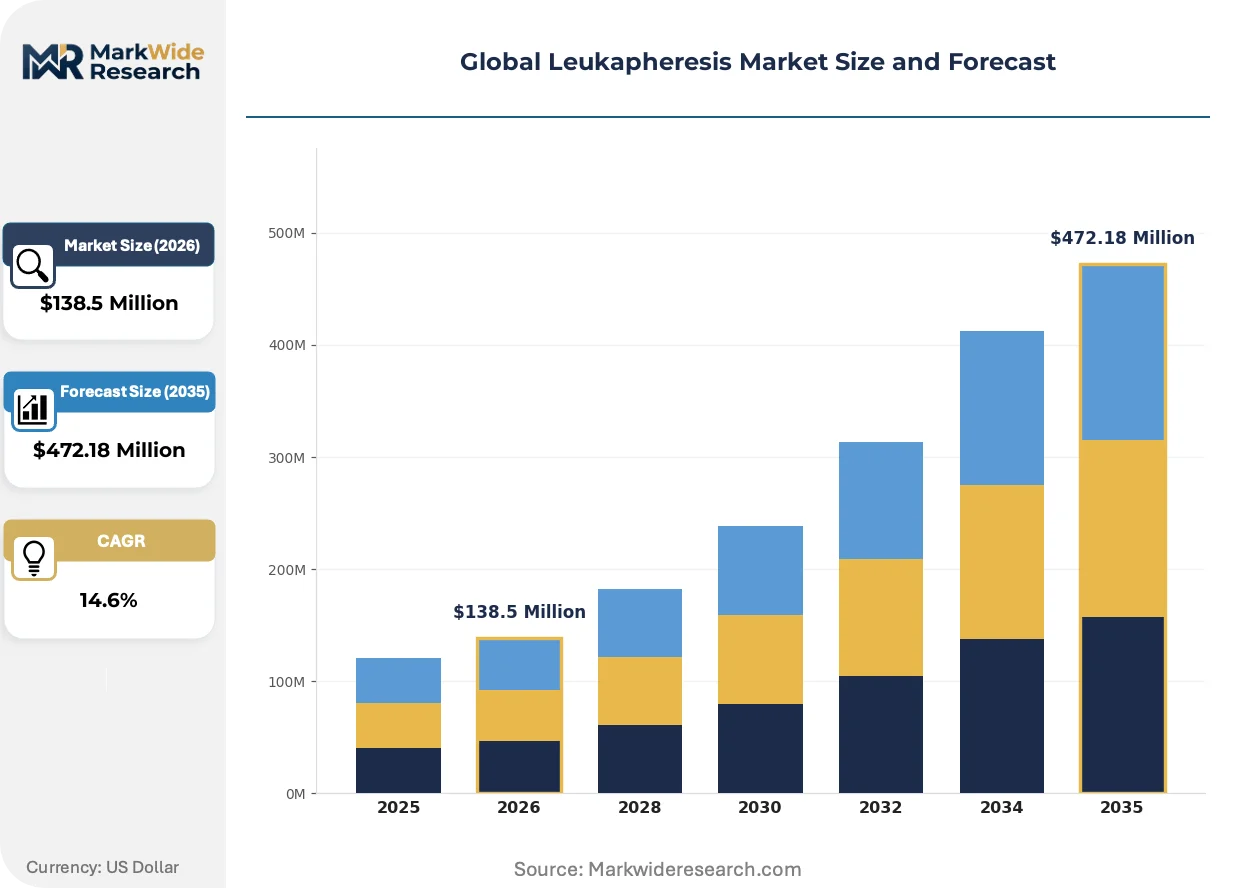
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $472.18 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Leukapheresis Devices, Manual Leukapheresis Kits, Disposable Kits, Reusable Components, Apheresis Machines Application: Hematopoietic Stem Cell Collection, Peripheral Blood Stem Cell Mobilization, Therapeutic Apheresis, Immunotherapy Preparation, Cell Separation End User: Research Laboratories, Blood Banks, Specialized Clinics, Academic Hospitals, Transplant Centers Technology: Centrifugation, Filtration, Membrane Separation, Continuous Flow, Adsorption Techniques |
| Companies Covered | Asahi Kasei Medical Co. Ltd, Haemonetics Corporation, Terumo BCT Inc., Fresenius SE & Co. KGaA, Macopharma, Lonza, Miltenyi Biotec, STEMCELL Technologies Inc., AllCells, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Leukapheresis Market Shifts & Advancements
Leukapheresis technology trajectories center on three vectors: procedural automation reducing operator variability, regulatory documentation embedded in device software, and service models that unbundle capital acquisition from per-procedure economics.
Closed-system centrifugation platforms with integrated cell counting and viability assessment are rewriting the standard for CAR-T starting material collection. Academic transplant centers in the United States and Germany are replacing first-generation open systems at replacement cycles compressed to five-to-seven years. The technology is compressing the gap between collection and manufacturing handoff, reducing cold-chain logistics complexity for time-sensitive autologous therapies.
The EU MDR's Annex I general safety and performance requirements now extend to apheresis devices used in ATMP production, mandating software validation and post-market surveillance systems that many legacy platforms lack. Device manufacturers face industrial consequence in the form of portfolio rationalization, with smaller product lines discontinued rather than remediated. German and French hospital buyers are responding by consolidating procurement around vendors with established notified body relationships and MDR transition experience.
Service contracts that unbundle device placement from per-procedure disposable commitments are displacing traditional capital purchase models among European blood centers facing budget constraints. The segment being disrupted includes mid-sized hospital apheresis units that lack balance sheet capacity for six-figure equipment investments. This shift is most visible in the United Kingdom and the Netherlands, where NHS procurement frameworks and hospital group purchasing organizations favor operational expenditure structures over capital allocation.
Global Leukapheresis Market Segmentation
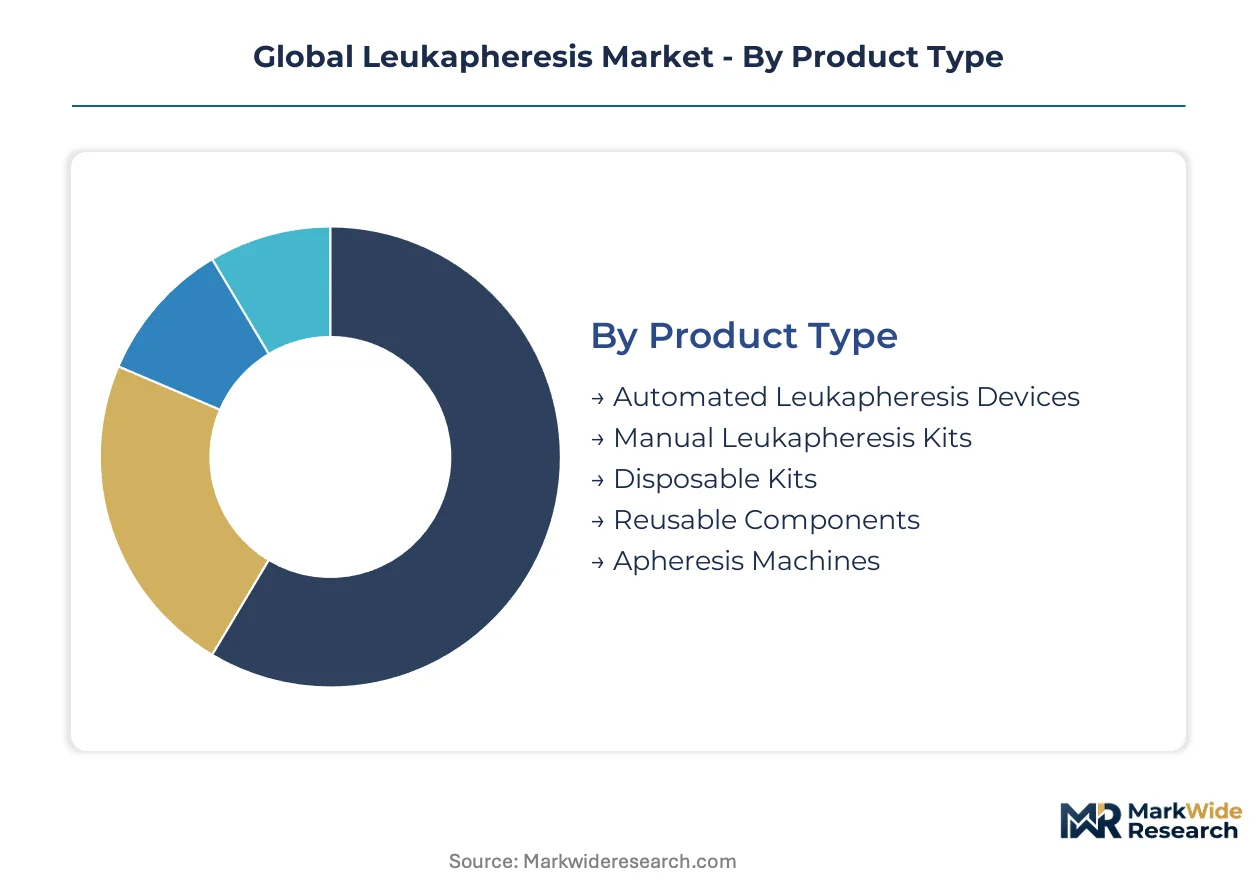
Leukapheresis market segmentation reflects divergent buyer priorities across capital-intensive transplant centers, cost-conscious blood banks, and research laboratories. Procurement criteria vary sharply by end-use: GMP documentation dominates cell therapy manufacturing, while throughput-per-hour drives blood center economics.
Product Type:
Capital deployment constraints and regulatory documentation requirements drive purchasing decisions across product categories.
- Automated Leukapheresis Devices:Closed-system centrifugation platforms integrate cell counting, viability assessment, and automated documentation trails for cGTP compliance. Demand concentrates at academic hospitals in the United States and Germany where CAR-T manufacturing partnerships require qualified starting material collection with audit-ready data packages.
- Disposable Kits:Single-use tubing sets and separation chambers lock blood centers into long-term consumable contracts with limited third-party alternatives. European blood banks face margin compression from proprietary disposable pricing, accelerating interest in service contracts that unbundle capital from per-procedure economics.
- Manual Leukapheresis Kits:Open-system configurations retain niche use in resource-limited settings lacking trained apheresis nursing staff.
- Reusable Components:Separation chambers and circuit elements designed for sterilization and redeployment appeal to budget-constrained hospital apheresis units.
- Apheresis Machines:Integrated hardware platforms span collection, processing, and data management functions for high-volume operators.
Volume sits with disposable kits; growth tilts toward automated devices.
Application:
Clinical indication determines cell yield specifications, processing duration, and downstream manufacturing compatibility requirements.
- Hematopoietic Stem Cell Collection:Standard-of-care procedure for autologous and allogeneic transplantation processes four to six blood volumes over two to four hours. Transplant centers in Japan concentrate demand as PMDA-aligned PIC/S standards expand qualified collection site networks.
- Immunotherapy Preparation:CAR-T starting material collection demands mononuclear cell viability preservation for subsequent magnetic selection workflows. Academic medical centers in Germany and France face EU MDR-driven site qualification bottlenecks that restrict viable collection locations.
- Peripheral Blood Stem Cell Mobilization:Pre-collection pharmacological stimulation protocols require coordination between oncology and apheresis units.
- Therapeutic Apheresis:Removal of pathogenic leukocyte populations treats autoimmune and hematologic conditions outside transplantation.
- Cell Separation:Research-scale applications prioritize gentle handling over throughput speed.
Procedure volume clusters in stem cell collection; steepest expansion trajectory belongs to immunotherapy preparation.
End User:
Facility type determines regulatory exposure, capital access, and staffing specialization levels.
- Transplant Centers:Dedicated cellular therapy units maintain GMP-adjacent cleanroom infrastructure and specialized apheresis nursing teams. United States academic hospitals concentrate purchasing power through integrated stem cell and CAR-T patient pipelines.
- Research Laboratories:Membrane filtration and adsorption technique experimentation prioritizes cell viability over clinical-scale throughput. German and French university labs drive demand for gentler handling technologies ahead of manufacturing handoff.
- Academic Hospitals:Dual-purpose clinical and research missions require flexible equipment configurations.
- Blood Banks:High-volume, standardized protocols favor automation and consumable cost minimization.
- Specialized Clinics:Satellite apheresis units in Australia and Canada explore mobile collection models for dispersed rural populations.
Revenue concentrates at transplant centers; capability investment flows fastest toward research laboratories.
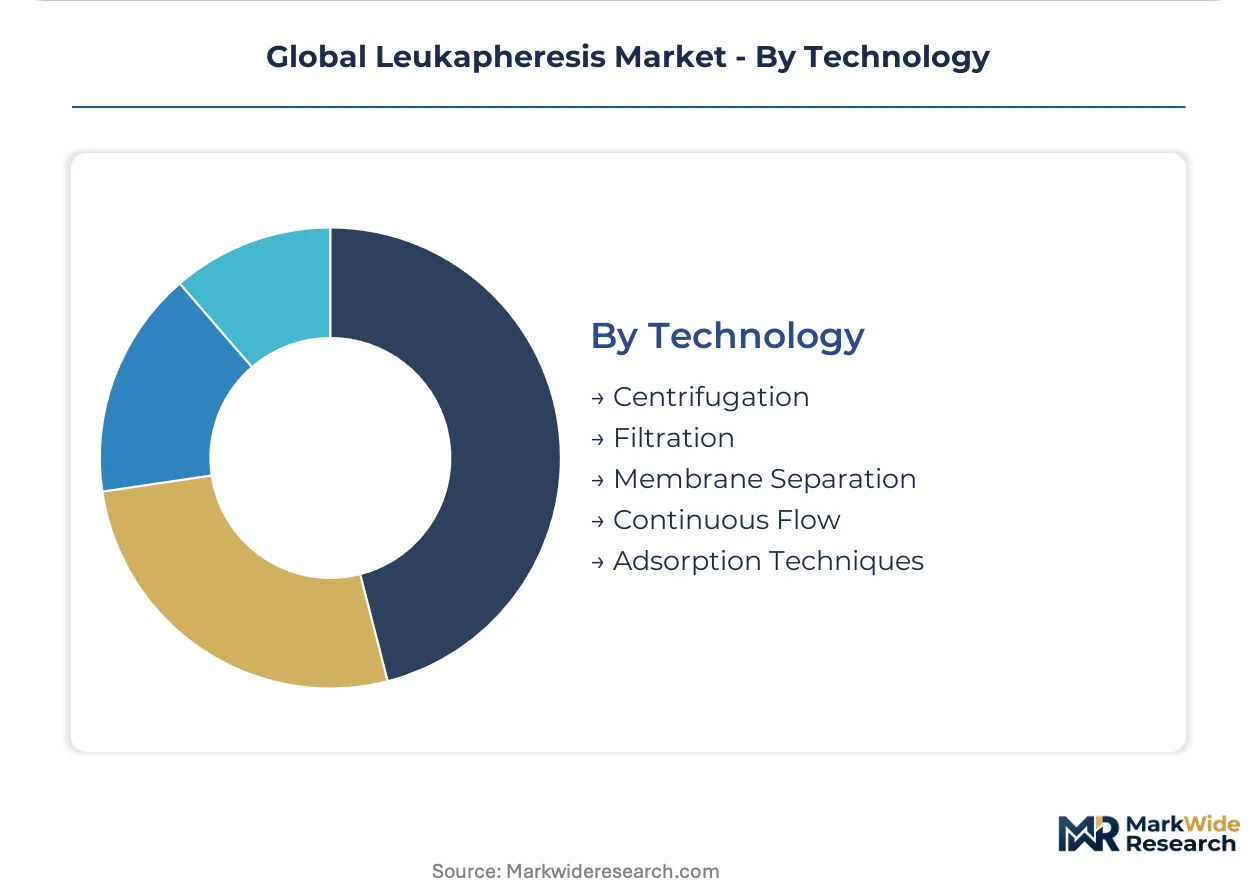
Technology:
Separation mechanism selection trades processing speed against cell integrity preservation.
- Centrifugation:Density-gradient separation commands clinical procedure volume through proven scalability and operator standardization. Blood center automation in North America relies on centrifugation platforms with installed-base scale and regulatory documentation depth.
- Membrane Separation:Filtration-based systems reduce shear stress on mononuclear cells but process volumes too slowly for clinical-scale CAR-T manufacturing. Research laboratories in Japan and Germany adopt membrane techniques for immunotherapy preparation where viability trumps speed.
- Filtration:Pore-size-based separation serves niche therapeutic apheresis applications.
- Continuous Flow:Uninterrupted blood processing maximizes cell yield per session duration.
- Adsorption Techniques:Selective leukocyte binding to functionalized surfaces enables targeted cell subset removal.
Procedure volume rests with centrifugation; technology investment shifts toward membrane separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors CAR-T manufacturing partnerships that concentrate leukapheresis demand at qualified collection sites. The FDA enforces cGTP standards that mandate automated documentation trails. Academic hospitals in this cluster replace first-generation open systems at compressed five-to-seven-year cycles.
United States
Transplant centers at academic medical centers in Boston, Seattle, and Houston expand apheresis unit throughput for autologous stem cell and CAR-T pipelines. The FDA's current Good Tissue Practice mandates qualified collection sites with audit-ready data packages. Manufacturing partnerships in the Research Triangle Park corridor reshape procurement toward closed-system automation.
Germany
Hospital apheresis units in Munich and Heidelberg face EU MDR-driven site qualification bottlenecks that restrict viable collection locations for ATMP starting materials. The EMA's ATMP framework extends quality requirements to collection site qualification across member states. The Rhine-Main cluster concentrates magnetic cell separation integration downstream of leukapheresis collection.
Japan
PMDA alignment with PIC/S standards expands qualified collection site networks for aging transplant infrastructure. Japan's pharmaceutical regulator harmonizes apheresis-derived cell product standards with international benchmarks. Tokyo and Osaka academic hospitals drive demand for automated systems that preserve mononuclear cell viability.
France
Paris and Lyon hospital buyers consolidate procurement around vendors with established notified body relationships and MDR transition experience. ANSM enforces post-market surveillance systems that many legacy platforms lack. The Île-de-France region concentrates service contracts that unbundle device placement from per-procedure disposable commitments.
United Kingdom
NHS procurement frameworks favor operational expenditure structures over capital allocation for mid-sized hospital apheresis units. The Medicines and Healthcare products Regulatory Agency enforces software validation requirements under EU MDR Annex I. London teaching hospitals replace equipment through service contracts rather than six-figure capital investments.
Global Leukapheresis Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with installed-base scale and regulatory documentation depth. Blood center automation and hospital dialysis footprints anchor market presence in North America and Europe respectively. Three archetypes dominate: centrifugation platform specialists, magnetic cell separation integrators, and blood component automation incumbents. Capacity expansion at qualified collection sites and M&A targeting regulatory documentation capabilities constitute the dominant competitive moves.
Among diversified technology conglomerates, Fresenius SE & Co. KGaA and Terumo BCT Inc. occupy positions shaped by hospital system integration and blood center automation heritage respectively. Haemonetics Corporation exemplifies the installed-base scale archetype in North American blood center markets. Miltenyi Biotec represents the magnetic cell separation integration vector that downstream immunotherapy manufacturing workflows now demand. Asahi Kasei Medical Co. Ltd anchors the membrane filtration technology position in research-scale applications where gentler cell handling trumps throughput speed.
| Leading Market Players |
|---|
| Asahi Kasei Medical Co. Ltd |
| Haemonetics Corporation |
| Terumo BCT Inc. |
| Fresenius SE & Co. KGaA |
| Macopharma |
| Lonza |
| Miltenyi Biotec |
| STEMCELL Technologies Inc. |
| AllCells |
| Others |
Supply & Pricing Matrix
Backward integration into single-use disposable manufacturing anchors pricing power for centrifugation platform vendors serving North American blood centers and German hospital apheresis units. The EU MDR's technical documentation requirements concentrate procurement around conglomerates with captive supply chains for proprietary tubing sets and separation chambers, compressing margins for third-party consumable suppliers.
Pricing Analysis
Value-based pricing tied to mononuclear cell yield and cGTP-compliant documentation anchors contract structures for automated leukapheresis devices. Price differentiation rests on FDA certification tier and installed-base service depth, with academic transplant centers in Boston and Seattle showing lowest price sensitivity due to CAR-T manufacturing partnerships. Cost compression in mid-sized hospital apheresis units is intensifying because NHS procurement frameworks favor operational expenditure models over capital purchases.
Supply Chain Analysis
Refurbishment flows for separation chambers and circuit elements concentrate in Germany and the United States, where sterilization-validated redeployment extends equipment lifecycle for budget-constrained operators. Raw material dependencies span medical-grade polymers, precision pumps, and cell separation membranes sourced from Japan and Switzerland. Single-source vulnerability in magnetic cell separation consumables feeds from Miltenyi Biotec's downstream integration. Distribution runs through hospital group purchasing organizations and blood center consortia with multi-year disposable commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Leukapheresis Market operates as a cost-of-compliance story where EU MDR site qualification requirements erect barrier-to-entry moats favoring vendors with established notified body relationships and MDR transition experience.
For Market Incumbents: Extend regulatory documentation depth through software validation investments that address EU MDR Annex I post-market surveillance mandates. Fortify installed-base lock-in by embedding cell counting and viability assessment modules that generate audit-ready data packages for FDA cGTP compliance. Capacity addition in Japan's PMDA-aligned PIC/S markets captures aging transplant infrastructure replacement cycles. For New Entrants and Emerging Players: The premium-to-economy price-point gap in membrane filtration research-scale systems offers white-space entry ahead of clinical-scale CAR-T manufacturing compatibility. Target Australian and Canadian satellite clinics exploring mobile collection models for dispersed rural populations. Pursue service contract structures that unbundle capital acquisition from per-procedure economics for NHS procurement frameworks. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified medical technology conglomerates seeking magnetic cell separation integration capabilities. Long-term viability favors targets with closed-system automation patents and established GMP-adjacent cleanroom infrastructure partnerships. Monitor FDA guidance revisions on regenerative medicine starting materials for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Remediation | Portfolio rationalization eliminates smaller product lines, consolidating procurement around vendors with notified body relationships. |
| Magnetic Cell Separation Integration | Downstream CliniMACS compatibility preserves mononuclear cell viability for immunotherapy manufacturing workflows. |
| Mobile Apheresis Unit Deployment | Satellite clinic reach reduces patient travel burden for dispersed rural populations in Australia and Canada. |
| Closed-System Automation Convergence | Single disposable set integration addresses contamination risks currently requiring separate cleanroom processing. |
| Service Contract Unbundling | Operational expenditure structures displace capital purchases for mid-sized hospital apheresis units under NHS frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with apheresis unit nursing directors, hospital GPO contracts managers, biomedical engineers, and cell therapy manufacturing executives combined with FDA 510(k) databases, EMA ATMP qualification registries, and hospital procurement databases. Bottom-up device shipment tracking and top-down healthcare expenditure triangulation validated market sizing across the analysis window.
Data-stream reconciliation across product type, application, end user, technology, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from installed-base replacement cycles, CAR-T pipeline expansion trajectories, and EU MDR transition timelines. Industry-specific forecast inputs incorporated PMDA-PIC/S harmonization progress and academic medical center capital allocation surveys.
Inputs from notified body technical documentation audits and blood center disposable procurement records were available through the study window; gaps in real-time CAR-T manufacturing yield correlation data introduce uncertainty bands around immunotherapy preparation segment projections. Practitioners should monitor FDA regenerative medicine guidance revisions and EU MDR implementation enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Transplantation Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Motion Sickness Treatment Market