
 Rotary Blade UAV Drones Market | 2026-2036
Rotary Blade UAV Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Blade UAV Drones Market Analysis
Modular payload bundling is hardening as the dominant procurement pattern for commercial rotary blade UAV operators. DJI sustains manufacturing scale across integrated camera-gimbal-telemetry packages that reduce field configuration time. AeroVironment specializes in military-grade modular architectures that swap sensors between ISR and electronic warfare missions. Skydio navigates autonomous flight module subscriptions that unbundle software capabilities from hardware purchases.
Rotary blade UAV drones are unmanned aerial vehicles that generate lift through one or more vertically oriented rotors, typically employing brushless DC motors with carbon-fiber reinforced polymer arms to achieve thrust-to-weight ratios exceeding two-to-one for stable hover and maneuverability in confined environments. These platforms serve commercial and defense end users requiring vertical takeoff and landing capability without runway dependency. Multirotor configurations dominate civil and commercial volume due to mechanical simplicity and payload flexibility, while single rotor systems retain structural margin pools in heavy-lift agriculture and defense logistics where endurance and fuel efficiency outweigh acquisition cost. Hybrid architectures that combine rotary lift with fixed-wing cruise are capturing fastest-growing status in infrastructure inspection applications requiring both loiter precision and transit range.
FAA Part 107 and Remote ID rules in the United States, EASA drone regulation frameworks across European member states, and China's CAAC low-altitude economy policies collectively shape airspace access, product certification timelines, and cross-border market entry requirements for manufacturers and operators. Compliance with these overlapping regulatory regimes now determines which technology tiers achieve commercial deployment at scale. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver frameworks and emerging detect-and-avoid mandates as the primary variables that will reorder competitive positioning in enterprise and defense procurement channels.
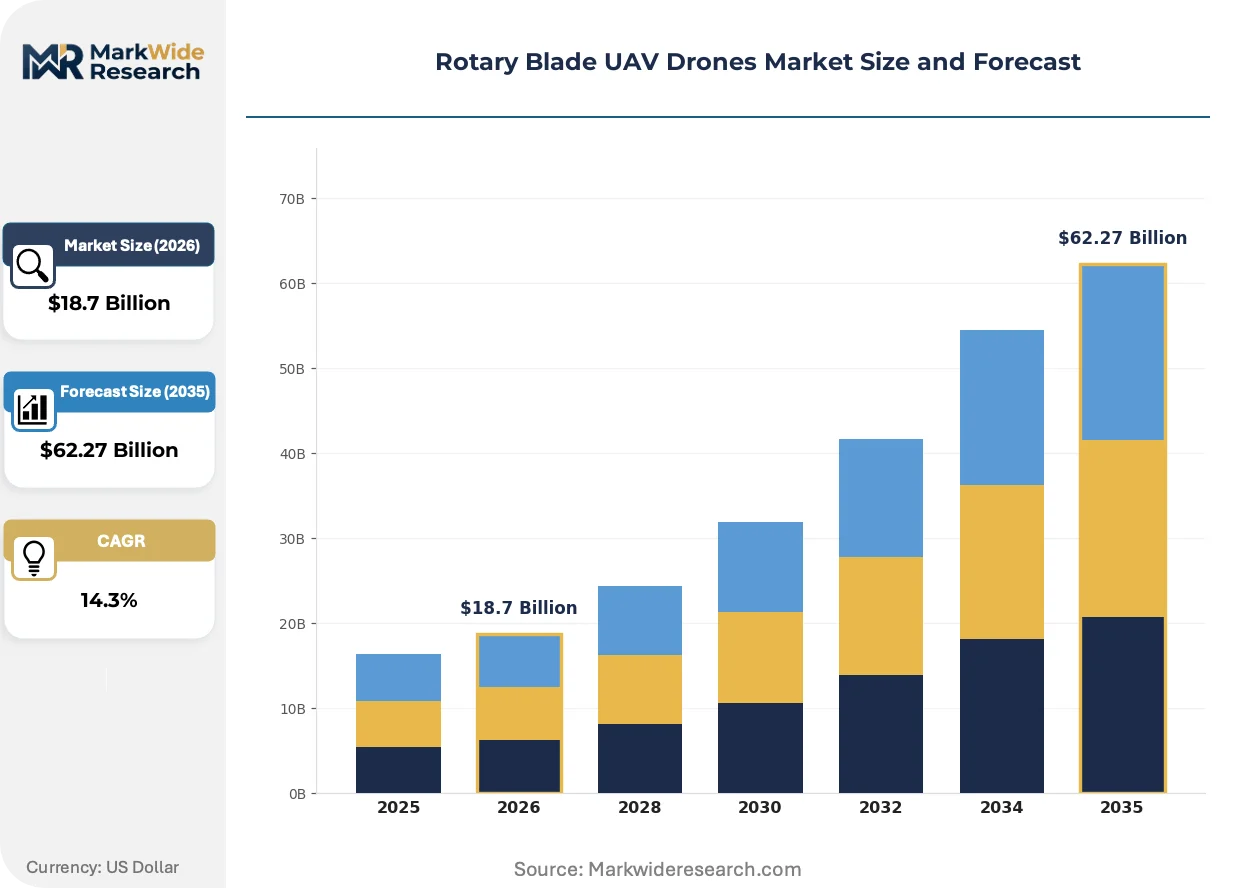
Market Dynamics
Modular payload architectures are compressing procurement cycles across defense and commercial rotary blade UAV operators, forcing manufacturers to unbundle hardware from software capabilities and restructure aftermarket revenue streams around subscription-based flight autonomy modules.
Growth Catalysts
- Beyond-Visual-Line-of-Sight waivers:FAA Part 107 waiver expansion for infrastructure inspection and emergency response missions is unlocking enterprise fleet scaling without pilot-per-aircraft ratios.
- Carbon-fiber reinforced polymer rotor arms:Material advances in Guangdong manufacturing corridors are pushing thrust-to-weight ratios past two-to-one, enabling heavier pesticide payloads in precision agriculture.
- EU drone regulation harmonization:EASA's unified airworthiness certification framework is collapsing 27 national approval pathways into single-market product launches.
Market Restraints
- Lithium-polymer battery supply concentration:Cathode precursor refining in China's Hunan province creates input cost volatility and geopolitical exposure for non-domestic assemblers.
- Remote ID hardware mandates:FAA and EASA compliance deadlines are forcing retrofits on legacy fleets, squeezing operator margins in price-sensitive agricultural segments.
- Fixed-wing hybrid substitution:Infrastructure inspection buyers are pivoting to VTOL-fixed-wing hybrids for corridor missions exceeding 50 kilometers, eroding pure rotary blade addressable market in long-range applications.
Strategic Opportunities
- Brazilian precision agriculture penetration:Mato Grosso soybean operators are expanding multirotor spraying drone procurement faster than regulatory framework maturation, creating first-mover service provider consolidation potential.
- Detect-and-avoid technology convergence:Integration of onboard radar with optical flow sensors is enabling autonomous operations in GPS-denied environments, opening underground mining and dense urban inspection verticals.
- CAAC low-altitude economy zones:China's municipal pilot programs in Shenzhen and Chengdu are pre-approving airspace corridors for commercial UAV logistics, compressing certification timelines versus Western pathways.
Industry Challenges
- Flight autonomy engineering scarcity:Computer vision and sensor fusion talent pools concentrate in Shenzhen and Boston, forcing manufacturers to relocate R&D or pay 40-60% salary premiums.
- Airworthiness certification timeline compression:EASA's new drone category framework requires extensive flight hour documentation, stretching product launch schedules for mid-tier manufacturers without existing type certificates.
- Interoperability with legacy command systems:Defense operators require STANAG 4586 compliance for NATO integration, adding software architecture costs that civilian-focused suppliers struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Blade UAV Drones Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Single Rotor, Fixed Wing, Hybrid Application: Agriculture, Surveillance, Parcel Delivery, Infrastructure Inspection End User: Aerospace, Defense, Civil, Commercial Technology: GPS, LiDAR, Camera Systems, Communication Systems |
| Companies Covered | AeroVironment, JOUAV, DJI, 3D Robotics, Draganfly Innovations, Skydio, Parrot, Microdrones, Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Blade UAV Drones Market Emerging Trajectories
Autonomous flight stacks are migrating from aftermarket add-ons to factory-integrated standard equipment, compressing the value capture window for pure-play software vendors and shifting competitive advantage toward sensor-software-hardware co-design capabilities.
Hybrid VTOL architectures that combine multirotor hover precision with fixed-wing cruise efficiency are expanding into transmission line and pipeline inspection fleets previously served by pure rotary blade platforms. European infrastructure operators in Norway and Germany are adopting these configurations for 100-kilometer corridor missions. The technology is expanding into addressable market space previously ceded to crewed helicopters, compressing per-kilometer inspection costs by eliminating pilot rotation requirements.
EASA's Specific Category operational authorization framework is mandating standardized risk assessment methodologies for commercial UAV flights in populated areas. The regulation is forcing manufacturers to pre-integrate parachute recovery systems and geofencing databases at factory level rather than operator retrofit. Agricultural spraying contractors in France and Spain are delaying fleet renewals until OEMs certify integrated safety packages, compressing hardware refresh cycles by 12-18 months.
Enterprise buyers are consolidating vendor relationships around full-stack service contracts that bundle hardware, pilot training, maintenance, and regulatory compliance. Defense procurement officers in the US and UK are displacing component sourcing in favor of system-of-systems awards to prime contractors. Brazilian agribusiness operators show the most visible concentration, with Mato Grosso cooperatives reducing supplier counts from six to two per fleet to simplify airworthiness documentation and pilot certification tracking.
Rotary Blade UAV Drones Market Segmentation
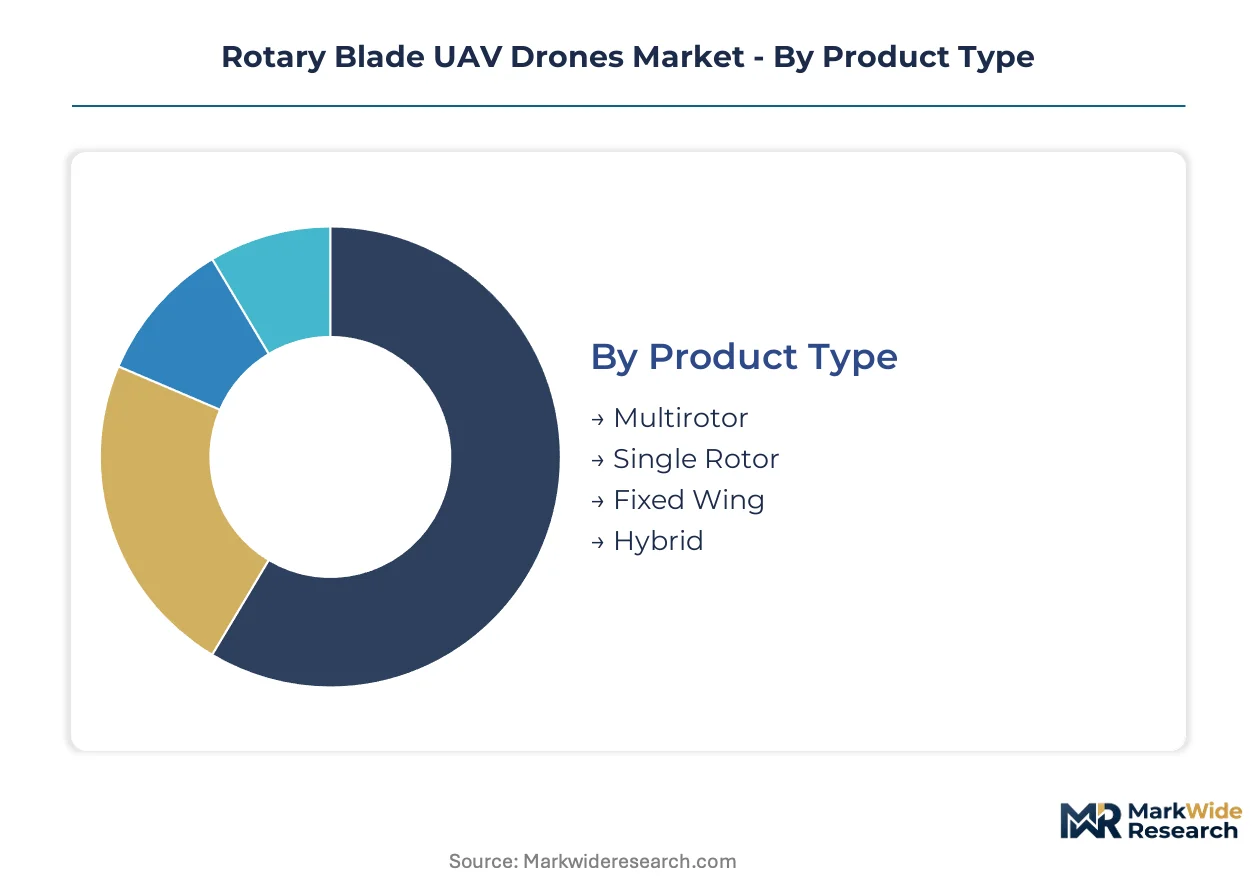
Rotary blade UAV procurement patterns diverge sharply across product architectures and payload configurations. Capital deployment, regulatory compliance burdens, and operational mission profiles all shift meaningfully between segments.
Product Type:
Capital intensity peaks with hybrid architectures requiring dual propulsion systems and complex flight control software. Single rotor platforms demand precision transmission engineering that multirotor designs avoid entirely.
- Multirotor:Three-plus vertically oriented rotors deliver mechanical simplicity and instantaneous thrust vectoring for precision hovering. Demand concentrates in China's Guangdong manufacturing corridor where DJI and Autel Robotics anchor component ecosystems, driven by precision agriculture spraying contracts in Brazil's Mato Grosso state where field maneuverability outweighs endurance requirements.
- Single Rotor:One main rotor with anti-torque tail rotor achieves fuel efficiency and payload capacity impossible with battery-electric multirotor alternatives. Heavy-lift logistics operators in defense and agricultural segments absorb higher acquisition costs for extended flight duration and structural margin reserves.
- Fixed Wing:Conventional aerodynamic lift surfaces maximize range and endurance for corridor surveillance missions. Operators with runway access in remote monitoring applications favor this configuration for cost-per-kilometer efficiency.
- Hybrid:VTOL rotary lift transitions to fixed-wing cruise, combining hover precision with transit range. Infrastructure inspection buyers in Norway and Germany are adopting these for 100-kilometer pipeline and transmission line missions previously requiring crewed helicopters.
Most installed capacity flows through Multirotor. Expansion is steepest in Hybrid.
Application:
Mission duration and payload sophistication separate high-investment surveillance deployments from commoditized agricultural spraying operations.
- Agriculture:Crop monitoring and pesticide application dominate unit volume with standardized payload packages. Brazilian soybean cooperatives are consolidating fleet procurement around full-stack service contracts bundling hardware, pilot training, and regulatory compliance documentation.
- Surveillance:ISR missions demand sensor fusion architectures integrating electro-optical, infrared, and signals intelligence payloads. Defense procurement officers in the US and UK are displacing component sourcing in favor of system-of-systems awards to prime contractors with STANAG 4586 compliance.
- Parcel Delivery:Last-mile logistics requires detect-and-avoid integration and beyond-visual-line-of-sight certification. China's CAAC low-altitude economy zones in Shenzhen and Chengdu are pre-approving airspace corridors, compressing commercial deployment timelines versus Western regulatory pathways.
- Infrastructure Inspection:Bridge, tower, and pipeline assessment combines high-resolution imaging with stable hover positioning. European operators are delaying fleet renewals until OEMs certify integrated parachute recovery systems mandated by EASA's Specific Category framework.
Volume leadership sits with Agriculture. Parcel Delivery is climbing the fastest as airspace frameworks mature.
End User:
Procurement sophistication and compliance tolerance vary dramatically between institutional defense buyers and fragmented commercial operators.
- Aerospace:Manufacturing quality assurance and facility security applications require integration with existing enterprise systems. Tier-one suppliers are specifying OEM service contracts covering predictive maintenance and regulatory documentation.
- Defense:Mission-critical specifications mandate modular payload architectures swapping sensors between ISR and electronic warfare roles. NATO interoperability requirements add software architecture costs that civilian-focused suppliers struggle to absorb.
- Civil:Government agencies and public safety organizations operate under constrained budgets with waiver-dependent airspace access. FAA Part 107 expansion for emergency response missions is unlocking fleet scaling without pilot-per-aircraft ratios.
- Commercial:Enterprise and small-business operators span agriculture, construction, and media production with divergent payload needs. Vendor consolidation is reducing supplier counts from six to two per fleet to simplify airworthiness documentation and pilot certification tracking.
Defense commands highest per-unit expenditure. Commercial segments are gaining share fastest through enterprise fleet scaling.
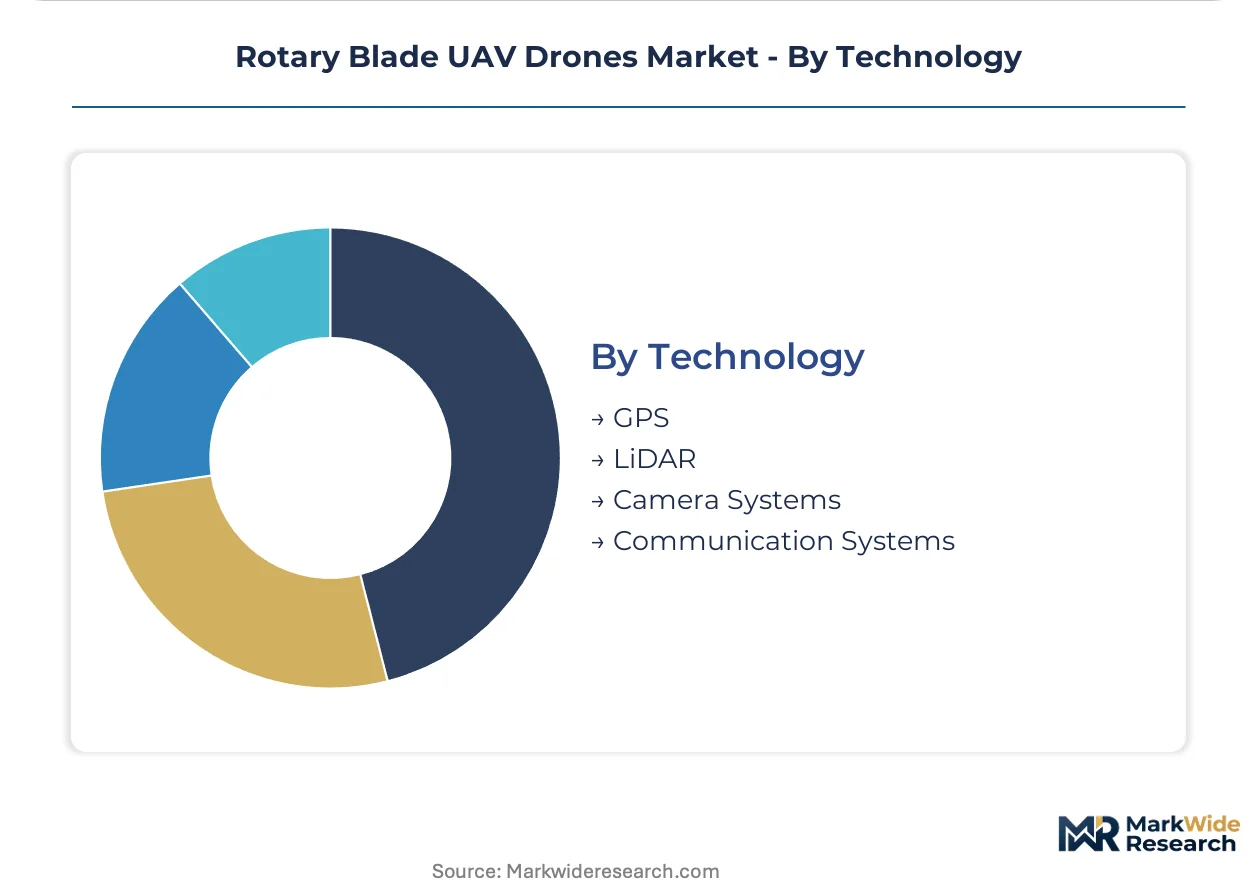
Technology:
Sensor and navigation subsystem costs represent an increasing share of total platform value as autonomy requirements intensify.
- GPS:Satellite positioning remains foundational for waypoint navigation and georeferenced data collection. Signal denial vulnerabilities are driving investment in backup navigation architectures for contested environments.
- LiDAR:Laser ranging enables three-dimensional mapping and obstacle detection in degraded visual conditions. Underground mining and dense urban inspection verticals are opening as onboard radar converges with optical flow sensors for GPS-denied autonomy.
- Camera Systems:Electro-optical and infrared imaging dominate payload mass and power budgets. Integrated camera-gimbal-telemetry packages from Guangdong manufacturers are reducing field configuration time for commercial operators.
- Communication Systems:Command links and data transmission infrastructure determine operational range and real-time control reliability. Beyond-visual-line-of-sight waiver frameworks are the primary variable reordering competitive positioning in enterprise procurement channels.
Camera Systems carry the largest installed base. LiDAR is expanding most quickly as autonomy stacks migrate from aftermarket add-ons to factory-integrated standard equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rotary blade UAV industry traces its commercial scaling to Shenzhen's manufacturing ecosystem, where component integration and export assembly established the production template now replicated across multiple geographies.
United States
FAA Part 107 waiver expansion for infrastructure inspection and emergency response missions is accelerating enterprise fleet procurement. Remote ID hardware mandates are forcing retrofits on legacy agricultural fleets, compressing operator margins. Defense procurement officers in Arlington and Boston corridors are consolidating awards around system-of-systems primes with STANAG 4586 compliance.
China
CAAC low-altitude economy zones in Shenzhen and Chengdu are pre-approving commercial UAV logistics corridors, compressing deployment timelines versus Western pathways. Municipal pilot programs are compressing certification timelines for parcel delivery operators. Guangdong manufacturing clusters anchor global component ecosystems for brushless DC motors and carbon-fiber rotor arms.
Brazil
Mato Grosso soybean cooperatives are expanding multirotor spraying drone procurement faster than ANVISA regulatory framework maturation. Full-stack service contracts bundling hardware, pilot training, and compliance documentation are consolidating supplier relationships. São Paulo-based service providers are capturing first-mover consolidation potential in precision agriculture.
Germany
EASA's unified airworthiness certification framework is collapsing 27 national approval pathways into single-market product launches. Infrastructure operators in Bavaria and North Rhine-Westphalia are adopting hybrid VTOL configurations for 100-kilometer pipeline missions. OEMs are delaying integrated parachute recovery system certifications under Specific Category mandates.
Norway
Transmission line operators are pivoting to VTOL-fixed-wing hybrids for corridor inspections exceeding 50 kilometers, eroding pure rotary blade addressable market in long-range applications. EASA risk assessment methodologies for populated area flights are mandating factory-integrated safety packages. Stavanger and Bergen energy clusters are driving per-kilometer inspection cost compression.
Rotary Blade UAV Drones Market Vendor Landscape
Premium-margin players sit above commodity-margin players across autonomy software and integrated payload dimensions, with tiering visible in sensor-software-hardware co-design depth. The vendor base separates into three strategic archetypes: Guangdong-anchored scale manufacturers, defense-focused modular architects, and autonomy-software subscription specialists. Consolidation pressure is intensifying through M&A activity among mid-tier hardware assemblers and strategic partnerships between flight stack developers and sensor fusion specialists.
Among Shenzhen-anchored scale manufacturers, DJI and Autel Robotics exemplify the integrated camera-gimbal-telemetry packaging archetype that reduces field configuration time for commercial operators. AeroVironment occupies a position within the defense modular architecture tier, representing the sensor-swapping ISR-to-electronic-warfare mission flexibility that NATO procurement officers specify. Skydio sits within the autonomy-software subscription segment, anchoring the unbundled software capability model that separates flight autonomy modules from hardware purchases. These three archetypes illustrate how competitive positioning now depends on where value capture concentrates—manufacturing scale, mission flexibility, or recurring software revenue—rather than hardware unit economics alone.
| Leading Market Players |
|---|
| AeroVironment |
| JOUAV |
| DJI |
| 3D Robotics |
| Draganfly Innovations |
| Skydio |
| Parrot |
| Microdrones |
| Autel Robotics |
| Others |
Supply Flow & Price Mechanics
FAA Remote ID hardware mandates and EASA airworthiness deadlines are forcing legacy fleet retrofits that compress operator margins and push procurement toward factory-integrated safety packages. This demand-side specification shift concentrates buying power among Guangdong-scale manufacturers with captive component ecosystems, hardening price premiums for integrated telemetry-gimbal-camera bundles while squeezing mid-tier assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates defense-grade modular architectures from agricultural workhorse units and entry-level inspection platforms. Certification grade and volume scale drive price differentiation, with STANAG 4586-compliant systems commanding substantial premiums over commercial equivalents. Cost compression in agricultural segments is intensifying because Brazilian cooperatives consolidate supplier counts and negotiate full-stack service contracts. Commercial agriculture operators exhibit highest price sensitivity, while defense procurement officers show lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Single-source vulnerability sits with lithium-polymer cathode precursor refining concentrated in China's Hunan province. Brushless DC motors and carbon-fiber rotor arms draw from Guangdong manufacturing clusters, while flight autonomy chipsets rest on Taiwan and South Korean semiconductor fabrication. Tariff exposure on battery inputs creates input cost volatility for non-domestic assemblers. Distribution runs through OEM-direct enterprise contracts and agricultural cooperative purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
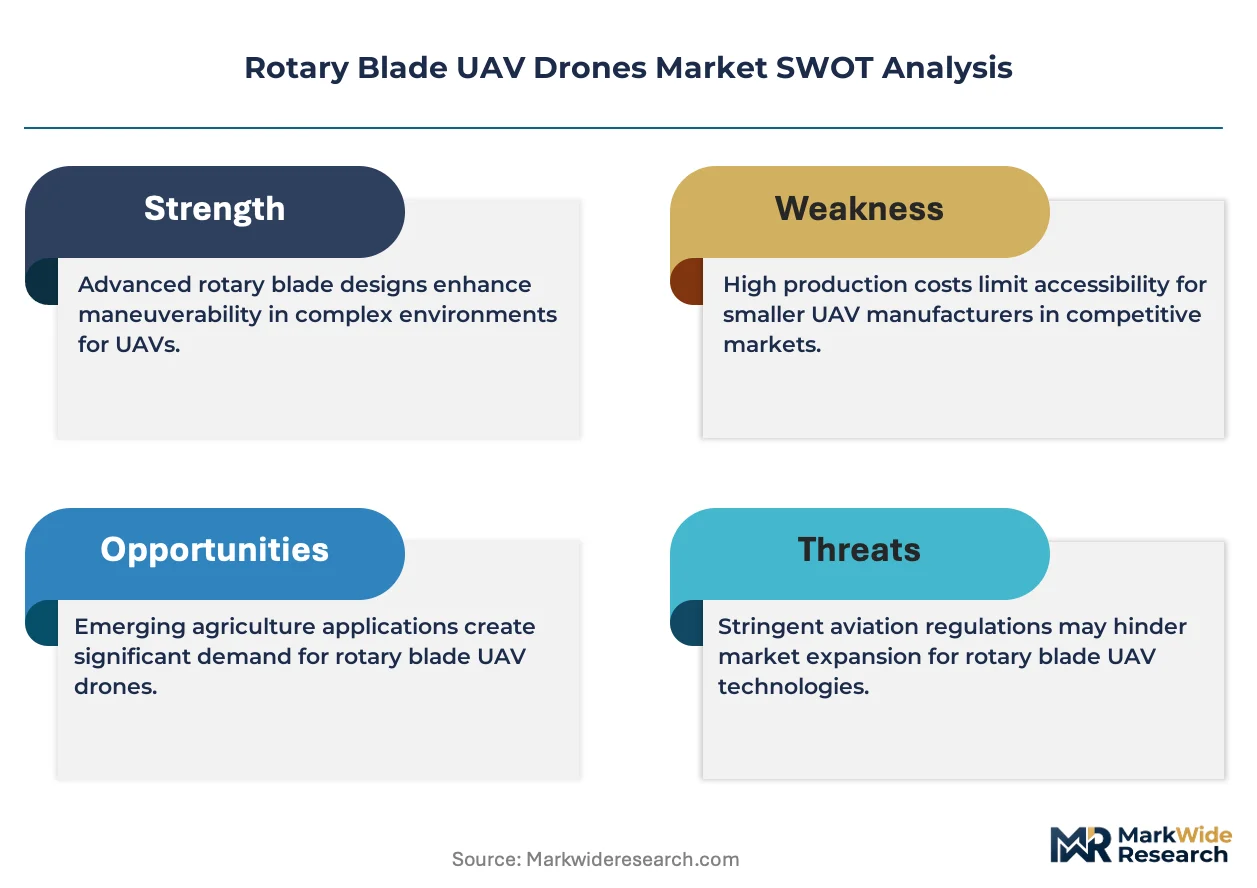
This market compounds regulatory tailwinds into procurement acceleration, with EASA's unified certification framework collapsing approval pathways and compressing product launch timelines for compliant manufacturers.
For Market Incumbents: To counter fixed-wing hybrid substitution in long-range infrastructure inspection, deepen sensor-software-hardware co-design capabilities and secure CAAC low-altitude economy zone partnerships in Shenzhen and Chengdu. Certification investment in parachute recovery systems and geofencing databases defends position against EASA Specific Category mandates. For New Entrants and Emerging Players: Underground mining operators in GPS-denied environments represent an underserved buyer archetype with limited incumbent penetration. Detect-and-avoid technology convergence opens white-space in dense urban inspection verticals. A go-to-market angle anchored to autonomy software subscriptions unbundled from hardware purchases bypasses capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with flight stack developers possessing sensor fusion expertise in Shenzhen or Boston talent corridors. Long-term viability favors acquisition targets with factory-integrated autonomy architectures rather than aftermarket software vendors. The signal to watch is beyond-visual-line-of-sight waiver expansion velocity as the primary inflection indicator for enterprise fleet scaling.| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Low-Altitude Zone Partnership | Pre-approved logistics corridors in Shenzhen compress certification timelines versus Western pathways. |
| Detect-and-Avoid Technology Acquisition | Onboard radar-optical flow convergence enables GPS-denied autonomy in mining and urban inspection. |
| Full-Stack Service Contract Expansion | Bundled hardware-training-compliance offerings capture Brazilian agricultural cooperative consolidation. |
| STANAG 4586 Compliance Investment | NATO interoperability certification unlocks defense procurement channels with premium margin structures. |
| Hybrid VTOL Architecture Development | Dual-propulsion systems address 100-kilometer corridor missions eroding pure rotary blade market share. |
Methodological Framework
Multiple input streams — primary interviews with UAV fleet operators, component procurement leads, and regulatory compliance officers; secondary validation through FAA waiver databases, EASA type certificate registries, and CAAC low-altitude economy policy filings; plus customs trade data on brushless motor and carbon-fiber arm shipments — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation across product architecture, application vertical, end-user sophistication, and technology subsystem dimensions anchored volume and value outputs throughout the forecast period. CAGRs were derived from segmented growth trajectory blending and cross-referenced against airspace regulatory milestone timelines. Forecast inputs incorporated beyond-visual-line-of-sight waiver velocity and detect-and-avoid technology adoption curves specific to infrastructure inspection and agricultural spraying verticals.
Underlying measurement precision varies by segment; multirotor agriculture and defense surveillance carry tighter precision than emerging parcel delivery and hybrid VTOL categories. Forecasts reflect assumptions on regulatory harmonization pace and battery chemistry cost curves, with outcomes best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia-Pacific Drone Software Market
UAV
Global Drone Light Shows Market
UAV
Miniature Drone Market
UAV
Drone Data Management Market
UAV
Global Drone Software Market
UAV
Global Drone Data Services Market
UAV
UAV Navigation Systems Market
UAV
Commercial UAV Market
UAV
Global Renewable Drones Market
UAV
Drone Defense System Market
UAV
UAV Simulator Software Market
UAV
Global Multirotor UAV Market
UAV
Portable Drone Market
UAV
Latin America Small UAV Market
UAV
Drone Identification System Market
UAV
UAV Battery Market