
 Miniature Drone Market | 2026-2036
Miniature Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Miniature Drone Market Insights
Defense and emergency response is realigning the miniature drone competitive map as military procurement shifts toward squad-level ISR platforms. SZ DJI Technology Co., Ltd. dominates the commercial tier through manufacturing scale and channel control across consumer and prosumer segments. AeroVironment, Inc. anchors the defense vertical with specialized small UAV systems tailored to battlefield portability requirements. Skydio, Inc. differentiates through autonomous navigation software that leverages computer vision for obstacle avoidance in GPS-denied environments.
A miniature drone denotes an unmanned aerial vehicle with maximum dimensions typically under 250 millimeters and gross takeoff weight below 25 kilograms, powered by lithium-polymer battery packs and controlled via radio frequency or autonomous flight computers executing waypoint missions. Multirotor configurations lead volume shipments due to mechanical simplicity and vertical takeoff capability, while hybrid VTOL architectures capture premium positioning where endurance and range requirements exceed pure rotary-wing limitations. GPS navigation technology remains the baseline positioning layer, though LiDAR integration is expanding fastest among surveying and infrastructure inspection deployments where centimeter-level accuracy commands price premiums.
The FAA Part 107 framework in the United States and EASA open category standards in Europe shape product design thresholds, particularly the 250-gram regulatory boundary that separates exempt operations from certified pilot requirements. China's MIIT and NMPA coordinate frequency allocation and airworthiness protocols for domestic manufacturers exporting under GB standards compliance. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver processes and emerging counter-drone mandates that will determine which technology portfolios retain market access across the three dominant regulatory blocs.
Market Dynamics
Defense procurement is compressing development cycles for squad-level ISR platforms while FAA Part 107 and EASA open category rules harden the 250-gram regulatory boundary that separates exempt from certified commercial operations.
Growth Catalysts
- Precision Agriculture:Crop monitoring and variable-rate spraying applications are pulling construction firms and disaster management agencies into fleet procurement.
- FAA Part 107:Remote pilot certification frameworks in the United States are professionalizing commercial operations and expanding the addressable operator base.
- LiDAR Integration:Surveying and infrastructure inspection deployments are commanding price premiums for centimeter-level accuracy in GPS-denied environments.
Market Restraints
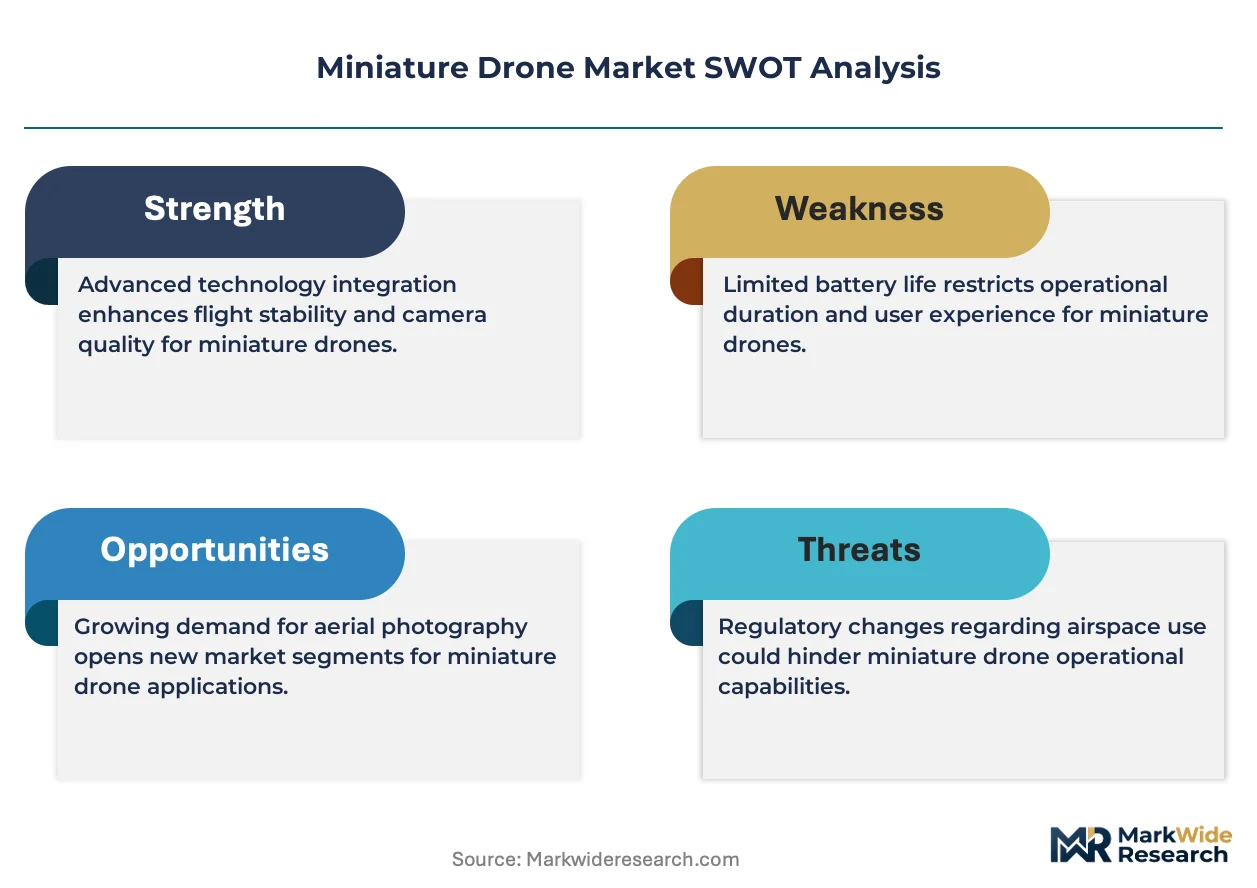
- Lithium-Polymer Supply Concentration:Battery pack sourcing clusters in Chinese manufacturing corridors, exposing procurement to geopolitical friction and export control volatility.
- Radio Frequency Spectrum Scarcity:Control link congestion in the 2.4 GHz and 5.8 GHz bands is constraining swarm coordination and beyond-visual-line-of-sight mission density.
- EASA Open Category Ceiling:The 250-gram operational threshold blocks heavier sensor payloads from exempt flights, fragmenting product architectures across regulatory tiers.
Strategic Opportunities
- Wildlife Monitoring:Environmental organizations in Germany are expanding fleet deployments for habitat mapping and anti-poaching surveillance, opening conservation procurement channels.
- Hybrid VTOL Architectures:Convergence of multirotor simplicity with fixed-wing endurance is capturing premium positioning in infrastructure inspection missions exceeding pure rotary-wing range.
- Beyond-Visual-Line-of-Sight Waivers:Emerging FAA waiver processes for extended range operations are creating first-mover advantages for autonomous navigation software stacks.
Industry Challenges
- Remote Pilot Certification Bottlenecks:FAA Part 107 testing capacity and EASA theoretical knowledge requirements are throttling operator supply expansion in commercial segments.
- Counter-Drone Mandate Compliance:Emerging detection and mitigation protocols in defense and critical infrastructure environments are forcing hardware redesigns for signature reduction and identification broadcasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniature Drone Market |
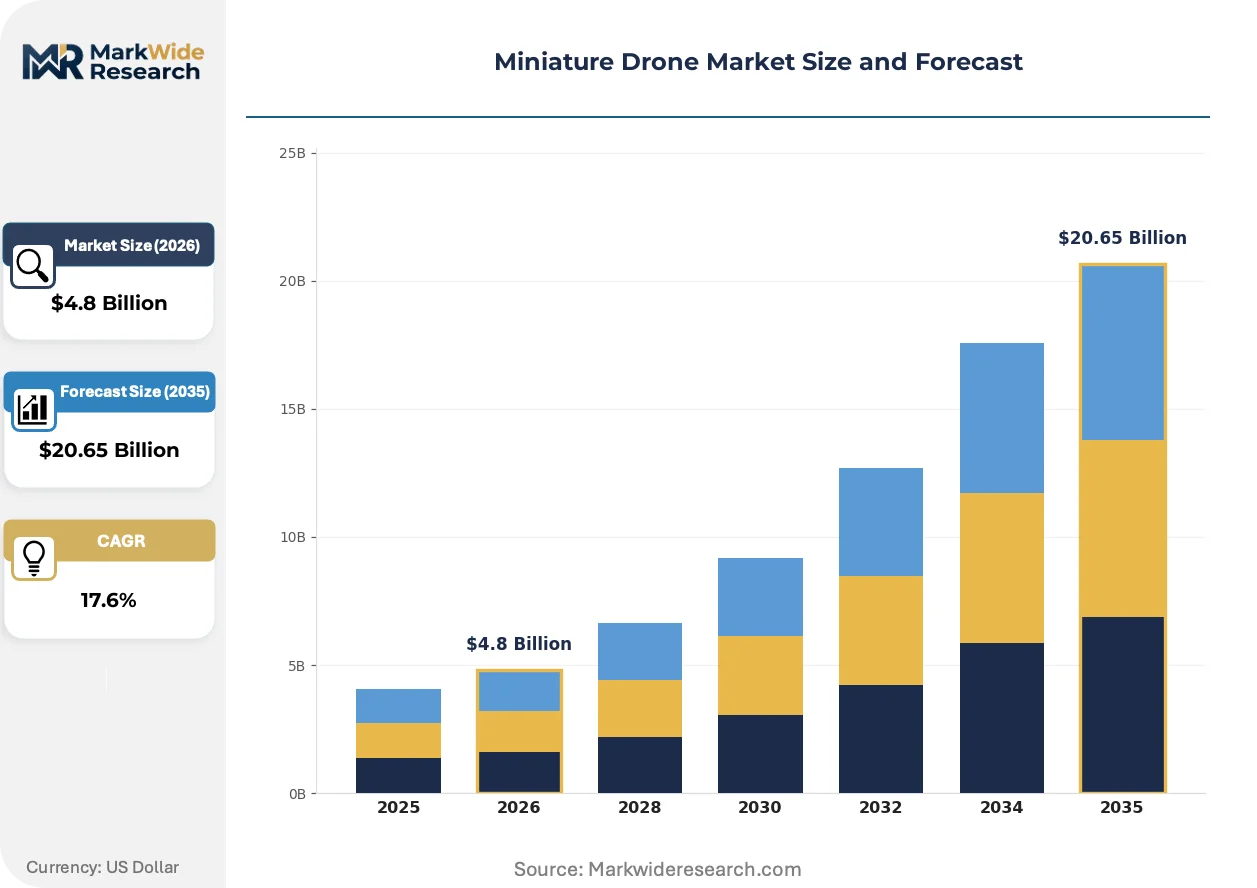
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Single Rotor, Hybrid VTOL Technology: GPS Navigation, Optical Flow, Ultrasonic, Inertial Measurement Unit, LiDAR Application: Precision Agriculture, Infrastructure Inspection, Emergency Response, Wildlife Monitoring, Surveying End User: Research Institutions, Construction Firms, Disaster Management Agencies, Environmental Organizations |
| Companies Covered | SZ DJI Technology Co., Ltd., Parrot Drones SAS, AeroVironment, Inc., Skydio, Inc., Autel Robotics Co., Ltd., Yuneec International Co. Ltd., Teledyne Technologies Incorporated, Northrop Grumman Corporation, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniature Drone Market Trends and Innovations
Computer vision and edge AI are compressing the autonomy stack from ground stations onto airframes, while regulatory frameworks in the United States, Europe, and China diverge on safety assurance methodologies.
Autonomous navigation software is automating obstacle avoidance and waypoint execution without GPS dependency. Defense ministries and emergency response agencies are accelerating adoption for contested environment operations. This capability compression is automating mission planning labor and reducing operator training thresholds for complex ISR deployments.
EASA open category standards are hardening technical documentation requirements for C0-C4 drone classes. Manufacturers must now submit noise testing, kinetic energy calculations, and remote identification protocols before market access. The 250-gram boundary is most acutely affecting commercial prosumer segments in Germany and France, where operators are downsizing payloads or accepting certified pilot costs.
Construction firms are unbundling equipment procurement from flight service contracts, preferring to lease drone-in-a-box systems with embedded pilot networks. Traditional distributor channels face disintermediation as manufacturers deploy direct-to-fleet subscription models. This shift is most visible in the United States, where infrastructure inspection verticals are consolidating vendor relationships around outcome-based deliverables rather than hardware ownership.
Miniature Drone Market Segmentation
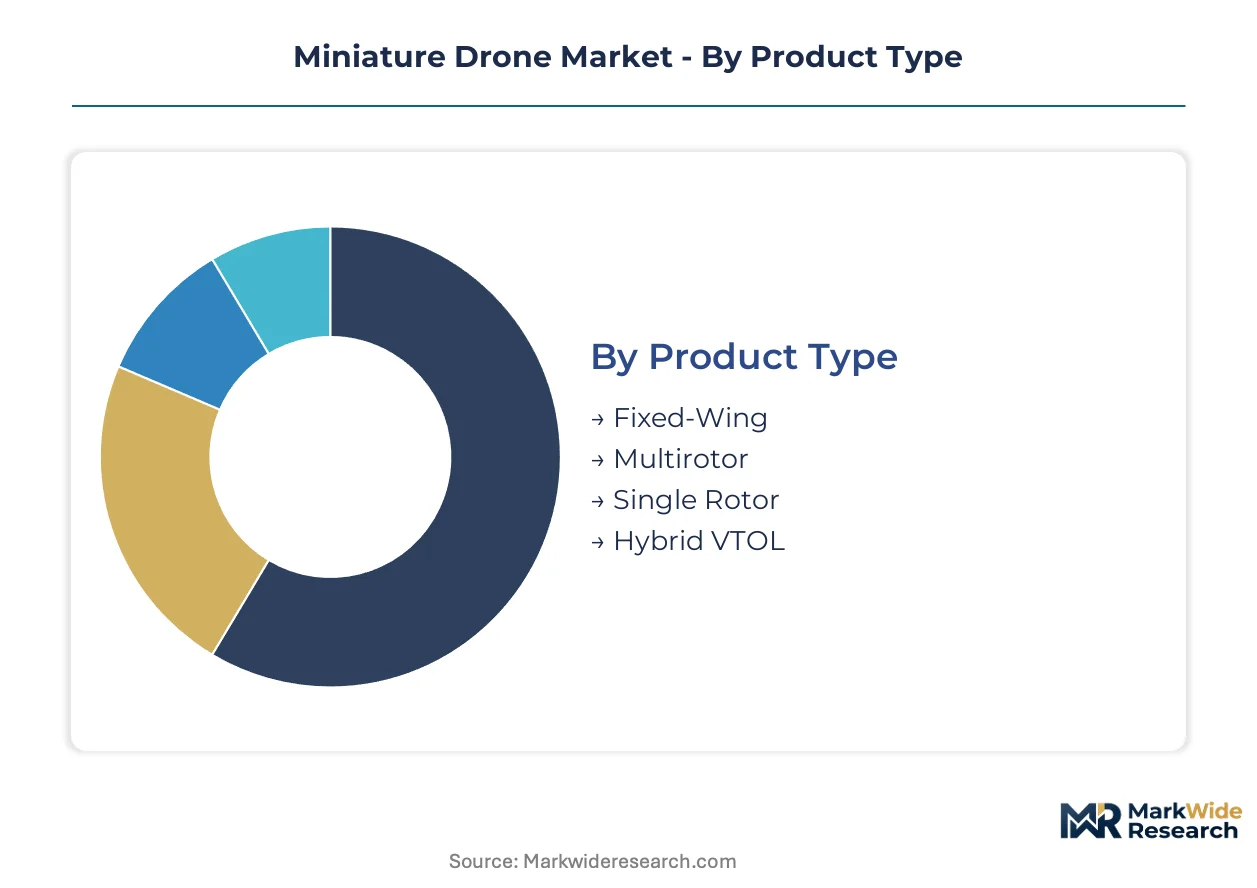
Miniature drone procurement patterns diverge sharply across product architectures and sensor payloads. Regulatory thresholds and mission endurance requirements fragment demand into distinct operational tiers with incompatible hardware specifications.
Product Type:
Volume shipments concentrate in mechanically simple platforms, while premium positioning accrues to endurance-optimized architectures that breach the 250-gram regulatory boundary.
- Multirotor:Four-to-eight rotor configurations dominate commercial shipments through vertical takeoff simplicity and mechanical redundancy. Demand concentrates among construction firms in the United States and Germany executing infrastructure inspection missions where maneuverability trumps range.
- Hybrid VTOL:Converged tilt-rotor and lift-plus-cruise architectures capture premium positioning where fixed-wing endurance must combine with rotary launch flexibility. Environmental organizations in Germany deploy these for wildlife monitoring missions exceeding pure multirotor range limitations.
- Fixed-Wing:Conventional pusher-propeller designs optimize for pure endurance in open terrain mapping.
- Single Rotor:Helicopter-style platforms serve niche heavy-payload applications in defense ISR.
Mature deployment sits with Multirotor. Newer deployment is concentrated in Hybrid VTOL.
Technology:
Positioning accuracy requirements stratify sensor integration, with baseline GPS giving way to optical and inertial augmentation in contested environments.
- GPS Navigation:Satellite-based positioning remains the default layer for waypoint missions and geofencing compliance. FAA Part 107 certification mandates GPS logging for commercial operations in the United States, entrenching this technology across certified pilot workflows.
- LiDAR:Light detection and ranging systems command price premiums in surveying and infrastructure inspection where centimeter-level accuracy justifies payload weight penalties. Deployment is climbing the fastest among German environmental organizations mapping habitat topography.
- Optical Flow:Computer vision-based dead reckoning enables indoor navigation without satellite lock.
- Inertial Measurement Unit:Accelerometer-gyroscope fusion stabilizes flight in GPS-denied environments.
- Ultrasonic:Proximity sensing for precision landing and low-altitude obstacle detection.
Established integration sits with GPS Navigation. Accelerating integration is concentrated in LiDAR.
Application:
Mission type determines payload configuration and regulatory pathway, with agricultural and inspection workflows driving distinct procurement rhythms.
- Precision Agriculture:Crop health monitoring and variable-rate spraying applications pull construction firms and disaster management agencies into fleet procurement. China's MIIT coordinates frequency allocation for agricultural drones operating under GB standards compliance.
- Infrastructure Inspection:Bridge, pipeline, and power line surveys demand close-proximity maneuvering and high-resolution imaging. EASA open category rules in Germany and France constrain heavier sensor payloads, fragmenting product architectures across regulatory tiers.
- Emergency Response:Search-and-rescue and damage assessment missions prioritize rapid deployment.
- Wildlife Monitoring:Habitat mapping and anti-poaching surveillance open conservation procurement channels.
- Surveying:Cadastral and topographic mapping requires geodetic-grade positioning accuracy.
Scaled deployment sits with Precision Agriculture. Expanding deployment is concentrated in Infrastructure Inspection.
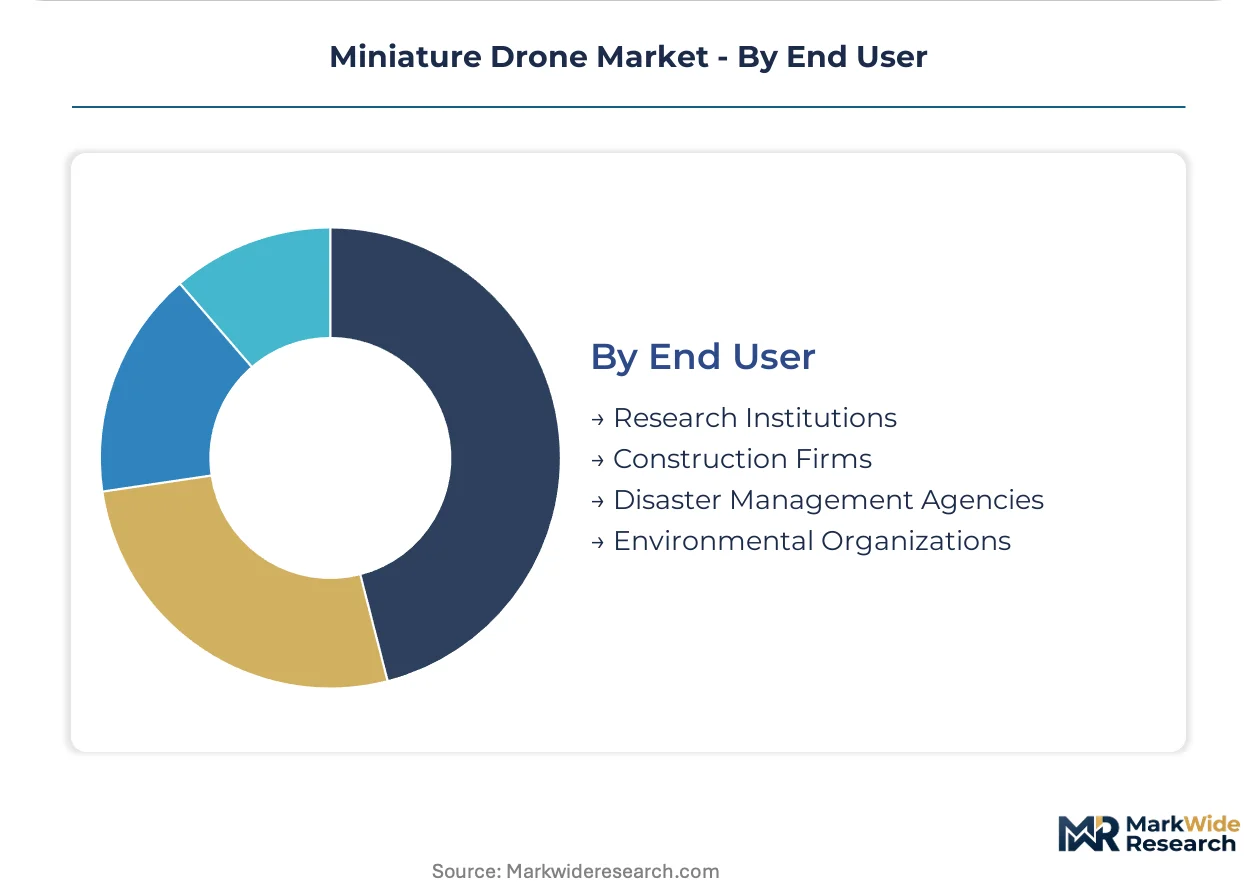
End User:
Procurement authority and operational expertise divide the addressable market between institutional research programs and field-service organizations.
- Construction Firms:Equipment procurement is unbundling from flight service contracts, with firms preferring to lease drone-in-a-box systems with embedded pilot networks. This shift is consolidating vendor relationships around outcome-based deliverables rather than hardware ownership.
- Disaster Management Agencies:Emergency response coordination requires rapid deployment capability and interoperability with existing command structures. FAA Part 107 remote pilot certification bottlenecks are throttling operator supply expansion in this segment.
- Research Institutions:Academic programs drive experimental payload integration and autonomy algorithm development.
- Environmental Organizations:Conservation missions prioritize low acoustic signature and minimal wildlife disturbance.
Institutionalized deployment sits with Construction Firms. Emerging deployment is concentrated in Disaster Management Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates battery pack and flight controller manufacturing, drawing component suppliers into clustered procurement corridors. This special-economic-zone status accelerates customs clearance for lithium-polymer cells and RF modules destined for export assembly.
United States
Defense procurement from the Pentagon's Rapid Capabilities Office drives squad-level ISR platform demand. FAA Part 107 remote pilot certification mandates GPS logging for commercial operations. Austin's hardware accelerator corridor hosts flight software startups refining autonomous navigation stacks for GPS-denied environments.
China
Domestic agricultural spraying fleets scale under MIIT frequency coordination for sub-6 GHz control links. NMPA airworthiness protocols govern GB standards compliance for export-bound manufacturers. Dongguan's electronics assembly belt concentrates brushless motor and ESC production for global OEM supply.
Germany
Environmental organizations deploy hybrid VTOL platforms for Black Forest habitat mapping exceeding multirotor endurance limits. EASA open category C0-C4 classification mandates noise testing and remote ID protocols. Munich's aerospace engineering cluster advances LiDAR integration for centimeter-level surveying accuracy.
Japan
MetI funding programs accelerate disaster response drone deployment for earthquake damage assessment. JIS standards govern electromagnetic compatibility for urban flight operations. Nagoya's industrial automation corridor develops precision landing systems for infrastructure inspection in GPS-challenged environments.
South Korea
MFDS-equivalent aviation safety frameworks professionalize commercial pilot certification pathways. Government smart city initiatives fund beyond-visual-line-of-sight corridor testing in Incheon Free Economic Zone. Seongnam's robotics cluster prototypes swarm coordination algorithms for 2.4 GHz spectrum optimization.
Miniature Drone Market Competitive Landscape
Top-tier vendors anchor defense and enterprise segments, while mid-tier specialists populate prosumer and agricultural niches. The vendor base stratifies across three functional tiers: vertically integrated platform manufacturers, component-specialist subsystem suppliers, and software-centric autonomy providers. Two dominant competitive moves are reshaping positioning: strategic partnerships between hardware OEMs and navigation software houses, and geographic expansion through local certification partnerships in EASA and FAA jurisdictions.
Within the defense-contractor archetype, AeroVironment, Inc. and Northrop Grumman Corporation occupy positions shaped by battlefield portability requirements and military procurement cycles. SZ DJI Technology Co., Ltd. exemplifies the vertically integrated commercial tier, representing manufacturing scale advantages across consumer and prosumer segments. Skydio, Inc. anchors the autonomy-software specialist position, exemplifying competitive differentiation through computer vision-based obstacle avoidance capabilities.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Parrot Drones SAS |
| AeroVironment, Inc. |
| Skydio, Inc. |
| Autel Robotics Co., Ltd. |
| Yuneec International Co. Ltd. |
| Teledyne Technologies Incorporated |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive lithium-polymer cell production in Shenzhen's Qianhai Free Trade Zone anchors both supply security and margin control for tier-one manufacturers exporting under GB standards compliance. This upstream integration insulates dominant vendors from export control volatility while compressing procurement costs for flight controller and RF module assembly.
Pricing Analysis
Short lead-time premiums command pricing power for defense procurement cycles, while spot inventory discounts concentrate among construction firms leasing drone-in-a-box systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in the prosumer tier intensifies as SZ DJI Technology Co., Ltd. scales manufacturing through channel control. Disaster management agencies exhibit highest price sensitivity due to budget-constrained fleet procurement, while defense ministries absorb premium positioning for squad-level ISR platforms.
Supply Chain Analysis
Domestic-content mandates in China's MIIT frequency allocation protocols are reshaping sourcing toward Dongguan-based brushless motor and ESC production for export-bound OEMs. Component dependencies center on lithium-polymer cells from Shenzhen corridors, RF modules from South Korean semiconductor fabs, and precision gyroscopes from Japanese MEMS foundries. Single-source vulnerability concentrates in battery pack chemistry formulations subject to geopolitical friction. Distribution runs through direct-to-fleet subscription models that disintermediate traditional distributor channels in United States infrastructure inspection verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where flight controller firmware and autonomous navigation stacks represent the decisive downstream lever. Players capturing in-house production of LiDAR sensors and edge AI processors will command pricing power across surveying and infrastructure inspection deployments.
For Market Incumbents: Anticipate regulatory fragmentation as EASA open category standards and FAA Part 107 waivers diverge on beyond-visual-line-of-sight requirements. Defensive consolidation should prioritize certification investment in C0-C4 drone classes and channel control through embedded pilot network leases. Threat vectors include swarm coordination algorithms from Seongnam's robotics cluster and counter-drone mandate compliance costs forcing hardware redesigns.
For New Entrants and Emerging Players: The price-point gap between premium hybrid VTOL architectures and economy multirotor platforms opens white-space targeting in German environmental organizations deploying Black Forest habitat mapping. Most penetrable segment sits with disaster management agencies throttled by remote pilot certification bottlenecks. Go-to-market angle should emphasize autonomous navigation software stacks that reduce operator training thresholds for complex ISR deployments.
For Investors and Strategic Acquirers: Exit pathways concentrate in autonomy-software specialist acquisitions by hardware OEMs seeking computer vision capabilities for GPS-denied environments. Long-term viability favors vertically integrated platform manufacturers with captive battery supply and GB standards export compliance. Signal to watch: FAA beyond-visual-line-of-sight waiver approval velocity as inflection indicator for autonomous navigation software valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LiDAR Sensors | Captures centimeter-level accuracy premiums in German surveying verticals. |
| Strategic Partnership with Navigation Software Houses | Accelerates GPS-denied autonomy deployment for contested environment operations. |
| Geographic Expansion through EASA Certification Partnerships | Unlocks C0-C4 drone class access in German and French conservation procurement channels. |
| Product Launch: Hybrid VTOL Architecture | Addresses wildlife monitoring missions exceeding pure multirotor endurance limitations. |
| Direct-to-Fleet Subscription Model | Consolidates vendor relationships with United States construction firms around outcome-based deliverables. |
Research Methodology
Multi-period observation of fleet deployment volumes, regulatory waiver approvals, and component pricing anchored the trend analysis, supplemented by interviews with defense procurement officers, FAA certification consultants, agricultural spraying fleet operators, and LiDAR integration engineers. Secondary validation drew from FAA Part 107 waiver databases, EASA technical documentation requirements, MIIT frequency allocation notices, and customs records for lithium-polymer cell exports. Bottom-up shipment estimates triangulated against top-down defense budget allocations and agricultural subsidy programs.
The input-output matrix framed demand drivers against supply constraints across product architecture, sensor payload, application vertical, and end-user procurement authority dimensions. CAGRs were derived from regression analysis of historical fleet expansion rates and projected regulatory pathway maturation. Industry-specific forecast inputs included beyond-visual-line-of-sight waiver approval timelines and counter-drone mandate implementation schedules across the three dominant regulatory blocs.
Inputs from defense procurement databases and environmental organization grant disclosures were available through the study window; gaps in real-time lithium-polymer spot pricing and classified military ISR budgets introduce uncertainty bands around squad-level platform demand estimates. Forecasts reflect documented assumptions on regulatory convergence and battery chemistry cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Industrial Drones Market
UAV
North America Small UAV Market
UAV
UAV Simulator Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Drone-In-A-Box Market
UAV
Europe Commercial Drones Market
UAV
Enterprise Drone Management Solutions Market
UAV
North America Drone Software Market
UAV
Commercial Drone Market
UAV
Asia-Pacific Drone Motor Market
UAV
Electric Glider Market
UAV
Drone Tracking Antenna Market
UAV
Solar Powered Drones Market
UAV
Passenger Drones Market
UAV
FPV Drone Goggles Market
UAV
Latin America Small UAV Market