
 Global Drone Data Services Market | 2026-2036
Global Drone Data Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Data Services Market Foresight
Certified drone pilot availability is rotating from bottleneck to growth enabler as training programs scale across aviation academies and community colleges. DroneDeploy leverages cloud-based photogrammetry platforms to sustain enterprise market penetration. PrecisionHawk anchors agricultural analytics through its specialized crop health algorithms. Pix4D SA competes on survey-grade accuracy for construction and infrastructure clients.
Drone data services encompass the capture, processing, analysis, and delivery of geospatial intelligence derived from unmanned aerial vehicle sensors, typically involving orthomosaic generation at sub-centimeter ground sample distances and point cloud densification for volumetric measurement. These services convert raw imagery into actionable asset intelligence for industries managing distributed physical infrastructure. Mapping services currently dominate revenue as utilities and mining firms mandate digital twin refresh cycles, while inspection services represent the fastest-expanding margin pool as predictive maintenance contracts replace episodic manual surveys. Cloud-based deployment models lead adoption among mid-market survey firms seeking elastic compute for seasonal project surges.
The FAA's Part 107 certification requirements and EASA's open/specific/certified operational categories shape pilot qualification standards and airspace access tiers across the United States and Europe. China's CAAC drone regulations and GB standards enforce manufacturing conformity and flight logging protocols for domestic operators and exporters. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver frameworks and data sovereignty requirements as automated fleet operations expand across jurisdictions.
Market Dynamics
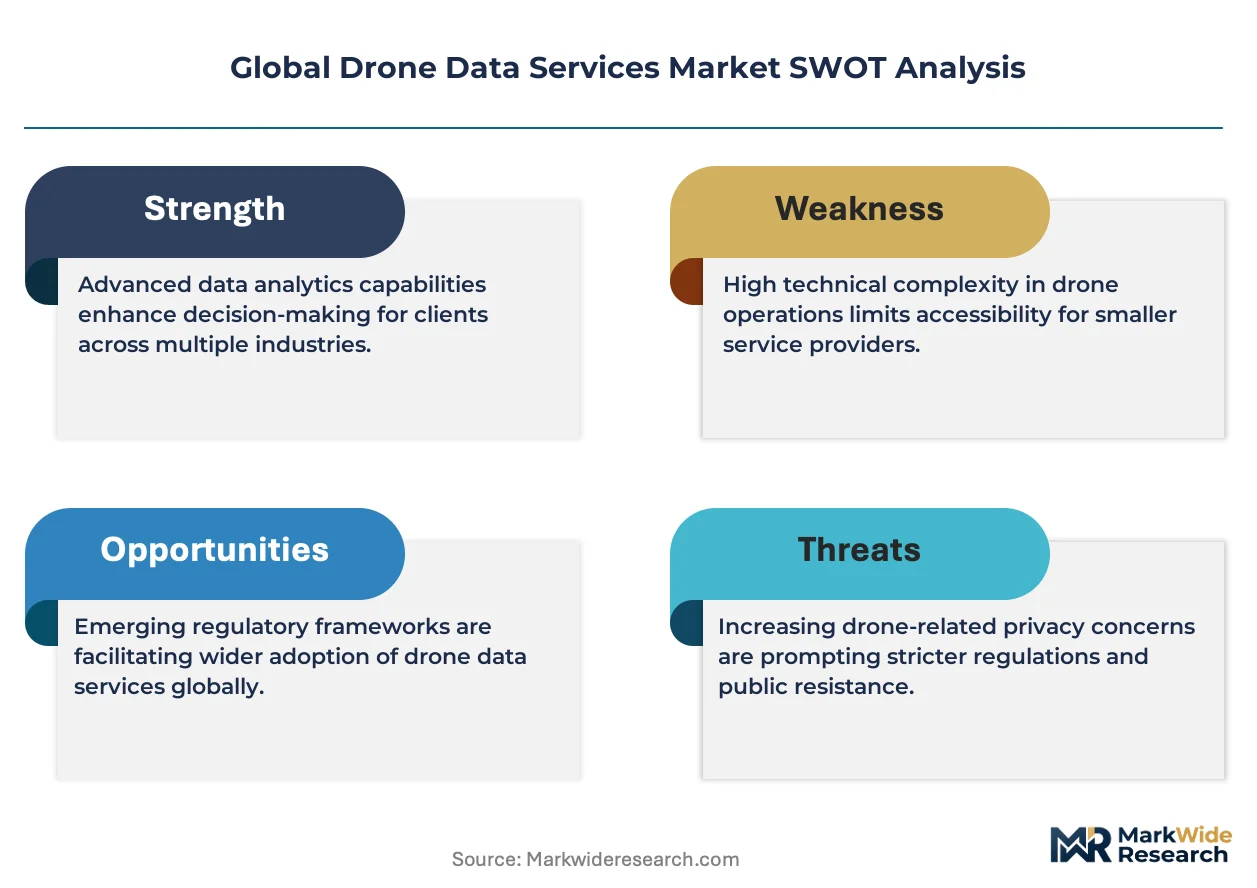
Beyond-visual-line-of-sight certification corridors are compressing project timelines for infrastructure operators while fragmenting competitive positioning between cloud-native platforms and hardware-anchored service providers.
Growth Catalysts
- FAA Part 107 recurrent training mandates:Standardized pilot certification pipelines across United States aviation academies are expanding qualified operator pools for commercial mapping contracts.
- Digital twin refresh cycles:Utilities and mining firms in Australia now mandate annual geospatial updates, creating recurring revenue anchors for survey-grade data providers.
- Sub-centimeter ground sample distance sensors:Advancements in photogrammetric camera arrays are enabling volumetric measurement precision previously requiring terrestrial lidar deployment.
Market Restraints
- Sensor hardware cost volatility:Specialized multispectral and thermal imaging payloads face supply concentration risks from German and Japanese optical component manufacturers.
- Data sovereignty friction:China's GB standards for flight logging and cross-border data transfer create operational complexity for multinational infrastructure operators.
- Manual survey substitution ceiling:Dense urban environments with complex airspace layering limit full automation potential, preserving episodic human inspection for high-risk assets.
Strategic Opportunities
- India's agricultural digitization:The country's PLI scheme for drone manufacturing and state-level crop insurance mandates are opening precision analytics contracts for domestic and foreign service providers.
- EU Green Deal infrastructure monitoring:CSRD reporting requirements for environmental asset condition are mandating aerial inspection protocols for renewable energy installations across member states.
- Edge computing convergence:Onboard AI inference chips paired with 5G network slicing are enabling real-time anomaly detection without full imagery upload, reducing latency for emergency response applications.
Industry Challenges
- BVLOS certification timeline compression:Operators in Germany and France face 12-18 month waiver processing delays for automated fleet expansion beyond pilot visual range.
- Geospatial data fusion complexity:Integration of drone-captured point clouds with legacy CAD and BIM systems requires specialized middleware development that strains mid-market survey firm technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Data Services Market |
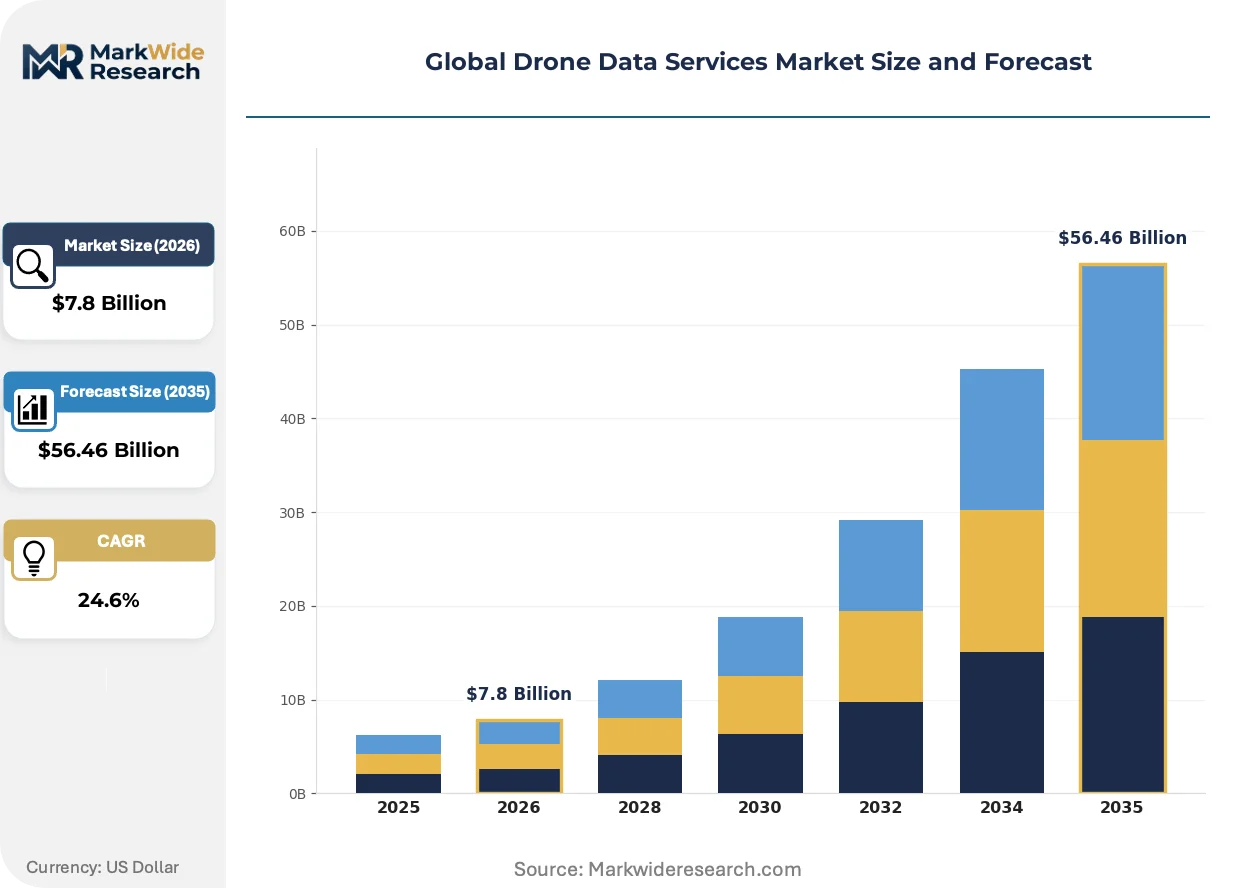
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $56.46 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Image Processing, Data Storage, Mapping Services, Inspection Services Application: Agricultural Monitoring, Construction Surveying, Environmental Assessment, Infrastructure Inspection, Emergency Response End User: Survey Firms, Utility Providers, Environmental Agencies, Agriculture Enterprises, Public Safety Organizations Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services |
| Companies Covered | DroneDeploy, PrecisionHawk, Pix4D SA, Cyberhawk, Terra Drone Corporation, Skycatch, Inc., Sentera, Dronecloud, Agribotix.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Data Services Market Shifts & Advancements
Real-time edge inference and automated flight path optimization are compressing the gap between data capture and actionable intelligence, reshaping competitive differentiation around latency rather than resolution alone.
Photogrammetry software executing dense point cloud generation directly on drone-mounted GPUs is displacing ground-station post-processing workflows for time-critical infrastructure inspections. Emergency response agencies in Japan and seismic monitoring operators in California are deploying these systems for immediate damage assessment following natural events. The structural consequence is a margin squeeze on traditional cloud-based processing services that require hours for equivalent outputs.
EASA's specific operational category framework for automated flights above 120 meters is forcing infrastructure operators to redesign pilot qualification programs across European Union member states. Grid operators in Spain and Nordic wind farm managers must now document human-machine interface competency for remote supervision roles. The segment most affected is long-linear asset inspection, where operators are consolidating vendor relationships to reduce compliance documentation burden.
Subscription-based fleet management platforms are unbundling hardware ownership from data service delivery among mid-market agricultural cooperatives. Brazilian soybean growers and Australian pastoral leaseholders now access seasonal analytics through per-hectare pricing rather than capital-intensive drone procurement. This shift is most visible in emerging agricultural economies where credit constraints and seasonal cash flow patterns favor operational expenditure models over equipment finance.
Global Drone Data Services Market Segmentation
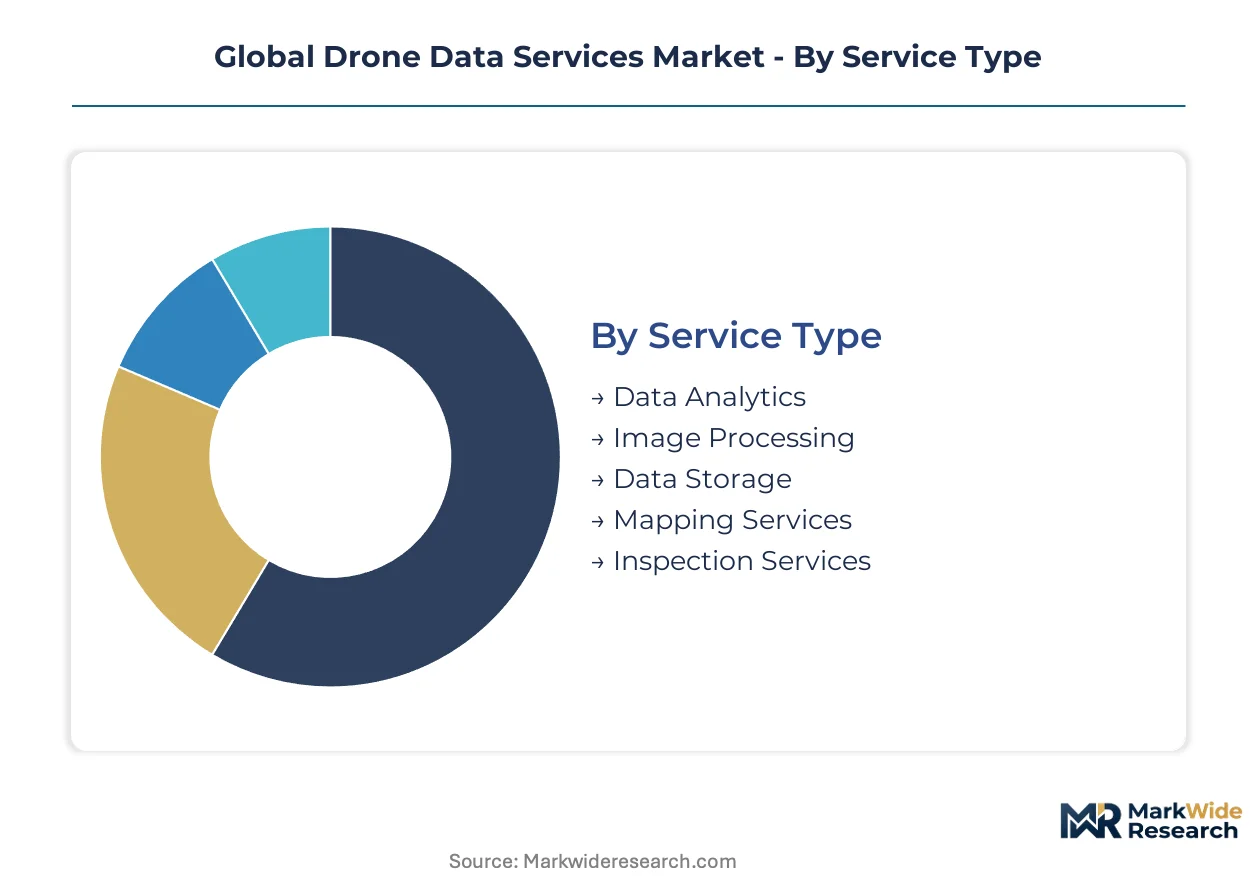
Drone data services fragment across operational models, end-user sophistication, and data sovereignty requirements. Each segmentation axis reveals distinct margin structures and competitive barriers that reshape vendor positioning across infrastructure, agriculture, and public safety verticals.
Service Type:
Substitution pressure concentrates on commoditized image processing as automated photogrammetry tools displace manual post-production workflows, while specialized analytics retain pricing power through proprietary algorithmic IP.
- Mapping Services:Orthomosaic generation and point cloud densification for volumetric measurement dominate contract value among mining firms and utilities mandating digital twin refresh cycles. Australian mining operators and German grid managers now require sub-centimeter ground sample distances for quarterly asset updates.
- Inspection Services:Predictive maintenance contracts for linear infrastructure and renewable energy installations command premium pricing through recurring revenue structures. Nordic wind farm operators and Spanish solar utilities are shifting from episodic manual surveys to automated aerial monitoring protocols.
- Data Analytics:Crop health algorithms and anomaly detection models deliver specialized intelligence for agricultural cooperatives and environmental regulators.
- Image Processing:Dense point cloud generation and orthorectification workflows face compression from onboard GPU processing capabilities.
- Data Storage:Geospatial data lakes for multi-year asset histories attract compliance-driven procurement from regulated infrastructure sectors.
Mapping Services anchors the volume base while Inspection Services gains share at the steepest rate.
Application:
Cost tier differentiation separates high-frequency monitoring contracts from episodic survey engagements, with subscription models penetrating agricultural and environmental segments while capital-intensive infrastructure demands project-based procurement.
- Agricultural Monitoring:Precision analytics for crop health, irrigation optimization, and yield forecasting now deploy across Brazilian soybean operations and Australian pastoral leaseholders through per-hectare pricing models. India's PLI scheme for drone manufacturing accelerates domestic service provider expansion.
- Infrastructure Inspection:Linear asset monitoring for power transmission, pipelines, and transportation corridors commands the highest contract values through BVLOS-enabled automated flight programs. German and French operators face extended waiver timelines that consolidate vendor relationships.
- Construction Surveying:Progress monitoring and earthwork volumetrics for major civil projects require survey-grade accuracy and CAD-BIM integration middleware.
- Environmental Assessment:CSRD-mandated ecological monitoring drives aerial protocols for renewable energy installations across EU member states.
- Emergency Response:Real-time damage assessment for seismic events and natural disasters leverages edge-computing inference chips for immediate actionable intelligence.
Infrastructure Inspection captures the premium pricing tier while Agricultural Monitoring expands most quickly through operational expenditure adoption.
End User:
Customer type maturity determines procurement sophistication, with regulated utilities and environmental agencies mandating compliance documentation while agricultural cooperatives prioritize seasonal flexibility over technical specifications.
- Utility Providers:Grid operators and renewable energy asset managers mandate recurring digital twin updates and predictive maintenance integration with SCADA systems. Spanish and Nordic operators consolidate vendor panels to reduce BVLOS compliance documentation burden.
- Survey Firms:Mid-market geospatial service providers seek elastic compute for seasonal project surges and cloud-native photogrammetry platforms.
- Agriculture Enterprises:Large-scale cooperatives and pastoral leaseholders access analytics through subscription fleet management rather than capital-intensive hardware procurement.
- Environmental Agencies:Regulators enforcing CSRD and national environmental standards require auditable flight logging and data sovereignty compliance.
- Public Safety Organizations:Emergency response agencies in Japan and California deploy edge-enabled systems for immediate post-disaster assessment.
Utility Providers dominate contract value concentration while Agriculture Enterprises climb the fastest through pricing model innovation.
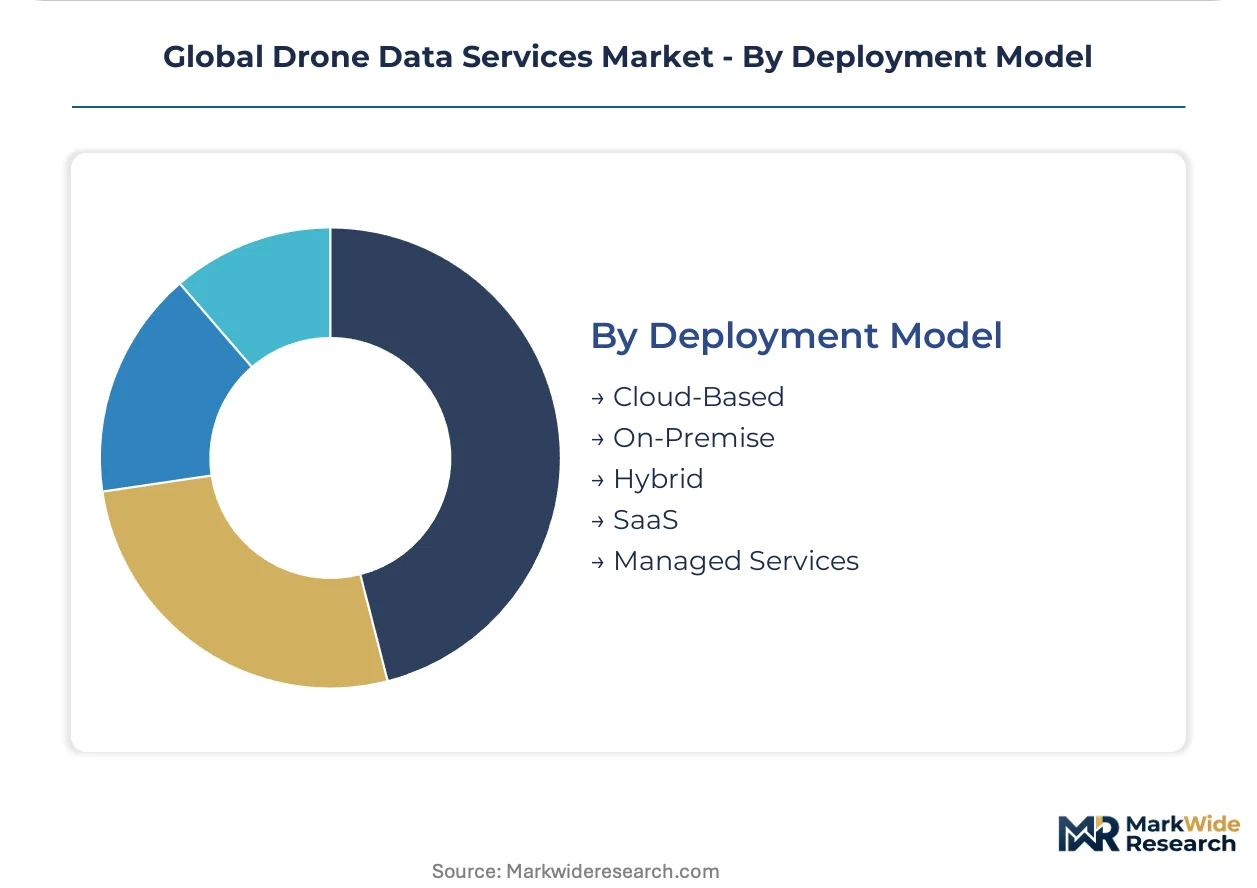
Deployment Model:
Supply concentration in cloud infrastructure creates vendor lock-in risks for mid-market survey firms, while hybrid architectures attract regulated sectors with data sovereignty requirements.
- Cloud-Based:Elastic compute for seasonal photogrammetry surges and collaborative project workflows dominates adoption among mid-market survey firms and agricultural cooperatives. AWS, Azure, and specialized geospatial clouds compete for workload hosting.
- Hybrid:Onboard GPU processing paired with selective cloud upload addresses latency-critical emergency response and data-sensitive infrastructure monitoring. 5G network slicing enables real-time anomaly detection without full imagery transfer.
- On-Premise:Air-gapped processing environments serve defense, critical infrastructure, and jurisdictions with strict cross-border data transfer restrictions.
- SaaS:Per-hectare and per-mile subscription pricing unbundles hardware ownership from analytics delivery in emerging agricultural economies.
- Managed Services:Turnkey flight operations with certified pilot provision and regulatory compliance handling attract enterprises lacking internal aviation expertise.
Cloud-Based deployment anchors current adoption while Hybrid architectures gain share at the steepest rate through edge-AI convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA's Part 107 framework anchors the United States as the regulatory template shaping pilot certification standards worldwide. EASA's open/specific/certified categories and China's CAAC GB standards create parallel compliance architectures across Europe and Asia-Pacific. Demand concentrates where beyond-visual-line-of-sight corridors and certified training pipelines achieve operational scale.
United States
Utility providers and mining firms mandate quarterly digital twin refresh cycles for distributed infrastructure assets. FAA Part 107 recurrent training mandates expand qualified operator pools through aviation academy partnerships. Texas and California host the densest concentrations of cloud-native photogrammetry platforms serving mid-market survey firms.
China
Domestic drone manufacturing scale and agricultural digitization programs drive service provider expansion. CAAC GB standards enforce manufacturing conformity and flight logging protocols for domestic operators and export markets. The Yangtze River Delta cluster anchors precision analytics contracts for state-backed crop insurance mandates.
Germany
Grid operators and renewable energy asset managers consolidate vendor panels to reduce BVLOS compliance documentation burden. EASA's specific operational category framework forces redesign of pilot qualification programs for automated flights above 120 meters. Bavaria and North Rhine-Westphalia concentrate infrastructure inspection service providers facing 12-18 month waiver processing delays.
Australia
Mining operators mandate sub-centimeter ground sample distances for volumetric measurement and asset monitoring. National aviation regulations align with EASA frameworks for commercial flight permissions and certified operational categories. Western Australia and Queensland host the largest deployments of survey-grade data providers serving pastoral leaseholders.
India
State-level crop insurance mandates and the PLI scheme for drone manufacturing open precision analytics contracts for domestic and foreign service providers. BIS standards and DGFT regulations shape equipment import and operational compliance requirements. Maharashtra and Gujarat lead agricultural cooperative adoption of per-hectare subscription pricing models.
Global Drone Data Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-native platforms competing against hardware-anchored service providers for infrastructure and agriculture contracts. The market structure rewards proprietary algorithmic IP in specialized analytics while commoditizing standardized image processing workflows. Two strategic archetypes dominate: vertically integrated operators controlling sensor-to-delivery pipelines, and pure-play software platforms leveraging elastic compute for seasonal demand surges. Competitive moves concentrate on strategic partnerships for BVLOS certification access and portfolio diversification into predictive maintenance contracts.
Within the cloud-native platform tier, DroneDeploy and Skycatch, Inc. exemplify the software-first archetype unbundling hardware ownership from analytics delivery. Pix4D SA anchors the survey-grade accuracy segment serving construction and infrastructure clients with specialized photogrammetry tools. PrecisionHawk occupies a position bridging agricultural analytics specialization with recurring revenue structures for crop health monitoring contracts.
| Leading Market Players |
|---|
| DroneDeploy |
| PrecisionHawk |
| Pix4D SA |
| Cyberhawk |
| Terra Drone Corporation |
| Skycatch, Inc. |
| Sentera |
| Dronecloud |
| Agribotix.com |
| Others |
Supply & Pricing Matrix
Ninety-day sensor procurement cycles for German and Japanese optical components concentrate margin pressure on hardware-anchored service providers while amplifying pricing power for cloud-native platforms with elastic compute contracts. This lead-time structure rewards vendors who decouple sensor ownership from analytics delivery through subscription fleet management.
Pricing Analysis
United States-based inspection contracts command 40-60% premiums over equivalent Indian agricultural analytics due to FAA Part 107 certification requirements and BVLOS waiver scarcity. The dominant pricing model stratifies across premium survey-grade accuracy, standard photogrammetry processing, and economy image-only tiers. Price differentiation rests on certification level and sensor payload quality. Cost compression in the economy tier intensifies as onboard GPU processing displaces ground-station workflows. Agricultural cooperatives exhibit highest price sensitivity through per-hectare procurement, while utility providers accept premium rates for predictive maintenance integration.
Supply Chain Analysis
Strait of Malacca transit exposure for semiconductor components used in AI inference chips creates vulnerability for edge-computing drone manufacturers. Supply concentrates in China for airframe manufacturing, Germany for precision optics, and Japan for thermal imaging sensors. Raw material dependencies include rare earth magnets for motor assemblies, CMOS sensors for photogrammetry arrays, and lithium-ion cells for extended flight endurance. Single-source vulnerability concentrates in German optical component suppliers. Distribution runs through direct OEM relationships for enterprise fleets and regional distributor networks for agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and per-hectare analytics subscriptions expand faster than hardware sales. Recurring revenue layers now anchor enterprise valuations.
For Market Incumbents: Secure BVLOS certification corridors in Germany and France through consolidated vendor panels that reduce compliance documentation burden for grid operators. Deepen upstream control over sensor calibration workflows to defend margin position against cloud-native platforms displacing hardware-anchored providers. Lock in multi-year digital twin refresh contracts with Australian mining operators and Texas utility providers. For New Entrants and Emerging Players: FAA Part 107 fast-track partnerships with aviation academies open qualified operator pools for mid-market survey firms seeking elastic compute. India's state-level crop insurance mandates and PLI scheme for drone manufacturing create the most penetrable white space for precision analytics contracts. Target per-hectare subscription pricing models among Brazilian soybean cooperatives and Australian pastoral leaseholders facing capital constraints. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because predictive maintenance contracts for linear assets generate decade-long revenue visibility. Acquisition targets should display proprietary algorithmic IP in crop health or anomaly detection alongside established BVLOS waiver relationships. Watch FAA and EASA automated flight category expansions as the inflection signal for fleet-scale deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | FAA waiver acquisition in Texas and California compresses project timelines for infrastructure operators. |
| Edge Computing Integration | Onboard AI inference chips paired with 5G network slicing enable real-time anomaly detection for emergency response. |
| Subscription Fleet Management | Per-hectare pricing models penetrate Brazilian agricultural cooperatives facing seasonal cash flow constraints. |
| Backward Integration into Sensors | In-house production of photogrammetry arrays reduces dependency on German and Japanese optical suppliers. |
| Regulatory Partnership | EASA specific operational category compliance documentation consolidation reduces vendor burden for Nordic wind farm managers. |
Research Methodology
A spread of perspectives from certified drone pilots, utility asset managers, agricultural cooperative procurement leads, and photogrammetry software engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA Part 107 certification databases, EASA operational category filings, and customs records for drone component imports. Bottom-up triangulation across service provider contract values and top-down cross-checks against national aviation authority flight hour statistics anchored volume estimates.
Segmentation dimensions modeled include service type, application vertical, end-user sophistication tier, and deployment architecture across the projection horizon. CAGRs derived from fitted growth curves incorporating BVLOS regulatory expansion timelines, sensor cost trajectories, and cloud compute adoption patterns. Industry-specific forecast inputs encompass digital twin refresh cycle mandates from Australian mining operators and CSRD reporting requirements driving EU environmental inspection protocols.
Underlying assumptions cover sustained FAA and EASA regulatory harmonization, with deviation risk concentrated in sensor hardware cost volatility from optical component supply concentration. Practitioners should keep alternative scenarios live as China's GB standards for cross-border data transfer and India's PLI scheme implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Industrial Drones Market
UAV
Ultra Micro Drone Market
UAV
Europe Commercial Drones Market
UAV
UAV Payload Market
UAV
UAV Payload and Subsystems Market
UAV
Short-Range Delivery Drone Market
UAV
North America Drone Services Market
UAV
Portable Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Stratospheric Flying Drone Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Fixed Wing Military Drones Market
UAV
Multirotor Drones Market
UAV
Drone Powered Business Solutions Market
UAV
Drone Lens Market