
 Global Drone Light Shows Market | 2026-2036
Global Drone Light Shows Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Light Shows Market Foresight
A shortage of certified swarm pilots and FAA Part 107 remote operators is reorganizing talent pipelines across the industry. Intel Corporation leverages its semiconductor heritage to sustain proprietary flight-control chipsets that anchor large-scale synchronization. Verge Aero competes on domestic manufacturing scale, while EHang dominates regulatory relationships in China through early airworthiness certifications for passenger-grade autonomous platforms.
Drone light shows are coordinated aerial performances using GPS-navigated, LED-equipped unmanned aircraft that execute choreographed flight paths via swarm algorithms, typically operating at 2.5-4 watts per drone for visible night-sky illumination. The primary purpose is to replace pyrotechnics with reusable, programmable, and weather-adaptive visual spectacles for mass audiences. Multirotor drones lead fleet compositions due to hovering precision and rapid directional changes, while entertainment events command the largest application share as stadium openings and holiday celebrations standardize drone substitutions for fireworks. Show design and programming services capture premium margins because proprietary choreography software creates recurring licensing revenue and client lock-in.
FAA Part 107 waivers and EASA open-category frameworks govern night operations, beyond-visual-line-of-sight flights, and crowd proximity across the United States and European Union, directly constraining fleet size per show and pilot-to-drone ratios. China's CAAC and NMPA coordinate airspace deconfliction with military corridors, creating location-specific scheduling advantages for domestic operators like EHang. Stakeholders must monitor evolving counter-drone and electromagnetic interference standards as municipal authorities weigh spectacle permits against airspace security protocols.
Market Dynamics
Fleet synchronization algorithms and waiver-based operational frameworks are compressing pilot-to-drone ratios while expanding permissible show scales across municipal airspace.
Growth Catalysts
- FAA Part 107 night waivers:The United States regulator permits expanded after-dark operations, unlocking stadium and festival bookings previously restricted to pyrotechnics.
- LED efficiency gains:Solid-state illumination at 2.5-4 watts per unit extends flight endurance, reducing battery swap frequency and ground crew overhead.
- Entertainment events in the United Arab Emirates:Cultural festivals and national celebrations in Dubai and Riyadh are standardizing drone substitutions for fireworks displays.
Market Restraints
- Lithium-polymer battery supply:Cell production concentrates in China, exposing operators to input cost volatility and logistics bottlenecks.
- Certified swarm pilot scarcity:Training pipelines for FAA Part 107 remote operators lag fleet expansion timelines, constraining show frequency.
- Weather dependency:Precipitation and wind thresholds above 25 knots force cancellations, degrading revenue predictability for outdoor events.
Strategic Opportunities
- Germany's municipal procurement:City authorities in Berlin and Munich are integrating drone displays into national holiday programming with multi-year service contracts.
- Real-time kinetic advertising:Brand-sponsored choreography over commercial districts offers recurring licensing revenue beyond one-off entertainment bookings.
- EASA open-category harmonization:Simplified cross-border approvals enable fleet redeployment between EU member states without jurisdiction-specific recertification.
Industry Challenges
- Electromagnetic interference mitigation:Operators must coordinate with military and civilian radar systems, adding airspace deconfliction complexity.
- Proprietary software lock-in:Choreography platforms create switching costs that fragment vendor-client relationships and complicate multi-operator collaborations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Light Shows Market |
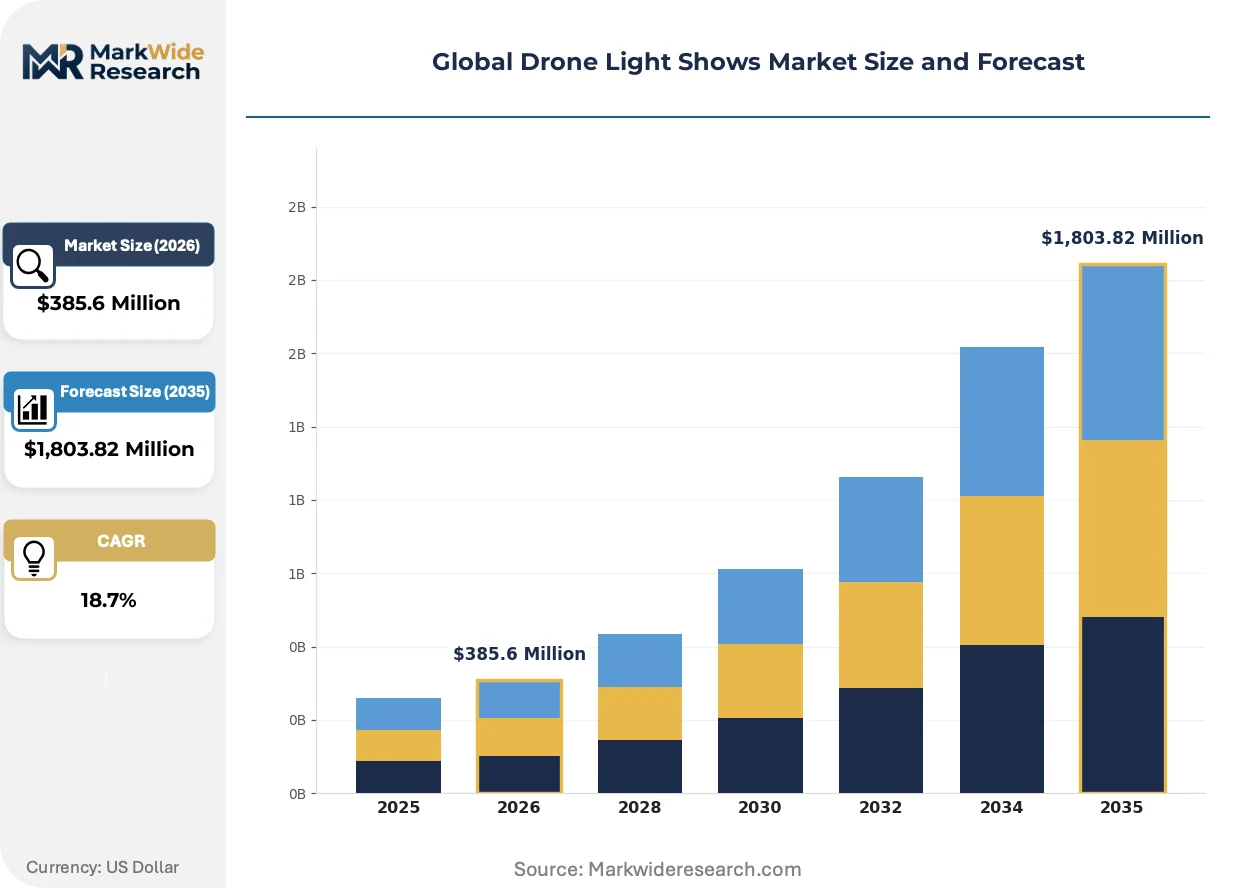
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Multirotor Drones, Fixed-wing Drones, Hybrid Drones, Nano Drones, Micro Drones Application: Entertainment Events, Advertising Campaigns, Sports Events, Cultural Festivals, Corporate Gatherings End User: Event Management Companies, Marketing Agencies, Entertainment Parks, Theme Attractions, Public Displays Service Type: Show Design & Programming, Drone Fleet Operation, Maintenance & Repair, Equipment Rental, Technical Consultancy |
| Companies Covered | Intel Corporation, Verge Aero, Dronisos, CollMot Entertainment, EHang, Sky Elements, Firefly Drone Shows, Great Lakes Drone Company, Damoda Aerial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Light Shows Market Shifts & Advancements
Swarm intelligence architectures and regulatory automation are compressing deployment timelines while fragmenting competitive advantage between hardware manufacturers and choreography software providers.
RTK-GPS positioning modules are displacing standard GPS receivers in premium fleet configurations. Stadium operators and luxury event producers in the United States are adopting centimeter-accuracy navigation for tighter formation geometry. This precision is displacing pyrotechnic proximity exemptions as the primary spectacle differentiator, forcing fireworks contractors into defensive positioning.
EASA's open-category drone rules are standardizing operational compliance across EU member states. The framework reduces pilot certification burdens for sub-25kg platforms while mandating remote identification for all night operations. German and French operators are responding by consolidating fleet procurement around EU-manufactured hardware to streamline conformity assessment.
Subscription-based choreography licensing is restructuring buyer relationships in the entertainment vertical. Event producers in China are shifting from per-show design fees to annual software access models. This rotation is most visible in Shenzhen and Shanghai, where municipal authorities package drone displays into recurring cultural programming budgets rather than discretionary procurement cycles.
Global Drone Light Shows Market Segmentation
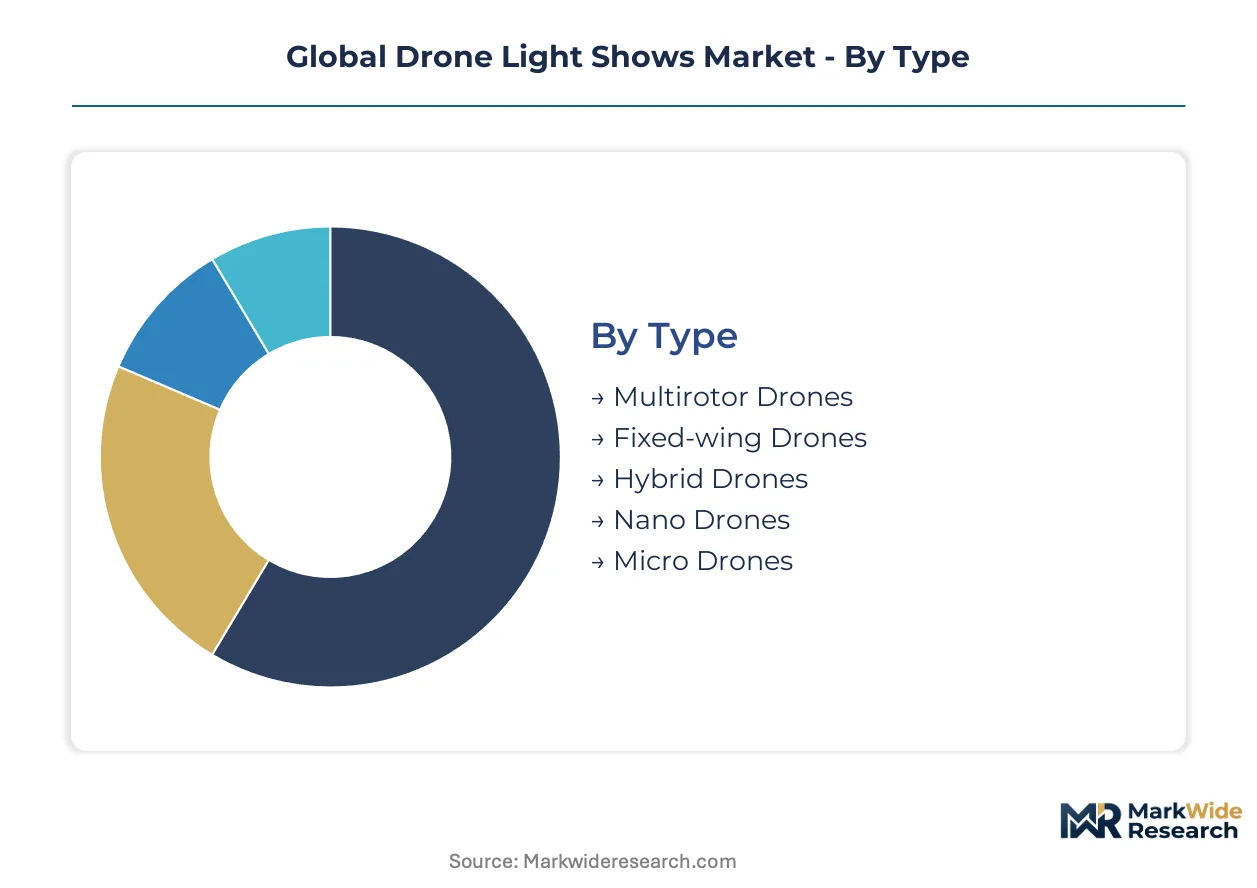
Drone light show segmentation reveals how hardware specifications, client procurement patterns, and service bundling create distinct margin profiles. Each category carries unique substitution pressures from pyrotechnics, projection mapping, and traditional aerial photography.
Type:
Multirotor platforms face acute substitution pressure from ground-based LED arrays and laser projection systems at lower altitudes.
- Multirotor Drones:Quad- and hexacopter configurations dominate fleet compositions due to hovering precision and rapid directional changes. Stadium openings in the United States and cultural festivals in the United Arab Emirates concentrate demand here, driven by FAA Part 107 night waiver accessibility.
- Fixed-wing Drones:Winged platforms sacrifice hovering capability for extended endurance and larger payload capacity. Survey and mapping operators in Germany repurpose these units for linear display formations over rivers and highways where sustained flight paths reduce battery swap logistics.
- Hybrid Drones:Tilt-rotor designs merge vertical takeoff with efficient cruise flight. Chinese operators under CAAC jurisdiction deploy these for mixed-terrain shows spanning urban cores to suburban venues.
- Nano Drones:Sub-250gram platforms exploit EASA open-category exemptions for simplified compliance. Indoor entertainment venues in France and the Netherlands adopt these for confined-space choreography without pilot certification burdens.
- Micro Drones:Mid-size units bridge nano portability and multirotor performance. Theme attractions in Japan integrate these for repeatable daily shows with reduced ground crew requirements.
Multirotor drones anchor the volume base while nano drones gain share at the steepest rate.
Application:
Cost tier stratification separates one-off spectacle bookings from recurring municipal programming contracts with divergent margin structures.
- Entertainment Events:Stadium openings, product launches, and holiday celebrations constitute the largest revenue pool. Saudi Arabia's Riyadh Season and Dubai's New Year displays standardize drone substitutions for fireworks, locking in multi-year procurement frameworks.
- Advertising Campaigns:Brand-sponsored kinetic choreography over commercial districts commands premium per-minute rates. Real-time logo morphing and product visualization in Shanghai and Shenzhen attract automotive and consumer electronics advertisers.
- Sports Events:Pre-game and halftime spectacles at football and cricket venues require rapid deployment windows. Indian Premier League franchises in Mumbai and Chennai are piloting drone integrations alongside traditional pyrotechnic sequences.
- Cultural Festivals:National day celebrations and heritage commemorations prioritize patriotic iconography. German Unity Day programming in Berlin and Munich incorporates drone formations into multi-decade tradition cycles.
- Corporate Gatherings:Annual meetings and shareholder events utilize smaller fleets for indoor or courtyard displays. Swiss pharmaceutical and banking conferences in Zurich and Geneva lead adoption of privacy-compliant, closed-airspace performances.
Entertainment events generate the deepest revenue base while advertising campaigns expand most quickly.
End User:
Customer type fragmentation reflects divergent technical capabilities, with sophisticated buyers internalizing fleet operations and smaller players outsourcing entirely.
- Event Management Companies:Full-service producers bundle drone shows into comprehensive festival logistics. These buyers in the United States and Germany increasingly require in-house FAA Part 107 certified pilots to reduce vendor dependency.
- Marketing Agencies:Creative shops subcontract technical execution while retaining creative control. Campaigns for luxury automotive and fashion brands in Milan and Paris drive demand for rapid-concept-to-airborne timelines.
- Entertainment Parks:Fixed-venue operators amortize fleet costs across nightly programming. Orlando and Anaheim clusters in the United States deploy drones as permanent fireworks replacements to reduce insurance and environmental compliance costs.
- Theme Attractions:Location-based entertainment venues integrate drones into narrative-driven experiences. Japanese operators under METI guidelines pioneer indoor-outdoor hybrid shows with synchronized audio and ground effects.
- Public Displays:Government and municipal authorities fund civic spectacles through cultural budgets. Australia's Sydney New Year's Eve and Melbourne White Night festivals anchor public procurement with taxpayer-funded programming.
Event management companies dominate current procurement volume while entertainment parks demonstrate the steepest fleet internalization trajectory.
Service Type:
Supply concentration in choreography software creates margin capture asymmetry between design licensors and hardware operators.
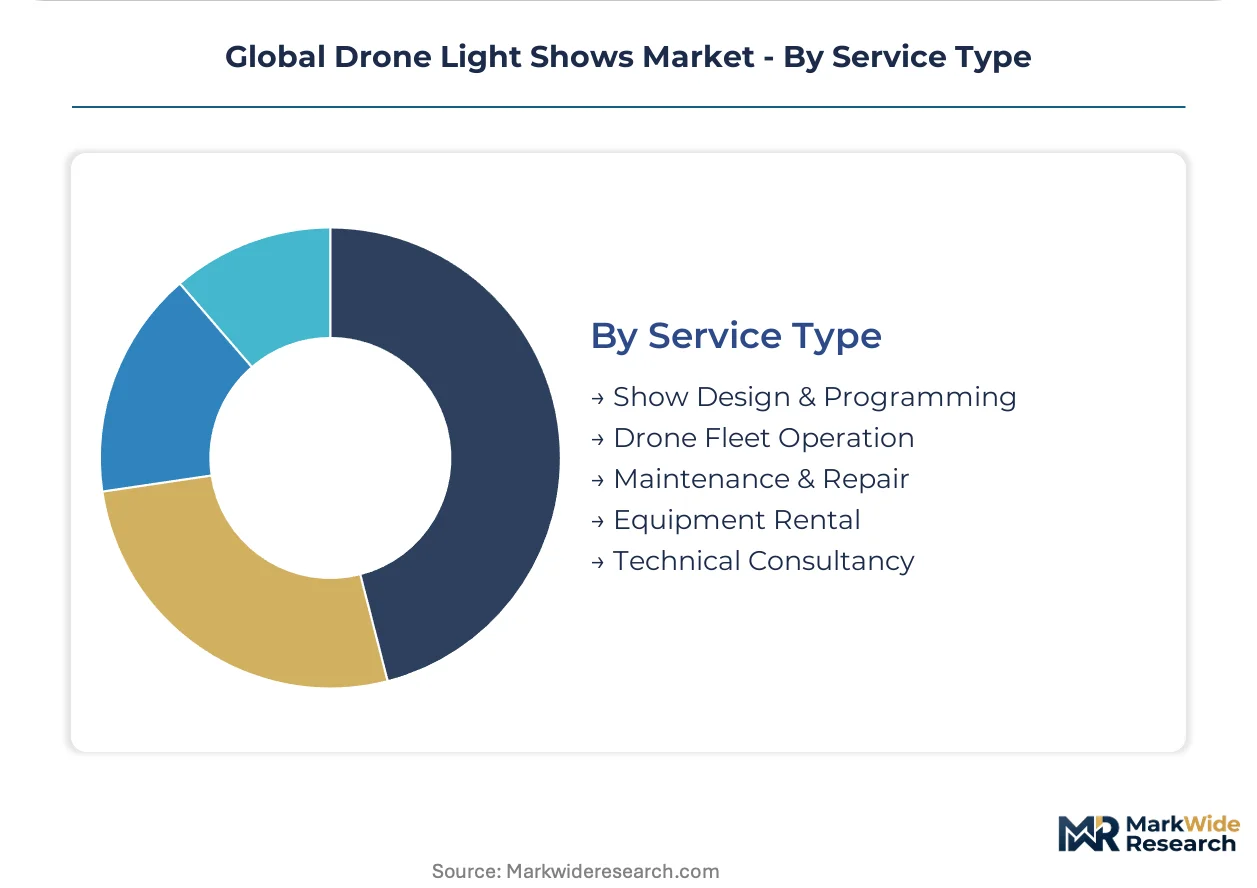
- Show Design & Programming:Proprietary swarm algorithms and animation tools generate recurring licensing revenue. Shenzhen-based studios are transitioning Chinese municipal clients from per-show fees to annual subscription access.
- Drone Fleet Operation:Turnkey execution services include pilot teams, ground control, and airspace coordination. Operators in the United States leverage FAA Part 107 waiver portfolios as competitive moats against unlicensed competitors.
- Maintenance & Repair:Post-show inspection, component replacement, and firmware updates sustain fleet airworthiness. European operators under EASA remote identification mandates require documented maintenance trails for night operation permits.
- Equipment Rental:Dry-hire provision of drone hardware without operational crew. Australian and Canadian markets show rising demand from film production companies seeking temporary fleet augmentation for cinematic sequences.
- Technical Consultancy:Advisory services covering regulatory navigation, insurance placement, and risk assessment. Emerging operators in Brazil and South Korea engage consultants to accelerate CAAC and ANAC compliance pathways.
Show design and programming commands the highest margin concentration while fleet operation delivers the steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 107 waivers anchor operational expansion in the United States, while EASA frameworks and CAAC coordination reshape compliance architectures across Europe and China. Fleet deployments concentrate where regulators permit night operations, beyond-visual-line-of-sight flights, and reduced pilot-to-drone ratios.
United States
Stadium openings and festival bookings in Las Vegas and Orlando drive fleet utilization. FAA Part 107 night waivers unlock after-dark spectacles previously restricted to pyrotechnics. Intel Corporation and Verge Aero anchor operations in California and Texas clusters.
Germany
Berlin and Munich municipal authorities integrate drone displays into Unity Day programming with multi-year service contracts. EASA open-category rules standardize cross-border approvals for sub-25kg platforms. Fleet procurement consolidates around EU-manufactured hardware to streamline conformity assessment.
China
Shenzhen and Shanghai municipal clients shift from per-show fees to annual software subscription models. CAAC and NMPA coordinate airspace deconfliction with military corridors, creating location-specific scheduling advantages. EHang leverages early airworthiness certifications for passenger-grade autonomous platforms.
United Arab Emirates
Dubai's New Year displays and Riyadh Season standardize drone substitutions for fireworks, locking in multi-year procurement frameworks. MOHAP and national aviation regulators facilitate rapid permit processing for cultural festivals. Fleet deployments concentrate along Dubai Marina and Jeddah waterfront corridors.
Australia
Sydney New Year's Eve and Melbourne White Night festivals anchor taxpayer-funded public procurement. The country's national aviation regulator mandates remote identification for all night operations. Local operators build documented maintenance trails to sustain permit eligibility.
Global Drone Light Shows Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with semiconductor heritage and domestic manufacturing scale serving as primary differentiation vectors. The upper tier captures premium margins through proprietary flight-control chipsets and choreography software licensing, while mid-tier operators compete on waiver portfolios and fleet utilization rates. Strategic moves concentrate on regulatory certification accumulation and geographic expansion through municipal contract capture.
Within the integrated technology tier, Intel Corporation exemplifies semiconductor-to-spectacle vertical positioning, while Verge Aero occupies a position emphasizing domestic manufacturing scale. EHang anchors the regulatory-relationship archetype in China through early airworthiness certifications. These three entities represent distinct competitive vectors: chipset control, production scale, and regulatory pre-emption.
| Leading Market Players |
|---|
| Intel Corporation |
| Verge Aero |
| Dronisos |
| CollMot Entertainment |
| EHang |
| Sky Elements |
| Firefly Drone Shows |
| Great Lakes Drone Company |
| Damoda Aerial |
| Others |
Supply & Pricing Matrix
LED module substitution for traditional pyrotechnic payloads is simultaneously redrawing component sourcing maps and compressing per-show cost structures across operator tiers. This input shift concentrates procurement leverage with semiconductor foundries in Taiwan and South Korea while eroding legacy fireworks contractors' volume-based pricing power.
Pricing Analysis
Geographic price spreads between North American and Chinese operators exceed three-to-one for equivalent fleet-hour rates, reflecting FAA Part 107 compliance overhead and domestic manufacturing premiums. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification requirements and show complexity, with municipal authorities in Germany and Australia exhibiting lowest price sensitivity due to multi-year programming commitments. Cost compression in the standard tier is intensifying because Chinese operators undercut on hardware depreciation models. Advertising campaign buyers in Shanghai and Shenzhen demonstrate highest price elasticity, while entertainment parks in the United States accept premium positioning for nightly-repeat reliability.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time battery procurement for festival operators and strategic stockpiling of RTK-GPS modules by permanent-venue installations. Component supply concentrates in China for lithium-polymer cells, Taiwan for flight-control chipsets, and Germany for precision navigation hardware. Raw material dependencies span cobalt cathode chemistry, rare-earth magnets for brushless motors, and aluminum airframe extrusions. Single-source vulnerability in Chinese cell production exposes operators to logistics chokepoints at Shenzhen port. Distribution runs through direct manufacturer relationships for fleet-scale buyers and specialized AV distributors for smaller event producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
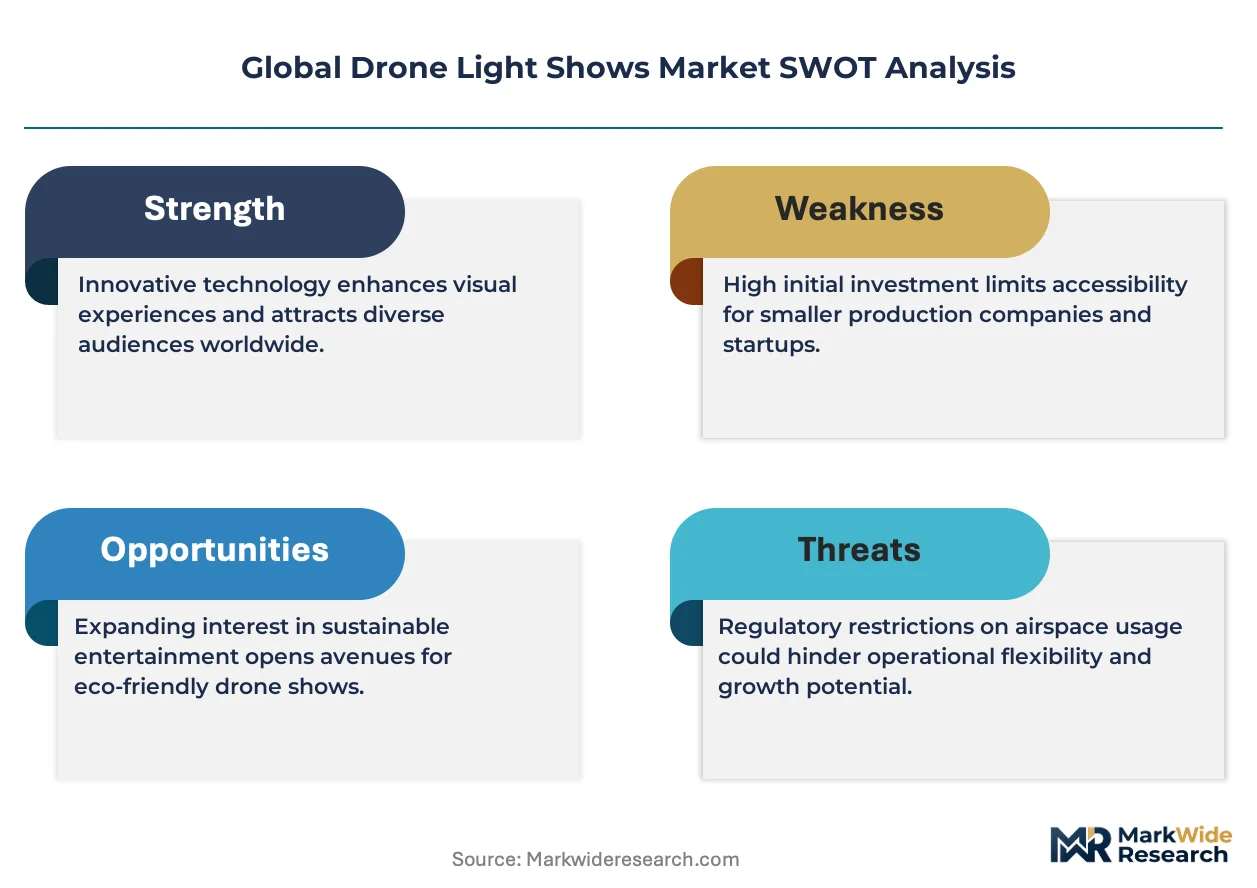
Fragmentation opportunity emerges as municipal procurement shifts from discretionary spectacle budgets to recurring cultural infrastructure line items, creating niches for specialized operators between integrated technology giants and regional fireworks contractors.
For Market Incumbents: Shield proprietary choreography software margins through subscription licensing lock-in against open-source swarm algorithm alternatives. Accumulate FAA Part 107 waiver portfolios as defensive moats against unlicensed competitors entering stadium and festival verticals. Deepen backward integration into flight-control chipset design to sustain hardware-software margin capture. For New Entrants and Emerging Players: Real-time kinetic advertising creative services represent the most penetrable white-space where incumbents under-serve brand marketers seeking rapid-concept-to-airborne timelines. Target mid-size automotive and consumer electronics advertisers in Milan and Paris with campaign-specific choreography subscriptions rather than fleet ownership. Pursue EASA open-category compliance arbitrage for cross-border EU fleet redeployment without jurisdiction-specific recertification. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertically integrated mid-cap specialists with waiver portfolios and municipal contract backlogs. Long-term viability hinges on regulatory certification accumulation rather than pure hardware scale. Target acquisition profiles center on operators holding multi-year service contracts with German municipal authorities or UAE cultural festival organizers. Watch FAA Part 107 night waiver processing velocity as inflection indicator for US market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Choreography Software Licensing | Recurring revenue streams from Shenzhen studios transition municipal clients to subscription models. |
| FAA Part 107 Waiver Accumulation | Regulatory moats protect US operators against unlicensed competitors in stadium verticals. |
| RTK-GPS Module Integration | Centimeter-accuracy navigation displaces pyrotechnic proximity exemptions as primary spectacle differentiator. |
| EASA Open-Category Harmonization | Simplified cross-border approvals enable fleet redeployment between EU member states without recertification. |
| Lithium-Polymer Supply Diversification | Reduced dependency on Chinese cell production mitigates input cost volatility and logistics bottlenecks. |
Research Methodology
The analysis maps multirotor fleet operators, choreography software licensors, and municipal procurement authorities, each validated through show producers, FAA Part 107 certified pilots, airspace coordination specialists, and festival logistics directors. Primary interviews with these stakeholders combined with secondary validation against FAA waiver databases, EASA regulatory filings, CAAC airworthiness certifications, and municipal budget disclosures. Bottom-up fleet deployment counts triangulate with top-down entertainment industry expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models segmentation by drone type, application vertical, end-user category, and service layer, with additional dimensioning by regulatory jurisdiction cluster. CAGRs derive from fleet expansion trajectories, waiver approval velocities, and substitution rates from pyrotechnics. Industry-specific forecast inputs include LED efficiency improvement curves and lithium-polymer cell cost decline assumptions.
Forecasts assume regulatory continuity in FAA Part 107, EASA open-category, and CAAC airworthiness regimes; material policy shifts would require re-modeling. Revision becomes warranted when electromagnetic interference standards or counter-drone protocols cross implementation thresholds that restrict permissible fleet densities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Payload Market
UAV
UAV Payload and Subsystems Market
UAV
Rc Helicopter Market
UAV
UAV Simulator Software Market
UAV
Drone-In-A-Box Market
UAV
Drone Flight Controller System Market
UAV
Electric Glider Market
UAV
Drone Inspection Service Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Drone Defense System Market
UAV
United States Drone Services Market
UAV
Drone-As-A-Service Market
UAV
Enterprise Drone Management Solutions Market
UAV
Stratospheric Flying Drone Market
UAV
Tethered Drones Market
UAV
Ultra Micro Drone Market