
 Asia-Pacific Drone Software Market | 2026-2036
Asia-Pacific Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drone Software Market Analytics
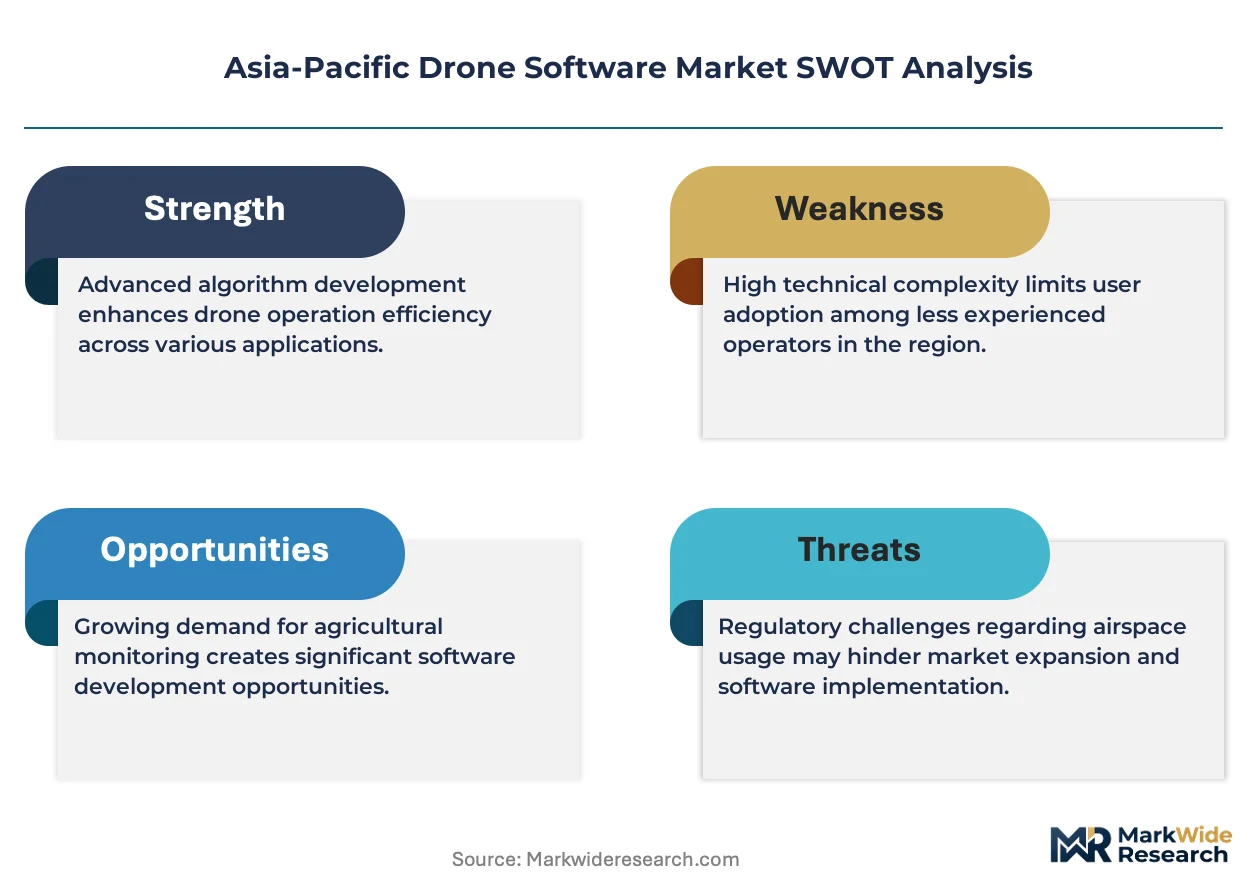
Platform licensing revenue is reconfiguring margin pools away from perpetual hardware sales toward recurring software subscriptions. SZ DJI Technology Co., Ltd. dominates flight control firmware ecosystems across East Asian commercial fleets. DroneDeploy, Inc. leverages cloud-based analytics portals to sustain recurring revenue from construction and agriculture clients. Pix4D SA specializes in photogrammetry engines that anchor premium pricing for surveying workflows.
Asia-Pacific drone software encompasses embedded flight control algorithms, real-time kinematic positioning modules, and geospatial data processing stacks that coordinate autonomous navigation, sensor fusion, and mission planning for unmanned aerial vehicles. These systems typically integrate GPS-denied navigation protocols, machine vision pipelines, and mesh networking layers to enable precision agriculture, infrastructure inspection, and last-mile logistics coordination. Flight control software and data analysis software represent the most entrenched revenue pools, while edge computing deployment architectures are expanding fastest as latency-sensitive missions proliferate across remote mining and maritime patrol applications. Fleet management software occupies a narrower but higher-margin niche serving enterprise operators with multi-asset coordination requirements.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces airspace classification protocols that constrain autonomous flight altitudes and corridors, while Australia's Civil Aviation Safety Administration mandates remote operator certification tiers that shape software compliance requirements for commercial deployments. China's Civil Aviation Administration issues unmanned aerial system operation certificates that gate market access for foreign software vendors. Stakeholders must monitor evolving beyond-visual-line-of-sight regulatory harmonization across Association of Southeast Asian Nations member states to anticipate certification reciprocity and cross-border service expansion.
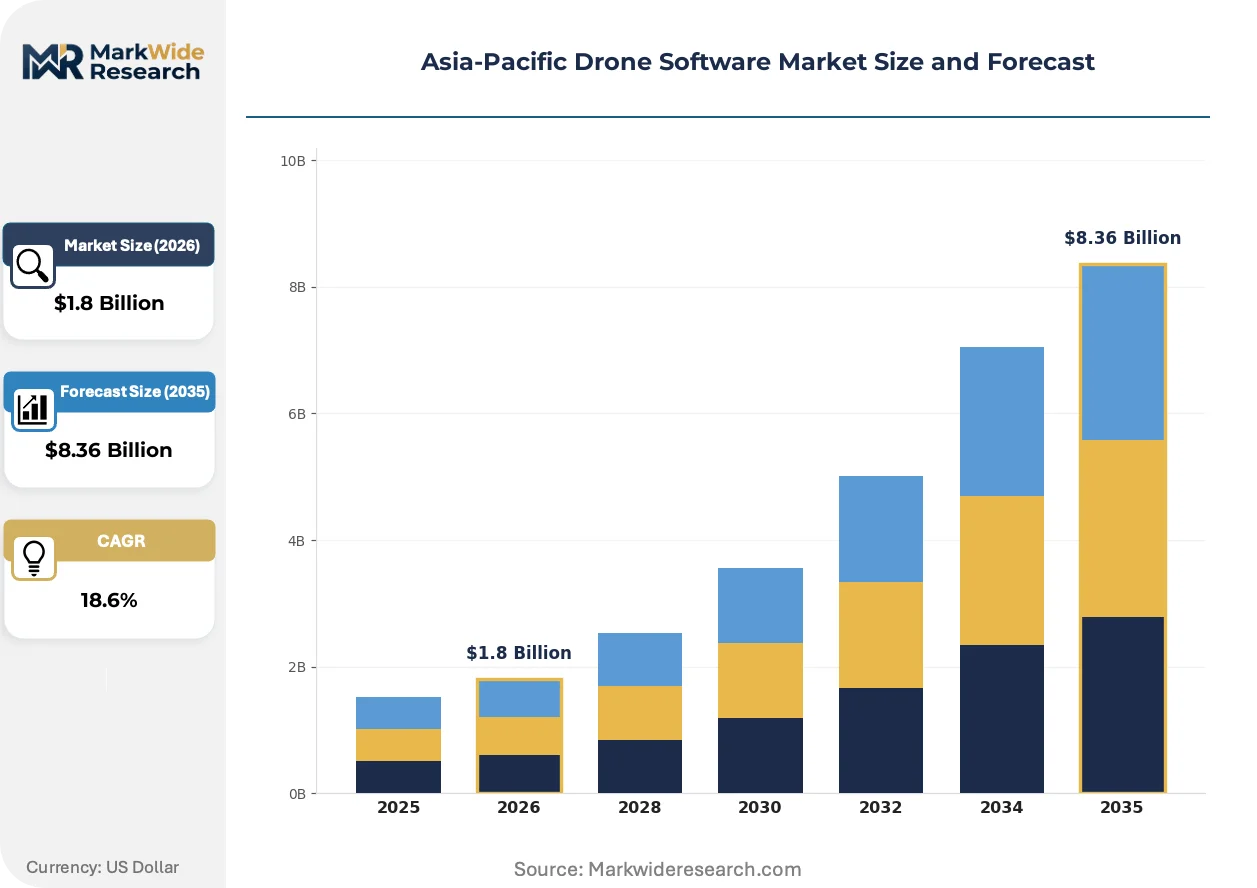
Market Dynamics
Platform licensing revenue is reconfiguring margin pools away from perpetual hardware sales toward recurring software subscriptions, forcing incumbents to rebuild customer lifetime value models around telemetry data and fleet orchestration services.
Growth Catalysts
- Beyond-visual-line-of-sight permissions:Japan's Civil Aeronautics Act amendments are streamlining BVLOS corridor approvals for commercial logistics and infrastructure inspection missions.
- Precision agriculture:Australian cotton and wheat operations are expanding autonomous spraying and crop monitoring deployments across Queensland and New South Wales.
- Edge computing architectures:Latency-sensitive mining and maritime patrol applications in Indonesia and the Philippines are driving embedded AI inference module adoption.
Market Restraints
- Semiconductor supply concentration:Flight control system-on-chip fabrication depends heavily on Taiwan and South Korean foundry capacity, creating single-source vulnerability.
- Regulatory fragmentation:Association of Southeast Asian Nations member states maintain non-harmonized airspace classification protocols that complicate cross-border fleet operations.
- GNSS spoofing vulnerability:GPS-denied navigation fallback systems add cost and complexity to mission-critical deployments in contested electromagnetic environments.
Strategic Opportunities
- Vietnam and Thailand logistics corridors:Underpenetrated last-mile delivery networks present greenfield deployment potential for autonomous cargo drone services.
- Digital twin convergence:Photogrammetry engines are hybridizing with building information modeling workflows to anchor premium pricing for smart city infrastructure monitoring.
- India's PLI scheme:Production-linked incentives for drone manufacturing are creating captive demand for domestically hosted software stacks and data sovereignty compliance.
Industry Challenges
- RTK positioning specialist scarcity:Real-time kinematic calibration engineers remain concentrated in Shenzhen and Tokyo, constraining fleet scaling in secondary markets.
- Type certification timelines:China's Civil Aviation Administration unmanned aerial system operation certificates require 12-18 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drone Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Software, Imaging Software, Data Analysis Software, Fleet Management Software End User: Agriculture, Construction, Logistics, Entertainment Deployment: Cloud-based, On-premise, Hybrid, Edge Computing Application: Aerial Surveying, Inspection, Mapping, Photography |
| Companies Covered | Kespry, Inc., Esri, Inc., SZ DJI Technology Co., Ltd., AgEagle Aerial Systems, Inc., Skydio, Inc., DroneDeploy, Inc., PrecisionHawk, Inc., DELAIR SAS, Pix4D SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drone Software Market Evolving Landscape
Autonomous navigation stacks are absorbing machine vision and mesh networking layers simultaneously, compressing the traditional hardware-software boundary and enabling new mission profiles in GPS-denied environments.
Edge-native flight control firmware is hybridizing convolutional neural network inference with traditional PID loops to enable real-time obstacle avoidance without ground station dependency. Australian mining operators in Western Australia's Pilbara region are deploying these systems for autonomous haul road inspection at night. The convergence is compressing sensor payload requirements and displacing heavier LiDAR configurations in cost-sensitive commercial segments.
China's Civil Aviation Administration is mandating remote identification broadcast protocols for all commercial unmanned aerial systems above 250 grams, effective across all operation certificates. This forces software vendors to embed standardized telemetry modules that broadcast position, altitude, and operator registration to ground monitoring stations. Agricultural and surveying fleets in Guangdong and Jiangsu provinces are retrofitting legacy hardware to maintain compliance.
Enterprise buyers in construction and energy verticals are unbundling perpetual license purchases in favor of metered mission-based billing tied to acreage surveyed or infrastructure assets inspected. DroneDeploy and Pix4D reseller channels in Australia and Japan are pivoting to consumption-based pricing to capture intermittent users. The shift is most visible in Southeast Asian markets where capital expenditure constraints favor operational expenditure treatment for regulatory compliance purposes.
Asia-Pacific Drone Software Market Segmentation
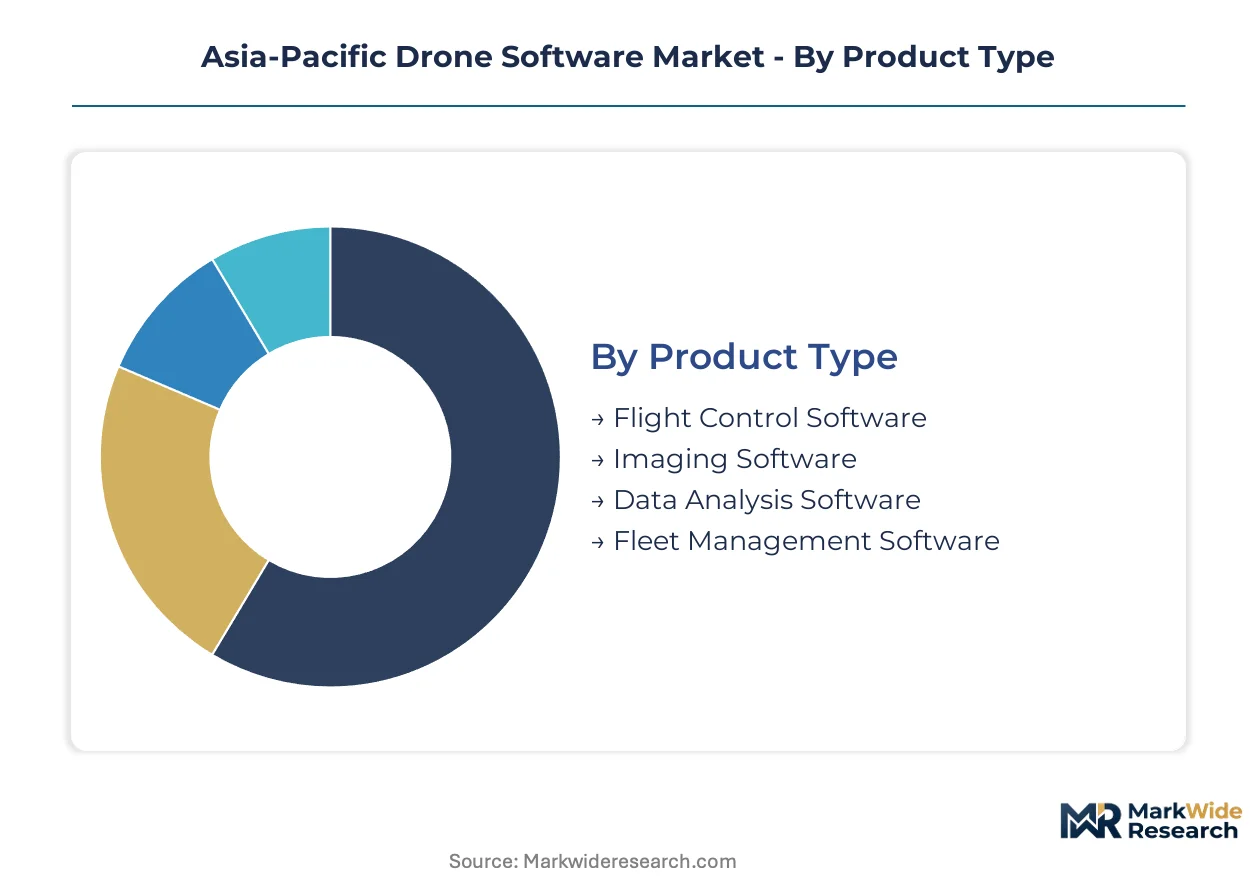
Drone software architectures in the Asia-Pacific region fragment across functional layers that determine integration complexity, recurring revenue potential, and regulatory compliance burdens. Vendors must align product roadmaps with the dominant deployment models and end-use concentrations emerging across Australia, Japan, China, and Southeast Asian corridors.
Product Type:
Flight control firmware through fleet orchestration platforms span a use-case spectrum from single-vehicle autonomy to multi-asset coordination across dispersed operations.
- Flight Control Software:Embedded algorithms govern real-time kinematic positioning, sensor fusion, and GPS-denied navigation fallback protocols. Australian cotton operations in Queensland deploy these systems for autonomous spraying missions where centimeter-level accuracy determines chemical application efficiency.
- Imaging Software:Real-time video processing pipelines compress bandwidth for telemetry transmission while enabling machine vision inference at the edge. Japanese infrastructure inspection fleets leverage these modules for crack detection on aging bridges and tunnels under METI-mandated maintenance schedules.
- Data Analysis Software:Photogrammetry engines convert aerial imagery into orthomosaics, digital elevation models, and volumetric measurements. Demand concentrates in China's construction and mining verticals around Shenzhen and Guangzhou.
- Fleet Management Software:Multi-vehicle coordination, maintenance scheduling, and compliance logging for enterprise operators with heterogeneous hardware deployments.
Established volume favors flight control firmware; emerging adoption favors fleet management platforms.
End User:
Customer archetypes range from capital-constrained agricultural cooperatives to engineering-procurement-construction conglomerates with dedicated unmanned systems divisions.
- Agriculture:Precision spraying, crop health monitoring, and yield prediction workflows dominate Australian wheat and cotton belts. Queensland and New South Wales operations are expanding autonomous fleet deployments under streamlined BVLOS permissions.
- Construction:Earthwork volumetrics, progress monitoring, and as-built documentation anchor recurring software subscriptions. Japanese contractors integrate photogrammetry outputs with building information modeling workflows.
- Logistics:Last-mile delivery route optimization and autonomous cargo coordination. Vietnam and Thailand present greenfield deployment potential for corridor-based drone delivery networks.
- Entertainment:Coordinated light shows and cinematography capture niche demand with high seasonality and project-based billing.
Construction and agriculture concentrate current revenue; logistics represents the steepest expansion trajectory as regulatory frameworks mature.
Deployment:
Infrastructure choices reflect latency tolerance, data sovereignty requirements, and connectivity constraints across archipelagic and remote mining geographies.
- Cloud-based:Centralized mission planning, data storage, and analytics accessible via browser portals. DroneDeploy and Pix4D reseller channels in Australia and Japan sustain recurring revenue through subscription models.
- On-premise:Local server installations for operators with sensitive infrastructure data or intermittent internet connectivity. Indonesian and Philippine mining operations favor this architecture for haul road inspection data.
- Hybrid:Edge preprocessing with cloud synchronization for bandwidth optimization. China's Civil Aviation Administration remote identification mandates are accelerating telemetry module standardization.
- Edge Computing:Embedded AI inference without ground station dependency. Western Australia's Pilbara region deploys these systems for autonomous night inspections where latency precludes cloud reliance.
Cloud architectures dominate commercial agriculture; edge-native deployments are climbing the fastest in mining and maritime patrol applications.
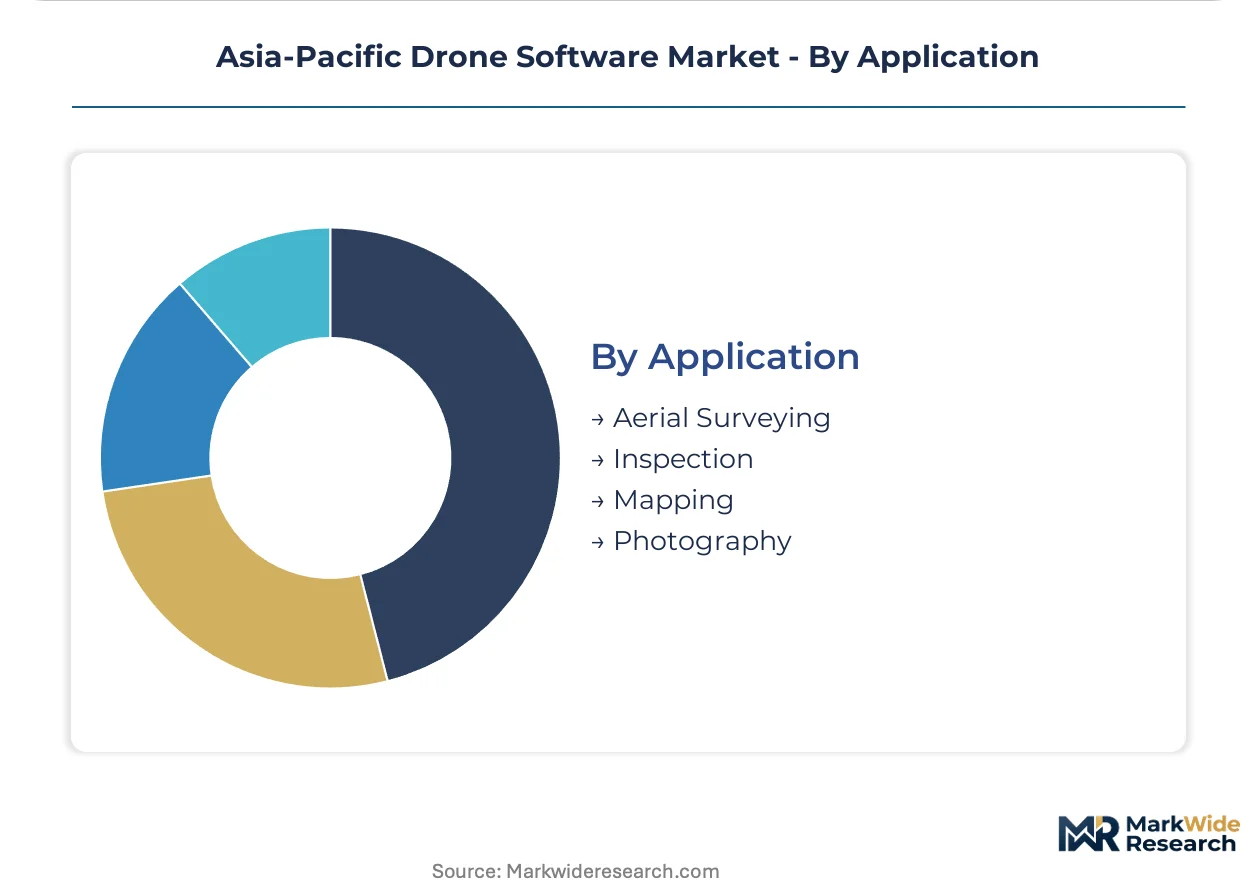
Application:
Mission profiles differentiate by sensor payload requirements, flight pattern complexity, and deliverable format standards.
- Aerial Surveying:Large-area orthomosaic generation with ground control point integration. Guangdong and Jiangsu agricultural fleets retrofit legacy hardware to maintain compliance with Civil Aviation Administration telemetry broadcast protocols.
- Inspection:Asset-specific flight planning with defect annotation and maintenance ticketing integration. Japanese energy infrastructure operators deploy these workflows under streamlined BVLOS corridor approvals.
- Mapping:Topographic and cadastral survey deliverables for land administration and engineering design. Australian state governments procure these services for remote boundary delineation.
- Photography:Cinematography and real estate marketing with lower technical barriers and commoditized pricing.
Inspection and surveying concentrate enterprise spending; mapping applications are gaining share fastest as digital twin convergence accelerates smart city infrastructure monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flight control firmware development clusters heavily in China's Pearl River Delta, while data analytics vendors concentrate in Australian and Japanese urban centers. Regulatory divergence across the region fragments certification pathways and shapes software localization requirements.
China
Commercial drone corridors around Shenzhen and Guangzhou anchor flight control algorithm development and hardware-software integration. The Civil Aviation Administration mandates remote identification broadcast protocols for all commercial unmanned aerial systems above 250 grams, forcing telemetry module standardization across agricultural and surveying fleets in Guangdong and Jiangsu provinces.
Japan
Infrastructure inspection missions and precision logistics operations drive demand for beyond-visual-line-of-sight permissions. METI-mandated maintenance schedules for aging bridges and tunnels accelerate adoption of automated crack detection workflows. Tokyo and Osaka host the concentrated base of real-time kinematic calibration engineers serving enterprise fleet operators.
Australia
Cotton and wheat operations across Queensland and New South Wales expand autonomous spraying and crop monitoring deployments under streamlined BVLOS permissions. The Civil Aviation Safety Administration mandates tiered remote operator certification that shapes software compliance requirements for commercial agriculture and mining applications in Western Australia's Pilbara region.
South Korea
Semiconductor foundry capacity in Seoul and Busan-Ulsan corridors supplies flight control system-on-chip fabrication for regional drone manufacturers. The country's national aviation regulator enforces airspace classification protocols that constrain autonomous flight altitudes, pushing software vendors toward embedded GPS-denied navigation fallback systems.
Vietnam
Underpenetrated last-mile delivery networks in Hanoi and Ho Chi Minh City corridors present greenfield deployment potential for autonomous cargo drone services. The national aviation authority maintains developing frameworks for commercial unmanned aerial system operation certificates, creating early-mover positioning opportunities for fleet management software providers targeting logistics verticals.
Asia-Pacific Drone Software Market Competitive Landscape
Integrated hardware-software conglomerates and specialized analytics pure-plays split the market into contrasting margin structures. SZ DJI Technology Co., Ltd. anchors flight control firmware ecosystems through captive hardware distribution, while cloud-native vendors pursue recurring revenue through subscription-based data processing portals. The competitive terrain rewards vertical integration into sensor manufacturing and strategic partnerships with civil aviation regulators for certification reciprocity. Geographic expansion into Southeast Asian logistics corridors and portfolio diversification toward edge computing architectures represent the dominant competitive moves reshaping positioning.
Within the integrated hardware-software tier, SZ DJI Technology Co., Ltd. exemplifies the conglomerate archetype through its Shenzhen-based operations. Among analytics specialists, DroneDeploy, Inc. and Pix4D SA occupy positions representing the cloud-native and photogrammetry-engine archetypes respectively. These three companies illustrate the strategic divergence between firmware-embedded control systems and standalone data processing platforms competing for enterprise construction and agriculture budgets across Australian and Japanese markets.
| Leading Market Players |
|---|
| Kespry, Inc. |
| Esri, Inc. |
| SZ DJI Technology Co., Ltd. |
| AgEagle Aerial Systems, Inc. |
| Skydio, Inc. |
| DroneDeploy, Inc. |
| PrecisionHawk, Inc. |
| DELAIR SAS |
| Pix4D SA |
| Others |
Value Network & Pricing Analysis
Shenzhen's concentrated flight control firmware development capacity grants incumbent vendors outsized pricing power over enterprise fleet operators seeking embedded autonomy stacks. Downstream software vendors face margin compression as hardware-software bundling tightens across Australian and Japanese commercial deployments.
Pricing Analysis
After-sales telemetry data subscriptions and fleet orchestration services now capture the dominant share of customer lifetime value, displacing perpetual license models. Three-tier pricing structure across premium, standard, and economy levels stratifies by RTK positioning accuracy and BVLOS certification tier. Cost compression in mid-tier cloud analytics is intensifying because DroneDeploy and Pix4D reseller channels are pivoting to consumption-based billing. Agricultural cooperatives in Queensland exhibit highest price sensitivity; Japanese infrastructure conglomerates with METI-mandated inspection schedules show lowest.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates strategic planning for flight control system-on-chip procurement. Fabrication capacity clusters in Taiwan, South Korea, and Japan, with raw material dependencies spanning silicon wafers, GaN substrates, and precision MEMS sensors. Single-source vulnerability at TSMC's advanced nodes threatens mission-critical mining deployments in Western Australia's Pilbara region. Distribution runs through Shenzhen hardware integrators and Australian-Japanese software reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beyond-visual-line-of-sight regulatory harmonization across Association of Southeast Asian Nations member states is accelerating penetration in logistics and infrastructure inspection verticals. Early-cycle positioning favors vendors with embedded compliance modules and edge-native architectures.
For Market Incumbents: Entrench firmware-software integration advantages by embedding Civil Aviation Administration remote identification protocols directly into flight control stacks. Acquire RTK calibration engineering capacity in Tokyo and Shenzhen to constrain competitor fleet scaling. Priority lever: backward integration into sensor manufacturing to displace LiDAR-dependent configurations. For New Entrants and Emerging Players: Pursue Vietnam and Thailand last-mile delivery corridors where national aviation frameworks remain under development. Greenfield logistics networks offer lowest competitive density. Go-to-market angle: metered mission-based billing tailored to capital-constrained Southeast Asian operators seeking operational expenditure treatment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive drone divisions lacking standalone software monetization. Long-term viability hinges on recurring revenue ratios and regulatory certification reciprocity across Asia-Pacific jurisdictions. Signal to watch: Civil Aviation Administration unmanned aerial system operation certificate issuance velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Flight control firmware absorption of machine vision pipelines compresses hardware-software boundaries for GPS-denied missions. |
| Geographic Expansion | Vietnam and Thailand logistics corridors present greenfield deployment potential before regulatory frameworks mature. |
| Acquisition of Specialist Firm | RTK positioning engineering scarcity in Shenzhen and Tokyo constrains fleet scaling without targeted capability capture. |
| Strategic Partnership | Building information modeling workflow integration anchors premium pricing for smart city infrastructure monitoring. |
| Product Launch | Edge-native AI inference modules enable autonomous night inspections without ground station dependency in mining applications. |
Research Methodology
A spread of perspectives from fleet operations managers, civil aviation regulatory leads, software platform engineers, and precision agriculture specialists converged on the working assumptions. Primary interviews combined with secondary validation against Civil Aviation Administration operation certificate databases, Australian Civil Aviation Safety Administration compliance filings, and Japanese METI infrastructure inspection mandates. Bottom-up deployment modeling across Queensland cotton operations and top-down market sizing from Shenzhen hardware shipment data were triangulated.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-use vertical, fleet scale tier, and regional regulatory maturity. CAGRs were derived from installed base expansion rates and software attach ratio trajectories. Industry-specific inputs encompassed BVLOS permission issuance timelines and edge computing module adoption curves in Indonesian mining operations.
Macroeconomic conditions sit as an overlay; deviation in semiconductor foundry utilization rates and cross-border data sovereignty enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization velocity and telemetry standardization mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Industrial Drones Market
UAV
Micro Drone Market
UAV
North America Fuel Cell UAV Market
UAV
Global Drone Software Market
UAV
Multirotor Drones Market
UAV
Global Drone Light Shows Market
UAV
Drones Market
UAV
Drone Tracking Antenna Market
UAV
Nano Drones Market
UAV
Europe Drone Services Market
UAV
Drone Roof Inspection Market
UAV
Anti-Drone Technology Market
UAV
UAV Battery Market
UAV
Passenger Drones Market
UAV
North America Drone Software Market
UAV
UAV Payload and Subsystems Market