
 UAV Navigation Systems Market | 2026-2036
UAV Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Navigation Systems Market Analytics
Software-defined flight autonomy is recalibrating how navigation capabilities get monetized, shifting value from hardware sales to recurring algorithm updates and airspace compliance modules. DJI Innovations leverages its Shenzhen R&D campus to anchor firmware ecosystems across consumer and enterprise drones. Northrop Grumman sustains defense-grade inertial navigation dominance through captive manufacturing of ring laser gyroscopes. Skydio specializes in computer vision-based obstacle avoidance for close-quarters industrial inspection.
UAV navigation systems integrate sensor fusion architectures—combining GNSS receivers, MEMS inertial measurement units, and visual odometry processors—to compute real-time position, velocity, and attitude for autonomous flight control, typically achieving horizontal accuracy within one centimeter when RTK corrections are active. Their primary purpose spans precision aerial maneuvering in GPS-denied environments and regulatory-compliant beyond-visual-line-of-sight operations. GPS technology occupies the largest installed base due to mature cost curves, yet computer vision segments attract the fastest investment as edge AI processors shrink latency for visual-inertial odometry. Military applications command premium pricing through hardened anti-jam specifications, while delivery pilots in controlled urban zones generate disproportionate software licensing revenue per unit.
The FAA enforces Remote ID broadcast requirements that reshape hardware architectures for US-registered commercial fleets, while EASA's drone regulation framework in Europe mandates specific fail-safe navigation behaviors for operations over populated areas. China's CAAC coordinates with MIIT to enforce GB standard compliance for domestic UAV navigation hardware, creating a separate certification path from Western markets. Stakeholders must monitor whether emerging sense-and-avoid mandates in multiple jurisdictions fragment firmware development or consolidate around interoperable open standards.
Market Dynamics
Software-defined navigation architectures are compressing hardware refresh cycles while inflating firmware licensing revenue per airframe. RTK-GPS correction networks and visual-inertial odometry stacks now determine competitive position more than sensor hardware specifications.
Growth Catalysts
- Remote ID mandates:FAA broadcast requirements force hardware retrofits across US commercial fleets, creating immediate replacement demand for compliant GNSS modules and telemetry radios.
- Precision agriculture automation:Brazilian spraying fleets now require RTK subscriptions for autonomous operation, converting navigation from capital expense to recurring service revenue.
- MEMS cost curves:Consumer-grade inertial measurement units achieve tactical-grade performance thresholds, enabling navigation redundancy in sub-$5,000 airframes previously limited to single-sensor architectures.
Market Restraints
- Ring laser gyroscope supply concentration:Defense-grade inertial navigation depends on captive production concentrated in North American and European defense primes, limiting price competition for hardened anti-jam specifications.
- GNSS jamming vulnerability:Civilian GPS receivers face spoofing and denial threats in contested electromagnetic environments, constraining beyond-visual-line-of-sight operations without backup navigation modes.
- Dual certification burden:China's GB standards for domestic UAV hardware diverge from FAA and EASA pathways, forcing manufacturers to maintain separate firmware branches and testing protocols.
Strategic Opportunities
- Urban air mobility corridors:Controlled low-altitude zones in China's Yangtze River Delta generate disproportionate software licensing revenue per unit for sense-and-avoid navigation stacks.
- Edge AI convergence:Visual odometry processors combined with neural network accelerators enable GPS-denied navigation in warehouse inspection and subterranean mapping applications.
- Airspace compliance modules:Subscription-based geofencing and dynamic rerouting algorithms capture recurring revenue from delivery pilots operating in European urban zones under EASA drone regulations.
Industry Challenges
- Sensor fusion engineering scarcity:Developers capable of integrating GNSS, IMU, and visual odometry streams into unified Kalman filter architectures command premium compensation, constraining team scaling.
- Certification timeline compression:EASA's evolving fail-safe navigation requirements for operations over populated areas force continuous firmware recertification, extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Navigation Systems Market |
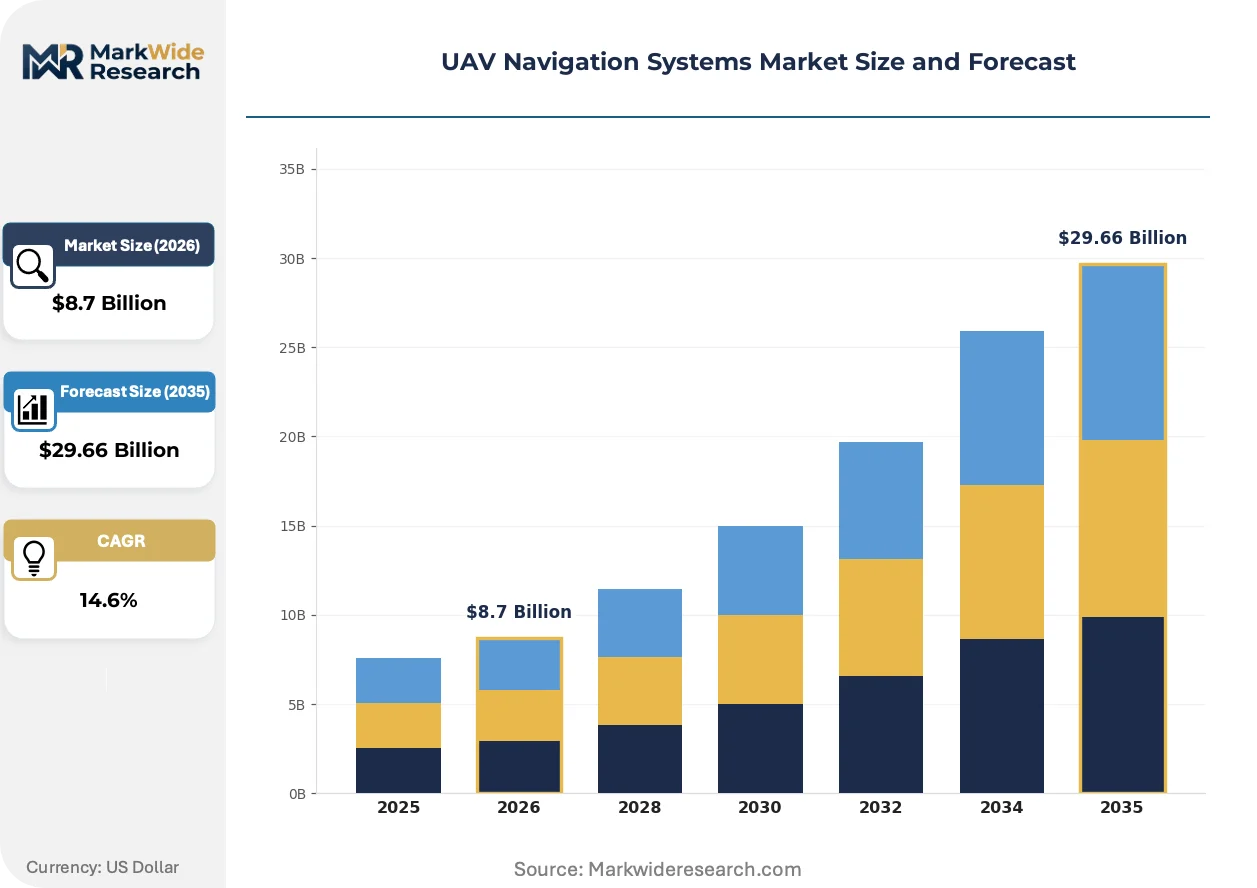
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Inertial Navigation Systems, Computer Vision, LiDAR Application: Agriculture, Military, Surveillance, Delivery End User: Commercial, Government, Law Enforcement, Research Control Type: Autonomous, Manual, Semi-Autonomous, Remote Piloted |
| Companies Covered | AeroVironment, JOUAV, DJI Innovations, Parrot, EHang, Skydio, Insitu (Boeing), XAG, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Navigation Systems Market Evolving Landscape
Navigation value capture is migrating from discrete hardware sales toward continuous algorithm delivery and airspace compliance services. Three developments are accelerating this structural shift.
Visual-inertial odometry is expanding into close-quarters industrial inspection where GPS signals degrade or vanish entirely. Mining operators and infrastructure surveyors in Australia and Canada now specify VIO-equipped platforms for confined-space asset monitoring. This capability compression eliminates the historical premium commanded by lidar-based navigation in GPS-denied environments.
EASA's drone regulation framework mandates specific fail-safe navigation behaviors for operations above populated European cities. The industrial consequence is firmware architecture fragmentation as manufacturers develop separate behavioral modes for continental versus urban flight profiles. Delivery service providers operating in German and French urban zones absorb disproportionate compliance engineering costs compared to rural agricultural counterparts.
Buyer procurement patterns now emphasize airspace-as-a-service subscriptions over perpetual hardware licenses. Agricultural cooperatives in Brazil and vineyard operators in France purchase RTK correction and geofencing updates as annual bundles rather than capitalizing navigation hardware. This shift concentrates vendor relationships around firmware ecosystem stickiness rather than sensor specification differentiation.
UAV Navigation Systems Market Segmentation
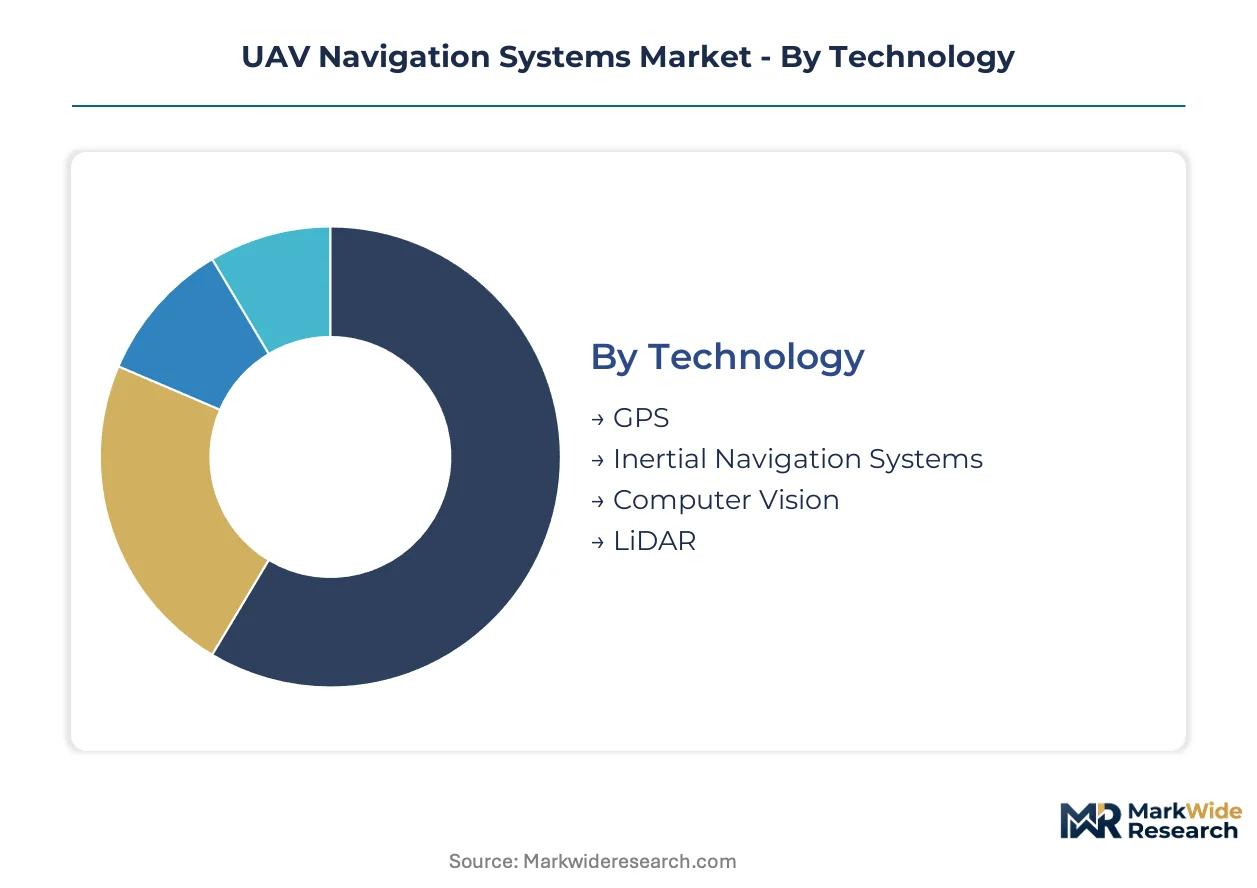
Navigation system procurement in unmanned aerial vehicles diverges sharply across mission profiles. Technology selection determines hardware architecture, while end-user classification dictates certification burden and pricing structure.
Technology:
Buyers prioritize accuracy thresholds against electromagnetic vulnerability when selecting sensor stacks.
- GPS:GNSS receivers with RTK correction capability deliver horizontal positioning within one centimeter under open sky. Brazilian agricultural cooperatives now mandate RTK subscriptions for autonomous spraying fleets, converting this technology from capital purchase to recurring service revenue.
- Inertial Navigation Systems:Ring laser gyroscopes and MEMS IMUs provide dead-reckoning capability when satellite signals degrade. Defense primes in North America sustain captive production of hardened anti-jam specifications, limiting price competition for military-grade platforms.
- Computer Vision:Visual-inertial odometry processors enable GPS-denied navigation through neural network accelerators.
- LiDAR:Laser-based ranging systems support precision landing and terrain mapping in dust-heavy environments.
Volume sits with GPS; growth tilts toward computer vision.
Application:
Mission-critical requirements reshape supplier relationships and firmware development priorities.
- Agriculture:Precision spraying and crop monitoring demand RTK-GPS integration with automated flight planning. Vineyard operators in France purchase navigation capabilities as annual service bundles rather than capital hardware, shifting vendor stickiness toward firmware ecosystems.
- Military:Hardened anti-jam specifications and spoof-resistant architectures command premium pricing through defense procurement channels. Contested electromagnetic environments necessitate redundant inertial backup modes unavailable in civilian systems.
- Surveillance:Extended endurance missions require low-power navigation stacks with failsafe return-to-home behaviors.
- Delivery:Urban corridor operations under EASA regulations absorb disproportionate compliance engineering costs for sense-and-avoid capabilities.
Procurement concentrates in agriculture; regulatory complexity peaks in delivery.
End User:
Certification pathways and liability frameworks segment buyer behavior across institutional categories.
- Commercial:Agricultural and infrastructure inspection operators prioritize cost-optimized MEMS architectures with subscription-based correction services.
- Government:Civil agencies balance budget constraints against airspace compliance mandates from national regulators.
- Law Enforcement:First responder units require rapid-deployment navigation with minimal calibration overhead.
- Research:Academic and institutional buyers drive adoption of experimental sensor fusion algorithms before commercial validation.
Revenue per unit peaks in government; volume expansion concentrates in commercial.
Control Type:
Autonomy level determines sensor redundancy requirements and software licensing models.
- Autonomous:Full self-piloting systems integrate GNSS, IMU, and visual odometry streams through unified Kalman filter architectures. China's Yangtze River Delta manufacturing corridors generate disproportionate software licensing revenue per unit for sense-and-avoid navigation stacks in controlled urban air mobility zones.
- Manual:Direct pilot control minimizes navigation hardware requirements to basic attitude reference.
- Semi-Autonomous:Pilot-supervised waypoint navigation dominates agricultural and inspection applications.
- Remote Piloted:Beyond-visual-line-of-sight operations demand failsafe navigation behaviors mandated by EASA for flights over populated European areas.
Hardware margins compress in manual; firmware value concentrates in autonomous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in China's Yangtze River Delta while consumption spreads across precision agriculture belts in Brazil and regulatory-mandated retrofit markets in the United States. This geographic split shapes divergent competitive strategies for hardware producers versus software licensors.
United States
FAA Remote ID mandates force hardware retrofits across commercial drone fleets, generating immediate demand for compliant GNSS modules and telemetry radios. Defense procurement channels sustain premium pricing for hardened anti-jam navigation specifications through Northrop Grumman's captive ring laser gyroscope production. California-based autonomy specialists and Texas agricultural operators drive divergent adoption patterns for consumer versus enterprise navigation stacks.
China
CAAC coordination with MIIT enforces GB standard compliance for domestic UAV navigation hardware, creating certification pathways separate from Western markets. The Yangtze River Delta hosts dense manufacturing and testing corridors where DJI and EHang operate integrated R&D and production facilities. Shenzhen firmware ecosystems anchor subscription revenue models across consumer and enterprise drone segments.
Brazil
Precision agriculture fleets now require RTK-GPS correction subscriptions for autonomous spraying missions, converting navigation from capital expense to recurring service revenue. ANVISA and DECEA regulations govern commercial UAV operations over agricultural zones with specific navigation reliability thresholds. São Paulo-based cooperatives and Mato Grosso soybean operators represent the largest concentrated demand for centimeter-accuracy guidance systems.
Germany
EASA drone regulations mandate specific fail-safe navigation behaviors for operations over populated areas, forcing firmware architecture fragmentation. Delivery service providers in German urban zones absorb disproportionate compliance engineering costs compared to rural agricultural counterparts. Bavarian industrial inspection specialists and Berlin logistics pilots drive contrasting requirements for GPS-denied versus regulatory-compliant navigation modes.
Australia
CASA regulations govern beyond-visual-line-of-sight operations with strict navigation redundancy requirements for remote area mining and infrastructure survey missions. Visual-inertial odometry equipped platforms penetrate confined-space asset monitoring in Western Australian iron ore operations and Queensland coal corridors. Perth and Brisbane serve as procurement hubs for VIO-capable systems replacing historical lidar-based navigation premiums.
UAV Navigation Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the navigation stack, with sensor foundries and algorithm developers occupying distinct value capture positions. The vendor base stratifies between defense primes sustaining captive inertial component production and commercial specialists licensing firmware on subscription terms. Three archetypes dominate: vertically integrated hardware manufacturers, software-defined autonomy platforms, and dual-use defense-commercial suppliers. Competitive moves concentrate on strategic partnerships for RTK correction network access and portfolio diversification into airspace compliance modules.
Among defense-commercial suppliers, Northrop Grumman exemplifies the captive production archetype through in-house ring laser gyroscope manufacturing for hardened specifications. DJI Innovations and Skydio represent contrasting commercial strategies, with the Shenzhen-based entity anchoring firmware ecosystem stickiness and the California specialist occupying computer vision-based obstacle avoidance positioning. These three entities illustrate the structural divergence between hardware-margin and software-recurring revenue models across the competitive landscape.
| Leading Market Players |
|---|
| AeroVironment |
| JOUAV |
| DJI Innovations |
| Parrot |
| EHang |
| Skydio |
| Insitu (Boeing) |
| XAG |
| Northrop Grumman |
| Others |
Value Network & Pricing Analysis
Captive in-house production of ring laser gyroscopes by Northrop Grumman anchors premium pricing power for defense-grade navigation specifications while forcing commercial vendors toward subscription-based firmware monetization. This integration choice separates military procurement channels from agricultural and delivery segments where MEMS cost curves compress hardware margins.
Pricing Analysis
Cost compression in civilian GNSS modules accelerates because MEMS inertial measurement units achieve tactical-grade thresholds at consumer price points. Pricing stratifies across hardened anti-jam specifications, RTK-corrected precision tiers, and basic uncorrected GPS receivers. Certification level under EASA and FAA mandates drives differentiation. Agricultural cooperatives in Brazil exhibit highest price sensitivity. Military buyers absorb premiums for spoof-resistant architectures.
Supply Chain Analysis
Dual-sourcing requirements from defense primes mandate qualified alternative suppliers for ring laser gyroscope subcomponents alongside MEMS foundries. Manufacturing concentrates in China, the United States, and Germany. Critical inputs span indium phosphide laser cavities, precision optical coatings, and neural network accelerator chips. Single-source vulnerability sits with defense-grade optical component suppliers. Distribution runs through direct OEM integration and tier-one subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV navigation market sits in a technology-transition phase where visual-inertial odometry displaces legacy lidar-based positioning for GPS-denied environments. Software-defined architectures now determine competitive position more than sensor hardware specifications.
For Market Incumbents: Acquire edge AI processor design capabilities to anchor firmware ecosystem stickiness against emerging computer vision specialists. Deepen backward integration into MEMS foundry partnerships to defend margin position from commoditization. Counter Skydio's obstacle avoidance positioning with integrated sense-and-avoid stacks for urban air mobility corridors.
For New Entrants and Emerging Players: Enter via RTK correction network services for Brazilian agricultural cooperatives where subscription revenue models remain underdeveloped. Target warehouse inspection applications requiring GPS-denied navigation with minimal certification burden. Pursue white-label firmware licensing to Chinese manufacturing corridors in the Yangtze River Delta.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by defense primes seeking dual-use navigation capabilities and enterprise software platforms acquiring airspace compliance modules. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Watch EASA sense-and-avoid mandate implementation timelines as inflection indicator for compliance engineering demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Edge AI Specialist | Secures neural network accelerators for visual-inertial odometry stacks replacing lidar premiums. |
| RTK Correction Network Partnership | Locks recurring subscription revenue from Brazilian agricultural spraying fleets requiring centimeter accuracy. |
| Dual Certification Investment | Enables simultaneous FAA Remote ID and EASA fail-safe navigation compliance for delivery operators. |
| MEMS Foundry Joint Venture | Captures tactical-grade inertial measurement unit supply for sub-five-thousand-dollar airframes. |
| Airspace Compliance Module Launch | Captures geofencing and dynamic rerouting subscriptions from European urban drone delivery pilots. |
Research Methodology
Independent corroboration across sensor fusion engineering directors, agricultural drone fleet operators, defense procurement officers, and regulatory affairs leads at CAAC and EASA underwrites the qualitative findings. Secondary validation draws from FAA certification databases, EASA drone regulation filings, Brazilian ANVISA operational records, and customs trade data for MEMS component flows. Bottom-up airframe shipment estimates triangulate against top-down navigation system revenue aggregation.
Rate-of-change decomposition separates volume expansion in precision agriculture from value migration toward software licensing across the analysis window. Segmentation dimensions span technology type, application mission profile, end-user institutional category, and control autonomy level. CAGRs derive from fitted growth curves against historical airframe adoption patterns and correction service subscription attach rates. Model inputs incorporate EASA regulatory timeline assumptions and MEMS cost curve trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GNSS jamming deployment in contested electromagnetic environments or delayed sense-and-avoid mandate harmonization across jurisdictions. Deviation in CAAC-FAA-EASA regulatory alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Drone Light Shows Market
UAV
Global Target Drone Market
UAV
Commercial UAV Market
UAV
Combat Drone Market
UAV
Solar Powered Drones Market
UAV
Ultra Micro Drone Market
UAV
US Commercial Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Global Renewable Drones Market
UAV
Europe Tethered Drone Market
UAV
Industrial Drones Market
UAV
Auto-Follow Drone Market
UAV
Drone Payload Market
UAV
Multirotor Drones Market
UAV
Firefighting Drone Market
UAV
Unmanned Combat Aerial Vehicle Market