
 Commercial UAV Market | 2026-2036
Commercial UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial UAV Market Analytics
Chinese manufacturing clusters is restructuring the global supply base for commercial unmanned aerial vehicles, with Shenzhen-based production lines now accounting for the majority of airframe and gimbal assembly capacity. SZ DJI Technology Co., Ltd. leverages vertical integration across flight controllers and camera systems to sustain cost leadership in the prosumer tier. General Atomics Aeronautical Systems Inc. anchors the large fixed-wing segment through its specialization in long-endurance platforms for government surveillance contracts. AeroVironment, Inc. differentiates in the tactical small-UAS niche where its Switchblade loitering systems compete for defense procurement dollars.
Commercial unmanned aerial vehicles are powered aircraft operating without a human pilot aboard, typically employing multi-rotor or fixed-wing configurations with maximum takeoff weights ranging from under 250 grams to above 25 kilograms, designed for payload delivery, aerial imaging, or remote sensing missions in civilian airspace. The agriculture application segment dominates current fleet utilization as agricultural companies deploy variable-rate spraying and multispectral crop health monitoring to reduce input costs. Infrastructure inspection is expanding fastest among user types as construction companies substitute UAV-based facade and tower assessments for rope-access teams, concentrating margin pools in software analytics rather than hardware sales.
The FAA's Part 107 framework governs remote pilot certification and operational waivers in the United States, while EASA's Specific Category under EU Regulation 2019/947 shapes market access across European member states with its risk-based operational authorization system. China's CAAC enforces real-name registration and geofencing compliance for all commercial flights above 250 grams, creating a compliance barrier that favors established domestic manufacturers. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings across these three jurisdictions to anticipate where regulatory arbitrage opportunities will open for cross-border service providers.
Market Dynamics
Commercial UAV demand is concentrating around beyond-visual-line-of-sight operations, forcing manufacturers and operators to navigate fragmented national airspace regimes while racing to certify autonomous flight systems for routine civilian deployment.
Growth Catalysts
- FAA Part 107 waivers:Expanded operational authorizations for night flights and over-people missions are unlocking infrastructure inspection contracts previously reserved for manned aviation.
- Multispectral imaging payloads:Agricultural operators in Brazil are deploying variable-rate spraying systems that reduce fertilizer input costs through precise crop health mapping.
- Shenzhen manufacturing clusters:Dense supplier ecosystems around SZ DJI Technology Co., Ltd. compress component lead times and enable rapid prototype-to-production cycles for airframe assemblies.
Market Restraints
- Lithium-polymer battery supply concentration:Cathode material processing capacity concentrates in China's Hunan and Fujian provinces, exposing non-Chinese assemblers to input cost volatility and export licensing delays.
- Geofencing firmware mandates:China's CAAC requires real-name registration and no-fly zone enforcement for all commercial units above 250 grams, creating compliance barriers that favor established domestic manufacturers over foreign entrants.
- Radio frequency spectrum scarcity:Command-and-control link congestion in the 5.8 GHz band limits swarm coordination capabilities for precision agriculture fleets operating in dense cultivation zones.
Strategic Opportunities
- EU Specific Category expansion:EASA's risk-based operational authorization system under EU Regulation 2019/947 is creating regulatory arbitrage opportunities for cross-border service providers establishing certified beyond-visual-line-of-sight hubs in Germany and France.
- Last-mile delivery corridors:Urban air mobility infrastructure investments in the United Arab Emirates are opening payload delivery routes for medical supplies and e-commerce fulfillment across Dubai's low-density industrial zones.
- AI-powered flight planning convergence:Integration of computer vision with predictive weather routing is enabling autonomous obstacle avoidance for infrastructure inspection missions in high-wind coastal environments.
Industry Challenges
- Remote pilot certification bottlenecks:FAA Part 107 practical testing capacity constraints in the United States are creating month-long queues that delay fleet expansion timelines for commercial service providers.
- Airworthiness certification timelines:Type certification requirements for unmanned aircraft systems above 55 pounds involve multi-year validation cycles that compress product refresh windows for fixed-wing platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial UAV Market |
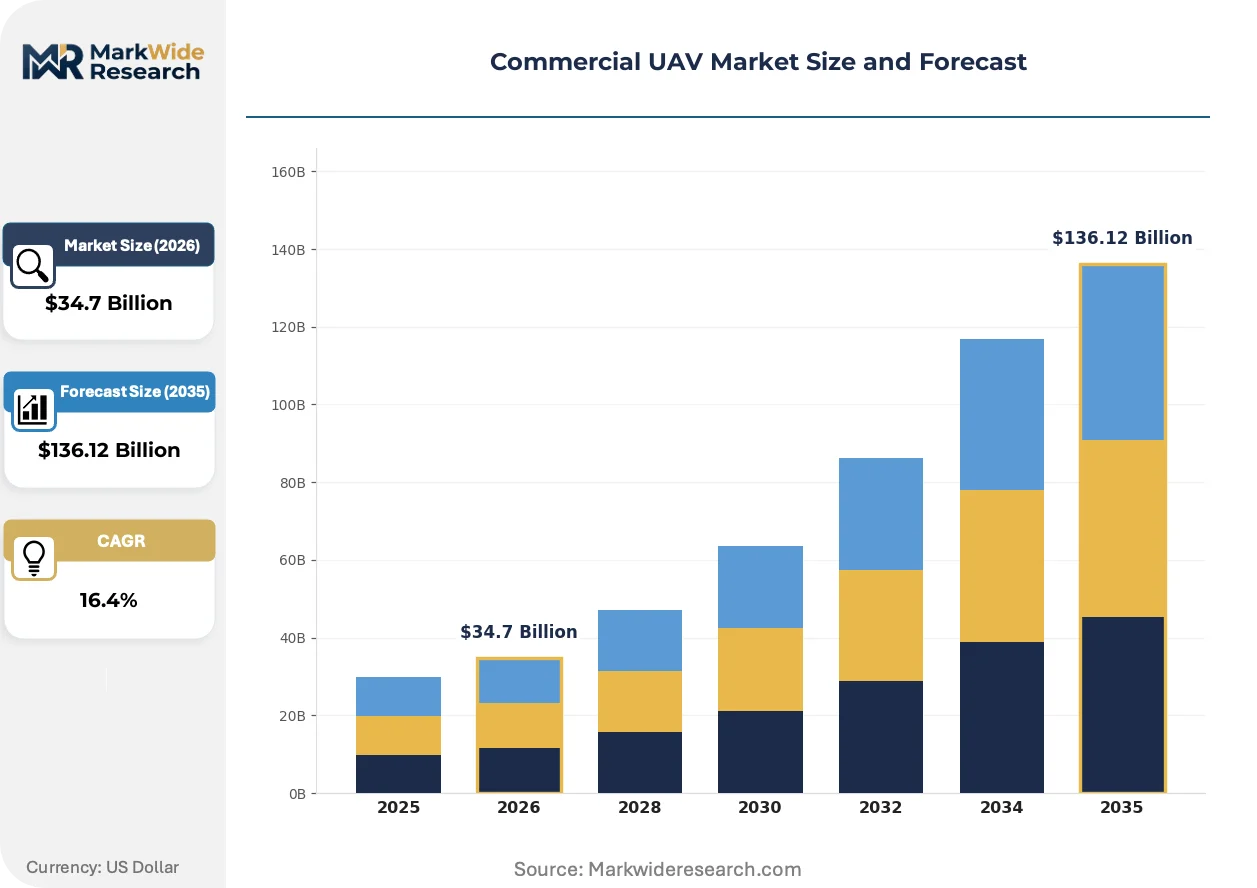
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $136.12 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Delivery Services, Infrastructure Inspection, Surveying User Type: Agricultural Companies, Logistics Firms, Construction Companies, Government Agencies Payload Capacity: Small, Medium, Heavy, Extra Heavy Operation Mode: Autonomous, Remotely Piloted, Hybrid, On-demand |
| Companies Covered | SZ DJI Technology Co., Ltd., Northrop Grumman Corporation, AeroVironment, Inc., Skydio, Inc., Parrot Drone SAS, General Atomics Aeronautical Systems Inc., Lockheed Martin Corporation, Teledyne FLIR LLC, Yuneec International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial UAV Market Evolving Landscape
Edge computing architectures are migrating flight-critical processing from ground stations to onboard units, compressing latency for real-time decision-making while reshaping hardware specifications across the supplier base.
Swarm coordination algorithms are decentralizing mission execution across multiple small-UAS platforms, enabling agricultural operators to survey thousand-hectare properties without centralized ground control infrastructure. Brazilian soybean producers are adopting these distributed systems at pace, replacing single large-platform contracts with federated fleets that compress survey timelines from days to hours. This shift is decentralizing procurement power toward regional agronomy cooperatives that can aggregate fleet utilization across multiple farm holdings.
EASA's Specific Category framework under EU Regulation 2019/947 is standardizing operational risk assessments for beyond-visual-line-of-sight missions, forcing manufacturers to redesign flight control redundancy systems for European market access. The regulation mandates documented safety management systems that previously existed only in manned aviation contexts. Infrastructure inspection providers in Germany and the Netherlands are responding by consolidating software analytics capabilities in-house rather than outsourcing flight operations to third-party drone service companies.
Equipment-as-a-service contracting is displacing capital purchase models for precision agriculture fleets, with Brazilian operators preferring per-hectare billing tied to yield optimization outcomes. This restructures vendor cash flow cycles and concentrates margin pools in subscription-based analytics platforms rather than hardware sales. The pattern is most visible in Mato Grosso's soybean belt, where cooperatives now treat UAV fleets as operational expenses rather than balance-sheet assets.
Commercial UAV Market Segmentation
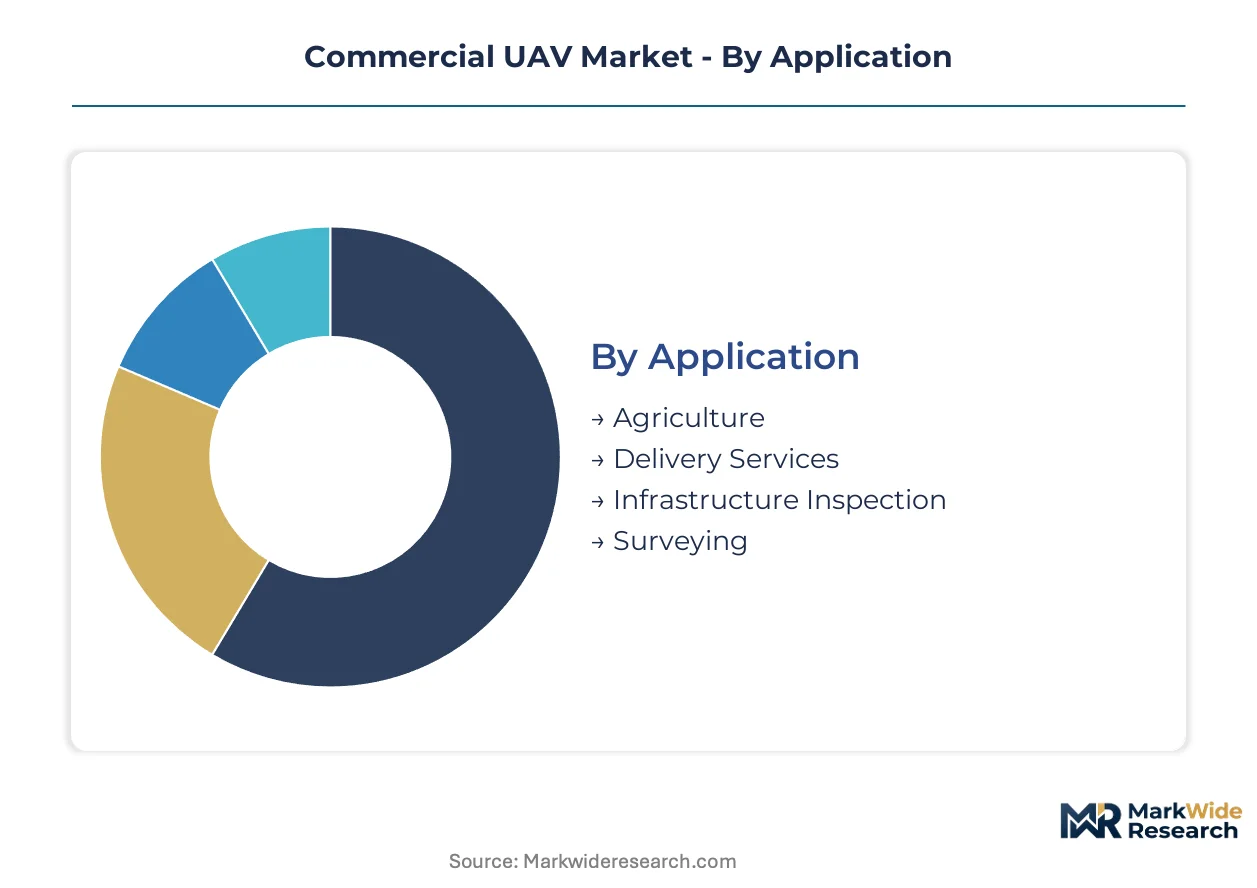
Commercial UAV procurement patterns diverge sharply across operational contexts, with application requirements dictating payload specifications and regulatory compliance tiers. Fleet operators prioritize platform modularity to accommodate sensor swaps between crop monitoring, infrastructure assessment, and last-mile delivery missions without airframe replacement.
Application:
Agriculture operators replace single-platform contracts every three to four growing seasons as multispectral sensor resolution improves, while infrastructure inspection providers extend replacement cycles through modular payload upgrades.
- Agriculture:Variable-rate spraying systems and NDVI crop health mapping dominate fleet utilization in Brazil's Mato Grosso soybean belt. Brazilian cooperatives aggregate demand across multiple farm holdings, compressing survey timelines from days to hours through federated fleet deployment.
- Infrastructure Inspection:Facade assessments and transmission tower surveys substitute UAV-based data collection for rope-access teams in Germany and the Netherlands. Construction companies consolidate software analytics capabilities in-house rather than outsourcing flight operations to third-party drone service providers.
- Delivery Services:Medical supply corridors in Dubai's low-density industrial zones and e-commerce fulfillment routes anchor payload capacity requirements.
- Surveying:Cadastral mapping and topographic assessment missions drive demand for RTK-GNSS integration in precision measurement applications.
Agriculture sits at the top of the volume ranking, with infrastructure inspection climbing the fastest.
User Type:
Procurement authority concentrates differently across user categories, with agricultural cooperatives wielding aggregated purchasing power while government agencies impose extended certification timelines.
- Agricultural Companies:Brazilian soybean producers adopt equipment-as-a-service contracting with per-hectare billing tied to yield optimization outcomes. This restructures vendor cash flow cycles toward subscription-based analytics platforms rather than hardware sales.
- Construction Companies:German and Dutch infrastructure developers internalize flight operations and software analytics capabilities to maintain margin control over facade and tower assessment workflows.
- Logistics Firms:E-commerce fulfillment providers in the United Arab Emirates pilot urban air mobility corridors for medical supply delivery across Dubai's industrial zones.
- Government Agencies:Surveillance and border patrol procurement in the United States flows through long-endurance fixed-wing platforms requiring multi-year type certification cycles above 55 pounds.
Agricultural companies command the largest fleet volumes, with construction companies expanding procurement most aggressively.
Payload Capacity:
Platform weight classes segment regulatory compliance burdens and operational authorization requirements across jurisdictions.
- Small:Units under 250 grams operate below China's CAAC real-name registration threshold, creating a compliance haven for consumer-tier entrants. Brazil's precision agriculture sector deploys these platforms for rapid crop scouting without pilot certification overhead.
- Medium:Multispectral sensors and lightweight spraying systems occupy this tier, with SZ DJI Technology Co., Ltd. dominating airframe and gimbal assembly capacity from Shenzhen manufacturing clusters.
- Heavy:Variable-rate application equipment and lidar payloads require reinforced airframes with extended flight endurance for thousand-hectare property surveys.
- Extra Heavy:Cargo delivery platforms above 25 kilograms face the most restrictive beyond-visual-line-of-sight authorization requirements in United States and European airspace.
Medium payload platforms dominate current fleet composition, with heavy-class units gaining share fastest in agricultural spraying applications.
Operation Mode:
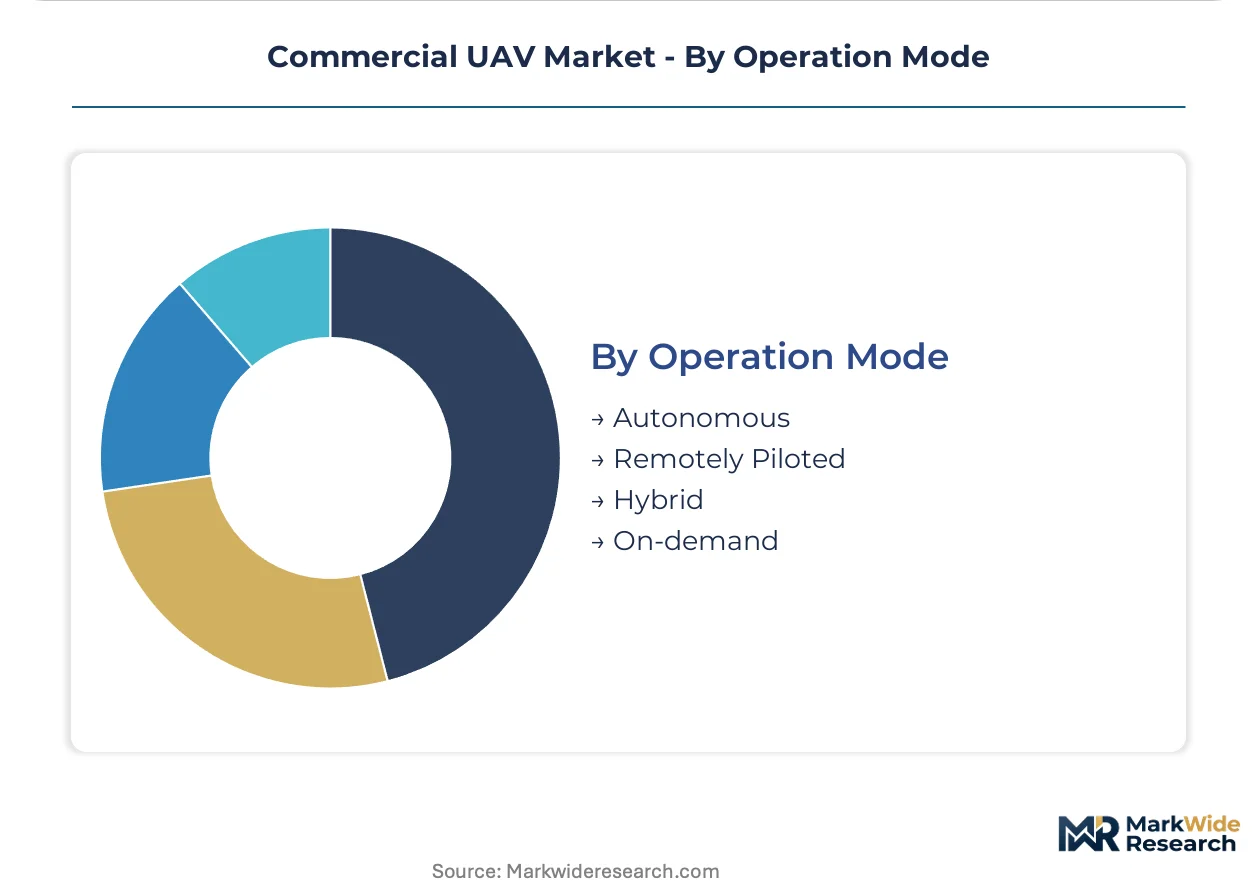
Autonomy levels determine ground infrastructure requirements and regulatory risk classification across the United States FAA Part 107 framework and EASA's Specific Category.
- Autonomous:Computer vision integration with predictive weather routing enables obstacle avoidance for infrastructure inspection in high-wind coastal environments without continuous human oversight.
- Remotely Piloted:FAA Part 107 certification bottlenecks create month-long practical testing queues that delay fleet expansion timelines for commercial service providers in the United States.
- Hybrid:Human-supervised autonomous modes bridge regulatory gaps during beyond-visual-line-of-sight transition periods in European risk-based operational authorization systems.
- On-demand:Ad-hoc deployment models concentrate in emergency response and disaster assessment missions requiring rapid airspace clearance.
Remotely piloted systems retain the largest installed base, with autonomous platforms expanding most quickly where EASA's Specific Category standardizes operational risk assessments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers relocate assembly to jurisdictions with streamlined airworthiness certification. Cost-of-compliance gaps between the United States, China, and European Union are concentrating investment in clusters where type-approval timelines compress competitive cycles.
United States
Infrastructure inspection contracts and agricultural spraying operations drive fleet expansion across the Midwest and Southeast. The FAA's Part 107 framework governs remote pilot certification and operational waivers, with expanded night-flight authorizations unlocking contracts previously reserved for manned aviation. Texas and California host the densest operator concentrations, where construction companies internalize UAV-based facade assessment capabilities.
China
Guangdong Province anchors global airframe and gimbal assembly capacity through Shenzhen-based manufacturing clusters. The CAAC enforces real-name registration and geofencing compliance for all commercial flights above 250 grams, creating compliance barriers that favor established domestic manufacturers. SZ DJI Technology Co., Ltd. leverages vertical integration across flight controllers and camera systems to sustain cost leadership from this production base.
Brazil
Precision agriculture operations in Mato Grosso's soybean belt deploy variable-rate spraying and multispectral crop health monitoring to reduce fertilizer input costs. ANVISA and the national civil aviation authority shape operational authorization for agricultural chemical application flights. Equipment-as-a-service contracting concentrates procurement power with regional agronomy cooperatives that aggregate fleet utilization across multiple farm holdings.
Germany
Infrastructure inspection providers in Bavaria and North Rhine-Westphalia consolidate software analytics capabilities in-house rather than outsourcing flight operations. EASA's Specific Category under EU Regulation 2019/947 mandates documented safety management systems that previously existed only in manned aviation contexts. Stuttgart and Munich host engineering clusters where manufacturers redesign flight control redundancy systems for European market access.
United Arab Emirates
Urban air mobility infrastructure investments in Dubai open payload delivery routes for medical supplies and e-commerce fulfillment across low-density industrial zones. MOHAP and the General Civil Aviation Authority coordinate operational authorization for beyond-visual-line-of-sight corridors. Abu Dhabi's industrial free zones attract logistics firms piloting autonomous delivery networks with reduced regulatory friction.
Commercial UAV Market Competitive Landscape
Chinese producers anchor the volume tier through dense supplier ecosystems and compressed prototype-to-production cycles; American specialists hold the premium tier through long-endurance platforms and defense procurement relationships. The vendor base stratifies across three tiers: integrated system houses controlling flight controllers and payloads, airframe assemblers sourcing subsystems from upstream suppliers, and software analytics providers layering on top of commoditized hardware. Competitive moves concentrate on strategic partnerships for beyond-visual-line-of-sight certification and portfolio diversification into subscription-based service models.
Within the integrated system tier, SZ DJI Technology Co., Ltd. exemplifies vertical control across flight controllers and camera systems, while General Atomics Aeronautical Systems Inc. occupies a position in large fixed-wing platforms for government surveillance contracts. AeroVironment, Inc. sits within the tactical small-UAS niche where loitering systems compete for defense procurement dollars. These three anchors represent distinct strategic archetypes: consumer-prosumer cost leadership, long-endurance government specialization, and tactical military application.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Northrop Grumman Corporation |
| AeroVironment, Inc. |
| Skydio, Inc. |
| Parrot Drone SAS |
| General Atomics Aeronautical Systems Inc. |
| Lockheed Martin Corporation |
| Teledyne FLIR LLC |
| Yuneec International |
| Others |
Value Network & Pricing Analysis
EASA's Specific Category sustainability mandates under EU Regulation 2019/947 gate qualified supply access for commercial UAV manufacturers seeking European market entry, compressing premium-tier pricing power toward certified flight control redundancy systems while excluding uncertified competitors from high-margin infrastructure inspection contracts.
Pricing Analysis
Distributor margins in the commercial UAV sector absorb 15-25 percent of final equipment value, with direct-to-OEM procurement discounts compressing this layer for volume agricultural cooperatives in Brazil's Mato Grosso region. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and flight endurance capability, with FAA Part 107-compliant platforms commanding sustained premiums over uncertified alternatives. Pricing pressure stems from Shenzhen manufacturing clusters flooding prosumer tiers with vertically integrated flight controller and gimbal assemblies. Agricultural cooperatives exhibit highest price sensitivity due to equipment-as-a-service contracting models, while government surveillance agencies demonstrate lowest sensitivity given multi-year type certification requirements.
Supply Chain Analysis
Reverse-logistics flows for lithium-polymer battery packs and flight controller refurbishment concentrate in Guangdong Province, where SZ DJI Technology Co., Ltd. operates captive remanufacturing facilities that compress replacement part lead times. Cathode material processing draws from China's Hunan and Fujian provinces, while semiconductor fabrication for flight-critical processors rests on Taiwan and South Korea. Single-source vulnerability in rare-earth magnet supply from China's Inner Mongolia region exposes non-Chinese assemblers to export licensing delays. Distribution runs through specialized industrial distributors serving precision agriculture and defense procurement channels, with direct manufacturer relationships dominating high-volume fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial UAV markets present margin-expansion trajectories anchored by equipment-as-a-service contracting models that shift revenue toward recurring analytics subscriptions and away from commoditized hardware transactions.
For Market Incumbents: Anticipate regulatory fragmentation across FAA Part 107, EASA Specific Category, and CAAC geofencing mandates by diversifying certification investments across multiple jurisdictions rather than concentrating in single-approval pathways. Consolidate software analytics capabilities in-house to defend against infrastructure inspection providers internalizing flight operations, while deepening backward integration into flight controller semiconductor sourcing to offset rare-earth supply volatility.
For New Entrants and Emerging Players: Regional agronomy cooperatives in Brazil's secondary soybean belts beyond Mato Grosso represent the most penetrable buyer archetype, with per-hectare billing models lowering capital barriers for equipment-as-a-service market entry. Target last-mile medical supply corridors in Dubai's industrial free zones where MOHAP authorization frameworks create reduced regulatory friction for autonomous delivery pilots. Partner with established logistics firms rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among airframe assemblers lacking captive flight controller or gimbal production, as these suppliers face margin compression from Shenzhen-integrated competitors. Long-term viability over the coming decade hinges on successful beyond-visual-line-of-sight certification completion and recurring software revenue attachment rates. Monitor EASA Specific Category operational authorization expansion timelines as the critical inflection signal for European infrastructure inspection market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Certification Investment | EASA Specific Category approvals unlock German infrastructure inspection contracts previously reserved for manned aviation. |
| Equipment-as-a-Service Platform Launch | Per-hectare billing models in Brazil shift vendor cash flows toward recurring analytics subscriptions. |
| Flight Controller Semiconductor Backward Integration | Captive processor design reduces exposure to Taiwan foundry capacity constraints and tariff volatility. |
| Multi-Jurisdictional Regulatory Certification | Simultaneous FAA Part 107 and CAAC compliance enables cross-border service provider arbitrage opportunities. |
| Autonomous Obstacle Avoidance Software Development | Computer vision integration differentiates platforms for high-wind coastal infrastructure inspection missions. |
Research Methodology
Coverage spans the United States, China, Brazil, Germany, and the United Arab Emirates, with primary inputs from each jurisdiction combining structured interviews with fleet operations managers at agricultural cooperatives, regulatory affairs leads at UAV manufacturers, procurement directors at construction firms, and channel partners at industrial distributors. Secondary validation draws from FAA Part 107 waiver filings, EASA operational authorization databases, CAAC registration records, ANVISA agricultural chemical application permits, and customs trade data for lithium-polymer battery and airframe component flows. Bottom-up fleet deployment estimates triangulate against top-down market value projections.
Granularity-level modeling disaggregates volume and value outputs across application segments, payload capacity tiers, operation modes, and user types, with additional dimensionality for regulatory compliance tier and geographic certification status. CAGRs derive from segment-level growth rate convergence analysis applied across the projection horizon. Forecast inputs incorporate beyond-visual-line-of-sight authorization timeline assumptions, equipment-as-a-service adoption curves in Brazilian agriculture, and urban air mobility infrastructure investment trajectories in Dubai.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-polymer battery supply disruptions, EASA Specific Category rulemaking expansions, and CAAC geofencing enforcement intensity. Practitioners should monitor FAA Part 107 practical testing capacity constraints, rare-earth export licensing patterns from China, and autonomous flight system type certification completion rates for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Combat Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Global Drone Analytics Market
UAV
Europe Tethered Drone Market
UAV
Drone Payload Market
UAV
Europe Drone Services Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Portable Drone Market
UAV
Electric Glider Market
UAV
Drone Leasing Market
UAV
Drone Roof Inspection Market
UAV
Airborne Digital Battlefield Market
UAV
UAV Drones Market
UAV
Drone Flight Controller System Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Tactical UAV Market